
 Direct-To-Patient Healthcare Logistics Market | 2026-2036
Direct-To-Patient Healthcare Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Direct-To-Patient Healthcare Logistics Market Insights
Real-time cold-chain IoT monitoring is reconfiguring last-mile pharmaceutical distribution by enabling continuous temperature verification from manufacturer to patient doorstep. Marken leverages its specialized clinical trial logistics network to dominate temperature-sensitive cell and gene therapy shipments. FedEx Healthcare sustains competitive advantage through its SenseAware sensor platform that tracks location, temperature, and light exposure across global lanes. DHL Supply Chain anchors its position with dedicated healthcare campuses that integrate packaging, storage, and customs brokerage under one roof.
Direct-to-patient healthcare logistics encompasses the end-to-end distribution of pharmaceuticals, biologics, and medical devices from supply origin to individual patient residences, requiring validated cold-chain maintenance between 2°C and 8°C for most temperature-sensitive products and cryogenic capabilities below -150°C for emerging cell therapies. Its primary commercial purpose eliminates intermediary storage points, reduces product handling risks, and accelerates therapy initiation for immobile or remote patients. Home delivery of medications leads segment volume due to chronic disease management needs, while automated packaging systems represent the fastest-growing technology dimension as pharmacies seek to reduce dispensing errors and labor costs. Pharmacy fulfillment occupies concentrated margin pools because of value-added services like patient counseling, prior authorization support, and adherence packaging that command premium reimbursement.
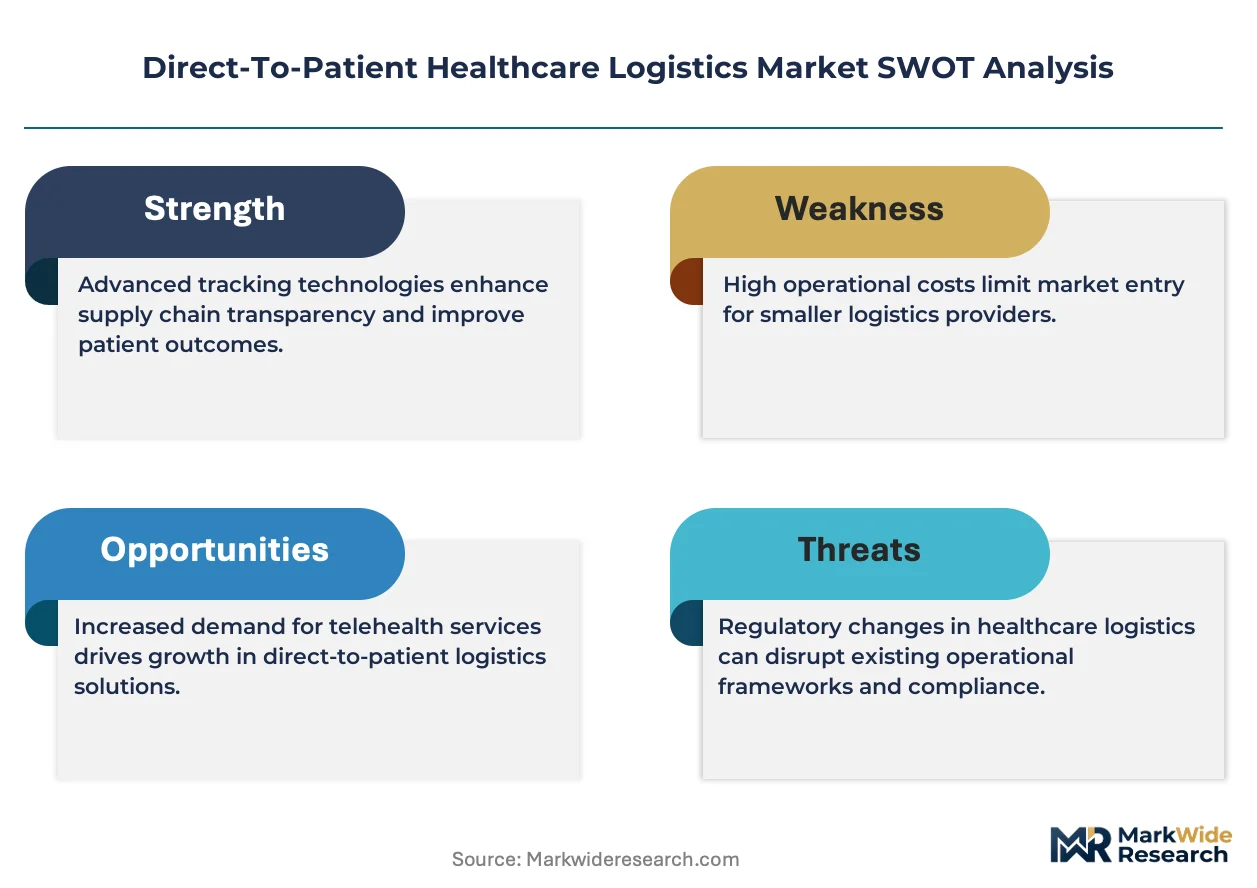
The FDA enforces current Good Distribution Practice standards through facility inspections and DSCSA track-and-trace requirements that mandate unit-level serialization, while the EU's GDP guidelines impose qualification protocols on transport containers and vehicles handling medicinal products. Japan's PMDA requires foreign manufacturers to designate in-country caretakers who assume liability for product quality through distribution, effectively raising market access barriers for non-compliant logistics providers. Stakeholders must monitor how telehealth platform integration with pharmacy management software reshapes patient onboarding workflows and regulatory scrutiny of digital prescription routing.
Market Dynamics
Real-time cold-chain IoT monitoring is compressing delivery windows for temperature-sensitive biologics while FDA DSCSA serialization mandates force logistics providers to rebuild tracking infrastructure from manufacturer to patient doorstep.
Growth Catalysts
- Chronic disease home administration:Patients receiving biologics for autoimmune conditions now expect direct delivery to residence, eliminating infusion center visits and accelerating therapy initiation timelines.
- EU GDP temperature qualification protocols:Mandatory container validation for 2°C to 8°C distribution has professionalized last-mile capabilities and created barrier-to-entry protection for compliant operators.
- Cryogenic infrastructure expansion:Cell and gene therapy commercialization below -150°C is pulling specialized logistics investment into patient-direct channels previously limited to clinical trial settings.
Market Restraints
- Dry ice supply concentration:Regional production bottlenecks for solid carbon dioxide constrain cryogenic shipment capacity during peak seasonal demand periods.
- Refrigerated vehicle qualification costs:GDP-compliant fleet certification requires thermal mapping studies and documented performance qualification that strain mid-size carrier capital reserves.
- Japan PMDA in-country caretaker liability:Foreign manufacturers must designate domestic quality-assuming agents, raising market access barriers for non-compliant logistics providers.
Strategic Opportunities
- Telehealth-pharmacy software convergence:Integration between virtual care platforms and dispensing systems creates embedded logistics demand for prescription fulfillment direct to video-visit patients.
- Automated adherence packaging:Robotic multi-dose strip production for polypharmacy patients commands premium reimbursement through reduced hospitalization risk.
- Germany's reimbursement shift toward ambulatory care:Diagnosis-related group reforms favor home-based therapy delivery, expanding eligible patient populations for direct distribution.
Industry Challenges
- Cold-chain engineer talent scarcity:Qualified professionals capable of validating thermal packaging and resolving temperature excursions remain concentrated among established pharmaceutical logistics specialists.
- Legacy warehouse management system integration:Patient-specific serialization requirements demand API connectivity between DSCSA-tracked inventory and last-mile delivery platforms that older ERP architectures cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct-To-Patient Healthcare Logistics Market |
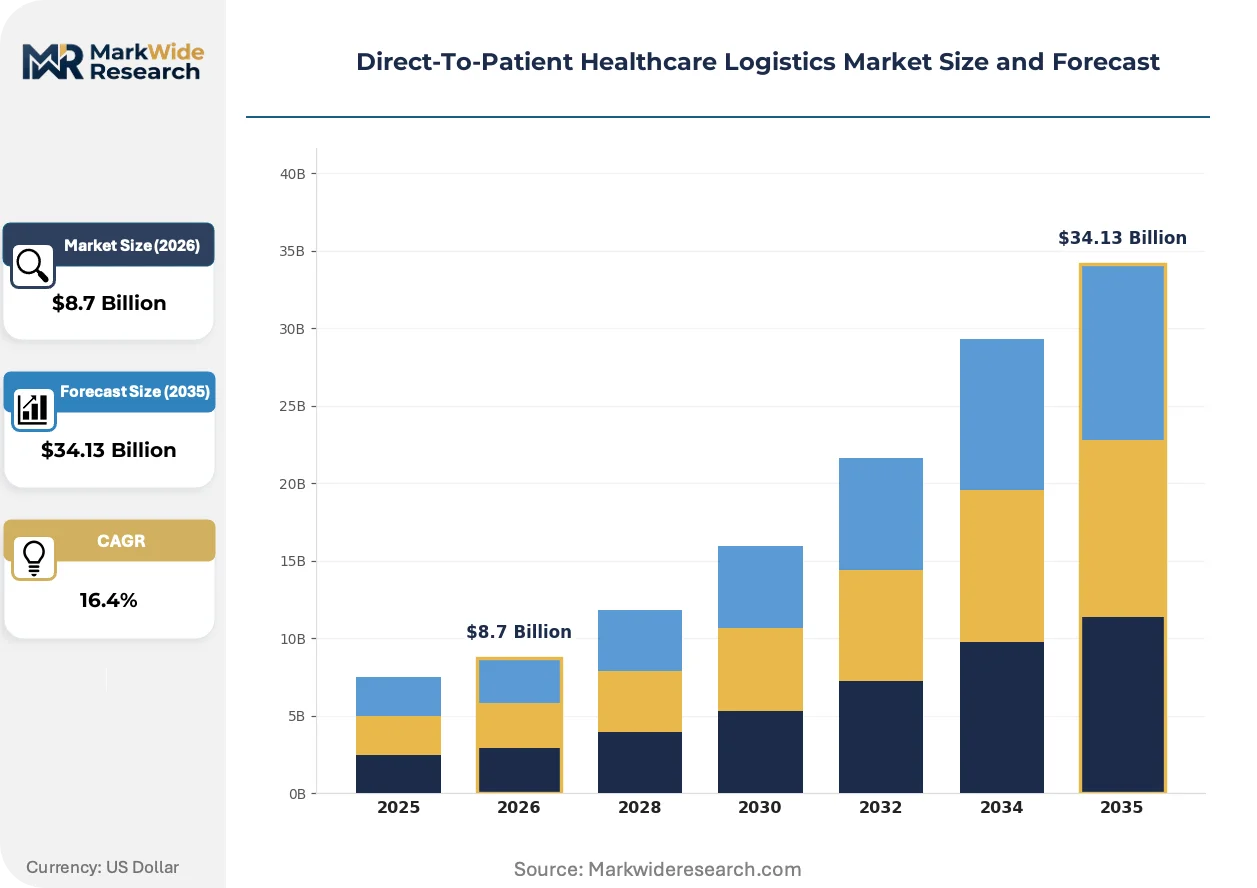
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Model: Home Delivery, Drop Shipping, Pharmacy Fulfillment, Direct Mail Product Type: Medications, Diagnostic Devices, Vaccines, Nutritional Supplements End User: Patients, Caregivers, Healthcare Providers, Pharmacies Technology: Tracking Systems, Automated Packaging, Order Management Software, Telehealth Platforms |
| Companies Covered | Marken, World Courier, DHL Supply Chain, FedEx Healthcare, Kuehne + Nagel, Catalent Clinical Supply Services, Thermo Fisher Scientific, Parexel International, CEVA Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct-To-Patient Healthcare Logistics Market Trends and Innovations
Sensor-enabled visibility platforms are collapsing the information gap between pharmacy dispatch and patient receipt, while regulatory serialization mandates force technology investment ahead of operational returns.
Blockchain-anchored temperature logging is hybridizing pharmaceutical supply chains by creating immutable custody records from manufacturer to patient. Specialty pharmacies serving oncology and rare disease populations are deploying these systems fastest. The technology is compressing insurance dispute resolution timelines by providing auditable proof of cold-chain integrity.
REACH-compliant sustainable packaging mandates in Europe are accelerating substitution of expanded polystyrene shippers with recyclable thermal materials. The regulation forces reformulation of validated shipping configurations. Cell therapy sponsors targeting EU commercialization are redesigning primary containers to accommodate narrower temperature ranges that new insulation materials can reliably maintain.
Patient onboarding workflows are consolidating prescription verification, benefits investigation, and delivery scheduling into single-session digital experiences. Hospital-owned specialty pharmacies are losing referral volume to independent dispensaries with integrated logistics platforms. The United States exhibits the fastest channel migration as health system employment of physicians creates captive referral streams to affiliated home delivery services.
Direct-To-Patient Healthcare Logistics Market Segmentation
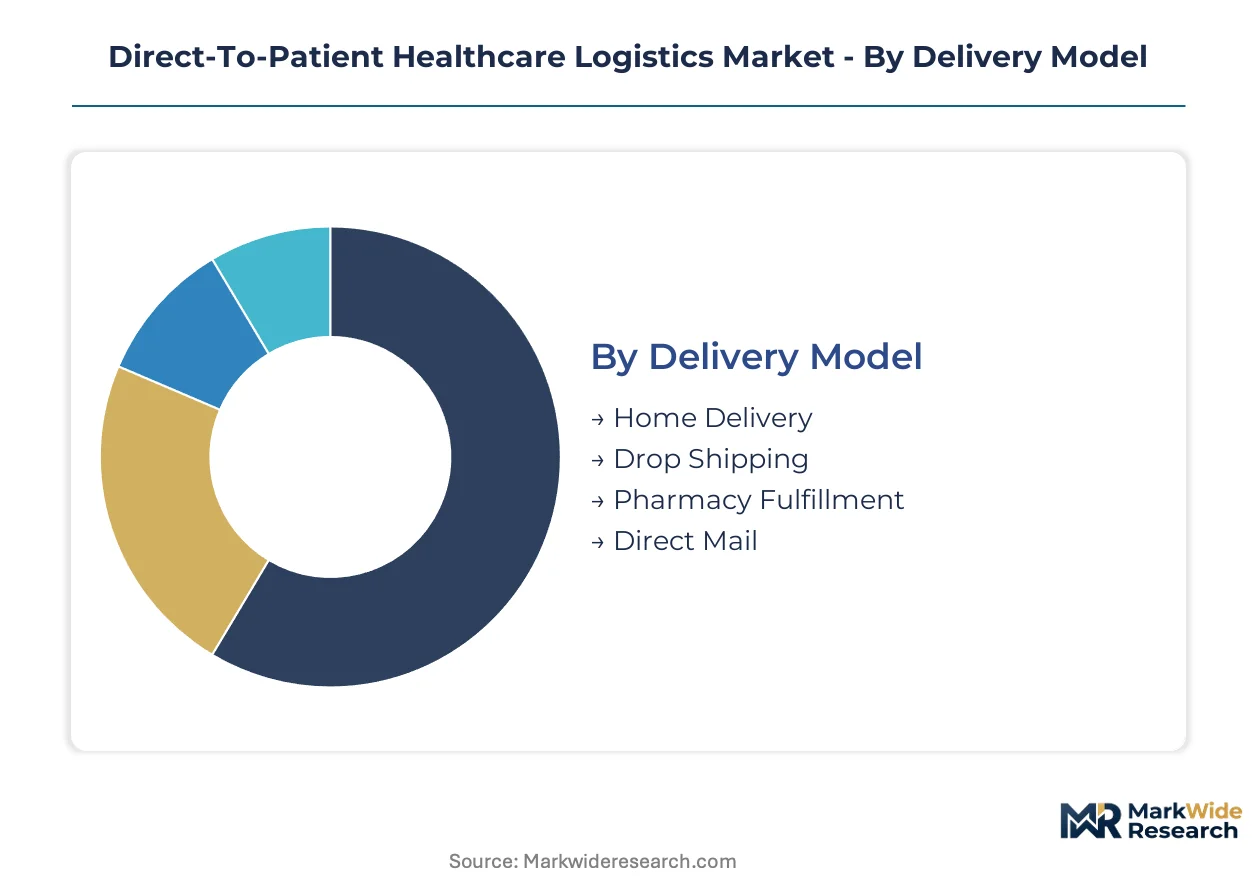
Direct-to-patient healthcare logistics fragments across four operational dimensions. Delivery model determines cold-chain infrastructure requirements. Product type dictates temperature range specifications from ambient to cryogenic. Technology integration separates premium service tiers from commodity fulfillment.
Delivery Model:
Cost tier stratification separates white-glove clinical services from standardized parcel delivery.
- Home Delivery:Validated cold-chain transport from pharmacy to patient residence with continuous temperature monitoring and signature capture. Chronic disease biologics for autoimmune conditions concentrate demand in the United States, Germany, and Japan where aging populations favor residence-based administration.
- Pharmacy Fulfillment:Centralized dispensing with value-added services including prior authorization support, patient counseling, and adherence packaging. Oncology and rare disease populations drive premium reimbursement through reduced hospitalization risk.
- Drop Shipping:Manufacturer-direct dispatch bypassing wholesale distribution to accelerate therapy initiation timelines for immobile patients.
- Direct Mail:Standardized postal distribution for ambient-stable maintenance medications with lower compliance documentation requirements.
Home Delivery holds installed capacity. Pharmacy Fulfillment is rotating up the share rankings.
Product Type:
Application severity determines packaging validation depth and insurance reimbursement tiers.
- Medications:Temperature-sensitive biologics requiring 2°C to 8°C maintenance dominate volume, with cryogenic below -150°C capabilities for cell and gene therapies representing the steepest expansion trajectory. FDA DSCSA serialization mandates and EU GDP guidelines tighten compliance for prescription fulfillment.
- Vaccines:Cold-chain distribution with excursion-sensitive potency requirements, particularly for mRNA formulations requiring ultra-low temperature infrastructure.
- Diagnostic Devices:Home-based monitoring equipment with calibration-sensitive shipping constraints for diabetes and cardiovascular conditions.
- Nutritional Supplements:Ambient-stable products with lighter regulatory burden but growing demand for subscription-based direct delivery.
Medications anchor revenue concentration. Vaccines are climbing the fastest on pandemic-era infrastructure investment.
End User:
Customer type dictates service intensity and regulatory liability allocation.
- Patients:Individual recipients requiring adherence support, delivery scheduling flexibility, and benefits investigation assistance. Japan's PMDA in-country caretaker requirements raise quality-assurance barriers for foreign manufacturer direct distribution.
- Caregivers:Family members or home health aides managing polypharmacy regimens for elderly or disabled patients, driving demand for automated adherence packaging.
- Healthcare Providers:Physicians and clinics prescribing direct-to-patient delivery to reduce infusion center burden and accelerate therapy initiation.
- Pharmacies:Independent and health system-owned dispensaries outsourcing logistics to specialized cold-chain operators.
Patients command the highest service touch requirements. Caregivers are gaining share fastest on geriatric population expansion.
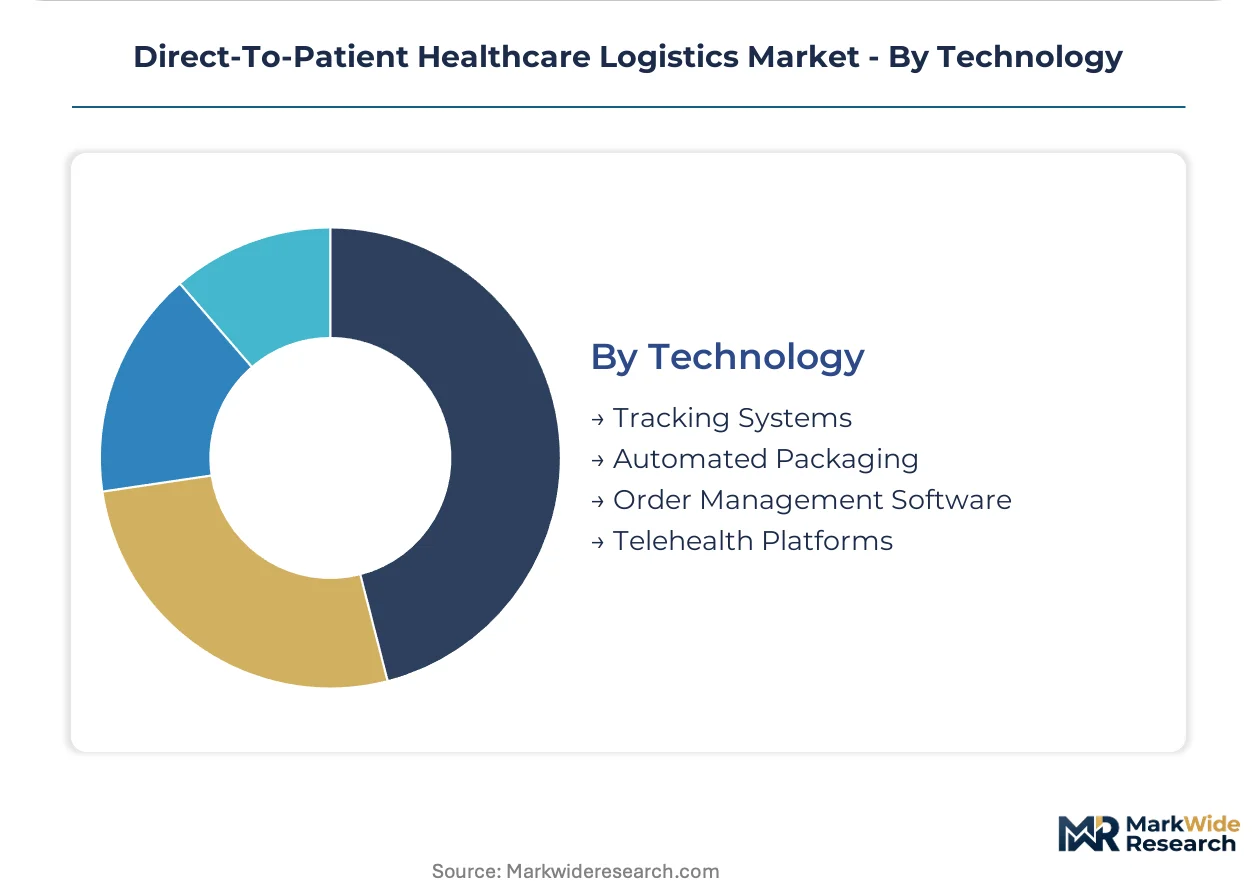
Technology:
Maturity gradients separate legacy ERP integrations from sensor-native platforms.
- Tracking Systems:IoT-enabled temperature, location, and light exposure monitoring creating auditable custody records from manufacturer to patient doorstep. Blockchain-anchored logging compresses insurance dispute resolution timelines for oncology shipments.
- Automated Packaging:Robotic multi-dose strip production reducing dispensing errors and labor costs for polypharmacy patients.
- Order Management Software:Pharmacy management systems requiring API connectivity to DSCSA-tracked inventory for patient-specific serialization compliance.
- Telehealth Platforms:Virtual care integration embedding prescription fulfillment demand through single-session digital onboarding workflows.
Tracking Systems hold installed capacity. Telehealth Platforms are rotating up the share rankings on virtual care permanence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chronic disease patients receiving biologics at home concentrate demand in aging economies with reimbursement shifts toward residence-based care delivery.
United States
Specialty pharmacies serving oncology and rare disease populations drive premium fulfillment volumes through integrated logistics platforms. FDA DSCSA serialization mandates force infrastructure rebuilds from manufacturer to patient doorstep. Hospital-owned dispensaries in the Northeast Corridor lose referral share to independent operators with embedded home delivery capabilities.
Germany
Diagnosis-related group reforms favor ambulatory therapy delivery, expanding eligible populations for direct distribution. EU GDP guidelines impose mandatory container validation for cold-chain transport, professionalizing last-mile capabilities. The Rhine-Ruhr cluster anchors pharmaceutical logistics investment as pharmacies consolidate fulfillment operations.
Japan
PMDA in-country caretaker requirements raise quality-assurance barriers for foreign manufacturer direct distribution. Aging demographics accelerate residence-based biologic administration for autoimmune conditions. The Kanto region around Tokyo concentrates specialty pharmacy networks managing prior authorization and adherence packaging.
United Kingdom
NHS reimbursement shifts toward community-based chronic disease management pull prescription fulfillment away from hospital settings. MHRA alignment with EU GDP protocols maintains temperature qualification standards post-Brexit. The Greater London area hosts the densest concentration of cold-chain engineering talent for thermal packaging validation.
Switzerland
Swissmedic oversight of cell and gene therapy commercialization attracts cryogenic logistics investment below -150°C. Precision medicine sponsors leverage the Basel biotech cluster for patient-direct clinical trial expansion. The Zürich-Geneva corridor specializes in white-glue delivery for ultra-rare disease populations.
Direct-To-Patient Healthcare Logistics Market Competitive Landscape
Channel-controlling players compete with product-specialist players for custody of temperature-sensitive shipments from manufacturer to patient residence. The vendor base stratifies across integrated express networks, clinical trial specialists, and pharmaceutical-grade warehousing operators. Three archetypes dominate: global integrators with sensor platforms, cell therapy logistics pure-plays, and health system-affiliated pharmacy fulfillment networks. Competitive moves concentrate on cryogenic capacity expansion and telehealth platform partnerships.
Within the clinical trial logistics tier, Marken and World Courier exemplify temperature-sensitive cell and gene therapy specialization. Among integrated express operators, FedEx Healthcare occupies a position anchored by sensor-native visibility infrastructure. DHL Supply Chain sits within the warehousing-centric archetype with dedicated healthcare campuses consolidating packaging, storage, and customs brokerage.
| Leading Market Players |
|---|
| Marken |
| World Courier |
| DHL Supply Chain |
| FedEx Healthcare |
| Kuehne + Nagel |
| Catalent Clinical Supply Services |
| Thermo Fisher Scientific |
| Parexel International |
| CEVA Logistics |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Ruhr pharmaceutical corridor anchors European cold-chain cost dynamics, where GDP-compliant fleet certification expenses concentrate pricing power among integrated operators while forcing smaller carriers into subcontractor relationships that compress margins across temperature-sensitive last-mile delivery tiers.
Pricing Analysis
Cost-plus contracts indexed to dry ice futures and fuel surcharges dominate cryogenic shipment pricing, with three-tier pricing structure across premium, standard, and economy levels differentiating by temperature validation depth and insurance-backed excursion liability. FDA DSCSA serialization compliance costs drive price differentiation between DSCSA-ready pharmacy networks and legacy dispensaries lacking track-and-trace infrastructure. Pricing pressure stems from health system employment of physicians creating captive referral streams that squeeze independent specialty pharmacy margins. Large hospital-owned dispensaries exhibit lowest price sensitivity due to integrated reimbursement capture, while independent rural pharmacies face acute cost compression.
Supply Chain Analysis
Supplier-financing through extended payment terms and supply-chain finance facilities has become critical for cryogenic packaging manufacturers serving cell therapy sponsors with lengthy clinical-to-commercial timelines. Dry ice production concentrates in the United States, Germany, and China, while specialized thermal packaging draws from expanded polystyrene alternatives developed in the Netherlands and recyclable insulation innovators in Scandinavia. Single-source vulnerability runs through regional dry ice bottlenecks during peak seasonal demand. Distribution runs through pharmacy fulfillment networks that integrate prior authorization, patient counseling, and last-mile cold-chain delivery under single-roof operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as pandemic-era telehealth infrastructure investment matures into permanent patient onboarding workflows, with reimbursement shifts toward ambulatory care providing the cyclical lift.
For Market Incumbents: Entrench cryogenic capacity advantages through backward integration into dry ice production and captive thermal packaging manufacturing, defending against emerging platform-native entrants with telehealth-pharmacy software convergence capabilities. Prioritize EU GDP qualification investment to maintain barrier-to-entry protection as REACH-compliant sustainable packaging mandates force container redesign cycles.
For New Entrants and Emerging Players: Japan's Kanto region presents underpenetrated opportunity where PMDA in-country caretaker requirements have stalled foreign logistics penetration, creating white-space for domestic quality-assuming agents with cryogenic infrastructure. Target caregiver-directed polypharmacy adherence packaging as the most penetrable segment, leveraging automated robotic strip production to command premium reimbursement through hospitalization risk reduction.
For Investors and Strategic Acquirers: Sensor-native visibility platform specialists with blockchain-anchored temperature logging capabilities represent the priority acquisition archetype, as insurance dispute resolution compression creates defendable moats in oncology and rare disease channels. Watch for inflection when cell therapy sponsors announce EU commercialization timelines requiring below -150°C patient-direct infrastructure buildout.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Infrastructure Expansion | Cell therapy commercialization below -150°C pulls specialized investment into patient-direct channels previously limited to clinical trials. |
| Telehealth-Pharmacy Integration | Virtual care platform embedding creates embedded logistics demand for prescription fulfillment direct to video-visit patients. |
| EU GDP Qualification Investment | Mandatory container validation for 2°C to 8°C distribution professionalizes last-mile capabilities and protects compliant operators. |
| Automated Adherence Packaging | Robotic multi-dose strip production commands premium reimbursement through reduced hospitalization risk for polypharmacy patients. |
| Sustainable Packaging Transition | REACH-compliant substitution of expanded polystyrene forces reformulation of validated shipping configurations for EU market access. |
Research Methodology
A standing panel of specialty pharmacy operations directors, cold-chain engineering leads, FDA regulatory consultants, and payer access specialists provided ongoing calibration, combining structured primary interviews with secondary validation against FDA DSCSA guidance documents, EU GDP guideline revisions, ClinicalTrials.gov logistics protocol filings, and pharmaceutical customs records. Bottom-up pharmacy fulfillment volume estimates triangulated against top-down express carrier healthcare revenue disclosures.
Scenario-bracketing around telehealth adoption permanence and cell therapy commercialization timelines anchored the analytical framework across the projection horizon, with segmentation dimensions covering delivery model tier, temperature range specification, patient population severity, and regional regulatory cluster. CAGRs derived from installed capacity buildout schedules and reimbursement policy trajectories, incorporating cryogenic infrastructure investment pipelines and pharmacy management software API connectivity adoption curves as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-native telehealth entrants or cell therapy sponsors bypassing established logistics networks would shift outcomes. Macroeconomic deviation in healthcare reimbursement, regulatory acceleration of serialization mandates, or breakthroughs in ambient-stable biologic formulations would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Europe Medical Affairs Outsourcing Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Global Corporate Wellness Solutions Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
US Medical Billing Outsourcing Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Europe Pharmaceutical Cold Chain Logistics Market
Healthcare Services
UK Ambulatory Services Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
US Hospice Market
Healthcare Services
Global Perfusion Services Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Global Funeral Homes and Funeral Services Market