
 Clinical Healthcare IT Market | 2026-2036
Clinical Healthcare IT Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Healthcare IT Market Insights
Subscription-based financing and operating-lease models for enterprise software are reconfiguring competitive access in clinical healthcare IT, allowing mid-sized hospital networks to deploy tier-one platforms without heavy upfront capital. Epic Systems Corporation leverages its integrated ecosystem architecture to dominate large academic medical center contracts. Oracle Health anchors its position through cloud infrastructure scale and database interoperability capabilities. McKesson Corporation competes via supply-chain-linked analytics modules that extend its pharmaceutical distribution relationships into clinical workflow software.
Clinical healthcare IT encompasses electronic systems for capturing, storing, exchanging, and analyzing patient health information, typically operating through HL7 FHIR APIs and requiring sub-100-millisecond query response times for real-time clinical decision support. Its primary purpose is to reduce medical error rates, streamline care coordination, and enable population-level health management across fragmented provider networks. EHR and EMR platforms represent the mature revenue core where replacement cycles and upgrade paths concentrate vendor margin pools. Cloud-based and SaaS deployment categories are expanding fastest as health systems prioritize remote accessibility and automatic regulatory compliance updates over on-premises control. AI-Driven Solutions within the technology dimension are attracting disproportionate R&D investment as vendors race to embed predictive analytics into routine diagnostic workflows.
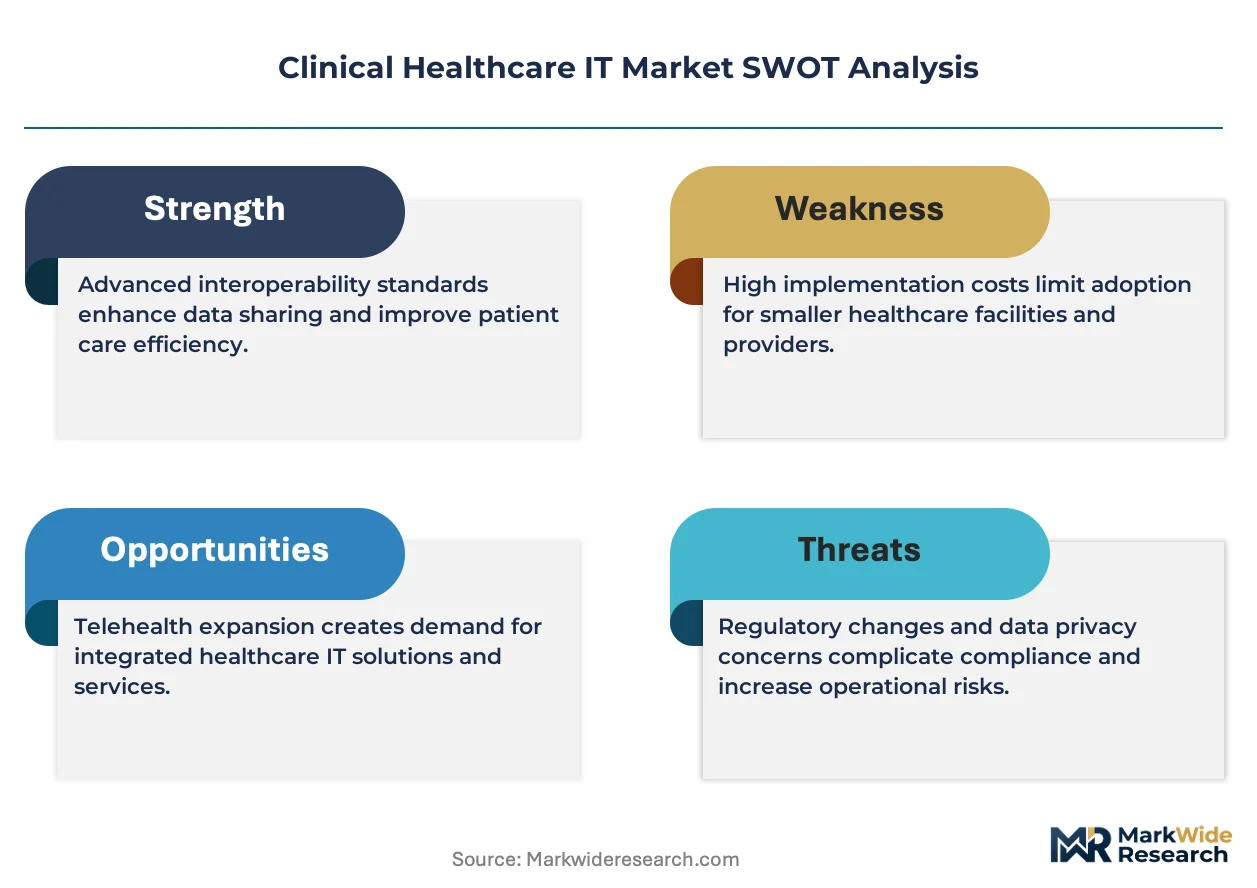
The ONC Cures Act Final Rule in the United States mandates standardized API-based data exchange, forcing vendors to open previously proprietary patient record formats or risk exclusion from federal reimbursement programs. FDA oversight of clinical decision support software and HIPAA security rule enforcement by OCR collectively elevate compliance costs while creating barriers for undercapitalized entrants. Stakeholders must monitor how emerging state-level privacy laws beyond federal minimums fragment interoperability requirements and reshape vendor certification burdens.
Market Dynamics
The ONC Cures Act interoperability mandates are forcing EHR vendors to dismantle proprietary data architectures, accelerating API standardization and cloud migration across hospital procurement cycles.
Growth Catalysts
- HL7 FHIR API standardization:The ONC Cures Act Final Rule mandates open data exchange protocols, compelling health systems to upgrade legacy platforms and creating replacement demand across mid-sized hospital networks.
- Cloud infrastructure migration:Operating-lease financing models for SaaS deployment are removing capital barriers, allowing community health systems to access enterprise-grade clinical platforms without heavy upfront investment.
- AI-embedded diagnostic workflows:Predictive analytics integration into routine clinical decision support is driving R&D investment and creating differentiation pressure among platform vendors.
Market Restraints
- HIPAA security rule compliance costs:OCR enforcement actions and breach notification requirements elevate operational expenditures, disproportionately burdening undercapitalized regional health IT vendors.
- Legacy system integration complexity:Proprietary data formats in installed EHR bases create technical debt that slows cloud migration timelines and inflates implementation costs for health systems.
- Specialized clinical informatics talent scarcity:Shortages of professionals trained in both clinical workflows and health data architecture constrain deployment velocity and support scalability.
Strategic Opportunities
- Rural health system digitization:Federally qualified health centers and critical access hospitals remain underpenetrated by integrated EHR platforms, creating whitespace for modular cloud solutions.
- Population health management modules:Value-based care contracts are expanding demand for analytics layers that aggregate patient data across fragmented provider networks into actionable risk stratification.
- State-level privacy law fragmentation:Emerging regulations beyond federal HIPAA minimums are creating compliance complexity that favors vendors with automated regulatory update capabilities.
Industry Challenges
- Interoperability certification timelines:ONC certification requirements for API functionality and information blocking compliance impose extended product development cycles that delay revenue recognition.
- Clinical workflow disruption during migration:Health system staff resistance and productivity dips during platform transitions create implementation risk and threaten contract renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Healthcare IT Market |
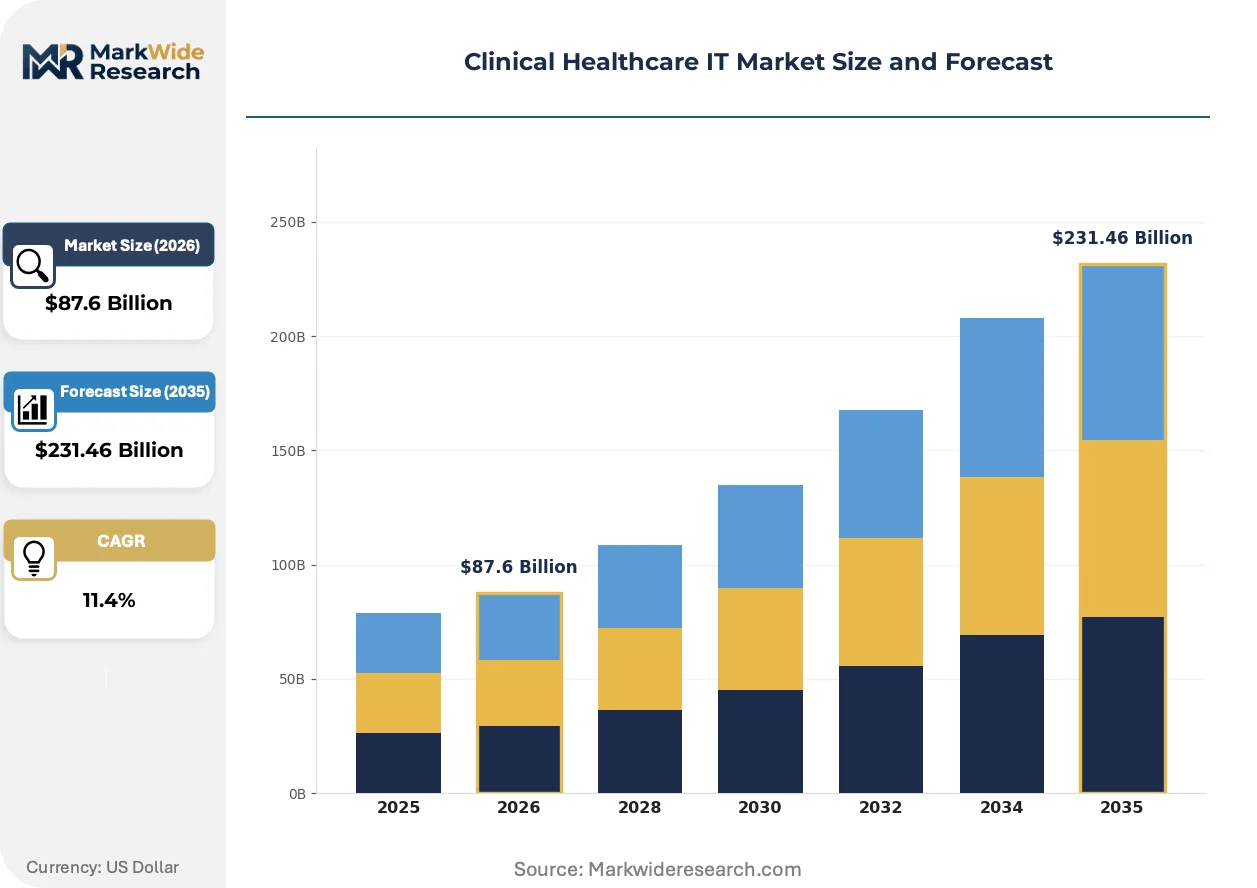
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EHR, EMR, Practice Management Software, Telemedicine Solutions Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Hospitals, Ambulatory Surgical Centers, Diagnostics Laboratories, Healthcare Providers Technology: AI-Driven Solutions, Blockchain, Interoperability Standards, Data Analytics |
| Companies Covered | Epic Systems Corporation, Oracle Health, GE HealthCare, Allscripts Healthcare Solutions, Koninklijke Philips N.V., Siemens Healthineers, McKesson Corporation, Meditech, athenahealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Healthcare IT Market Trends and Innovations
Clinical healthcare IT is experiencing convergent pressure from regulatory mandates, cloud infrastructure maturation, and AI capability integration that is compressing vendor competitive windows.
Generative AI documentation assistants are digitizing clinical encounter capture by automating physician note generation from ambient listening. Large academic medical centers are piloting these tools to reduce administrative burden and clinician burnout. This capability is digitizing the traditional medical scribe function and compressing documentation costs while raising questions about liability and hallucination risk.
The FDA's evolving oversight framework for clinical decision support software is reclassifying certain AI-enabled diagnostic tools as medical devices. This regulatory expansion imposes premarket submission requirements on previously unregulated algorithms. Radiology and cardiology AI modules face the steepest compliance ramps, with vendors restructuring development processes to accommodate quality system regulation alignment.
Subscription-based financing is displacing perpetual license models as the dominant procurement structure for enterprise clinical platforms. Health system CFOs are prioritizing operating expenditure predictability over capital ownership, particularly for cloud-native deployments. This shift is most pronounced in United States hospital networks with constrained balance sheets, where vendor financing arms are capturing competitive advantage through bundled service offerings.
Clinical Healthcare IT Market Segmentation
Segmentation in clinical healthcare IT reveals how procurement priorities diverge across infrastructure maturity, regulatory exposure, and care delivery settings. Understanding these fault lines allows vendors to align platform architectures with specific buyer constraints around capital availability, interoperability mandates, and workflow integration depth.
Product Type:
After-sales service intensity varies sharply across product categories, with integrated platforms demanding multi-year implementation support while modular solutions require lighter ongoing engagement.
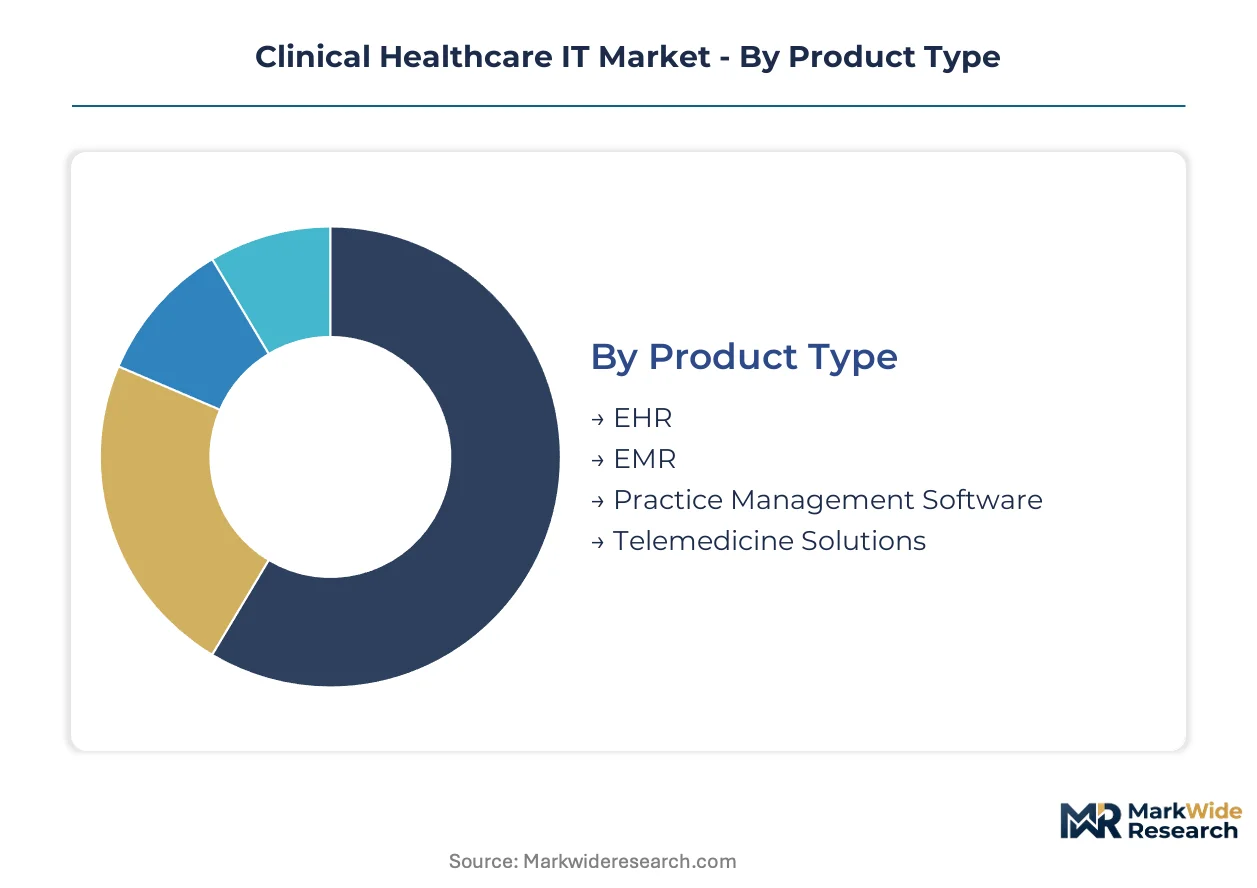
- EHR:Comprehensive digital platforms capturing longitudinal patient records across inpatient and outpatient encounters, requiring extensive workflow reconfiguration during deployment. Academic medical centers in the United States drive replacement demand as ONC Cures Act deadlines force API architecture upgrades.
- EMR:Narrower-scope electronic record systems focused on specific care settings or departmental workflows rather than enterprise-wide integration. Ambulatory surgical centers and specialty clinics favor these for faster deployment timelines and lower total cost of ownership.
- Practice Management Software:Administrative systems handling scheduling, billing, and revenue cycle operations for physician practices and outpatient facilities.
- Telemedicine Solutions:Virtual care platforms enabling remote consultations through video, audio, and asynchronous messaging channels.
EHR holds the largest share; momentum sits with Telemedicine Solutions.
Deployment:
Cost tier stratification dominates procurement decisions, with capital-constrained buyers gravitating toward operating-expense models while security-sensitive institutions retain on-premises control.
- Cloud-Based:Fully hosted infrastructure eliminating local server maintenance and enabling automatic regulatory compliance patches. Community hospital networks across the United States are expanding fastest here as subscription financing removes upfront capital barriers.
- SaaS:Software-as-a-service delivery with per-seat or per-encounter pricing, bundling maintenance, updates, and support into recurring fees. Federally qualified health centers leverage these models to access enterprise-grade capabilities without dedicated IT staff.
- On-Premises:Locally installed and managed systems retaining full data sovereignty and customization control for organizations with robust internal technical capabilities.
- Hybrid:Mixed architectures keeping sensitive clinical data on-site while offloading analytics, backup, or non-critical workloads to cloud infrastructure.
Cloud-Based deployment holds the largest share; momentum sits with SaaS.
End User:
Application complexity scales with organizational size, driving divergent requirements for customization depth, integration breadth, and regulatory reporting granularity.
- Hospitals:Large integrated delivery networks requiring enterprise-wide patient record unification across emergency, inpatient, surgical, and outpatient services. These buyers command the deepest vendor relationships and longest implementation cycles.
- Healthcare Providers:Individual physicians, group practices, and outpatient clinics prioritizing usability and rapid documentation capture over deep interoperability.
- Ambulatory Surgical Centers:Focused care facilities needing streamlined perioperative workflows and specialized regulatory reporting for same-day procedures.
- Diagnostics Laboratories:High-volume testing operations requiring bidirectional EHR integration for order entry and results delivery.
Hospitals hold the largest share; momentum sits with Healthcare Providers.
Technology:
Customer type differentiation separates buyers seeking incremental workflow optimization from those pursuing transformative diagnostic capabilities through emerging technology stacks.
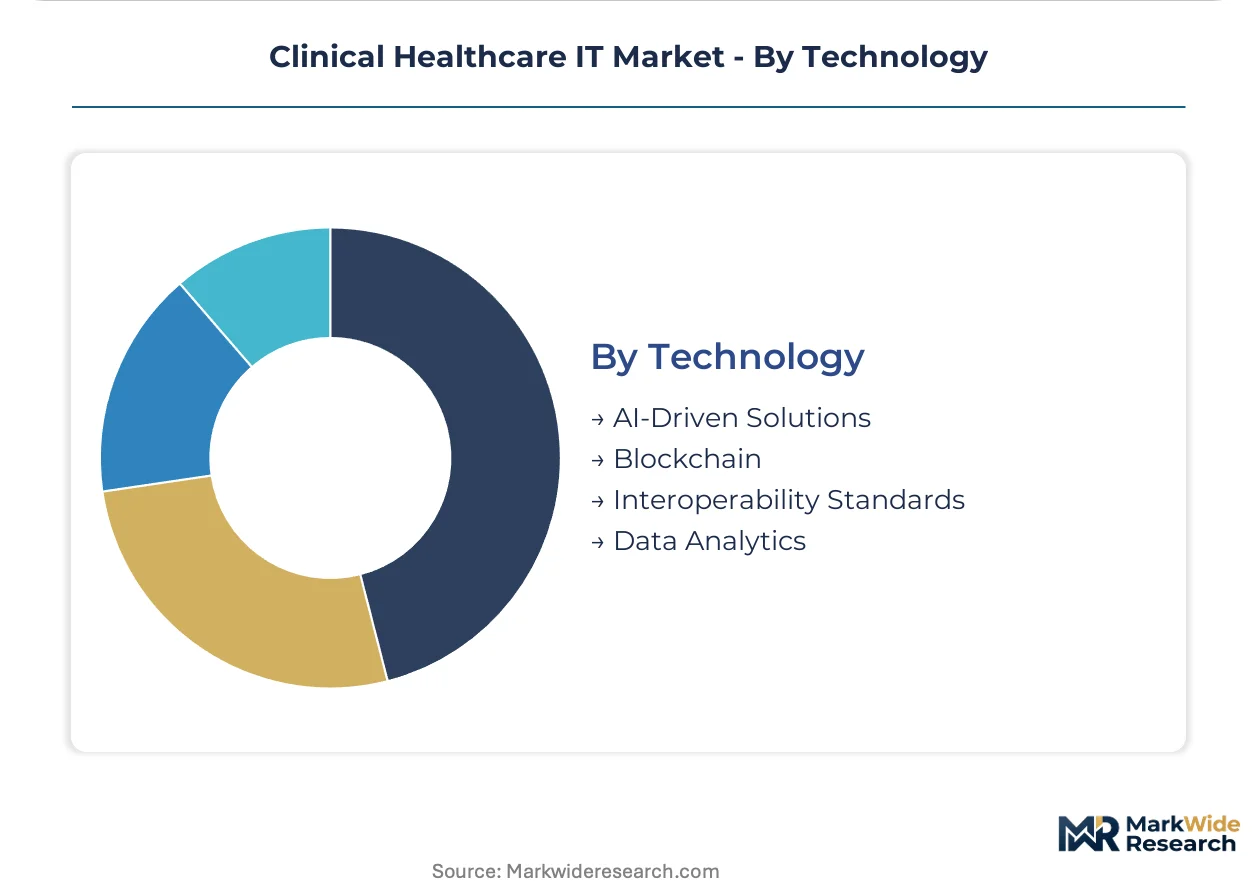
- AI-Driven Solutions:Machine learning models embedded into clinical decision support, documentation automation, and predictive risk stratification. Radiology and cardiology departments in the United States are piloting these tools under evolving FDA oversight frameworks.
- Data Analytics:Population health and operational intelligence platforms aggregating fragmented data sources into actionable dashboards for value-based care contracts.
- Interoperability Standards:HL7 FHIR-based exchange infrastructure enabling seamless data flow across previously siloed EHR systems and care settings.
- Blockchain:Distributed ledger architectures for credential verification, supply chain integrity, and patient consent management.
Data Analytics holds the largest share; AI-Driven Solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains substantial net export positioning in clinical healthcare IT services and intellectual property, while Germany and Japan balance trade through specialized hardware-software integration exports against cloud service imports from American hyperscalers.
United States
Federal interoperability mandates and value-based care contract expansion drive procurement acceleration across integrated delivery networks. The ONC Cures Act Final Rule compels API standardization, forcing legacy platform replacements. Epic Systems Corporation anchors market concentration in Wisconsin, while Oracle Health leverages cloud infrastructure scale from Austin and Redwood Shores facilities.
Germany
Hospital digitization funding through the Hospital Future Act creates replacement demand for legacy patient management systems. The EU AI Act imposes risk-classification requirements on diagnostic algorithms, elevating compliance architecture investments. Siemens Healthineers exemplifies industrial concentration in Erlangen, embedding clinical IT within imaging hardware ecosystems.
Japan
Aging demographics and labor shortages accelerate automation demand in clinical documentation and decision support. PMDA oversight of software-as-medical-device creates premarket clearance bottlenecks for foreign vendors. Tokyo and Osaka metropolitan clusters concentrate hospital procurement authority, favoring vendors with localized implementation capabilities.
United Kingdom
NHS England's Federated Data Platform consolidation creates single-buyer leverage for national procurement. NHS Digital interoperability standards mandate FHIR compliance, eliminating non-conforming vendors from supplier frameworks. London's health tech corridor concentrates startup activity around AI diagnostic tools, though acquisition pathways favor American strategic buyers.
India
Digital health mission expansion and medical tourism infrastructure investment create demand for affordable EHR deployment at scale. CDSCO regulation of clinical decision support software remains underdeveloped, creating compliance ambiguity for AI-enabled tools. Bengaluru and Hyderabad clusters concentrate health tech development talent, with vendors targeting Middle East and African export markets.
Clinical Healthcare IT Market Competitive Landscape
On the supply side, the industry is consolidating around integrated platform vendors capable of delivering end-to-end clinical and financial workflows. Three strategic archetypes dominate: ecosystem architects bundling EHR with population health analytics, cloud infrastructure operators leveraging database scale for interoperability, and supply-chain incumbents extending pharmaceutical distribution relationships into clinical software. M&A activity concentrates on AI diagnostic startups and regional EHR bolt-ons, while strategic partnerships between hardware manufacturers and cloud hyperscalers reshape deployment economics.
Within the ecosystem architect tier, Epic Systems Corporation and Oracle Health occupy positions defined by divergent capital structure approaches—one through perpetual dominance in academic medical centers, the other through cloud-native acquisition integration. McKesson Corporation anchors the supply-chain extension archetype, embedding clinical IT within pharmaceutical distribution relationships. These three entities exemplify how vendor competitive positioning increasingly depends on financing model innovation rather than feature differentiation alone.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Health |
| GE HealthCare |
| Allscripts Healthcare Solutions |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| McKesson Corporation |
| Meditech |
| athenahealth |
| Others |
Pricing and Supply Chain Analysis
Underutilized server capacity across United States hyperscale data centers is compressing cloud hosting rates and tilting vendor procurement toward operating-lease models, reshaping how clinical IT platforms price subscription tiers and source infrastructure.
Pricing Analysis
Hospital system CFOs anchor SaaS-tiered pricing structures across the clinical healthcare IT market. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with deep integration needs from community hospitals seeking core EHR functionality and rural clinics requiring modular point solutions. Price differentiation rests on HL7 FHIR certification grade and after-sales implementation support depth. Cost compression in the economy tier is intensifying because federally qualified health centers negotiate volume discounts through group purchasing organizations. Rural critical access hospitals exhibit highest price sensitivity; large integrated delivery networks with captive IT staff show least.
Supply Chain Analysis
Contract manufacturing for clinical IT hardware concentrates with Foxconn, Jabil, and Flex operating server assembly facilities across Taiwan, Mexico, and Malaysia. Software development talent clusters in India, Poland, and the United States. Raw material dependencies span semiconductor wafers from Taiwan, lithium-ion battery cells from South Korea, and rare earth magnets from China. Single-source vulnerability in Taiwan semiconductor foundries poses structural supply chain risk. Distribution runs through direct enterprise sales teams for large hospital networks and value-added resellers for mid-market ambulatory practices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical healthcare IT sits in early-cycle expansion as ONC Cures Act interoperability deadlines force replacement waves across legacy EHR installations that resisted prior upgrade cycles.
For Market Incumbents: Build switching-cost moats through deep workflow integration and captive data architectures. Defensive consolidation should prioritize AI diagnostic startups with FDA breakthrough device designation to preempt algorithmic substitution. Capacity addition in India for offshore implementation support addresses talent scarcity constraining deployment velocity.
For New Entrants and Emerging Players: Establish a beachhead in rural critical access hospitals and federally qualified health centers where Epic Systems Corporation and Oracle Health maintain lightest penetration. These segments offer fastest procurement cycles and lowest switching barriers. A modular cloud-native architecture with per-encounter pricing bypasses capital committee approval requirements that stall enterprise platform sales.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across SaaS deployment models as cloud infrastructure commoditizes hosting costs. Long-term viability favors vendors with automated regulatory update engines capable of absorbing state-level privacy law fragmentation. Acquisition target archetype: regional EHR bolt-ons with established ONC certification and sticky ambulatory clinic relationships. Signal to watch is FDA premarket submission volume for clinical decision support algorithms as regulatory clearance becomes competitive barrier.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Certification Pathway | ONC certification unlocks federal reimbursement eligibility and excludes non-compliant competitors. |
| AI Diagnostic Module Integration | FDA-cleared algorithms embedded in EHR workflows create differentiation against legacy platforms. |
| Cloud Infrastructure Partnership | Hyperscaler alliances reduce hosting costs and accelerate automatic HIPAA security patch deployment. |
| Regional EHR Acquisition | Certified installed bases in underserved geographies provide immediate ONC-compliant customer expansion. |
| Value-Based Care Analytics Suite | Risk stratification modules align vendor roadmaps with Medicare ACO contract requirements. |
Research Methodology
Operator-level perspectives from hospital CIOs, EHR implementation directors, GPO contracts managers, and clinical informaticists anchored the qualitative base. Primary interviews combined with secondary validation against CMS Medicare reimbursement databases, ONC certification registries, hospital procurement records, and SEC filings from publicly traded health IT vendors. Bottom-up deployment estimates triangulated against top-down market sizing across product type, deployment model, and end-user segments.
Scenario-bracketing framed the analytical approach across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size tier, integration complexity depth, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, cloud migration velocity, and AI module attach rate assumptions. Forecast inputs incorporated ONC compliance deadline enforcement patterns and FDA clinical decision support oversight expansion timelines.
Sensitivities concentrate around interoperability certification timeline delays and state privacy law fragmentation beyond federal HIPAA minimums. Forecasts reflect assumptions regarding health system capital availability and cloud vendor pricing trajectories. Quarterly review of ONC information blocking enforcement actions and FDA AI-enabled diagnostic tool reclassification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Back-End Revenue Cycle Management Market
Healthcare IT
Hand Hygiene Monitoring System Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
Global Technology Spending on Core Administration in Healthcare Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Assisted Living Software Market
Healthcare IT
Medical IoT Software Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
North America Wireless Healthcare Market
Healthcare IT
Femtech Market
Healthcare IT
Dental Implantology Software Market
Healthcare IT
Global Telepharmacy Market
Healthcare IT
Europe Smart Hospital Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
US Dental Clearing Houses Market