
 US Care Services Market | 2026-2036
US Care Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Care Services Market Intelligence
Skilled nursing facility quality ratings are unwinding traditional site-of-care preferences as CMS Five-Star benchmarks reshape consumer selection. Brookdale Senior Living competes through geographic clustering in Sun Belt metros. Kindred Healthcare leverages hospital-based partnerships for post-acute transitions. Amedisys anchors home health volume through Medicare-certified agency networks.
US Care Services encompass medically supervised and non-medical assistance delivered across residential, institutional, and virtual settings, regulated by clinical staffing ratios, infection control protocols, and interoperability standards for electronic health record exchange. The primary purpose spans chronic disease management, functional recovery, and end-of-life comfort through coordinated multidisciplinary teams. Home Health Care leads service type revenue as hospital-at-home waivers mature, while Telehealth delivery mode captures the fastest expansion trajectory among delivery channels. Hospice Care occupies concentrated margin pools tied to per-diem reimbursement structures and length-of-stay optimization.
CMS, state Medicaid agencies, and OSHA shape workforce standards, reimbursement rates, and safety compliance across the sector. Medicare Advantage plan expansion forces providers to absorb utilization risk through capitated arrangements. Stakeholders must monitor state-level certificate-of-need reforms and staffing minimum rulemakings to calibrate capacity investments against policy-driven demand shifts.
Market Dynamics
Medicare's mandatory shift toward value-based reimbursement is fragmenting traditional post-acute care pathways, forcing providers to absorb utilization risk while CMS Five-Star quality ratings rewrite consumer selection algorithms across institutional and home-based settings.
Growth Catalysts
- IRA Medicare Advantage expansion:Capitated payment models accelerate hospital-at-home waivers, pulling post-surgical recovery into residential settings previously served by skilled nursing facilities.
- Sun Belt retiree migration:Florida, Texas, and Arizona concentrate demand for age-in-place services as Medicaid expansion patterns in these states reshape eligibility for dual-eligible populations.
- Remote patient monitoring:Bluetooth-enabled biometric devices and FDA-cleared algorithms extend clinical surveillance into patient homes, enabling earlier intervention and reduced readmission exposure.
Market Restraints
- Workforce supply compression:Licensed practical nurse vacancy rates exceed 15% in rural counties, constraining agency expansion into underserved geographies regardless of demand signals.
- Reimbursement rate stagnation:CMS home health prospective payment system updates lag wage inflation in metropolitan statistical areas, compressing operating margins for Medicare-certified providers.
- Certificate-of-need moratoria:Twelve states maintain CON restrictions on new hospice licenses, artificially limiting bed supply in markets with demonstrated demand growth.
Strategic Opportunities
- Rural health clinic partnerships:Federally qualified health centers in Appalachian and Delta regions lack post-acute infrastructure, creating white space for mobile skilled nursing deployment.
- Telehealth-physical therapy convergence:Synchronous video platforms combined with motion-sensing wearables enable remote functional assessment, penetrating markets with therapist shortages.
- State Medicaid 1115 waivers:California and New York experimental programs now cover personal care services for non-elderly disabled adults, expanding addressable populations beyond traditional Medicare demographics.
Industry Challenges
- Interoperability implementation:CMS Promoting Interoperability standards require bidirectional EHR exchange between home health agencies and hospital discharge planners, demanding capital investment in HL7 FHIR infrastructure.
- Clinician retention:Burnout-driven turnover among certified nursing assistants forces continuous recruitment and training cycles that degrade care continuity metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Care Services Market |
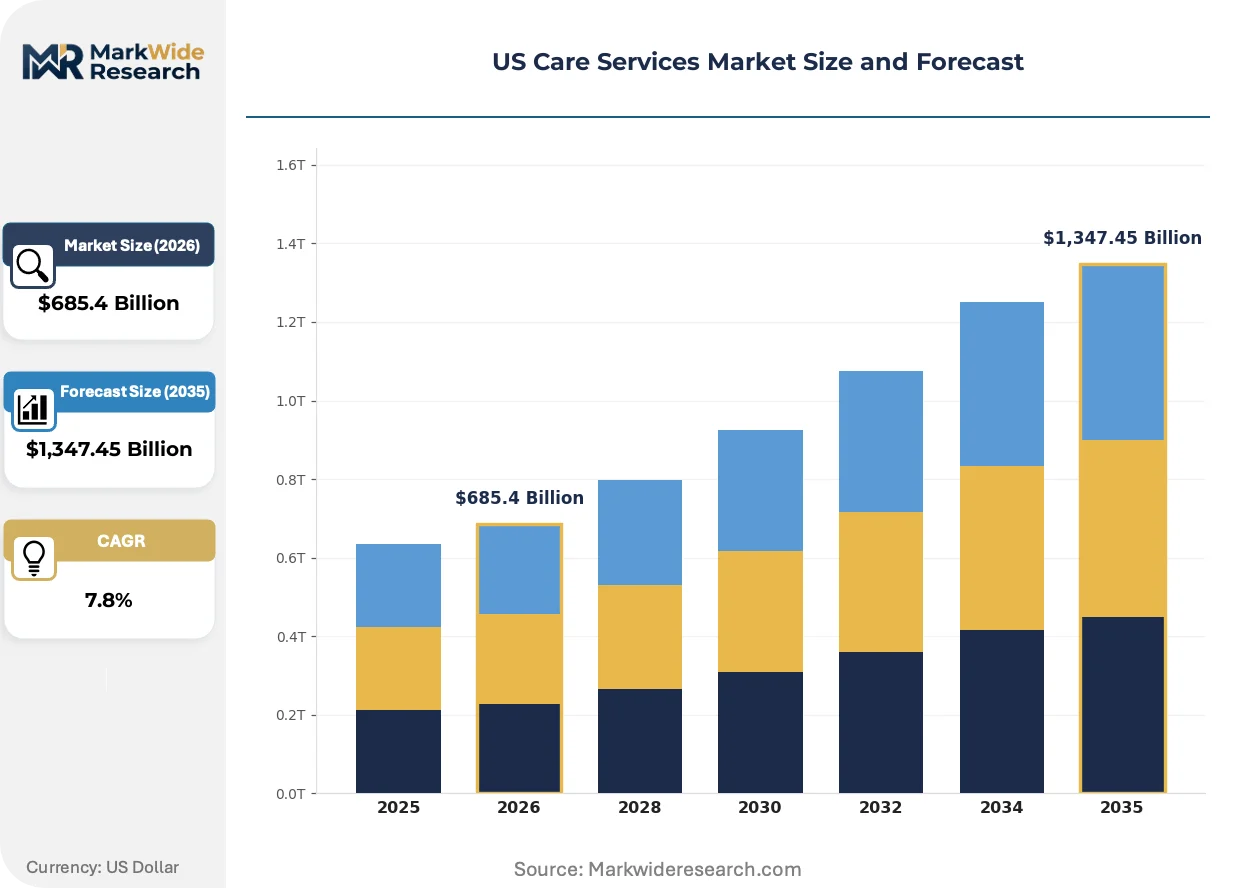
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,347.45 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Home Health Care, Hospice Care, Skilled Nursing Facilities, Rehabilitation Services End User: Elderly Patients, Disabled Individuals, Post-Surgical Patients, Palliative Care Patients Delivery Mode: In-Home Services, Outpatient Services, Facility-Based Services, Telehealth Payment Model: Private Pay, Medicare, Medicaid, Long-Term Care Insurance |
| Companies Covered | Kindred Healthcare, LLC, Amedisys, Inc, Sunrise Senior Living, LLC, Brookdale Senior Living, Inc, National HealthCare Corporation, Genesis Healthcare, Inc, Capital Senior Living Corporation, Home Instead, Inc, LHC Group, Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Care Services Market Strategic Shifts & Innovations
Digital infrastructure is penetrating care coordination workflows, replacing paper-based referral systems and enabling real-time visibility across previously siloed institutional and community-based providers.
Artificial intelligence risk stratification is decomposing traditional episode-based care management. Predictive algorithms ingest claims data, social determinants, and biometric feeds to flag high-risk patients before acute deterioration. Medicare Advantage plans in Pennsylvania and Ohio have deployed these tools to compress emergency department utilization. The technology is decomposing the role of clinical intuition in resource allocation, shifting decisions toward algorithmic triage protocols.
OSHA's updated bloodborne pathogens standard and state-level safe patient handling legislation are mandating mechanical lift equipment and needlestick prevention systems in home health settings. Compliance timelines vary by state, with Illinois and Massachusetts enforcing earlier adoption than federal minimums. Home health agencies in these jurisdictions report 12-18 month capital deployment cycles to achieve certification, creating temporary competitive gaps between compliant and non-compliant operators.
Beneficiary enrollment patterns are rotating toward Medicare Advantage at the expense of fee-for-service Medicare, with particular concentration in suburban counties where plan marketing investments concentrate. This channel shift forces providers to negotiate capitated rates rather than bill per-visit, compressing revenue cycle timelines and demanding upfront cost absorption. The behavioral pivot is most visible in Maricopa County, Arizona and Orange County, Florida, where MA penetration exceeds 55% of eligible beneficiaries.
US Care Services Market Segmentation
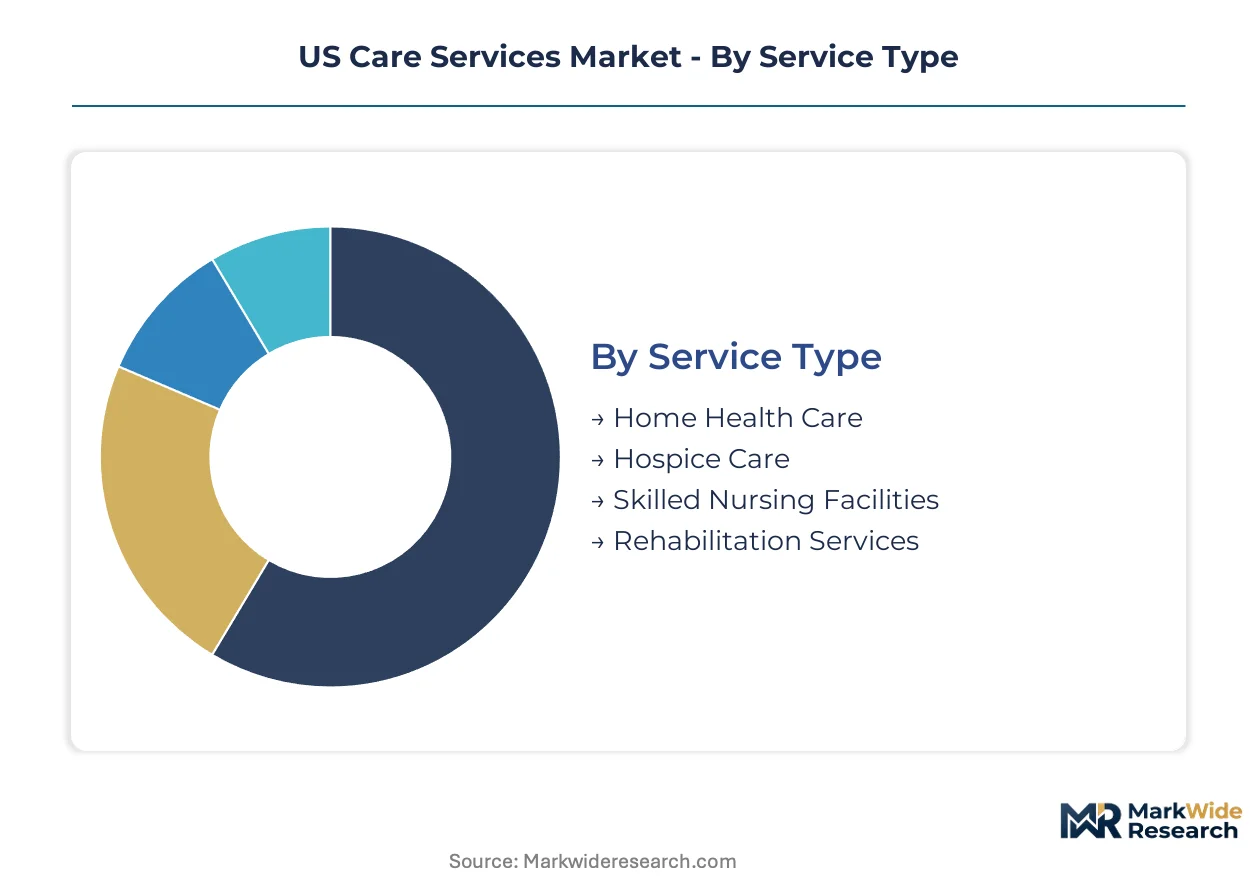
Segmentation in US Care Services determines reimbursement pathways, staffing requirements, and capital deployment intensity. Each dimension—service type, end user, delivery mode, and payment model—carries distinct regulatory overlays and margin profiles that shape provider strategy.
Service Type:
Margin pools concentrate in episodic care models where per-visit reimbursement can be optimized against standardized visit frequencies, while chronic disease management segments compete on scale economies.
- Home Health Care:Medicare-certified agencies deliver skilled nursing, physical therapy, and wound care in residential settings. Demand clusters in Maricopa County, Arizona and Orange County, Florida where Medicare Advantage penetration exceeds 55% and hospital-at-home waivers pull post-surgical recovery from institutional settings.
- Hospice Care:Per-diem reimbursement structures reward length-of-stay optimization and bereavement service bundling. Certificate-of-need moratoria in twelve states artificially constrain bed supply, creating margin concentration in deregulated markets.
- Skilled Nursing Facilities:CMS Five-Star quality ratings now drive consumer selection, forcing capital reinvestment in infection control infrastructure and therapy gym modernization.
- Rehabilitation Services:Post-acute recovery protocols following joint replacement surgery generate predictable episode volumes tied to orthopedic hospital partnerships.
The dominant share belongs to Home Health Care, while Hospice Care is closing the gap fastest.
End User:
Customer acquisition costs vary sharply across disability status and age cohorts, with dual-eligible populations requiring specialized enrollment navigation.
- Elderly Patients:Medicare-eligible beneficiaries over 65 drive volume concentration in Sun Belt retirement corridors. Florida, Texas, and Arizona absorb disproportionate migration flows, stretching agency capacity during seasonal peaks.
- Post-Surgical Patients:Orthopedic and cardiac recovery episodes represent the fastest-expanding addressable population as bundled payment models shorten institutional lengths of stay.
- Disabled Individuals:California and New York Medicaid 1115 waivers now extend personal care services to non-elderly adults, opening eligibility beyond traditional Medicare demographics.
- Palliative Care Patients:Concurrent care models allow curative treatment alongside symptom management, though billing complexity limits provider participation.
Elderly Patients retain the largest enrolled base, yet Post-Surgical Patients are gaining share fastest as surgical volumes rebound and site-of-care shifts accelerate.
Delivery Mode:
Capital intensity separates physical infrastructure requirements from technology-enabled alternatives, with regulatory clarity still evolving for hybrid models.
- Telehealth:Synchronous video platforms combined with FDA-cleared remote monitoring devices enable functional assessment and medication reconciliation without physical presence. Pennsylvania and Ohio Medicare Advantage plans have deployed AI risk stratification tools to compress emergency department utilization through this channel.
- In-Home Services:Licensed practical nurse deployment to residential addresses requires OSHA-compliant mechanical lift equipment and needlestick prevention systems, with Illinois and Massachusetts enforcing earlier adoption than federal minimums.
- Facility-Based Services:Brick-and-mortar skilled nursing and inpatient rehabilitation maintain clinical staffing ratio requirements that vary by state Medicaid plan.
- Outpatient Services:Ambulatory therapy clinics compete on geographic convenience and parking accessibility in suburban markets.
Facility-Based Services still account for the greatest revenue volume, though Telehealth is climbing the fastest as interoperability standards mature and reimbursement parity expands.
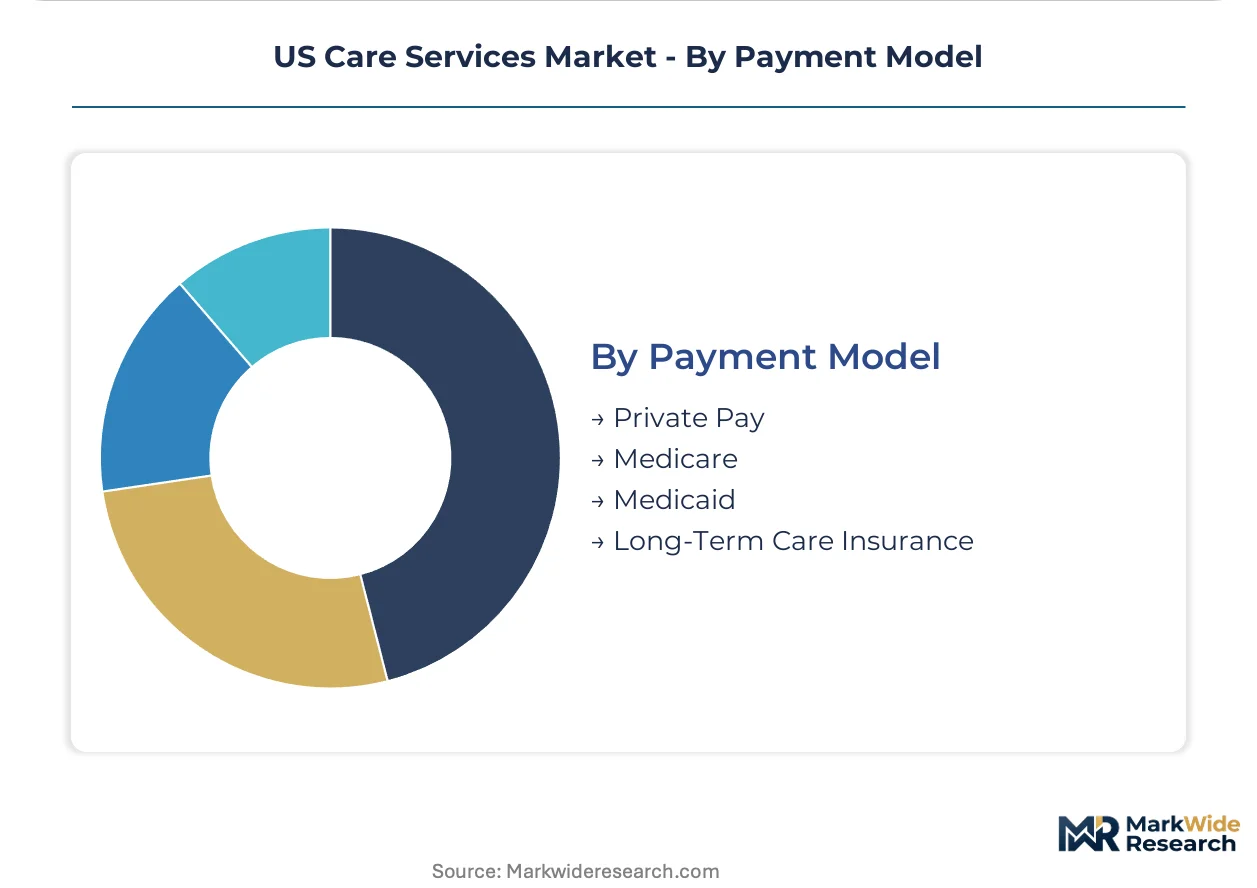
Payment Model:
Revenue cycle predictability and bad debt exposure differentiate payer categories, with capitated arrangements forcing upfront cost absorption.
- Medicare:Fee-for-service prospective payment systems for home health and hospice set national base rates adjusted for wage indices, though annual updates lag metropolitan inflation.
- Medicare Advantage:Capitated arrangements with delegated risk transfer now dominate suburban counties where plan marketing investments concentrate, compressing revenue cycle timelines.
- Medicaid:State-administered programs with federal matching vary dramatically in personal care service coverage and provider reimbursement levels.
- Private Pay:Self-funded long-term care purchases concentrate in affluent markets where asset thresholds exceed Medicaid eligibility.
- Long-Term Care Insurance:Policy lapse rates and benefit trigger definitions create claims complexity that delays provider payment.
Medicare retains the dominant share, yet Medicare Advantage is gaining enrollment fastest as beneficiary migration from fee-for-service accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agency capacity clusters in Sun Belt metros where Medicare Advantage penetration and retiree migration concentrate demand. State-level Medicaid expansion patterns and certificate-of-need regimes create divergent supply constraints across sub-regional markets.
Florida
Orange County and Tampa Bay absorb seasonal retiree influxes that strain home health nursing pools during winter peaks. The state maintains no certificate-of-need restrictions on hospice licensing, enabling rapid capacity response to demand growth. Miami-Dade and Palm Beach counties host dense networks of Medicare-certified agencies competing for Medicare Advantage contract volumes.
Texas
Houston and Dallas-Fort Worth metroplexes concentrate post-surgical home health demand from expanding hospital-at-home programs. Texas Medicaid 1115 waiver experiments now cover personal care services for non-elderly disabled adults, broadening addressable populations beyond traditional Medicare demographics. San Antonio and Austin agencies report licensed practical nurse vacancy rates below state rural averages due to urban clinical labor pools.
Arizona
Maricopa County exceeds 55% Medicare Advantage penetration, compressing revenue cycles toward capitated arrangements and demanding upfront cost absorption from providers. OSHA-compliant mechanical lift equipment mandates arrive earlier than federal minimums, forcing 12-18 month capital deployment cycles. Tucson and Flagstaff markets remain underserved relative to retiree migration flows, creating white space for mobile skilled nursing deployment.
California
Los Angeles County and Bay Area metros anchor Medicaid 1115 waiver programs covering personal care services for non-elderly disabled adults, expanding eligibility beyond traditional Medicare boundaries. State safe patient handling legislation enforces mechanical lift adoption timelines ahead of federal standards. Rural Central Valley counties face 15%+ licensed practical nurse vacancy rates that constrain agency expansion regardless of demand signals.
New York
New York City and Long Island concentrate dual-eligible enrollment navigation complexity, elevating customer acquisition costs for Medicaid-managed care plans. State Medicaid 1115 waivers mirror California's expansion of personal care services to non-elderly disabled populations. Upstate markets including Buffalo and Rochester exhibit lower Medicare Advantage penetration, preserving fee-for-service revenue cycle structures for longer timelines.
US Care Services Market Key Industry Players
Concentration sits with multi-site institutional operators and Medicare-certified home health networks. The vendor base spans publicly traded REIT-structured senior housing corporations, hospital-affiliated post-acute platforms, and founder-owned regional agencies. Three archetypes dominate: geographic cluster specialists optimizing Sun Belt density, hospital partnership integrators managing post-acute transitions, and technology-enabled remote monitoring deployers. Competitive moves center on Medicare Advantage contract capture and state-level certificate-of-need license accumulation.
Within the geographic clustering tier, Brookdale Senior Living anchors Sun Belt metro concentration strategies, while Kindred Healthcare exemplifies hospital-based partnership models for post-acute transitions. Amedisys occupies a position within Medicare-certified agency network expansion, representing the scale-driven archetype focused on home health volume aggregation through certified site proliferation.
| Leading Market Players |
|---|
| Kindred Healthcare, LLC |
| Amedisys, Inc |
| Sunrise Senior Living, LLC |
| Brookdale Senior Living, Inc |
| National HealthCare Corporation |
| Genesis Healthcare, Inc |
| Capital Senior Living Corporation |
| Home Instead, Inc |
| LHC Group, Inc |
| Others |
Cost & Logistics Intelligence
Fourteen-day inventory cycles for mechanical lift equipment and OSHA-compliant safety systems concentrate procurement leverage among distributors serving Illinois and Massachusetts, compressing margins for agencies in early-adoption states while amplifying pricing power for suppliers with certified product lines.
Pricing Analysis
CMS home health prospective payment system updates dictate the pricing tier structure across Medicare-certified agencies, with reimbursement rates stratifying across metropolitan wage indices, rural add-on adjustments, and value-based quality incentives. Price differentiation hinges on geographic wage index differentials and Medicare Advantage capitation rates versus fee-for-service benchmarks. Pricing pressure intensifies downward as annual CMS updates lag metropolitan inflation, squeezing operating margins in high-cost markets. Medicare Advantage plans exhibit lowest price sensitivity due to delegated risk absorption, while rural independent agencies face acute margin compression.
Supply Chain Analysis
Fourteen-day inventory cycles for mechanical lift equipment and OSHA-compliant safety systems concentrate procurement leverage among distributors serving Illinois and Massachusetts, compressing margins for agencies in early-adoption states. Supply draws from domestic medical equipment manufacturers in Ohio and Pennsylvania, plus imported electronic components from Taiwan and South Korea for remote monitoring devices. Single-source vulnerability concentrates in FDA-cleared biometric sensor modules. Distribution runs through regional durable medical equipment distributors holding exclusive territory agreements with hospital-at-home programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital-at-home waiver expansion is disrupting traditional site-of-care economics, creating asymmetric growth windows for providers capable of absorbing capitated risk.
For Market Incumbents: Consolidate Medicare Advantage contract portfolios in Maricopa County and Orange County where penetration exceeds fifty-five percent, locking in delegated risk arrangements before reimbursement rates compress further. Acquire certificate-of-need licenses in deregulated hospice markets to preempt capacity constraints. Vertical integration into remote patient monitoring hardware reduces per-episode cost exposure. For New Entrants and Emerging Players: Rural health clinic partnerships in Appalachian and Delta regions represent the most penetrable white space, where federally qualified health centers lack post-acute infrastructure. Target mobile skilled nursing deployment in Tucson and Flagstaff markets underserved relative to retiree migration flows. Pursue telehealth-physical therapy convergence using synchronous video platforms with motion-sensing wearables as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across OSHA compliance infrastructure, favoring scaled operators with twelve-to-eighteen month capital deployment cycles already completed. Long-term viability centers on Medicare-certified agency networks with dense Sun Belt clustering and established hospital partnership pipelines. Watch state-level certificate-of-need reform announcements as the primary inflection signal for hospice capacity expansion opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Medicare Advantage Contract Capture | Delegated risk arrangements with CMS-compliant quality metrics lock in recurring revenue streams. |
| Remote Patient Monitoring Deployment | FDA-cleared biometric devices extend clinical surveillance into patient homes under hospital-at-home waivers. |
| Certificate-of-Need License Accumulation | Preemptive licensing in deregulated hospice markets secures bed supply before artificial constraints tighten. |
| OSHA Compliance Infrastructure Investment | Mechanical lift equipment and needlestick prevention systems satisfy Illinois and Massachusetts early mandates. |
| Telehealth-Physical Therapy Convergence | Synchronous video platforms with motion-sensing wearables penetrate markets with licensed therapist shortages. |
Research Approach
A standing panel of home health agency executives, hospital discharge planners, Medicare Advantage contracting officers, and state Medicaid waiver administrators provided ongoing calibration across the study period. Primary interviews combined with secondary validation from CMS Medicare cost reports, state certificate-of-need filings, OSHA regulatory dockets, and hospital-at-home waiver program disclosures. Bottom-up agency capacity modeling triangulated against top-down expenditure forecasts from federal program actuaries.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, end user cohort, delivery mode, and payment model, with geographic clustering and regulatory framework as cross-cutting variables. CAGRs derived from historical expenditure trajectories, demographic migration patterns, and policy implementation timelines. Forecast inputs incorporated Medicare Advantage enrollment shifts and state Medicaid 1115 waiver expansion schedules.
Underlying assumptions cover reimbursement rate update trajectories, workforce supply recovery timelines, and technology adoption curves, with deviation risk concentrated in federal policy reversals on hospital-at-home waivers and state-level staffing minimum rulemakings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Hospice Market
Healthcare Services
South Korea Healthcare Cold Chain Logistics Market
Healthcare Services
Hospice and Palliative Care Centers Market
Healthcare Services
US Long Term Care Market
Healthcare Services
Medical Spa Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
Healthcare CMO Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
US Primary Care Physicians Market
Healthcare Services
Global Medical Affairs Outsourcing Market
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
Global Concierge Medicine Market
Healthcare Services
Per Diem Nurse Staffing Market