
 Tissue Banking Market | 2026-2036
Tissue Banking Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Banking Market Intelligence
A shortage of certified tissue recovery technicians is unwinding procurement capacity at several regional banks. Thermo Fisher Scientific leverages its cryopreservation media portfolio to anchor supply relationships with large hospital networks. BioLife Solutions sustains competitive differentiation through proprietary hypothermic storage solutions that extend tissue viability windows during transport. Lonza Group dominates contract manufacturing services for cell and tissue therapies, competing against integrated biobank operators that control end-to-end cold chain logistics.
Tissue banking encompasses the procurement, processing, preservation, storage, and distribution of human allografts for therapeutic or research use, requiring maintenance at temperatures between -80°C and -196°C for long-term viability. The primary commercial purpose is to supply sterile, traceable biological material for transplantation and regenerative medicine applications. Cryopreservation leads the storage method landscape due to its unmatched duration capacity, while regenerative medicine represents the fastest-growing end user segment as cell therapy developers seek qualified starting material. Skin and cornea product types command premium positioning because of urgent clinical need and shorter shelf-life constraints that compress supply availability.
The FDA enforces Current Good Tissue Practice (cGTP) regulations that mandate environmental monitoring and validated sterilization protocols, directly elevating compliance costs for market entrants. The EMA's Advanced Therapy Medicinal Products framework and the EU Tissue and Cells Directive impose parallel traceability requirements across European distribution channels. ISO 14155 and AATB accreditation standards further shape product quality benchmarks that determine institutional purchasing eligibility. Stakeholders must monitor evolving donor eligibility criteria and emerging pathogen detection technologies that could disqualify existing inventory or force process redesigns.
Market Dynamics
The FDA's Current Good Tissue Practice (cGTP) regulations are compressing operational margins while simultaneously raising barriers for new entrants, forcing incumbent operators to absorb validation costs that smaller banks cannot shoulder.
Growth Catalysts
- Orthopedic allograft demand:Hospitals in the United States are expanding utilization for reconstructive procedures, creating sustained procurement pull through established transplant infrastructure.
- Regenerative medicine pipeline:Cell therapy developers require qualified starting material under EMA's Advanced Therapy Medicinal Products framework, expanding addressable demand beyond traditional transplantation.
- Cryopreservation protocol standardization:ISO 14155 accreditation is becoming a mandatory purchasing criterion for institutional buyers, locking in premium positioning for compliant suppliers.
Market Restraints
- Donor screening cost inflation:Pathogen detection technology upgrades mandated by FDA HCT/P regulations are elevating per-unit recovery costs without commensurate reimbursement expansion.
- Technician supply concentration:Certified tissue recovery specialists cluster in metropolitan hospital corridors, leaving rural procurement zones chronically understaffed.
- Synthetic scaffold substitution:Biodegradable polymer alternatives for dermal applications are capturing price-sensitive segments that previously defaulted to allograft skin.
Strategic Opportunities
- Hypothermic transport extension:Proprietary storage solutions that extend viability windows during ground and air freight are opening distribution radius expansion for regional banks.
- Contract manufacturing services:Outsourced processing for cell therapy developers represents an emerging revenue stream distinct from traditional allograft banking.
- EU Tissue and Cells Directive harmonization:Cross-border accreditation mutual recognition is reducing redundant compliance costs for multi-jurisdictional operators.
Industry Challenges
- Cold chain integrity maintenance:Temperature excursions between -80°C and -196°C during multi-modal transport remain the leading cause of inventory disqualification.
- AATB accreditation timeline compression:Processing facility recertification cycles are accelerating, consuming technical staff bandwidth that would otherwise support volume expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Banking Market |
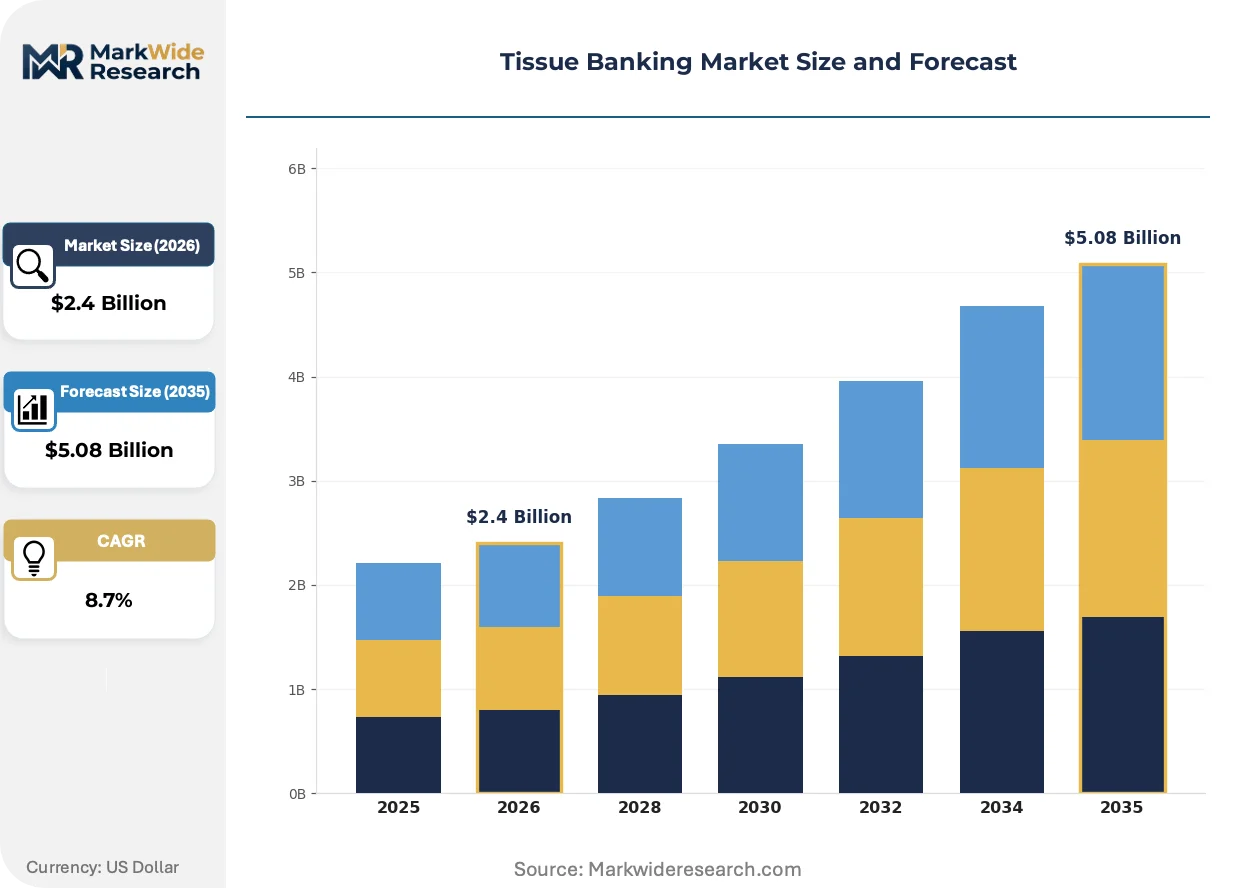
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone, Cartilage, Skin, Cornea Storage Method: Cryopreservation, Fresh, Dehydrated, Freeze-Dried End User: Hospitals, Research Institutes, Biobanks, Regenerative Medicine Application: Transplantation, Research, Drug Development, Tissue Engineering |
| Companies Covered | Thermo Fisher Scientific, BioLife Solutions, Sartorius, Eppendorf, Avantor, Azenta, Taylor-Wharton, Lonza Group, MTF Biologics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Banking Market Strategic Shifts & Innovations
Automation is penetrating tissue processing workflows, reducing human touchpoints that historically introduced contamination risk while compressing batch-to-batch variability that plagued manual protocols.
Next-generation cryopreservation media formulations are decomposing the traditional trade-off between storage duration and post-thaw viability. Cell therapy manufacturers are adopting these chemistries at accelerating pace to secure qualified starting material. The technology is decomposing regional procurement constraints by enabling longer-distance tissue sourcing without viability loss.
EMA's tightening donor eligibility criteria under the EU Tissue and Cells Directive are forcing European operators to redesign screening protocols. The industrial consequence is elevated documentation burden and extended quarantine periods for imported material. German and French hospital networks are responding by consolidating purchasing through accredited domestic banks with verified traceability systems.
Hospital procurement departments are consolidating allograft contracts through integrated delivery networks rather than maintaining fragmented supplier relationships with individual tissue banks. This concentration is displacing independent regional operators that lack scale to meet volume-commitment terms. The pattern is most visible in United States metropolitan markets where health system mergers have compressed vendor panels to three or fewer approved suppliers per product category.
Tissue Banking Market Segmentation
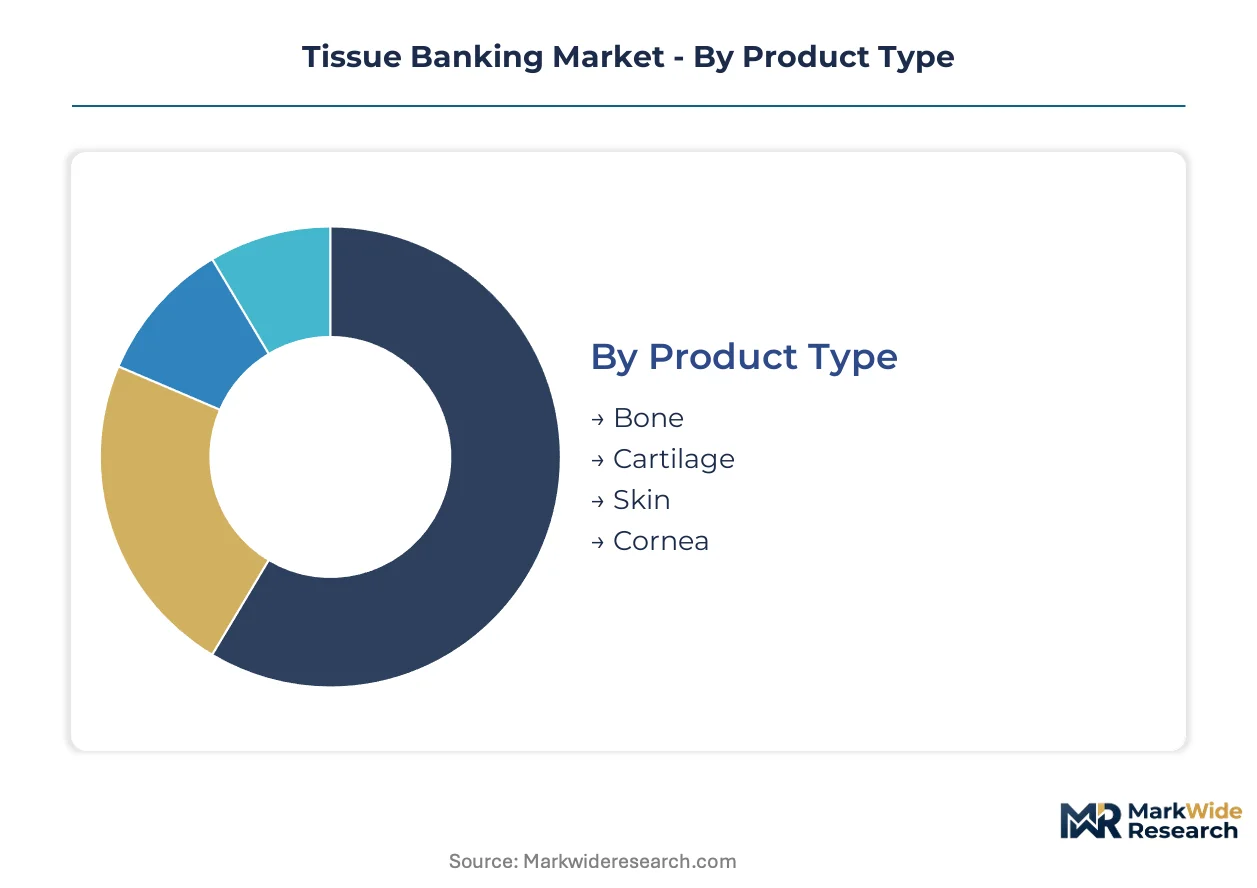
Tissue banking segmentation reveals divergent margin structures across preservation technologies and clinical applications. Procurement patterns vary sharply between emergency transplantation workflows and the extended qualification timelines required for regenerative medicine manufacturing.
Product Type:
Synthetic scaffold substitution pressure concentrates in dermal and cartilage segments where biodegradable polymers achieve functional equivalence at lower cost points.
- Bone:Structural allografts for spinal fusion and limb reconstruction command premium positioning due to load-bearing mechanical requirements. Hospital networks in the United States prioritize cortical bone for orthopedic trauma cases where synthetic alternatives lack osteoconductive performance.
- Skin:Split-thickness allografts face intensifying competition from engineered dermal matrices in burn care. Shorter shelf-life constraints compress supply availability, forcing burn centers to maintain redundant supplier relationships.
- Cartilage:Osteochondral grafts serve focal joint defects with limited synthetic alternatives. Sports medicine clinics drive procurement concentration in metropolitan corridors.
- Cornea:Optical clarity requirements and immune privilege properties sustain allograft dominance despite bioengineered substitutes in development. Eye banks maintain irreplaceable positioning in transplant infrastructure.
Bone retains volume leadership; skin holds the steepest expansion curve.
Storage Method:
Cost tier stratification separates institutional buyers by capital intensity and throughput requirements.
- Cryopreservation:Ultralow temperature protocols between -80°C and -196°C enable decade-scale storage for cell therapies and rare tissue types. Regenerative medicine developers under EMA's Advanced Therapy Medicinal Products framework mandate this method for qualified starting material.
- Fresh:Viability-dependent window of 24-72 hours restricts distribution radius to regional procurement zones. Cornea and vascular grafts dominate this category due to metabolic activity requirements.
- Dehydrated:Ambient-stable processing reduces cold chain burden for rural hospital networks with limited ultralow freezer infrastructure. Shelf-life extension trades against rehydration complexity.
- Freeze-Dried:Lyophilization achieves intermediate durability without continuous refrigeration. Military and disaster-response stockpiles favor this format for logistical flexibility.
Cryopreservation retains volume leadership; freeze-dried formats are gaining share fastest.
End User:
Customer type determines compliance burden intensity and contract structure complexity.
- Hospitals:Integrated delivery networks consolidate purchasing through accredited domestic banks with verified traceability systems. Orthopedic and burn care service lines drive procurement volume.
- Research Institutes:Academic medical centers require documented chain-of-custody for NIH-funded investigations. Quarantine period tolerance exceeds clinical transplantation standards.
- Biobanks:Population-scale repositories prioritize ISO 14155 accreditation for longitudinal study eligibility. German and French hospital networks source through these centralized facilities.
- Regenerative Medicine:Cell therapy manufacturers impose the most stringent donor eligibility criteria and documentation requirements. Outsourced processing represents an emerging revenue stream distinct from traditional allograft banking.
Hospitals retain volume leadership; regenerative medicine holds the steepest expansion curve.
Application:
Application maturity separates established reimbursement pathways from speculative development categories.
- Transplantation:Medicare reimbursement codes anchor demand predictability for cornea, skin, and bone grafts. FDA HCT/P regulations mandate environmental monitoring and validated sterilization protocols.
- Research:Exploratory protocols consume lower-grade tissue specimens excluded from clinical transplantation. Documentation burden remains substantial despite non-therapeutic end use.
- Drug Development:Toxicology and absorption studies utilize human tissue models for regulatory submission packages. Contract research organizations drive procurement concentration.
- Tissue Engineering:Scaffold seeding and bioreactor cultivation require sterile, traceable starting material with extended viability windows. Next-generation cryopreservation media formulations are decomposing regional procurement constraints.
Transplantation retains volume leadership; tissue engineering is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where established transplant infrastructure commands premium allograft valuations, while emerging procurement zones in Southeast Asia absorb compressed margins due to nascent cold chain networks.
United States
Hospital networks in Texas and Florida drive orthopedic allograft procurement volume through integrated delivery systems. FDA HCT/P regulations mandate validated sterilization protocols that elevate compliance costs for market entrants. The Greater Boston corridor anchors regenerative medicine demand as cell therapy developers seek qualified starting material under cGTP standards.
Germany
University hospital clusters in Bavaria and North Rhine-Westphalia sustain cornea and bone graft consumption for reconstructive procedures. EMA's Advanced Therapy Medicinal Products framework imposes traceability requirements that favor domestic banks with verified chain-of-custody systems. The Frankfurt-Rhine-Main biotech corridor concentrates contract manufacturing demand for European cell therapy developers.
Japan
Metropolitan Tokyo and Osaka medical centers prioritize cryopreserved allografts for ophthalmic transplantation. PMDA enforcement of ISO 14155 accreditation standards determines institutional purchasing eligibility for biobank operators. The Kansai region hosts specialized eye banks that supply domestic demand while maintaining export relationships with Southeast Asian markets.
India
Maharashtra and Karnataka state hospitals expand burn care capacity, intensifying split-thickness skin graft procurement. CDSCO tissue and cell regulations are tightening donor screening protocols that extend quarantine periods for imported material. The Delhi-NCR corridor concentrates emerging biobank infrastructure serving academic medical centers and contract research organizations.
Australia
New South Wales and Victoria public health systems sustain corneal transplantation networks with established eye bank partnerships. TGA compliance with EU Tissue and Cells Directive harmonization reduces redundant accreditation costs for multi-jurisdictional operators. The Melbourne biomedical precinct anchors research-grade tissue distribution for longitudinal population studies.
Tissue Banking Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where integrated biobank operators compete against specialized equipment and media suppliers. The market fragments across three strategic layers: end-to-end tissue bank operators controlling cold chain logistics, cryopreservation media specialists anchoring supply relationships, and contract manufacturing service providers serving cell therapy developers. Dominant competitive moves include strategic partnerships between equipment vendors and hospital networks, plus geographic expansion through accreditation mutual recognition agreements.
Among laboratory equipment and consumables specialists, Thermo Fisher Scientific and BioLife Solutions occupy positions representing the technology-driven archetype, while Lonza Group exemplifies the contract manufacturing service model. These three entities anchor the competitive structure without exhausting the vendor landscape, as regional tissue banks and emerging hypothermic storage specialists fill gaps between global equipment suppliers and localized procurement networks.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| BioLife Solutions |
| Sartorius |
| Eppendorf |
| Avantor |
| Azenta |
| Taylor-Wharton |
| Lonza Group |
| MTF Biologics |
| Others |
Cost & Logistics Intelligence
Thirty-day quarantine windows for donor screening compress inventory velocity and concentrate pricing power among accredited domestic banks with validated sterilization infrastructure. The United States commands premium positioning for cortical bone and corneal grafts where FDA cGTP compliance elevates procurement costs beyond what emerging markets can absorb.
Pricing Analysis
The customization-premium spread separates configured-to-order regenerative material from standard allograft catalogs. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 14155 accreditation status, cryopreservation protocol complexity, and after-sales traceability documentation. Pricing pressure stems from synthetic scaffold substitution in dermal applications where biodegradable polymers undercut allograft skin on unit economics. Research institutes exhibit highest price sensitivity due to NIH funding constraints, while regenerative medicine developers accept premium tiers for qualified starting material under EMA ATMP frameworks.
Supply Chain Analysis
The United States anchors tissue recovery operations with established eye bank networks and metropolitan hospital procurement corridors. Germany and Japan concentrate specialized processing capacity for corneal and osteochondral grafts. Raw material flows draw from voluntary donor registries, recovery technician labor pools, and cryopreservation media chemistries. Single-source vulnerability concentrates in certified recovery specialist availability, particularly in rural procurement zones. Distribution runs through integrated delivery networks that consolidate hospital purchasing through three-or-fewer approved suppliers per product category.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue banking market enters a cyclical recovery phase as orthopedic procedure volumes rebound from pandemic-depressed baselines and regenerative medicine pipelines advance toward commercial manufacturing.
For Market Incumbents: Consolidate procurement relationships with integrated delivery networks before health system mergers compress vendor panels further. Acquire regional banks in understaffed rural corridors to secure donor access outside metropolitan competition. Invest in automation-enabled processing facilities to absorb AATB recertification bandwidth without sacrificing volume expansion capacity. For New Entrants and Emerging Players: Lead with hypothermic transport solutions that extend viability windows for regional banks seeking distribution radius expansion. Target contract manufacturing services for European cell therapy developers facing EMA donor eligibility redesigns. Position through ISO 14155 accreditation as mandatory purchasing criteria harden among institutional buyers. For Investors and Strategic Acquirers: Carve-out targets emerge from hospital system biobank operations seeking capital-light models. Long-term viability hinges on exposure to regenerative medicine manufacturing rather than commoditized transplantation supply. Monitor EMA and FDA donor eligibility criteria evolution as inflection indicators that could disqualify existing inventory or force process redesigns at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Processing Facility Deployment | Reduces contamination risk from human touchpoints while compressing batch-to-batch variability under cGTP standards. |
| Next-Generation Cryopreservation Media Launch | Decomposes storage-duration versus post-thaw-viability trade-offs for cell therapy qualified starting material. |
| Cross-Border Accreditation Mutual Recognition | Reduces redundant compliance costs for multi-jurisdictional operators under EU Tissue and Cells Directive harmonization. |
| Contract Manufacturing Partnership with Cell Therapy Developers | Opens revenue stream distinct from traditional allograft banking under EMA ATMP traceability requirements. |
| Integrated Delivery Network Consolidation | Locks in volume-commitment terms before hospital procurement departments compress vendor panels to three suppliers. |
Research Approach
A standing panel of tissue bank operations directors, AATB accreditation specialists, hospital procurement managers, and cell therapy manufacturing executives provided ongoing calibration across the study period. Primary interview findings combined with secondary validation from FDA HCT/P guidance documents, EMA ATMP framework submissions, AATB annual reports, and hospital GPO contract databases. Bottom-up segment sizing triangulated against top-down market boundary checks from regulatory filing disclosures.
Consistency checks validated volume and value outputs against external benchmarks from customs trade data and institutional procurement disclosures across the projection horizon. Segmentation modeling incorporated preservation technology, product type, end-user archetype, application maturity, and regional regulatory cluster dimensions. CAGRs derived from procedure volume trajectories, reimbursement pathway stability, and regenerative medicine pipeline advancement rates.
The analysis sits within stated boundaries; outcomes outside sustained orthopedic procedure recovery or accelerated synthetic scaffold substitution would require recalibration. Forecasts reflect assumptions regarding FDA enforcement continuity, EMA donor eligibility stability, and cold chain infrastructure investment trajectories. Recalibration cycles align with material shifts in AATB accreditation timelines and pathogen detection technology mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Perfusion Services Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Medical Spa Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
US Acute Hospital Care Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Direct-To-Patient Healthcare Logistics Market
Healthcare Services
India Senior Living Market
Healthcare Services
Global Cord Blood Banking Services Market
Healthcare Services
Per Diem Nurse Staffing Market
Healthcare Services
Global Hospital Services Market
Healthcare Services
US Care Services Market
Healthcare Services
UK Ambulatory Services Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
US Hospice Care Market