
 North America Healthcare Cold Chain Logistics Market | 2026-2036
North America Healthcare Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Healthcare Cold Chain Logistics Market Intelligence
Multi-source outsourcing among biopharma shippers is expanding as vaccine and cell therapy pipelines diversify temperature requirements. FedEx leverages its specialized healthcare network to dominate time-critical biologics transport across the continent. Cencora anchors pharmaceutical distribution through controlled-environment warehousing in key population centers. UPS Healthcare differentiates via sensor-integrated monitoring platforms that track shipment integrity in real time.
Healthcare cold chain logistics encompasses the temperature-controlled storage, handling, and distribution of pharmaceutical products requiring maintenance between 2°C and 8°C or cryogenic conditions below -150°C, utilizing validated thermal packaging, continuous monitoring systems, and documented chain-of-custody protocols to preserve product efficacy from manufacture through patient administration. Refrigerated trucks and temperature-controlled warehouses constitute the mature infrastructure backbone where capital intensity creates high barriers to entry, while IoT devices and RFID tracking represent the fastest-expanding technology layer as real-time visibility becomes non-negotiable for gene therapy sponsors. Biologicals and vaccines command premium service margins due to stringent stability requirements, whereas clinical trial materials drive specialized demand for flexible, small-batch cold chain configurations.
FDA enforces Current Good Manufacturing Practice and Good Distribution Practice standards that mandate continuous temperature documentation, directly elevating compliance costs for logistics providers without validated cold chain infrastructure. Health Canada and the EPA jointly influence packaging material regulations and refrigerant emissions standards that shape equipment procurement decisions across cross-border operations. Stakeholders must monitor evolving cell and gene therapy temperature profiles that will force capital allocation toward cryogenic-capable infrastructure and redundant monitoring architectures.
Market Dynamics
FDA's tightening Good Distribution Practice validation requirements are forcing logistics providers to rebuild container qualification protocols, compressing competitive timelines and elevating capital barriers for temperature-controlled infrastructure across the United States and Canada.
Growth Catalysts
- Cell and gene therapy pipelines:Biotech sponsors require cryogenic-capable distribution networks below -150°C for CAR-T and gene-edited products, pulling specialized 3PL capacity into development.
- Health Canada harmonization:Alignment with FDA temperature documentation standards accelerates cross-border biologics movement through Ontario and Quebec distribution corridors.
- IoT sensor density:Real-time monitoring platforms now capture location, temperature, and shock data at 15-minute intervals, satisfying sponsor audit requirements for chain-of-custody verification.
Market Restraints
- Dry ice supply concentration:Regional carbon dioxide capture capacity limits constrain cryogenic packaging availability during vaccine surge periods.
- Refrigerant phase-down schedules:EPA hydrofluorocarbon restrictions under AIM Act compliance timelines force cold storage operators into premature equipment replacement cycles.
- Validated packaging lead times:Thermal container qualification studies require 12-18 month stability protocols, freezing out smaller logistics entrants from biologics contracts.
Strategic Opportunities
- Midwestern distribution gaps:Chicago and Minneapolis cold storage capacity lags Northeast corridor density, creating first-mover advantage for temperature-controlled warehouse development.
- Reusable thermal container networks:Reverse logistics infrastructure for qualified shippers reduces per-shipment packaging costs while satisfying EPA waste reduction incentives.
- RNA therapeutics expansion:mRNA manufacturing scale-up in Massachusetts and Pennsylvania generates demand for -80°C distribution lanes beyond traditional vaccine cold chain profiles.
Industry Challenges
- Cryogenic technician scarcity:Liquid nitrogen handling certification and dangerous goods training programs cannot match biologics facility expansion rates in New Jersey and Maryland.
- Legacy WMS integration:Warehouse management systems designed for ambient pharmaceutical storage require expensive retrofitting to capture continuous temperature telemetry for FDA audit trails.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Healthcare Cold Chain Logistics Market |
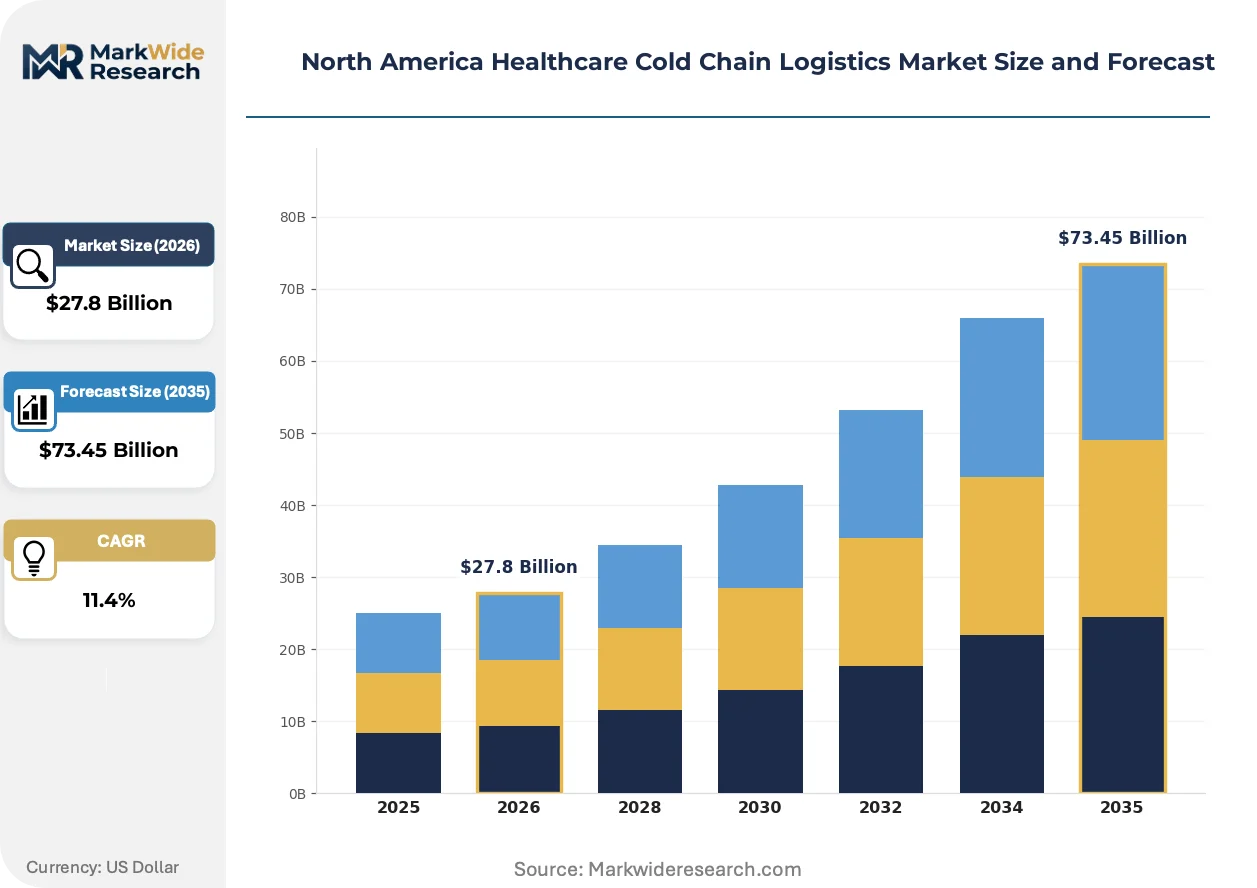
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $73.45 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Biologicals, Vaccines, Clinical Trial Materials End User: Hospitals, Pharmacies, Research Laboratories, Biotech Companies Service Type: Transportation, Packaging, Monitoring Solutions, Data Loggers Technology: Refrigerated Trucks, Temperature-Controlled Warehouses, IoT Devices, RFID Tracking |
| Companies Covered | Cencora, Cardinal Health, FedEx, UPS Healthcare, DHL Supply Chain, McKesson Corporation, AmerisourceBergen Corporation, Kuehne+Nagel, LifeConEx, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Healthcare Cold Chain Logistics Market Strategic Shifts & Innovations
Real-time visibility infrastructure is displacing retrospective temperature logging as the baseline compliance expectation, with sensor-integrated platforms now table stakes for biologics contracts rather than premium service differentiators.
Battery-electric refrigerated transport is electrifying last-mile delivery economics for temperature-sensitive shipments. Regional pharmacy chains and hospital networks in California and New York are piloting electric reefer vans for urban biologics distribution. This technology is electrifying total cost of ownership calculations by eliminating diesel price volatility while satisfying municipal emissions restrictions.
FDA's enhanced data integrity guidance for computerized systems is tightening validation requirements for cloud-based temperature monitoring platforms. Logistics providers must now demonstrate 21 CFR Part 11 compliance for electronic records used in distribution documentation. Small and mid-sized 3PLs in Pennsylvania and Illinois are responding by licensing validated software platforms rather than building proprietary systems.
Consolidated procurement of cold chain services is compressing vendor rosters among top-20 biopharma manufacturers. Sponsors now demand single-source accountability for multi-modal temperature-controlled movements, displacing fragmented lane-by-lane contracting. Massachusetts and New Jersey headquarters operations are most visible in this shift, with procurement teams centralizing spend under qualified global logistics partnerships.
North America Healthcare Cold Chain Logistics Market Segmentation
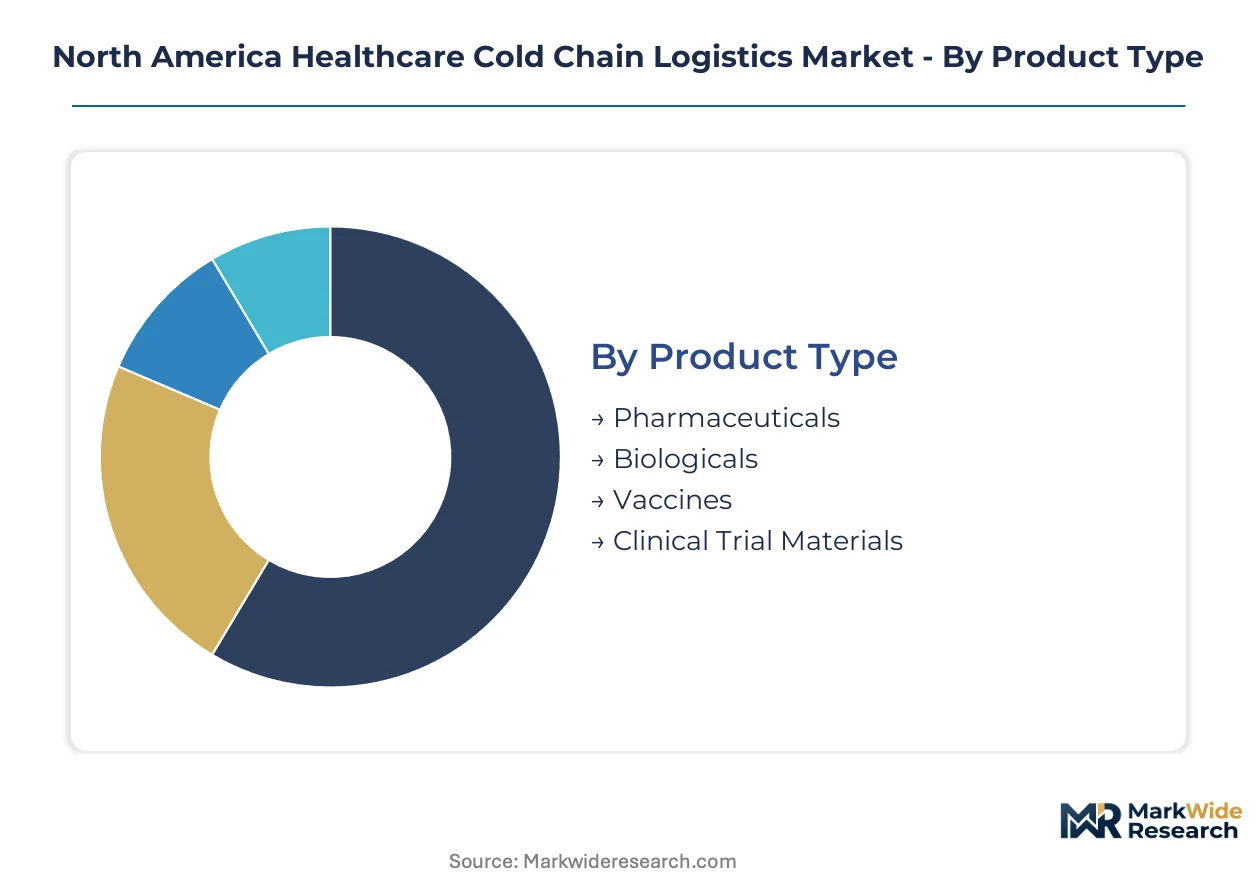
Healthcare cold chain logistics demands precise segment alignment between temperature profiles and infrastructure capabilities. Product stability requirements, end-user urgency thresholds, and technology integration layers each create distinct service configurations that logistics providers must match to capture contract value.
Product Type:
Upgrade cycles in thermal packaging and monitoring equipment track directly to product stability windows, with shorter shelf-life biologics forcing faster infrastructure refresh rates than traditional pharmaceuticals.
- Pharmaceuticals:Small-molecule drugs requiring 2°C to 8°C storage constitute the volume foundation of North American cold chain operations. Demand concentrates in generic injectables and insulin distribution through Pennsylvania and New Jersey distribution corridors, where FDA validation protocols for controlled-room temperature excursions create compliance premiums for qualified 3PLs.
- Biologicals:Monoclonal antibodies and recombinant proteins demand unbroken cold chains with narrow temperature bands. Massachusetts biotech clusters and Maryland bioscience corridors drive specialized demand for redundant monitoring architectures that satisfy sponsor audit requirements for commercial distribution.
- Vaccines:Bulk immunization programs require surge-capable distribution networks with validated thermal containers. Federal and state procurement contracts prioritize providers with demonstrated pandemic response scale.
- Clinical Trial Materials:Small-batch, patient-specific shipments need flexible cold chain configurations with rapid lane qualification. Investigational drug sponsors in California and North Carolina require adaptive logistics for temperature-sensitive comparator products.
Volume placements concentrate in Pharmaceuticals; the faster expansion belongs to Biologicals.
End User:
Customer procurement sophistication varies sharply across the care continuum, with hospital networks demanding integrated inventory visibility while research laboratories prioritize specimen integrity over cost optimization.
- Hospitals:Integrated delivery networks in Texas and Florida require just-in-time biologics replenishment with dock-to-pharmacy tracking. Health system consolidation is compressing vendor rosters toward single-source logistics partnerships with enterprise-wide temperature documentation.
- Biotech Companies:Cell therapy developers in Massachusetts and Maryland need cryogenic-capable distribution below -150°C for autologous product patient matching. Venture-funded pipeline expansion is pulling specialized 3PL capacity into pre-commercial development phases.
- Pharmacies:Retail and specialty pharmacy chains require last-mile cold chain integrity for patient-direct shipments. California and New York networks are piloting electric refrigerated vehicles for urban delivery compliance with municipal emissions restrictions.
- Research Laboratories:Academic medical centers and CROs need flexible, small-lot cold chain configurations for specimen transport. Clinical trial site networks in Illinois and Georgia require rapid lane qualification for temperature-sensitive biomaterials.
Contract value concentrates in Hospital networks; the steepest expansion trajectory belongs to Biotech Companies.
Service Type:
Margin capture shifts toward data-intensive service layers as sponsors demand real-time visibility over retrospective documentation, elevating monitoring solutions above commodity transportation in contract pricing.
- Transportation:Reefer trucking and air cargo constitute the infrastructure backbone where fuel volatility and driver scarcity compress operating margins. Interstate corridors connecting New Jersey, Pennsylvania, and Massachusetts carry the highest biologics freight density.
- Monitoring Solutions:Cloud-based temperature telemetry with 15-minute interval capture is displacing passive data loggers as the baseline compliance expectation. FDA 21 CFR Part 11 validation requirements for electronic records are forcing platform standardization among mid-sized 3PLs.
- Packaging:Qualified thermal containers with phase-change materials require 12-18 month stability studies that freeze out smaller logistics entrants. Reusable shipper networks are emerging as a cost-reduction mechanism for high-volume biologics sponsors.
- Data Loggers:Bluetooth-enabled disposable sensors provide low-cost chain-of-custody documentation for clinical trial materials. Battery life and calibration drift limitations constrain use to shorter-duration shipments.
Revenue concentration sits in Transportation; technology-led expansion is accelerating fastest in Monitoring Solutions.
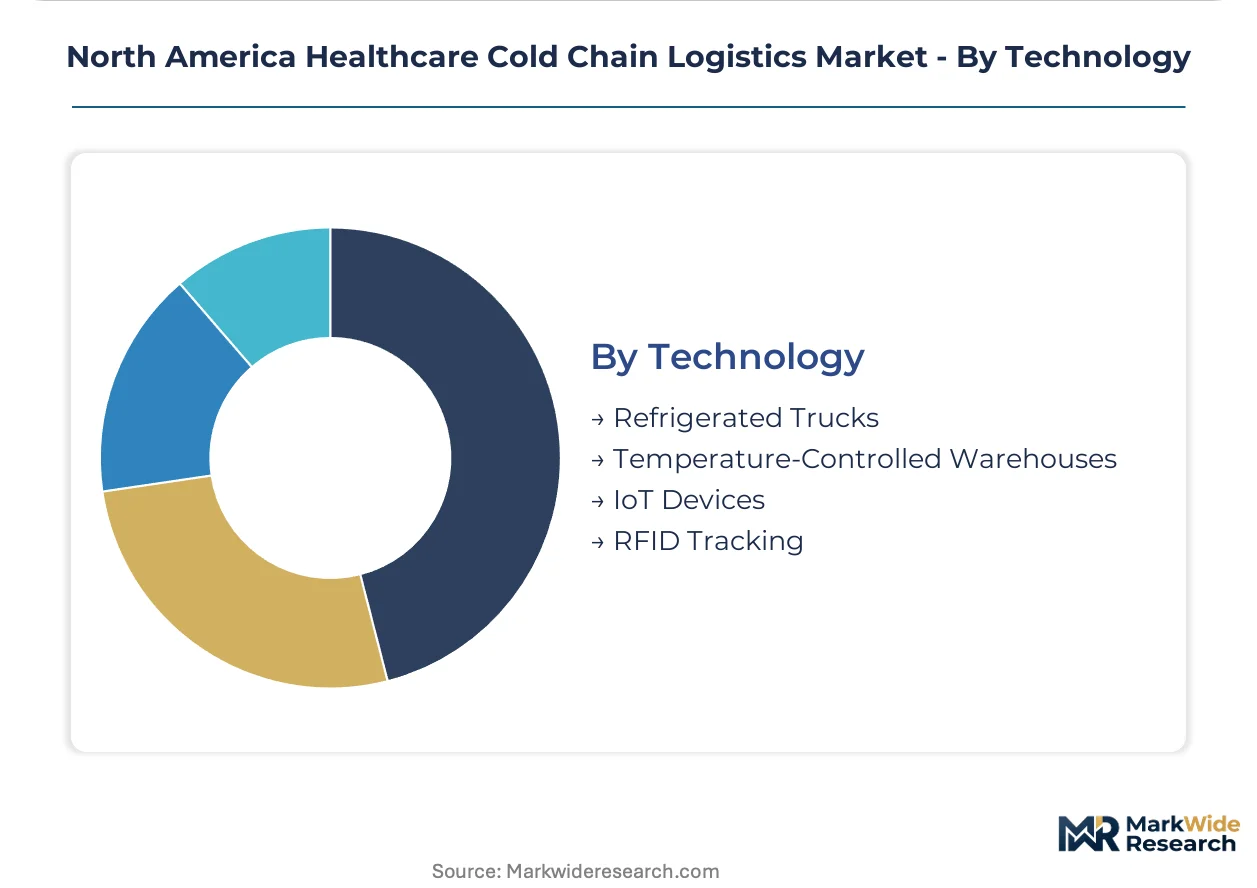
Technology:
Capital deployment patterns reveal infrastructure maturity versus innovation investment, with warehouse automation and IoT sensor density attracting disproportionate growth capital against established reefer fleet capacity.
- Temperature-Controlled Warehouses:Automated storage and retrieval systems in controlled-environment facilities anchor pharmaceutical distribution through population centers. Chicago and Minneapolis capacity lags Northeast corridor density, creating first-mover development opportunities.
- IoT Devices:Sensor-integrated platforms capturing location, temperature, and shock data in real time represent the fastest-expanding technology layer. Gene therapy sponsors now mandate continuous visibility as a non-negotiable contract requirement.
- Refrigerated Trucks:Diesel-powered reefer fleets constitute mature infrastructure where EPA refrigerant phase-down schedules under AIM Act compliance are forcing premature equipment replacement cycles. Battery-electric alternatives are electrifying total cost of ownership calculations for last-mile urban distribution.
- RFID Tracking:Passive and active radio-frequency identification enables automated inventory reconciliation and chain-of-custody verification. Integration with warehouse management systems requires expensive retrofitting for legacy ambient pharmaceutical facilities.
Installed base concentrates in Refrigerated Trucks; investment flows fastest into IoT Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical distribution concentrates in the Northeast pharmaceutical corridor spanning New Jersey, Massachusetts, and Pennsylvania, where biotech manufacturing density and FDA-regulated import gateways create unmatched cold chain demand.
United States
Massachusetts biotech clusters and Maryland bioscience corridors drive specialized demand for cryogenic-capable infrastructure below -150°C. FDA enforces Current Good Manufacturing Practice standards that mandate continuous temperature documentation, elevating compliance costs for logistics providers. New Jersey pharmaceutical distribution hubs anchor the continent's highest biologics freight density through validated controlled-environment warehousing.
Canada
Ontario and Quebec distribution corridors accelerate cross-border biologics movement through Health Canada harmonization with FDA temperature documentation standards. The country's national pharmaceutical regulator tightens container qualification protocols alongside EPA-aligned refrigerant emissions oversight. Toronto and Montreal cold storage facilities serve as critical staging points for temperature-sensitive products entering the United States.
Mexico
Northern border states concentrate pharmaceutical manufacturing investments targeting United States market access under USMCA trade provisions. Mexico's federal commission for protection against sanitary risk enforces cold chain standards for imported biologics and vaccines. Mexico City metro distribution networks expand temperature-controlled capacity to serve domestic healthcare systems and regional export lanes.
North America Healthcare Cold Chain Logistics Market Key Industry Players
Capacity expansion dominates the current landscape as logistics providers race to deploy cryogenic-capable infrastructure for cell therapy pipelines. The vendor base stratifies between integrated healthcare distributors, specialized express carriers, and global supply chain operators with pharmaceutical credentials. Three strategic archetypes define positioning: asset-heavy warehouse operators, technology-integrated transportation platforms, and hybrid providers combining physical infrastructure with compliance services. M&A activity and strategic partnerships concentrate competitive moves as sponsors demand single-source accountability for multi-modal temperature-controlled movements.
Within the integrated distribution tier, Cencora anchors pharmaceutical distribution through controlled-environment warehousing in key population centers. FedEx and UPS Healthcare represent the express carrier archetype, with the former leveraging specialized healthcare networks for time-critical biologics transport and the latter differentiating through sensor-integrated monitoring platforms. These three companies exemplify the capital intensity and regulatory compliance capabilities required to capture biologics contract value in FDA-regulated lanes.
| Leading Market Players |
|---|
| Cencora |
| Cardinal Health |
| FedEx |
| UPS Healthcare |
| DHL Supply Chain |
| McKesson Corporation |
| AmerisourceBergen Corporation |
| Kuehne+Nagel |
| LifeConEx |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up cold storage specialists in the Northeast pharmaceutical corridor anchor pricing discipline through concentrated ownership of FDA-validated warehouse capacity, while their financing structures demand yield compression that feeds back into selective equipment procurement and lane prioritization for biologics contracts.
Pricing Analysis
Volume concentrates in 2°C to 8°C pharmaceutical distribution where per-unit transactional pricing dominates, while cryogenic-capable services below -150°C capture premium margins through certification-grade differentiation and FDA validation tiers. Price differentiation rests on real-time monitoring integration and geographic delivery density, with Massachusetts and New Jersey corridors commanding service premiums against Midwestern lanes. Cost compression in standard cold chain tiers is intensifying because dry ice supply constraints and refrigerant phase-down schedules force premature equipment replacement. Hospital networks exhibit highest price sensitivity through consolidated procurement rosters, whereas cell therapy sponsors prioritize specimen integrity over cost optimization.
Supply Chain Analysis
Cryogenic technician scarcity in New Jersey and Maryland biologics corridors constrains facility expansion rates against pipeline growth, pulling specialized labor from adjacent manufacturing geographies. Supply concentrates in the United States for temperature-controlled warehousing and Canada for cross-border distribution staging, with Mexico's northern border states feeding USMCA-aligned pharmaceutical manufacturing. Raw material dependencies include liquid nitrogen supply, phase-change materials for thermal packaging, and EPA-compliant refrigerants for fleet operations. Single-source vulnerability runs through regional carbon dioxide capture capacity that limits dry ice availability during vaccine surge periods. Distribution feeds from automated Northeast corridor warehouses through validated reefer fleets to hospital networks and specialty pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time visibility infrastructure is displacing legacy retrospective temperature logging as the baseline compliance expectation, with sensor-integrated platforms now table stakes rather than premium differentiators for biologics contract capture.
For Market Incumbents: Extend cryogenic-capable infrastructure into pre-commercial cell therapy pipelines before venture-funded biotech sponsors lock in specialized 3PL partnerships. Consolidate monitoring platform investments to defend against cloud-native entrants offering 21 CFR Part 11-compliant telemetry at lower integration cost. Prioritize backward integration into reusable thermal container networks to capture packaging margin and satisfy EPA waste reduction incentives.
For New Entrants and Emerging Players: Sensor-integrated monitoring platforms with rapid deployment timelines offer the most penetrable wedge against legacy warehouse management systems requiring expensive retrofitting. Target Midwestern distribution gaps in Chicago and Minneapolis where cold storage capacity lags Northeast density and first-mover development advantages remain available. Lead with subscription-based visibility services that bypass capital-intensive warehouse construction while building sponsor relationships for future infrastructure expansion.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap cold storage operators with FDA-validated facilities in Pennsylvania and New Jersey corridors, where financing pressure from interest rate exposure creates acquisition windows below replacement cost. Long-term viability centers on cryogenic infrastructure positioning for cell and gene therapy commercialization, with monitoring technology capabilities as secondary value drivers. Watch Health Canada-FDA harmonization progress as signal for cross-border biologics volume inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Infrastructure Buildout | Positions 3PLs for CAR-T and gene-edited product distribution below -150°C. |
| Reusable Thermal Container Networks | Reduces per-shipment packaging costs while satisfying EPA waste reduction mandates. |
| 21 CFR Part 11 Platform Licensing | Enables mid-sized logistics providers to meet FDA data integrity requirements without proprietary development. |
| Midwestern Warehouse Development | Captures first-mover advantage in Chicago and Minneapolis capacity gaps against Northeast corridor saturation. |
| Battery-Electric Reefer Fleet Pilot | Aligns last-mile delivery with California and New York municipal emissions restrictions. |
Research Approach
Document review covered FDA guidance documents, EPA AIM Act compliance timelines, and Health Canada distribution standards, complemented by interviews with cold chain logistics executives, biotech supply chain directors, hospital pharmacy procurement managers, and thermal packaging engineers. Secondary validation drew from carrier fleet disclosures, warehouse development permits, and pharmaceutical sponsor RFP documentation. Bottom-up capacity modeling and top-down demand projections were triangulated against industry panel input.
Cross-referencing historical infrastructure deployment patterns with expert panel assessments shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include temperature profile tiers, end-user procurement sophistication, service type margin capture, and technology adoption intensity. CAGRs were derived through trend extrapolation adjusted for regulatory compliance cost inflation and capital availability constraints. Forecast inputs incorporated cell therapy pipeline advancement rates and refrigerant phase-down schedule impacts on equipment replacement cycles.
Several conditions sit outside the modeled scope, including pandemic-scale vaccine surge demand, radical battery-electric fleet adoption acceleration, and geopolitical disruption to cross-border pharmaceutical trade. Forecasts reflect assumptions about Health Canada-FDA harmonization progress and sustained venture funding for pre-commercial biologics. Material deviation in cryogenic technician training program expansion or dry ice supply infrastructure investment warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
UK Ambulatory Services Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
Global Mobile Clinics Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Healthcare Patent Filing Outsourcing Market
Healthcare Services
Professional Spa Services Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
Acute Care Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Australia and New Zealand Healthcare Logistics Market
Healthcare Services
Medical Second Opinion Market