
 Ozone Therapy Units Market | 2026-2036
Ozone Therapy Units Market Size, Share, and Industry Trends Forecast 2026-2036
Ozone Therapy Units Market Analytics
Medical-grade ozone concentration precision is bifurcating the competitive landscape between premium clinical suppliers and general wellness equipment makers. W&H Dentalwerk Burmoos GmbH leverages its precision engineering heritage to dominate dental ozone therapy applications across European clinics. J. Hänsler GmbH anchors the high-concentration segment with systems validated for hospital-grade sterilization protocols. Evozone GmbH differentiates through modular platform architectures that extend across multiple therapeutic modalities.
Ozone therapy units generate controlled ozone-oxygen mixtures for therapeutic administration, typically operating at concentrations between 10 and 100 micrograms per milliliter with precise flow regulation for patient safety. The equipment serves clinical applications spanning disinfection, oxygenation therapy, and localized immune modulation in regulated healthcare settings. Portable units lead volume sales in wellness centers and homecare channels where space constraints and mobility requirements shape procurement decisions. Stationary systems command margin concentration in hospital environments where integration with central gas supply infrastructure and compliance with IEC 60601-1 electrical safety standards determines vendor selection. Hybrid methods combining ozone generation with ultraviolet sterilization represent the fastest-growing technology segment as clinics seek dual-validation protocols for infection control.
The EU Medical Device Regulation and ISO 13485 quality management standards shape product certification pathways, with notified body involvement required for higher-risk device classifications that increasingly encompass therapeutic ozone generators. The US FDA maintains oversight through 510(k) clearance pathways for ozone therapy devices while state dental boards impose additional operational constraints on clinical use. Stakeholders must monitor evolving harmonization between European medical device standards and emerging national regulations in Asian clinical markets where ozone therapy adoption is accelerating.
Market Dynamics
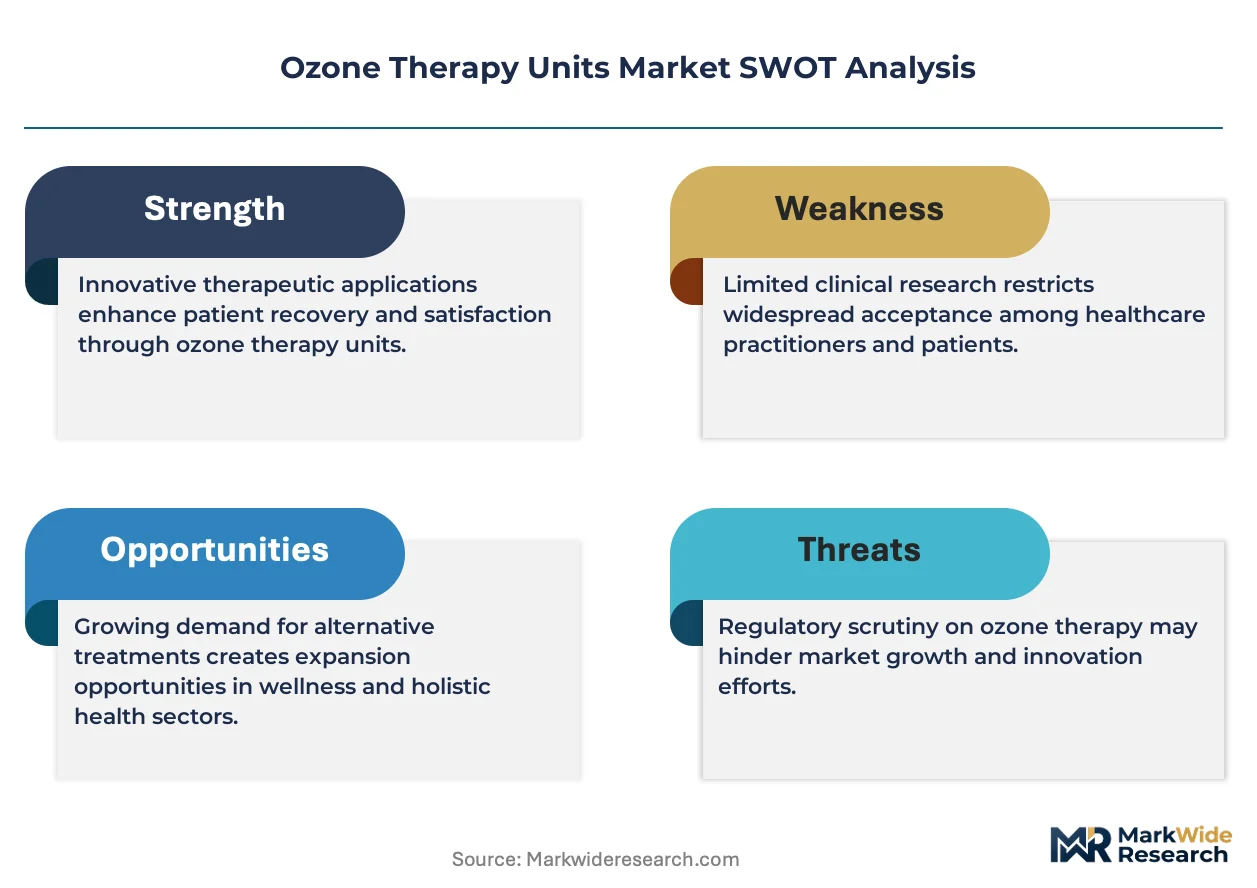
The EU Medical Device Regulation's escalating classification of therapeutic ozone generators is compressing vendor timelines and forcing capital reallocation toward notified body certification processes ahead of the 2026 enforcement cliff.
Growth Catalysts
- Chronic pain prevalence:Germany's statutory health insurance funds are expanding reimbursement codes for ozone therapy in orthopedic outpatient settings, validating clinical efficacy for musculoskeletal disorders.
- MDR harmonization:The EU Medical Device Regulation's centralized quality framework reduces fragmentation across member states, enabling cross-border equipment certification that accelerates market access for compliant manufacturers.
- Hybrid sterilization protocols:Integration of ozone generation with ultraviolet-C systems is decomposing single-modality equipment demand in dental and surgical sterilization workflows.
Market Restraints
- Platinum electrode supply concentration:Over 70% of medical-grade ozone generator electrodes rely on South African and Russian platinum group metal refining, exposing production costs to geopolitical supply shocks.
- Clinical evidence variability:Inconsistent randomized controlled trial outcomes for systemic ozone therapy create reimbursement friction with Germany's Federal Joint Committee and analogous bodies.
- Electromedical device substitution:Low-temperature hydrogen peroxide plasma sterilizers are capturing hospital central sterile supply department budgets previously allocated to ozone-based systems.
Strategic Opportunities
- Homecare channel expansion:Italy's regional health authorities are piloting remote patient monitoring programs that include portable ozone therapy units for post-surgical wound management in rural Lombardy and Sicily.
- Veterinary therapeutic crossover:Equine sports medicine clinics in Spain are adopting veterinary-certified ozone therapy systems originally developed for human orthopedic applications.
- CE-MDR pre-certification services:Third-party technical documentation consultancies are capturing margin from mid-tier manufacturers lacking in-house regulatory affairs capabilities.
Industry Challenges
- Notified body queue congestion:The EU's designated medical device conformity assessment organizations face 12-18 month backlogs for high-risk device classification reviews, freezing product launch timelines.
- Biocompatibility testing costs:ISO 10993 cytotoxicity and sensitization studies for ozone delivery tubing and catheters require capital outlays exceeding 250,000 euros per material formulation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ozone Therapy Units Market |
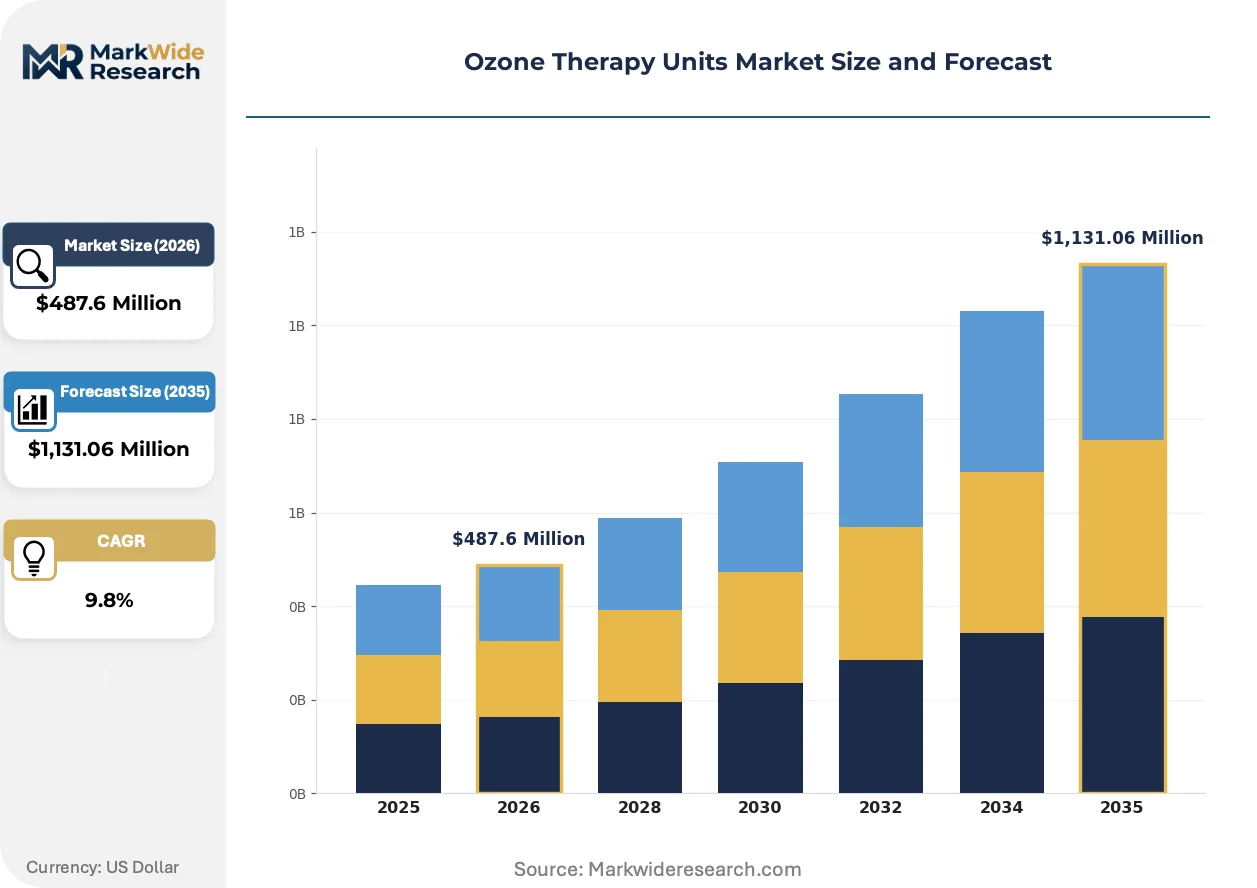
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,131.06 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Stationary Systems, Medical Devices, Accessories Technology: Ozone Generators, Ultraviolet Systems, Electrolytic Machines, Hybrid Methods Application: Chronic Pain Management, Skin Disorders, Dental Treatments, Respiratory Conditions End User: Clinics, Hospitals, Wellness Centers, Homecare |
| Companies Covered | Promolife, W&H Dentalwerk Burmoos GmbH, APOZA Enterprise Co., Ltd., Aquolab, J. Hänsler GmbH, Evozone GmbH, Herrmann Apparatebau GmbH, MIO International Ozonytron GmbH, Sedecal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ozone Therapy Units Market Evolving Landscape
Precision concentration control and dual-validation protocols are displacing legacy equipment architectures across European clinical procurement channels, while regulatory compliance automation reshapes vendor operational models.
Corona discharge ozone generators with closed-loop concentration feedback are decomposing legacy ultraviolet-based systems in dental and surgical applications. German university hospitals in Heidelberg and Munich are piloting these platforms for intraoperative sterilization protocols. The technology is decomposing price premiums previously commanded by electrochemical alternatives through simplified maintenance cycles and reduced platinum electrode degradation.
REACH regulation amendments restricting perfluorinated compound use in medical device components are forcing material substitutions in ozone generator seals and gaskets. Manufacturers serving the European Economic Area must validate fluoropolymer alternatives by 2025 or face market withdrawal. Spanish and Italian contract manufacturers are accelerating supply chain audits to identify contaminated stock before the enforcement window.
Direct procurement from equipment manufacturers is fragmenting traditional medical device distributor networks in the wellness center segment. German and Austrian physiotherapy chains are negotiating volume frameworks that bypass regional wholesalers, extracting 15-20% price concessions. This channel compression is most visible in Bavaria and Baden-Württemberg where multi-site clinic operators dominate regional demand aggregation.
Ozone Therapy Units Market Segmentation
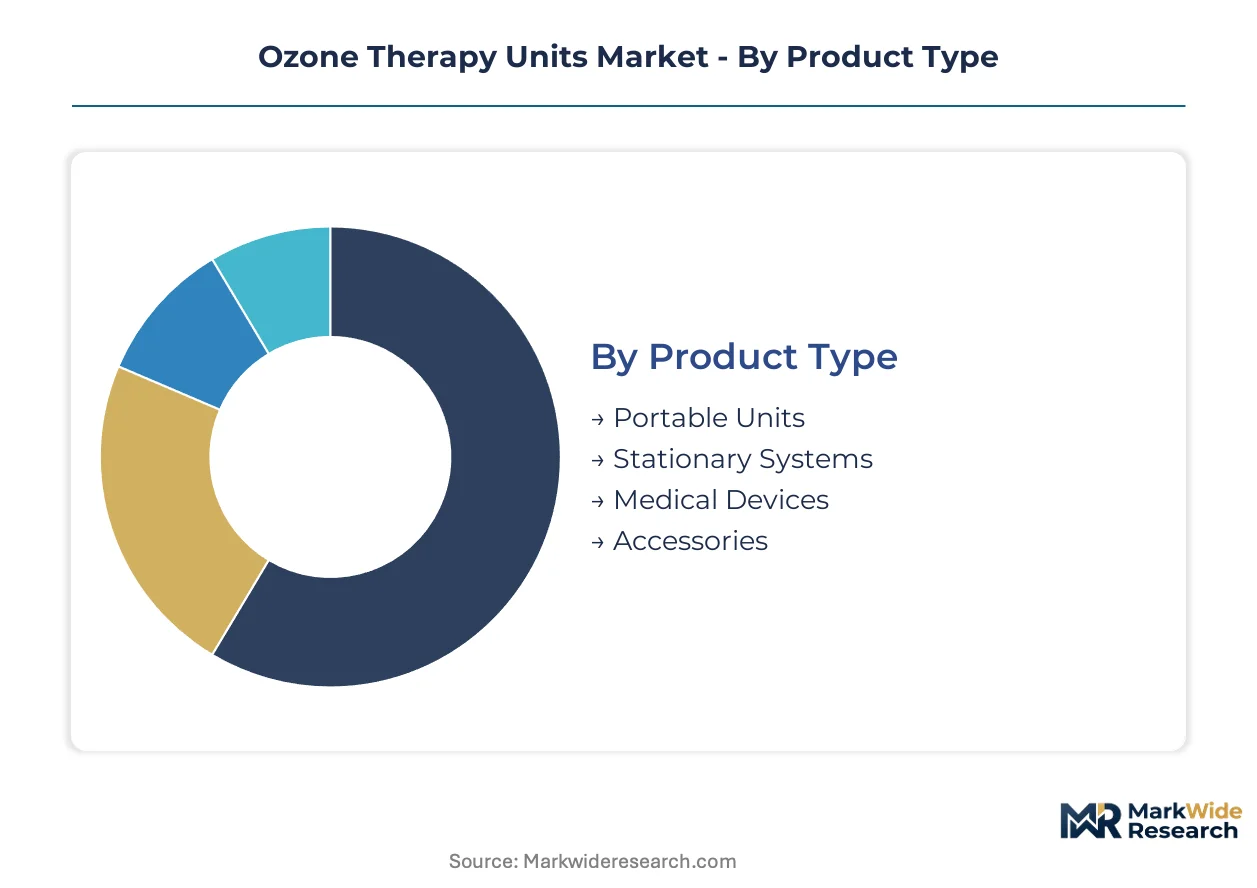
Segmentation in ozone therapy units reveals divergent margin architectures across mobility requirements, sterilization technologies, therapeutic modalities, and care settings. Each dimension carries distinct regulatory burdens and customer procurement behaviors that reshape vendor positioning.
Product Type:
Premium margin pools concentrate in systems requiring central gas infrastructure integration and multi-year service contracts.
- Portable Units:Compact ozone generators with battery or mains power options deliver 10-50 micrograms per milliliter concentration ranges for mobile clinical deployment. Wellness centers in Bavaria and physiotherapy chains across Austria prioritize these units for space-constrained treatment rooms where equipment mobility shapes workflow efficiency. Portable units hold installed capacity. Stationary Systems is rotating up the share rankings.
- Stationary Systems:Fixed-installation platforms integrate with hospital central gas supply networks and maintain IEC 60601-1 electrical safety compliance for surgical suite deployment. Heidelberg and Munich university hospitals specify these systems for intraoperative sterilization protocols requiring validated concentration stability over extended operational cycles. Stationary Systems holds installed capacity. Portable Units is rotating up the share rankings.
- Medical Devices:Class IIa and IIb therapeutic ozone generators under EU MDR face notified body certification requirements with 12-18 month review timelines.
- Accessories:Ozone delivery tubing, catheters, and electrode assemblies trigger ISO 10993 biocompatibility testing costs exceeding 250,000 euros per material formulation.
Stationary Systems holds installed capacity. Portable Units is rotating up the share rankings.
Technology:
Volume leadership sits with mature corona discharge platforms, while hybrid architectures capture the steepest expansion trajectory through dual-validation protocols.
- Ozone Generators:Corona discharge systems with closed-loop concentration feedback decompose legacy ultraviolet alternatives through simplified maintenance cycles and reduced platinum electrode degradation. German dental clinics specify these platforms for validated sterilization workflows requiring precise 20-80 micrograms per milliliter output control. Ozone Generators holds installed capacity. Hybrid Methods is rotating up the share rankings.
- Ultraviolet Systems:Mercury vapor lamp architectures generate ozone through 185nm wavelength photolysis of oxygen molecules. Italian regional health authorities in Lombardy maintain legacy procurement preferences for these systems in rural wound management programs where capital constraints limit equipment refresh cycles.
- Electrolytic Machines:Water electrolysis platforms produce ozone dissolved in aqueous solution for topical therapeutic administration. Spanish veterinary clinics adopt these systems for equine sports medicine applications requiring controlled oxidative stress induction.
- Hybrid Methods:Integrated ozone generation with ultraviolet-C sterilization enables dual-validation protocols that satisfy emerging infection control standards in dental and surgical settings. Heidelberg university hospital pilots validate these platforms for central sterile supply department workflows. Hybrid Methods holds installed capacity. Ozone Generators is rotating up the share rankings.
Hybrid Methods holds installed capacity. Ozone Generators is rotating up the share rankings.
Application:
Reimbursement density determines segment attractiveness, with musculoskeletal indications commanding statutory health insurance recognition.
- Chronic Pain Management:Ozone-oxygen mixture administration into paravertebral and intra-articular spaces targets disc herniation and osteoarthritis pathology. Germany's Federal Joint Committee has validated clinical efficacy for orthopedic outpatient settings, expanding statutory health insurance reimbursement codes. Chronic Pain Management holds installed capacity. Dental Treatments is rotating up the share rankings.
- Skin Disorders:Topical ozone application through ozonated oil formulations or bagging techniques addresses chronic wound healing and infectious dermatological conditions. Italian regional health authorities in Sicily pilot remote patient monitoring programs incorporating portable units for post-surgical wound management in rural geographies.
- Dental Treatments:Intraoral ozone delivery targets caries arrest, endodontic disinfection, and periodontal pocket sterilization. W&H Dentalwerk Burmoos GmbH dominates this segment through precision engineering heritage validated across European clinic networks. Dental Treatments holds installed capacity. Chronic Pain Management is rotating up the share rankings.
- Respiratory Conditions:Rectal insufflation and autohemotherapy protocols for systemic immune modulation face inconsistent randomized controlled trial outcomes that create reimbursement friction with German and analogous European health technology assessment bodies.
Chronic Pain Management holds installed capacity. Dental Treatments is rotating up the share rankings.
End User:
Procurement authority fragmentation across clinical, wellness, and domestic channels reshapes vendor go-to-market economics.
- Clinics:Specialized orthopedic and dental practices concentrate demand in Germany, Italy, and Spain within the European clinical segment. Direct procurement frameworks bypass traditional medical device distributors, extracting 15-20% price concessions through volume negotiations with multi-site operators in Bavaria and Baden-Württemberg. Clinics holds installed capacity. Homecare is rotating up the share rankings.
- Hospitals:Central sterile supply departments and surgical suites specify stationary systems with validated integration into medical gas pipeline infrastructure. J. Hänsler GmbH anchors hospital-grade sterilization protocols through high-concentration system validation. Hospitals holds installed capacity. Wellness Centers is rotating up the share rankings.
- Wellness Centers:Non-clinical therapeutic environments prioritize portable units for oxygenation therapy and localized immune modulation without diagnostic oversight requirements. Austrian physiotherapy chains aggregate regional demand to negotiate manufacturer-direct supply agreements.
- Homecare:Post-acute and chronic disease management applications in domestic settings face regulatory constraints under EU MDR personal use device classifications, limiting market access for therapeutic ozone generators outside supervised clinical environments.
Clinics holds installed capacity. Homecare is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum electrode supply chains and precision engineering capabilities concentrate ozone therapy unit manufacturing in Germany, Italy, and Spain, with regulatory harmonization under EU MDR accelerating cross-border equipment certification across the European clinical segment.
Germany
Federal Joint Committee reimbursement codes for orthopedic ozone therapy expand statutory health insurance coverage for musculoskeletal disorders. EU MDR notified body certification requirements compress vendor timelines ahead of enforcement cliffs. Heidelberg and Munich university hospitals pilot corona discharge systems with closed-loop concentration feedback for intraoperative sterilization protocols.
Italy
Regional health authorities in Lombardy and Sicily deploy portable units through remote patient monitoring programs for post-surgical wound management in rural geographies. REACH regulation amendments force fluoropolymer material substitutions in generator seals and gaskets by 2025. Direct procurement frameworks in northern Italy bypass traditional distributors, extracting price concessions from multi-site clinic operators.
Spain
Equine sports medicine clinics adopt veterinary-certified ozone therapy systems originally developed for human orthopedic applications. ISO 10993 biocompatibility testing costs exceed 250,000 euros per material formulation for ozone delivery components. Barcelona and Madrid contract manufacturers accelerate supply chain audits to identify contaminated stock before REACH enforcement windows.
United States
FDA 510(k) clearance pathways govern therapeutic ozone device oversight while state dental boards impose additional operational constraints on clinical use. Chronic pain prevalence drives outpatient clinic adoption for disc herniation and osteoarthritis treatment. California and Florida wellness centers prioritize portable units for space-constrained treatment environments.
Japan
PMDA medical device registration requirements create parallel certification burdens for manufacturers seeking Asian market access beyond European regulatory frameworks. METI industrial standards influence precision concentration control specifications for hospital-grade sterilization equipment. Tokyo and Osaka dental clinic networks validate hybrid ozone-ultraviolet sterilization protocols for infection control compliance.
Ozone Therapy Units Market Competitive Landscape
Concentration sits with precision engineering specialists and dental equipment heritage manufacturers that dominate European clinical procurement channels. The vendor base stratifies across three tiers: premium clinical suppliers with notified body certification capabilities, mid-tier wellness equipment makers serving physiotherapy chains, and modular platform architects extending across multiple therapeutic modalities. M&A activity targets regulatory affairs capabilities and ISO 13485 quality management infrastructure. Geographic expansion into Asian clinical markets accelerates as harmonization between European medical device standards and emerging national regulations progresses.
Among German precision engineering specialists, W&H Dentalwerk Burmoos GmbH and J. Hänsler GmbH exemplify divergent archetypes within the premium clinical tier. W&H Dentalwerk represents dental ozone therapy application dominance through engineering heritage validated across European clinic networks. J. Hänsler occupies a position in high-concentration system validation for hospital-grade sterilization protocols. Evozone GmbH anchors the modular platform architecture segment, with designs extending across multiple therapeutic modalities. These three entities collectively illustrate how regulatory compliance automation and concentration control precision bifurcate competitive positioning in the European clinical segment.
| Leading Market Players |
|---|
| Promolife |
| W&H Dentalwerk Burmoos GmbH |
| APOZA Enterprise Co., Ltd. |
| Aquolab |
| J. Hänsler GmbH |
| Evozone GmbH |
| Herrmann Apparatebau GmbH |
| MIO International Ozonytron GmbH |
| Sedecal |
| Others |
Value Network & Pricing Analysis
EU MDR notified body certification requirements gate both vendor qualification and price differentiation simultaneously, compressing mid-tier manufacturers into economy positioning while premium clinical suppliers capture margin through validated sterilization protocols. Pricing stratification reflects this regulatory moat, with compliant systems commanding substantial premiums over uncertified wellness equipment.
Pricing Analysis
EU MDR dictates the pricing tier structure across the European clinical segment, separating premium hospital-grade systems from standard clinic equipment and economy wellness center units. Price differentiation hinges on notified body certification status and ISO 13485 quality management infrastructure, with the former commanding substantial procurement premiums. Cost compression in the wellness tier is intensifying because physiotherapy chains in Bavaria and Austria negotiate direct manufacturer frameworks that bypass traditional distributor markups. Wellness centers exhibit highest price sensitivity due to capital constraints and absence of statutory reimbursement, while university hospitals in Heidelberg and Munich demonstrate lowest sensitivity given integration requirements and validated protocol demands.
Supply Chain Analysis
Container availability fluctuations on the Rotterdam-Genoa trade lane expose inbound logistics costs for ozone generator electrode assemblies sourced from South African platinum refiners. Manufacturing concentration centers on Germany, Italy, and Spain, with precision engineering capabilities anchored in Bavarian industrial clusters and contract manufacturing distributed across Barcelona and Madrid facilities. Raw material dependencies include platinum group metals for corona discharge electrodes, fluoropolymer compounds for generator seals facing REACH restriction, and medical-grade aluminum for housing assemblies. Single-source vulnerability runs through South African and Russian platinum refining concentration. Distribution runs through direct procurement frameworks in wellness segments and GPO-mediated hospital contracts in clinical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR enforcement cliffs are disrupting established competitive positioning, creating acquisition opportunities for regulatory-capable platforms while compressing timelines for certification-deficient vendors.
For Market Incumbents: Shield market position through accelerated notified body certification investment ahead of queue congestion, and anchor backward integration into platinum electrode supply through long-term offtake agreements with South African refiners. Hydrogen peroxide plasma sterilizer substitution in hospital central sterile supply departments threatens ozone system revenue pools, requiring defensive R&D pivot toward hybrid ultraviolet-ozone architectures.
For New Entrants and Emerging Players: Lead with veterinary-certified system crossover into equine sports medicine clinics in Spain, where regulatory barriers sit lower than human clinical applications and price sensitivity permits margin capture. Target homecare remote patient monitoring pilots in rural Lombardy and Sicily, where Italian regional health authorities actively seek portable unit suppliers for post-surgical wound management programs. Deploy direct-to-clinic digital sales channels to bypass entrenched distributor relationships in German physiotherapy chains.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across notified body certification pathways and ISO 10993 biocompatibility testing requirements, favoring scaled platforms with existing regulatory infrastructure over greenfield development. Five-to-ten year viability favors acquisition of mid-tier manufacturers possessing CE-MDR technical documentation capabilities but lacking capital for independent certification completion. Monitor notified body queue length as primary inflection signal—compression below twelve months would enable accelerated product launch timelines and valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Certification Pathway | Notified body validation unlocks hospital procurement eligibility across German and Italian clinical networks. |
| Backward Integration into Electrode Supply | Captive platinum group metal sourcing insulates production costs from South African supply shocks. |
| Hybrid Sterilization Platform Development | Dual-validation ozone-ultraviolet protocols satisfy emerging infection control standards in Heidelberg university hospital pilots. |
| Direct-to-Clinic Channel Expansion | Bypassing Bavarian distributors extracts 15-20% price concessions from multi-site physiotherapy operators. |
| Veterinary Market Crossover | Equine sports medicine adoption in Spain opens lower-regulation pathway for human orthopedic system validation. |
Research Methodology
Desk research of EU MDR technical documentation databases, ISO 13485 certification registries, and German Federal Joint Committee reimbursement filings preceded structured interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs leads at notified bodies. Primary fieldwork with ozone therapy unit manufacturers in Bavaria and Baden-Württemberg combined with secondary validation through customs trade data and hospital procurement databases. Bottom-up installed base estimates triangulated against top-down market sizing derived from statutory health insurance reimbursement code utilization.
Variance decomposition across product type, technology architecture, therapeutic application, and end-user channel shaped the analytical framework over the projection horizon. CAGRs were derived through logistic adoption curve modeling calibrated to reimbursement expansion timelines and regulatory enforcement windows. Industry-specific forecast inputs included platinum electrode degradation rates affecting replacement cycle economics and REACH fluoropolymer substitution deadlines impacting material validation costs.
The analysis sits within stated boundaries; outcomes outside EU MDR harmonization progress or platinum supply chain stability would require recalibration. Forecasts reflect documented assumptions regarding reimbursement code expansion velocity and notified body capacity expansion. Geopolitical disruption to South African refining operations or accelerated hydrogen peroxide plasma sterilizer adoption in German hospitals would compress ozone therapy unit demand projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Medicine
Flower Essences Market
Alternative Medicine
Electrotherapy Market
Alternative Medicine
Aromatherapy Market
Alternative Medicine
US Aromatherapy Market
Alternative Medicine
Botanicals & Acupuncture Market
Alternative Medicine
Bio Magnetic Ear Stickers Market
Alternative Medicine
Orthomolecular Medicine Market
Alternative Medicine
Biopuncture Treatment Market
Alternative Medicine
Cold Laser Therapy Market
Alternative Medicine
Homeopathic Medicine Market
Alternative Medicine
Traditional Chinese Medicine Market
Alternative Medicine
Vacuum Cupping Market
Alternative Medicine
Allergy Immunotherapy Market
Alternative Medicine
Disposable Acupuncture Needle Market
Alternative Medicine
Homeopathy Products Market
Alternative Medicine
Natural Cold, Cough, and Sore Throat Remedies Market