
 Pharma 4.0 Market | 2026-2036
Pharma 4.0 Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma 4.0 Market Analytics
The scarcity of professionals fluent in both GMP compliance and industrial IoT architecture is rotating Pharma 4.0 project timelines toward hybrid workforce models. Siemens Healthcare GmbH leverages its embedded position in regulated manufacturing environments to sustain long-term service contracts. Honeywell International Inc. anchors its offering through integrated batch execution systems that dominate validation-heavy facilities. IBM Corporation competes via quantum-safe encryption layers tailored to pharmaceutical data sovereignty requirements.
Pharma 4.0 denotes the integration of cyber-physical production systems, digital twin architectures, and real-time process analytical technology within regulated drug manufacturing environments, where ISA-95/ISA-88 standards govern equipment hierarchy and data exchange protocols. Its primary purpose is to enable continuous manufacturing, real-time release testing, and adaptive supply chain responses while maintaining batch-level traceability for regulatory submission. Artificial Intelligence and Internet of Things solutions occupy the fastest-expanding margin pools as sponsors shift from pilot programs to validated production deployments. Predictive Analytics within the Solution dimension leads contract value per engagement, though Data Management retains the broadest install base across mid-tier biopharmaceutical companies.
FDA's guidance on computerized systems in manufacturing, EMA's reflection paper on artificial intelligence in drug lifecycle, and ISO 13485 quality management standards collectively shape vendor qualification pathways and customer procurement criteria. The EU AI Act introduces additional conformity obligations for algorithm-driven quality control decisions, forcing platform providers to rearchitect audit trail functionalities. Stakeholders must weigh interoperability investments against the risk of stranded assets as regulatory frameworks diverge on cloud residency and model explainability thresholds.
Market Dynamics
Pharma 4.0 deployment momentum hinges on the collision between FDA and EMA data integrity mandates and the operational reality of brownfield manufacturing infrastructure. Continuous process verification requirements are forcing sponsors to choose between full-scale retrofitting and greenfield facility construction, with capital allocation decisions now predicated on regulatory audit readiness rather than pure throughput economics.
Growth Catalysts
- Continuous Manufacturing Mandates:FDA's guidance on real-time release testing incentivizes sponsors to replace batch processing with flow chemistry platforms. This regulatory pressure accelerates validation protocols for integrated process analytical technology.
- EMA Reflection Paper on AI:The European regulator's formal stance on machine learning in quality control creates procurement certainty for algorithm-driven inspection systems. Sponsors gain cover to advance from pilot to production deployment.
- Cloud-Based Batch Records:Germany's early adoption of validated electronic systems demonstrates compliance pathways for cross-border data residency. This precedent reduces perceived regulatory risk for multinational sponsors.
Market Restraints
- Legacy Equipment Interoperability:Brownfield facilities face capital-intensive retrofitting to achieve ISA-95/ISA-88 standard compliance. The sunk cost of existing automation infrastructure creates path dependency.
- Specialized Talent Scarcity:Professionals possessing dual fluency in GMP compliance and industrial IoT architecture command premium compensation. This bottleneck extends project timelines and inflates implementation costs.
- Validation Protocol Burden:FDA's computerized systems validation requirements impose documentation overhead that slows deployment velocity. Smaller sponsors lack resources to maintain parallel paper and electronic systems.
Strategic Opportunities
- Modular Continuous Manufacturing:Portable skid-mounted production units enable sponsors to reconfigure capacity across therapeutic modalities. This flexibility addresses demand volatility for orphan and personalized medicines.
- Quantum-Safe Encryption:Post-quantum cryptographic standards create upgrade cycles for data sovereignty infrastructure. Early movers capture long-term service contracts from data-intensive biologics manufacturers.
- Digital Twin Convergence:Integration of process simulation with supply chain modeling enables predictive deviation management. This capability supports adaptive release decisions under tightened EMA inspection protocols.
Industry Challenges
- Hybrid Workforce Integration:Blending traditional process engineers with data science specialists creates organizational friction. Training programs struggle to achieve cross-functional competency at scale.
- Audit Trail Architecture:EU AI Act explainability requirements force reengineering of black-box algorithmic decisions. Platform providers must reconstruct decision pathways without degrading model performance.
- Supplier Qualification Bottlenecks:Cloud infrastructure vendors lack pharmaceutical-specific validation documentation. Sponsors absorb extended vendor assessment timelines that compress implementation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma 4.0 Market |
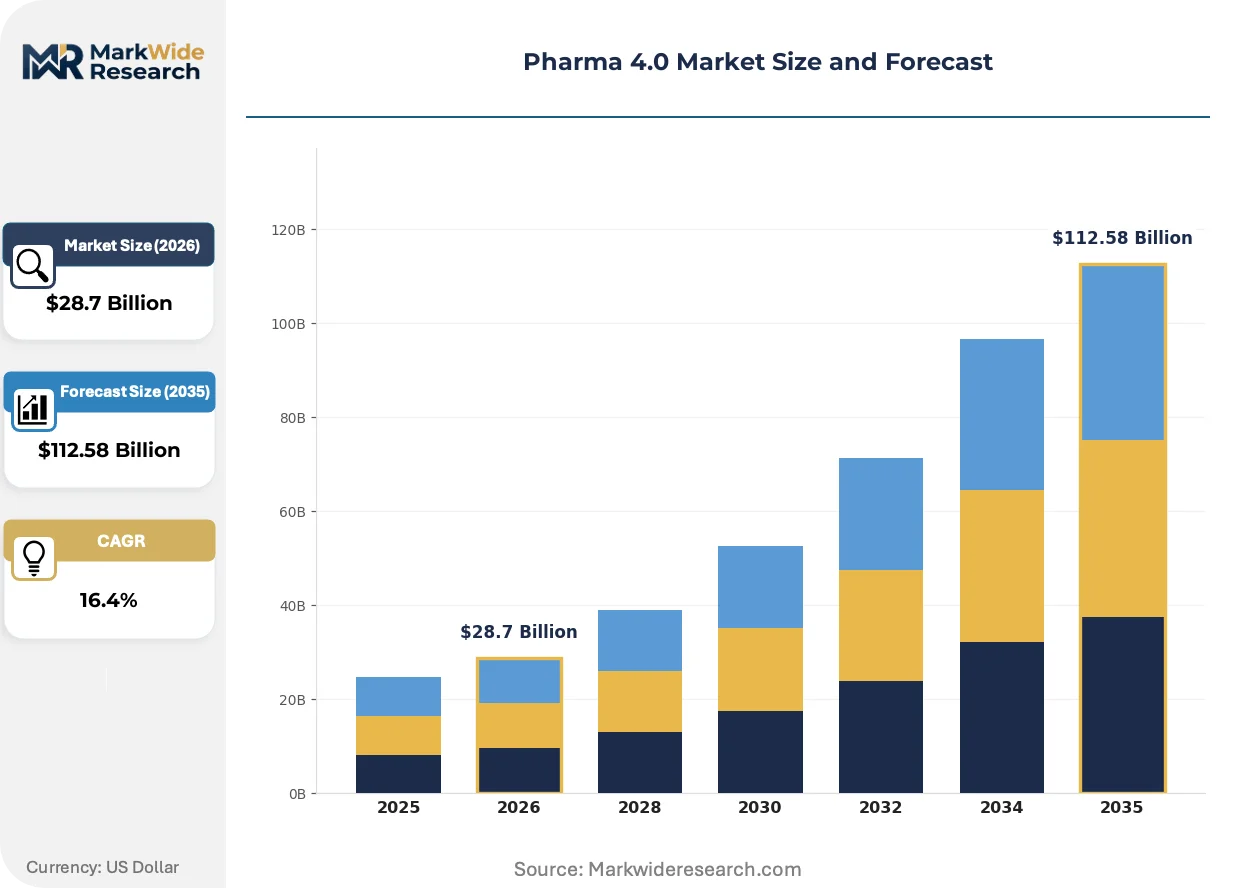
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $112.58 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Artificial Intelligence, Machine Learning, Internet of Things, Big Data Application: Drug Development, Manufacturing Process, Quality Control, Supply Chain Management End User: Biopharmaceutical Companies, Contract Research Organizations, Regulatory Authorities, Research Institutions Solution: Digital Twin, Predictive Analytics, Data Management, Automation Solutions |
| Companies Covered | Cisco Systems, Inc., ABB, Microsoft Corporation, Amazon Web Services, Inc., Siemens Healthcare GmbH, Oracle Corporation, GE Healthcare, Honeywell International Inc., IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma 4.0 Market Evolving Landscape
Digital twin architectures are migrating from asset monitoring to full process simulation, compressing the gap between virtual commissioning and regulatory submission. This shift redefines competitive advantage around model fidelity rather than hardware scale.
Process analytical technology is bifurcating between at-line spectroscopic sensors for small-molecule synthesis and in-line bioreactor probes for cell culture monitoring. Large-molecule sponsors in the United States are accelerating deployment of Raman-based glucose control systems. This capability compression enables real-time titer prediction that reduces offline testing burden and accelerates batch release decisions.
REACH and the EU AI Act collectively impose algorithmic transparency obligations on quality control automation. Vendors must now document training data provenance and decision boundary logic for inspection system neural networks. Biologics manufacturers operating across European member states are prioritizing explainable machine learning platforms to preempt regulatory challenge during GMP inspections.
Biopharmaceutical procurement is fragmenting between centralized enterprise platform contracts and site-specific best-of-breed solutions. Mid-tier sponsors in Japan favor modular subscriptions that preserve operational autonomy. This pattern forces vendors to support hybrid deployment architectures rather than monolithic system replacements.
Pharma 4.0 Market Segmentation
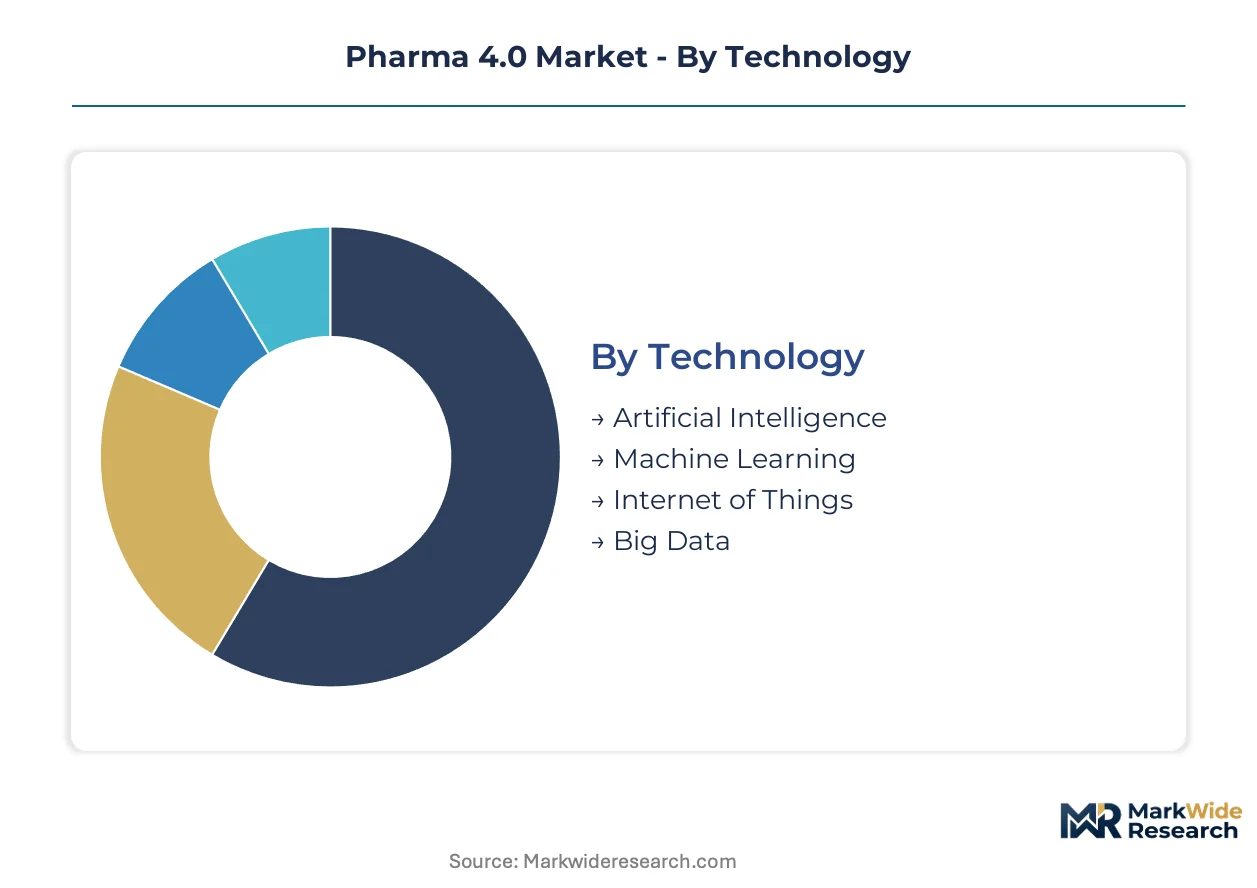
Pharma 4.0 segmentation reveals how technology maturity, regulatory validation requirements, and capital intensity create divergent adoption curves across customer types. Mapping these dimensions exposes where substitution pressures from adjacent industrial software categories threaten incumbent positioning.
Technology:
Artificial Intelligence faces acute substitution pressure from general-purpose industrial AI platforms that lack pharmaceutical-specific validation documentation but undercut on licensing costs.
- Artificial Intelligence:Neural networks for process optimization and quality prediction require FDA-validated training data provenance. Biopharmaceutical companies in Germany absorb extended vendor qualification timelines to deploy algorithmic release decisions under EMA inspection protocols.
- Machine Learning:Supervised learning models for deviation classification and predictive maintenance demand continuous retraining on batch-specific data. Contract manufacturing organizations prioritize interpretable algorithms that satisfy EU AI Act explainability requirements for GMP audits.
- Internet of Things:Sensor networks for environmental monitoring and equipment performance tracking.
- Big Data:Distributed architectures for batch record aggregation and cross-facility analytics.
Internet of Things retains volume leadership across validated manufacturing environments; Artificial Intelligence holds the steepest expansion curve as sponsors shift from pilot to production deployment.
Application:
Cost tier stratification separates validated production systems from exploratory R&D tools, with quality control commanding premium pricing due to direct regulatory submission exposure.
- Quality Control:Automated visual inspection and spectroscopic analysis systems integrate process analytical technology for real-time release. United States biologics manufacturers deploy Raman-based glucose control to compress offline testing burden and accelerate batch decisions.
- Manufacturing Process:Continuous processing platforms and digital batch execution systems anchor capital allocation. Brownfield facilities in Japan face retrofit costs that tilt decisions toward greenfield construction for ISA-95 compliance.
- Drug Development:Computational modeling and simulation tools for molecule optimization.
- Supply Chain Management:Track-and-trace serialization and cold chain monitoring platforms.
Manufacturing Process captures the largest contract values per engagement; Quality Control is climbing the fastest as real-time release testing mandates tighten.
End User:
Customer type determines procurement autonomy, with centralized biopharmaceutical enterprises favoring platform consolidation while distributed research institutions demand modular subscriptions.
- Biopharmaceutical Companies:Integrated sponsors with internal manufacturing networks drive enterprise platform contracts. Siemens Healthcare GmbH sustains long-term service agreements through embedded positions in regulated environments.
- Contract Research Organizations:Outsourced development and manufacturing providers prioritize flexible deployment models. Mid-tier Japanese sponsors favor modular subscriptions that preserve site-level operational autonomy against monolithic replacements.
- Regulatory Authorities:FDA and EMA technology assessment programs for algorithmic inspection tools.
- Research Institutions:Academic centers piloting digital twin architectures for process simulation.
Biopharmaceutical Companies dominate absolute spending; Contract Research Organizations are gaining share fastest as sponsor outsourcing accelerates.
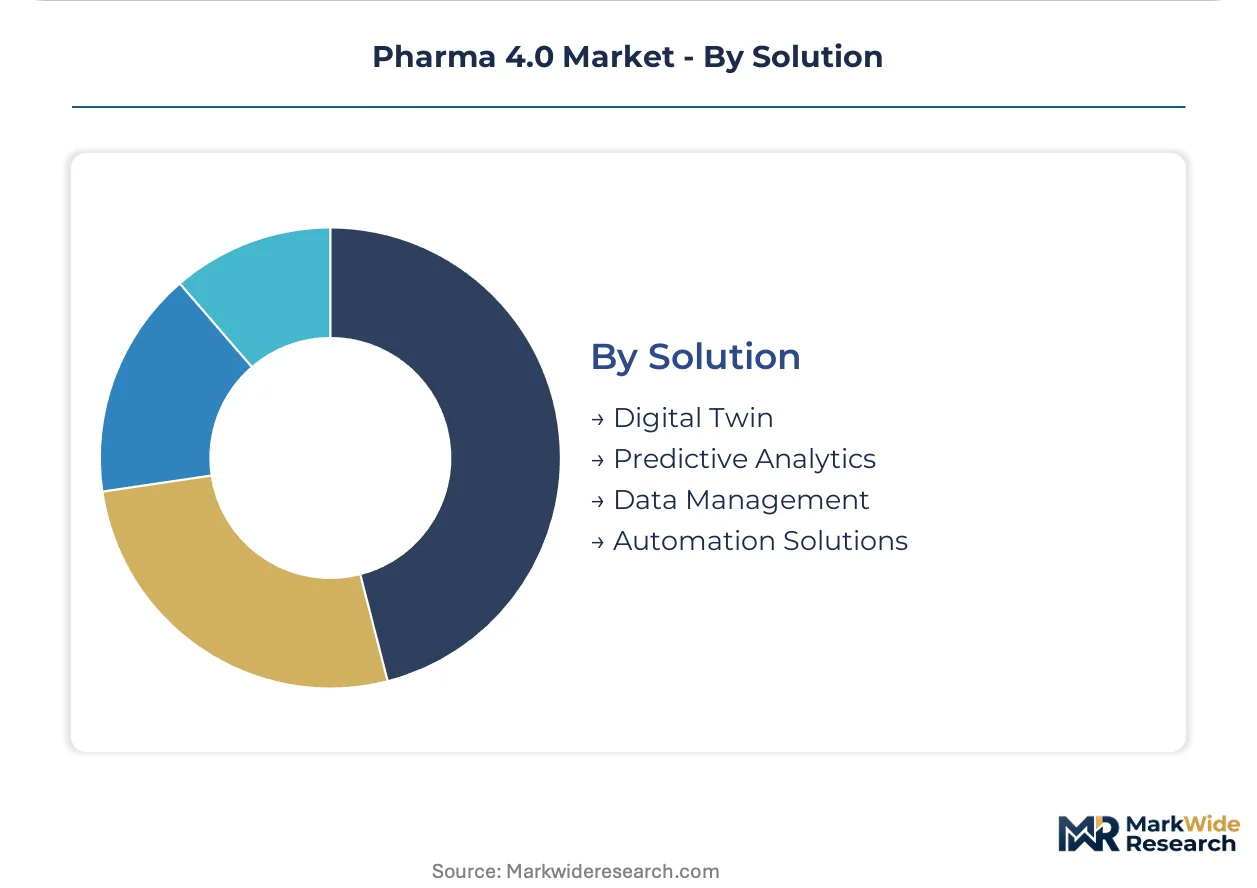
Solution:
Margin concentration tracks data sovereignty requirements, with predictive analytics commanding premium pricing for algorithmic intellectual property while data management spreads across commoditized infrastructure.
- Predictive Analytics:Statistical and machine learning models for deviation prediction and yield optimization. Honeywell International Inc. anchors market position through integrated batch execution systems that dominate validation-heavy facilities.
- Data Management:Electronic batch records, laboratory information management systems, and cloud data lakes. IBM Corporation competes via quantum-safe encryption layers tailored to pharmaceutical data residency requirements.
- Digital Twin:Virtual process simulation and asset monitoring for commissioning acceleration.
- Automation Solutions:Distributed control systems and manufacturing execution system integration.
Data Management retains the broadest install base across mid-tier sponsors; Predictive Analytics holds the steepest expansion trajectory as AI validation protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys Pharma 4.0 infrastructure primarily for continuous process verification in biologics manufacturing, while the United States concentrates investment on AI-driven quality control and real-time release testing systems. Japan emphasizes modular brownfield retrofitting to preserve legacy asset value. This consumption-mix differential shapes vendor qualification pathways and capital allocation priorities across the three dominant markets.
Germany
Bavarian biologics manufacturers drive demand for validated cloud-based batch records and digital twin architectures. The country's national pharmaceutical regulator has issued formal guidance on electronic systems validation that reduces perceived compliance risk for cross-border data residency. The Rhine-Main cluster around Frankfurt anchors Siemens Healthcare GmbH's embedded service infrastructure for continuous manufacturing platforms.
United States
FDA mandates on real-time release testing and process analytical technology accelerate sponsor migration from batch to continuous processing. The agency's guidance on computerized systems in manufacturing imposes documentation overhead that favors vendors with pre-validated platform offerings. Greater Boston's biologics corridor concentrates deployment of Raman-based glucose control systems for in-line bioreactor monitoring.
Japan
PMDA inspection protocols emphasize adaptive release decisions under tightened deviation management requirements. METI programs for smart factory certification create procurement pathways for modular continuous manufacturing skids. The Kansai region around Osaka faces acute brownfield retrofit challenges as sponsors balance ISA-95 compliance against sunk automation costs.
Switzerland
Swissmedic's alignment with EMA reflection papers on artificial intelligence creates regulatory cover for algorithmic quality control deployment. The Basel biopharma cluster concentrates investment in quantum-safe encryption for data sovereignty infrastructure. Vendors compete through long-term service contracts anchored in pre-existing validation relationships.
India
CDSCO's tightening data integrity requirements for export-oriented facilities drive adoption of electronic batch records and laboratory information management systems. The Maharashtra-Gujarat pharmaceutical corridor concentrates contract manufacturing organization demand for modular subscription models that preserve site-level operational autonomy. Mid-tier sponsors prioritize flexible deployment architectures over monolithic system replacements.
Pharma 4.0 Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with industrial automation conglomerates and cloud infrastructure providers occupying distinct competitive positions. The upper tier commands premium pricing through pre-validated platform architectures and embedded regulatory relationships. Three archetypes dominate: diversified industrial technology groups with healthcare verticals, hyperscale cloud providers with compliance-layer investments, and specialized pharmaceutical software vendors with domain-specific validation expertise. Competitive moves concentrate on strategic partnerships for interoperability certification and portfolio diversification into adjacent process analytical technology segments.
Within the industrial technology tier, Siemens Healthcare GmbH and Honeywell International Inc. exemplify platform consolidation strategies that leverage embedded positions in regulated manufacturing environments. IBM Corporation occupies a distinct position around data sovereignty infrastructure, representing the cybersecurity-specialist archetype. These three companies anchor the competitive landscape through divergent entry points: automation hardware, integrated batch execution systems, and quantum-safe encryption layers respectively.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| ABB |
| Microsoft Corporation |
| Amazon Web Services, Inc. |
| Siemens Healthcare GmbH |
| Oracle Corporation |
| GE Healthcare |
| Honeywell International Inc. |
| IBM Corporation |
| Others |
Value Network & Pricing Analysis
Long-term service contracts with embedded validation support anchor pricing visibility for biopharmaceutical sponsors seeking ISA-95 compliant platform deployments. Siemens Healthcare GmbH and Honeywell International Inc. leverage pre-validated architectures to lock in multi-year engagements across Germany and the United States, compressing procurement uncertainty for brownfield retrofit projects.
Pricing Analysis
Project-based pricing dominates initial platform deployment, with subscription tiers for ongoing validation support and digital twin maintenance creating recurring revenue anchors. Price differentiation hinges on FDA pre-validation documentation depth and quantum-safe encryption certification tier. Cost compression in mid-tier data management solutions intensifies as general-purpose cloud providers enter with undercut licensing. Contract manufacturing organizations exhibit highest price sensitivity due to margin pressure from sponsor consolidation; integrated biopharmaceutical enterprises absorb premium pricing for embedded regulatory relationships.
Supply Chain Analysis
Strategic stockpiling of ISA-88 compliant automation hardware characterizes sponsor procurement as lead times for validated components extend. Component concentration centers on Germany for distributed control systems, the United States for process analytical technology sensors, and Japan for precision bioreactor instrumentation. Supply chains draw from specialized semiconductor foundries for industrial IoT chipsets, spectroscopic sensor arrays, and quantum-resistant cryptographic modules. Single-source vulnerability pervades FDA-validated training data repositories. Distribution runs through certified system integrators with embedded regulatory affairs capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharma 4.0 infrastructure monetization increasingly depends on validation-as-a-service layers expanding faster than hardware sales, as sponsors prioritize audit-ready documentation over capital equipment ownership.
For Market Incumbents: Fortify embedded positions through backward integration into cloud data sovereignty infrastructure and captive development of quantum-safe encryption modules. General-purpose industrial AI platforms threaten substitution with undercut licensing; defensive certification investment in EU AI Act explainability tooling preserves premium positioning against commoditization. For New Entrants and Emerging Players: Differentiate on modular continuous manufacturing skids targeting Japan's brownfield retrofit urgency and India's export-oriented contract manufacturing expansion. White-space concentration sits with mid-tier biopharmaceutical companies lacking resources for monolithic platform replacement. Go-to-market leverage rests on site-level operational autonomy preservation against enterprise consolidation mandates. For Investors and Strategic Acquirers: Specialized pharmaceutical software vendors with domain-specific validation expertise and pre-existing FDA inspection relationships represent priority acquisition archetypes. Long-term viability frames around service-attach ratio expansion and recurring validation revenue predictability. Watch for EMA algorithmic transparency enforcement tightening as inflection signal for explainable AI platform valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Validation-as-a-Service Expansion | Recurring revenue from FDA-compliant documentation layers outpaces hardware margins across German and US deployments. |
| Quantum-Safe Encryption Integration | Post-quantum cryptographic standards force upgrade cycles for data sovereignty infrastructure in Swiss and US biologics manufacturing. |
| Modular Continuous Manufacturing Skids | Portable production units address demand volatility for orphan medicines across Japanese brownfield facilities. |
| EU AI Act Explainability Tooling | Algorithmic transparency obligations from Brussels reengineer black-box quality control decisions without model degradation. |
| Cloud Data Sovereignty Partnerships | Cross-border residency compliance reduces perceived regulatory risk for multinational sponsors in Germany's Rhine-Main cluster. |
Research Methodology
The analysis maps cyber-physical production systems, digital twin architectures, and process analytical technology deployments, each validated through primary interviews with continuous manufacturing engineers, regulatory affairs leads at FDA and EMA, GMP compliance officers, and pharmaceutical procurement directors. Secondary sources include FDA guidance documents on computerized systems, EMA reflection papers on artificial intelligence, ISO 13485 quality management standards, and ISA-95/ISA-88 protocol documentation. Bottom-up facility deployment tracking triangulates against top-down vendor revenue segmentation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. Segmentation dimensions encompass technology type, application function, end-user category, and solution architecture, with additional modeling of regulatory cluster differentiation between FDA, EMA, and PMDA jurisdictions. CAGRs derive from facility investment pipeline analysis and validated platform adoption curves. Forecast inputs incorporate continuous process verification mandate timing and cloud-based batch record penetration rates.
Material uncertainties — regulatory divergence on algorithmic explainability thresholds and cloud residency requirements — sit outside the modeled envelope. Forecasts reflect assumptions regarding EMA inspection protocol stability and FDA real-time release testing guidance continuity. Revision becomes warranted when EU AI Act enforcement intensity or PMDA deviation management tightening crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Germany Opioids Market
Pharmaceuticals
Decongestants Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Oxaliplatin Market
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Dyslipidemia Drugs Market
Pharmaceuticals
Pharmaceuticals Serialization Market
Pharmaceuticals
Stye Drug Market
Pharmaceuticals
Global Alteplase Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
Cannabinoid Drugs Market
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Global Dementia Drugs Market