
 Surgical Fluid Disposal Market | 2026-2036
Surgical Fluid Disposal Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Fluid Disposal Market Analytics
Hospital-grade closed-system specifications is collapsing the gap between premium fluid disposal units and standard waste management across operating theaters. Stryker Corporation leverages its endoscopy and surgical technologies footprint to sustain integrated fluid capture-to-disposal workflows. B. Braun Melsungen AG anchors European market access through its sterilization and hospital supply infrastructure. Cardinal Health, Inc. competes on distribution density and same-day replenishment capabilities for high-volume surgical centers.
Surgical fluid disposal encompasses the collection, containment, treatment, and terminal disposal of blood, irrigation solutions, and bodily fluids generated during operative procedures, typically requiring leak-proof, puncture-resistant containment rated for biohazard level 2 or higher materials. The primary purpose centers on preventing nosocomial infection transmission, protecting healthcare workers from sharps and splash exposure, and ensuring environmental compliance for downstream waste processing. Disposal units and management systems command the strongest margin pools as hospitals consolidate from commodity waste bags toward automated, trackable fluid handling platforms. Autoclaving and chemical treatment technologies lead installed base volumes, though microbial treatment represents the fastest-growing segment as facilities seek lower-energy alternatives to incineration.
The US FDA governs fluid management device safety and performance standards under 510(k) pathways, while the EPA enforces Resource Conservation and Recovery Act provisions that dictate cradle-to-grave tracking for hazardous medical waste streams. The EU MDR and REACH frameworks impose stricter material composition and disposal documentation requirements on devices sold across member states. Stakeholders must monitor evolving state-level biomedical waste rules in the US and EU Green Deal circular economy mandates that could mandate reusable containment formats over single-use disposables.
Market Dynamics
Closed-loop fluid management systems are consolidating hospital purchasing decisions around integrated capture-to-disposal platforms, collapsing standalone waste bag procurement into capital equipment cycles governed by infection control committees rather than supply chain managers.
Growth Catalysts
- EU MDR documentation mandates:Stricter material traceability and disposal chain records are accelerating replacement of legacy containment with trackable, RFID-enabled systems across German and French surgical centers.
- Ambulatory surgical center expansion:Freestanding outpatient facilities in the United States are installing compact automated fluid disposal units to meet OSHA bloodborne pathogen standards without centralized sterilization infrastructure.
- Microbial treatment adoption:Low-energy biological neutralization processes are gaining preference over autoclaving in facilities seeking carbon footprint reduction aligned with EU Green Deal circular economy targets.
Market Restraints
- Specialized polymer supply concentration:Medical-grade puncture-resistant thermoplastics rely on concentrated petrochemical feedstock suppliers in the US Gulf Coast, exposing margins to input volatility.
- 510(k) pathway friction:FDA clearance timelines for novel fluid containment technologies extend 12-18 months, delaying commercialization of next-generation barrier materials.
- Reusable containment substitution:EU Green Deal mandates favoring washable, sterilizable fluid collection vessels threaten single-use disposable volume in member state hospitals.
Strategic Opportunities
- India surgical infrastructure buildout:Government hospital modernization programs under Ayushman Bharat create first-mover advantage for integrated fluid management system vendors establishing service networks.
- Robotic surgery integration:Convergence of automated fluid handling with da Vinci and comparable surgical robotic platforms enables real-time suction-quantification-disposal workflows in high-volume oncology centers.
- Japan PMDA fast-track pathway:Priority review designation for infection-prevention devices accelerates market entry for novel containment technologies in an aging surgical demographic.
Industry Challenges
- Biohazard certification complexity:ISO 13485 quality management system implementation for fluid disposal devices requires 18-24 month validation cycles that strain mid-tier manufacturer cash reserves.
- Legacy EMR integration:Automated fluid quantification systems face interoperability barriers with Cerner and Epic installations, forcing costly custom API development for volume tracking compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Fluid Disposal Market |
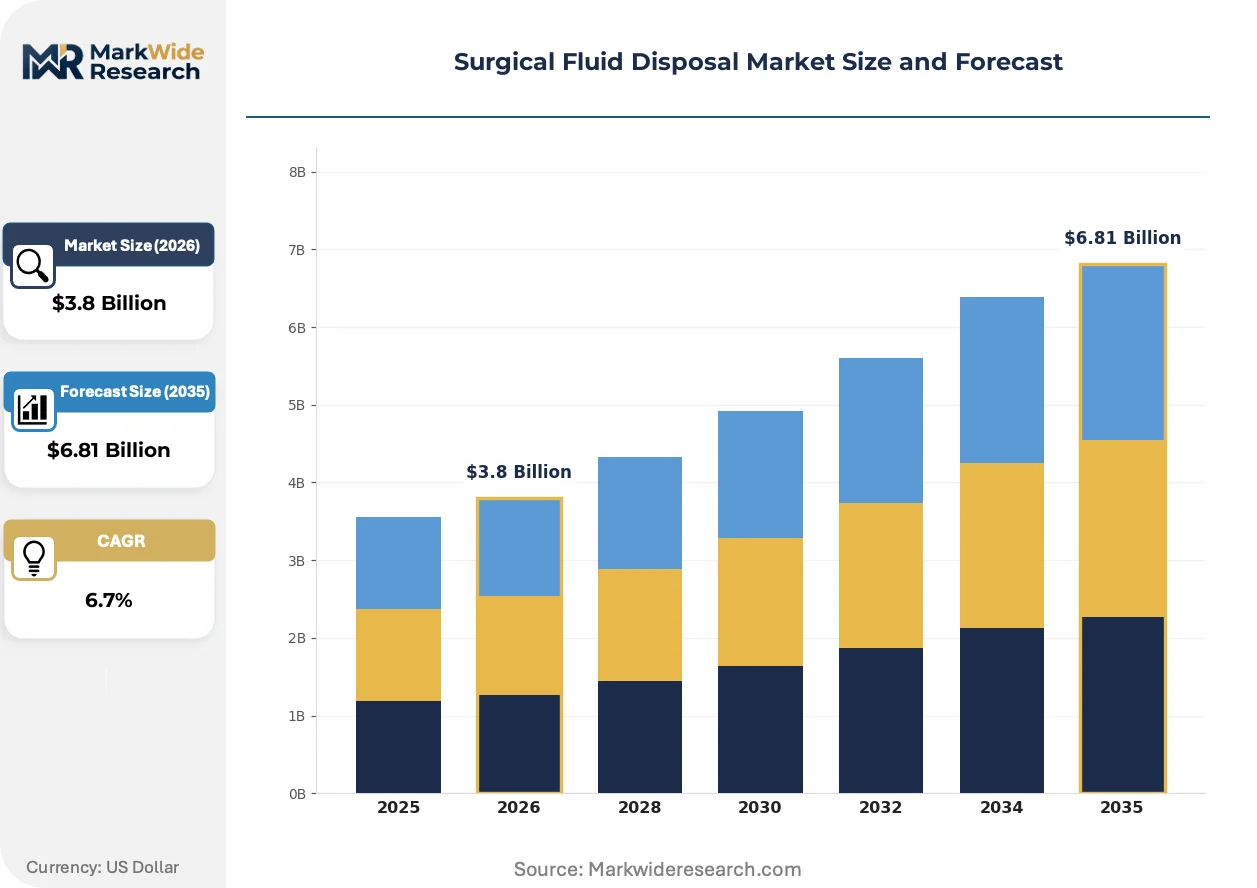
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sharps Containers, Waste Bags, Disposal Units, Management Systems End User: Hospitals, Ambulatory Surgical Centers, Clinics, Long-Term Care Facilities Technology: Incineration, Autoclaving, Chemical Treatment, Microbial Treatment Packaging Type: Single-Use Packs, Bulk Containers, Dispensers, Specialty Bags |
| Companies Covered | B. Braun Melsungen AG, Skyline Medical, Inc., Baxter International, Inc., Cardinal Health, Inc., Hill-Rom Holdings, Inc., Bard, A Becton Dickinson Company, Medtronic Plc, Olympus Corporation, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Fluid Disposal Market Evolving Landscape
Digital tracking and biological neutralization are converging to transform fluid disposal from a passive waste handling function into an active data-generating, compliance-automating surgical workflow component.
RFID-tagged containment canisters are supplanting color-coded plastic bags in tertiary hospital operating theaters. Surgical services departments in the United States and Germany are mandating scan-at-disposal documentation for Joint Commission and EU MDR audit trails. This technology is compressing liability exposure for hospitals while creating recurring revenue streams for device-software platform vendors.
REACH substance restriction updates are phasing out certain phthalate plasticizers in medical-grade polymers used for fluid collection reservoirs. European manufacturers are reformulating barrier layer compositions to maintain puncture resistance under revised ECHA authorization lists. German sterilization equipment suppliers are accelerating validation of alternative elastomer seals to preempt supply disruption.
Consolidated purchasing through integrated delivery networks is displacing individual hospital procurement autonomy in the United States. IDN supply chain directors are mandating standardized fluid disposal platforms across 15-30 facility footprints to leverage volume pricing and simplify clinical staff training. This concentration is most visible in Texas and Florida health systems where ambulatory expansion has outpaced infrastructure standardization.
Surgical Fluid Disposal Market Segmentation
Surgical fluid disposal segmentation reveals divergent procurement patterns across acute care versus outpatient settings. Product and technology choices cluster around infection control mandates, waste volume profiles, and capital availability rather than uniform institutional preference.
Product Type:
Domestic manufacturing dominates sharps containers and waste bags, while disposal units and integrated management systems flow through specialized medical device distributors with cross-border service networks.
- Sharps Containers:Puncture-resistant polypropylene vessels engineered for needle and scalpel containment. German hospital systems mandate color-coded, lockable designs under BfArM guidance. Demand concentrates in high-volume orthopedic and cardiac surgery suites where instrument turnover accelerates fill rates.
- Waste Bags:Biohazard-rated polyethylene film with tear-resistant seams and heat-sealed closures. Ambulatory surgical centers in Texas and Florida specify compact, cart-mounted bag systems to accommodate limited sterile processing space. OSHA bloodborne pathogen compliance drives specification rigidity.
- Disposal Units:Automated containment with integrated suction and quantification sensors.
- Management Systems:Closed-loop platforms combining capture, treatment tracking, and disposal documentation.
Sharps containers hold the largest share; momentum sits with management systems as IDN procurement consolidates around integrated platforms.
End User:
Cost tier stratification separates capital-intensive hospitals from budget-constrained clinics, with ambulatory surgical centers occupying a mid-tier position demanding compact automation without enterprise-scale infrastructure.
- Hospitals:Tertiary medical centers with dedicated sterile processing departments and 24-hour waste handling operations. Academic medical centers in Boston and Cleveland specify RFID-tracked fluid disposal to satisfy Joint Commission audit requirements. Capital equipment cycles govern purchasing decisions.
- Ambulatory Surgical Centers:Freestanding outpatient facilities performing same-day procedures. California and Arizona ASCs favor wall-mounted, space-efficient disposal units with automated treatment cycles. Medicare reimbursement pressures compress equipment payback thresholds.
- Clinics:Primary and specialty care settings with intermittent procedural volume.
- Long-Term Care Facilities:Skilled nursing and rehabilitation centers with limited surgical intervention.
Hospitals command the dominant procurement volume; ambulatory surgical centers are expanding most quickly as outpatient migration accelerates.
Technology:
Application context dictates technology selection—high-volume academic centers prioritize throughput, while sustainability-focused facilities emphasize energy intensity and carbon footprint.
- Incineration:High-temperature combustion systems for pathological and pharmaceutical waste streams. Limited new installations in EU member states under Industrial Emissions Directive constraints. Remains prevalent in US Gulf Coast medical waste processing facilities with grandfathered permits.
- Autoclaving:Steam sterilization under pressure for decontamination prior to landfill disposal. German and French hospital networks maintain extensive installed bases. Energy consumption and cycle duration pressure operating economics.
- Chemical Treatment:Oxidative or chlorine-based neutralization for liquid biohazard streams.
- Microbial Treatment:Enzymatic and biological digestion processes for organic fluid breakdown.
Autoclaving retains the largest installed base; microbial treatment is gaining share fastest as EU Green Deal carbon targets reshape facility energy profiles.
Packaging Type:
Volume concentration among high-throughput surgical centers favors bulk procurement, while specialty bag innovations target robotic surgery and minimally invasive procedure waste profiles.
- Single-Use Packs:Pre-sterilized, individually wrapped containment for immediate procedural deployment. Massachusetts and Pennsylvania hospital systems specify single-use for oncology and transplant services where cross-contamination risk tolerance approaches zero. Premium pricing reflects sterilization validation costs.
- Bulk Containers:Large-volume collection vessels for central sterile processing departments. Texas medical centers with high-volume cardiac surgery programs deploy bulk systems to minimize material handling labor. Unit economics improve with scale.
- Dispensers:Wall-mounted or cart-integrated distribution systems for point-of-use access.
- Specialty Bags:Procedure-specific designs for laparoscopic suction canisters and robotic surgery fluid capture.
Bulk containers dominate procurement spend; specialty bags are climbing the fastest as robotic surgery adoption generates novel fluid containment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented German manufacturers supply precision sterilization equipment to hospital systems across Central Europe, while the United States maintains a fluid import balance in single-use containment materials sourced from Asian polymer processors. Trade flows concentrate where regulatory stringency creates premium-tier demand for certified disposal systems.
United States
Ambulatory surgical center expansion in Texas and Florida drives compact automated unit procurement. FDA 510(k) pathways and EPA RCRA tracking mandates govern device approval and waste chain documentation. Boston academic medical centers specify RFID-tracked fluid disposal platforms for Joint Commission audit compliance.
Germany
High surgical volume and BfArM infection control standards sustain demand for closed-loop management systems. EU MDR documentation requirements and REACH substance restrictions accelerate replacement of legacy containment with traceable platforms. Baden-Württemberg sterilization equipment clusters validate alternative elastomer seals for revised ECHA authorization lists.
Japan
Aging surgical demographics and robotic procedure adoption expand fluid handling infrastructure requirements. PMDA fast-track pathways for infection-prevention devices compress market entry timelines for novel containment technologies. Tokyo metropolitan hospital networks integrate automated quantification systems with existing EMR installations.
India
Government hospital modernization under Ayushman Bharat creates procurement volume for integrated fluid management systems. CDSCO medical device regulations and BIS quality standards structure import substitution incentives for domestic manufacturers. Maharashtra and Karnataka surgical hubs attract first-mover vendors establishing service networks.
United Kingdom
NHS procurement consolidation favors standardized disposal platforms across integrated care systems. MHRA post-Brexit regulatory alignment with EU MDR frameworks maintains certification continuity for continental suppliers. London and Southeast England tertiary centers deploy microbial treatment alternatives to reduce carbon intensity targets.
Surgical Fluid Disposal Market Competitive Landscape
Listed leaders compete with private specialists across capital equipment and consumable segments, producing a tiered structure where scale-driven corporations anchor premium integrated systems and mid-cap fabricators dominate commodity containment. Three archetypes occupy distinct competitive positions: diversified medical technology conglomerates with surgical workflow integration capabilities; sterilization and hospital supply specialists with European distribution density; and distribution-focused health service companies with same-day replenishment networks. M&A activity concentrates on automated fluid handling platform acquisitions, while geographic expansion through localized service partnerships targets emerging market hospital buildouts.
Within the diversified technology tier, Stryker Corporation and Medtronic Plc exemplify integrated capture-to-disposal workflow positioning, leveraging endoscopy and surgical robotics footprints to anchor system-level contracts. B. Braun Melsungen AG represents the sterilization-specialist archetype with European market access through hospital supply infrastructure. Cardinal Health, Inc. occupies the distribution-density position, competing on replenishment velocity for high-volume surgical centers. These three entities collectively illustrate how competitive advantage derives from either workflow integration, regional regulatory mastery, or logistics scale rather than product-specific differentiation.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Skyline Medical, Inc. |
| Baxter International, Inc. |
| Cardinal Health, Inc. |
| Hill-Rom Holdings, Inc. |
| Bard, A Becton Dickinson Company |
| Medtronic Plc |
| Olympus Corporation |
| Stryker Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at medical-grade polymer processors in the US Gulf Coast and German chemical corridors shapes both supply concentration and price floors for puncture-resistant containment materials. Scale advantages at these petrochemical hubs compress margin flexibility for mid-tier manufacturers while anchoring premium-tier pricing power with integrated device suppliers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in surgical fluid disposal. Price differentiation rests on FDA 510(k) certification tier and volume scale commitments from integrated delivery networks. Cost compression in standard containment tiers is intensifying because REACH substance restrictions force polymer reformulation investments. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare reimbursement pressures, while academic medical centers prioritize certification grade over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for medical-grade thermoplastic feedstocks. Supply concentrates in US Gulf Coast petrochemical complexes, German Ruhr industrial clusters, and South Korean polymer processors. Raw material dependencies include polypropylene resins, phthalate-free plasticizers, and RFID-enabled tracking components. Single-source vulnerability in specialized elastomer seals threatens continuity for European sterilization equipment manufacturers. Distribution runs through specialized medical device distributors with cross-border service networks rather than commodity plastics brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of validated ISO 13485 quality management capabilities constrains mid-tier manufacturer expansion, creating defensive moats for established sterilization specialists and workflow-integrated device conglomerates.
For Market Incumbents: Secure backward integration into medical-grade polymer compounding to preempt REACH authorization disruptions and capture margin from reformulated barrier materials. Expand service network density in Maharashtra and Karnataka surgical hubs before domestic competitors achieve CDSCO certification scale. Threat of reusable containment mandates under EU Green Deal circular economy targets demands preemptive investment in sterilizable vessel platforms. For New Entrants and Emerging Players: Differentiate on microbial treatment energy intensity metrics to capture carbon-conscious procurement committees in NHS integrated care systems and German hospital networks. White-space concentration sits with compact automated units for Arizona and California ambulatory surgical centers lacking centralized sterile processing infrastructure. Go-to-market leverage through GPO contracts managers at regional surgical center chains bypasses incumbent IDN consolidation barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sterilization-specialist archetypes with European regulatory mastery and hospital supply infrastructure density. Long-term viability hinges on convergence with robotic surgery fluid handling workflows rather than commodity containment replacement. Acquisition targets should demonstrate validated EMR interoperability with Cerner and Epic installations. Signal to watch: PMDA fast-track designations for infection-prevention devices indicating regulatory pathway efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Accelerated clearance timelines compress commercialization delays for novel barrier materials. |
| EU MDR Documentation Compliance | Traceable RFID-enabled systems satisfy BfArM audit requirements across German surgical centers. |
| Hospital System Partnership | Integrated delivery network standardization mandates displace individual facility procurement autonomy. |
| Software Companion Development | API integration with Epic and Cerner platforms resolves EMR interoperability barriers for volume tracking. |
| Reimbursement Strategy | Medicare alignment for ambulatory surgical center equipment payback thresholds shapes ASC procurement decisions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across sterile processing departments, biomedical engineering teams, GPO contracts managers, and infection control committee chairs. Secondary validation drew from FDA 510(k) filings, EPA RCRA tracking documentation, EU MDR technical file submissions, and hospital procurement database extracts. Bottom-up facility-level equipment counts and top-down polymer consumption estimates were triangulated to anchor volume projections.
Across the analysis window, the forecasting framework modeled product type segmentation, technology adoption curves, end-user capital availability tiers, and regional regulatory cluster intensity. CAGRs were derived from equipment replacement cycle analysis and surgical volume elasticity to fluid containment ratios. Industry-specific inputs included autoclave energy cost trajectories and REACH substance restriction implementation timelines.
Material uncertainties — regulatory acceleration of reusable containment mandates, polymer feedstock price volatility, and 510(k) pathway duration extensions — sit outside the modeled envelope. Forecasts reflect assumptions about IDN consolidation velocity and EU Green Deal enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Europe Pharmaceutical Logistics Market
Healthcare Services
Hospital Outsourcing Market
Healthcare Services
US Care Services Market
Healthcare Services
Global Hospital Services Market
Healthcare Services
India Senior Living Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Life Science Trade Lane Design and Qualification Services Market
Healthcare Services
Medical Case Management Services Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
Medical Transcription Services Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Australia Senior Living Market
Healthcare Services
Medical Waste Disposal Services Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
US Value-Based Healthcare Service Market