
 Healthcare Finance Solutions Market | 2026-2036
Healthcare Finance Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Finance Solutions Market Intelligence
Asset-light leasing models for diagnostic and surgical equipment is reconfiguring capital deployment across hospital networks. Siemens Financial Services leverages captive finance structures to anchor long-term equipment relationships with tier-one health systems. General Electric Company sustains competitive positioning through specialized healthcare lending programs tied to imaging modalities. Koninklijke Philips N.V. differentiates via integrated subscription models that bundle devices with performance-linked financing.
Healthcare finance solutions encompass software platforms, lending instruments, and payment infrastructure that manage revenue capture, patient billing, and capital procurement for medical providers. Core systems integrate HL7 FHIR interoperability standards with real-time claims adjudication engines to reduce days in accounts receivable. Revenue cycle management platforms dominate transaction volume, while AI-driven analytics segments capture expanding margin pools as predictive denial management tools penetrate mid-size hospital markets. Cloud-based solutions lead deployment preferences, though on-premise solutions persist among compliance-sensitive academic medical centers.
FDA oversight of software-as-medical-device billing modules and HIPAA security requirements shape product development roadmaps for platform vendors. CMS reimbursement rulemaking, including the No Surprises Act implementation, forces continuous recalibration of patient access and estimation tools. Stakeholders must monitor evolving state-level balance billing prohibitions and their interface with federal price transparency mandates to anticipate compliance-driven procurement cycles.
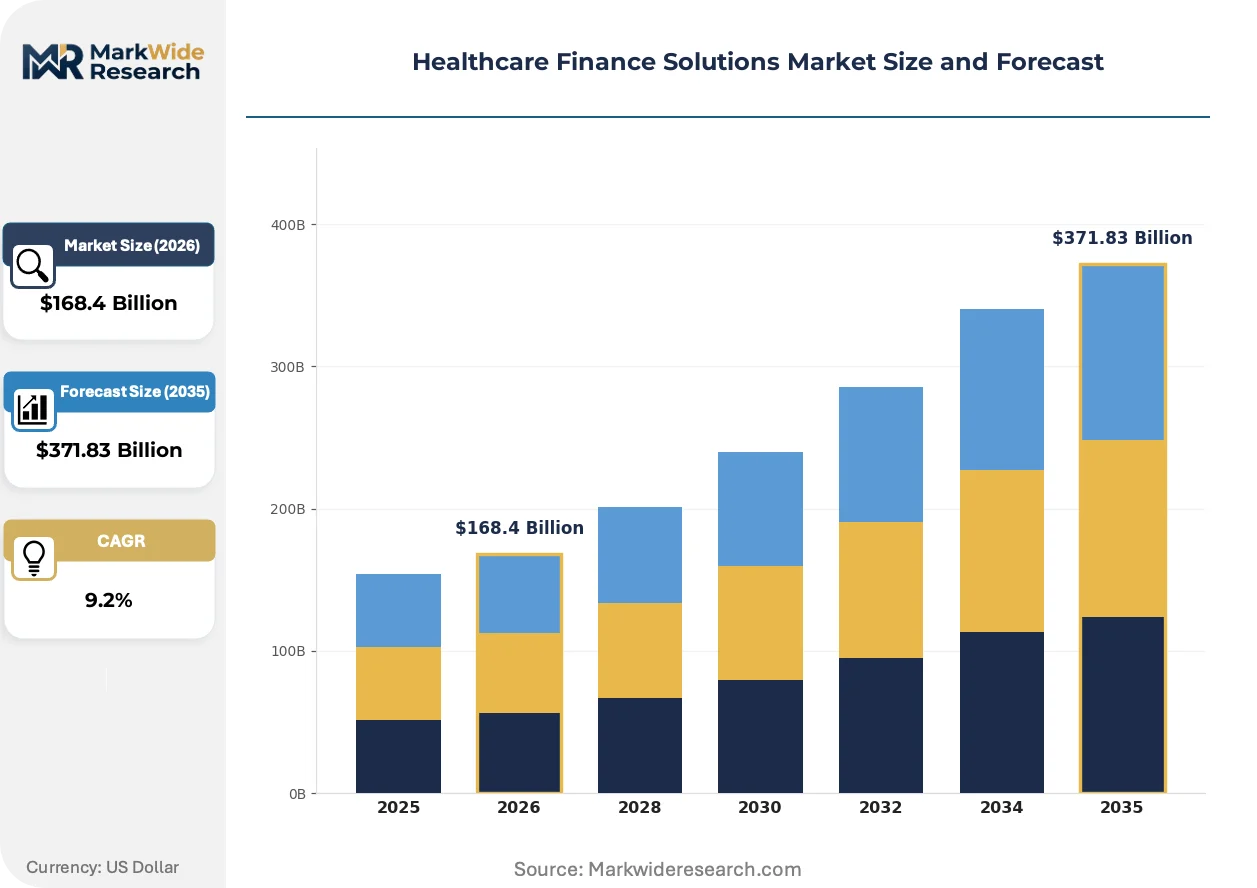
Market Dynamics
Cloud migration is compressing deployment cycles for revenue cycle management platforms as hospital systems abandon decade-old on-premise infrastructure. The No Surprises Act and CMS price transparency mandates are forcing simultaneous rewrites of patient estimation modules and claims adjudication engines across vendor roadmaps.
Growth Catalysts
- Interoperability mandates:HL7 FHIR standards adoption is accelerating data exchange between disparate clinical and financial systems. Hospital networks in the United States are prioritizing platforms with native FHIR compliance to reduce integration friction.
- Denial management automation:AI-driven predictive analytics are reducing days in accounts receivable for mid-size hospital markets. These tools identify claim defects prior to submission, cutting rework costs for revenue cycle teams.
- Integrated delivery consolidation:Health system mergers are creating demand for unified financial platforms spanning multiple facilities. Consolidated entities require centralized visibility across previously siloed revenue operations.
Market Restraints
- Compliance-sensitive infrastructure lock-in:Academic medical centers maintain on-premise deployments due to HIPAA security requirements and institutional review board protocols. Migration costs and audit trail preservation slow cloud adoption at these sites.
- Specialized talent scarcity:Revenue cycle management platforms require expertise spanning clinical workflows, payer contract structures, and software configuration. Health systems compete for limited professionals with hybrid clinical-technical backgrounds.
- State-level regulatory fragmentation:Balance billing prohibitions vary across jurisdictions, complicating national platform standardization. Vendors must maintain jurisdiction-specific rule engines, increasing development overhead.
Strategic Opportunities
- Subscription bundling models:Equipment manufacturers are integrating device financing with performance-linked service contracts. These structures shift capital expenditure to operational budgets for capital-constrained hospitals.
- Patient financial engagement platforms:Consumer-directed payment plans and transparent cost estimation tools address rising patient responsibility for healthcare costs. Early adopters are reducing bad debt write-offs through point-of-service collections.
- Real-time claims adjudication:Instant eligibility verification and prior authorization automation are compressing reimbursement timelines. Payer-provider data exchange improvements are enabling same-day payment confirmation.
Industry Challenges
- Legacy system integration complexity:Decades-old practice management software and custom-built billing modules resist API-based connectivity. Health systems face protracted migration timelines and dual-system operational overhead.
- Certification timeline compression:FDA oversight of software-as-medical-device billing modules requires quality management system documentation. Vendors must navigate 510(k) pathways or De Novo classifications for algorithm-driven clinical decision support features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Finance Solutions Market |
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $371.83 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Revenue Cycle Management, Patient Access Solutions, Payment Processing Systems, Medical Billing Services Client Type: Hospitals, Clinics, Insurance Providers, Healthcare Systems Technology: Cloud-Based Solutions, On-Premise Solutions, AI-Driven Analytics, Mobile Applications End User: Finance Departments, Administrative Staff, C-suite Executives, Compliance Officers |
| Companies Covered | Koninklijke Philips N.V., General Electric Company, Siemens Financial Services, Inc., Commerce Bancshares, Inc., Thermo Fisher Scientific, Inc., Stryker, Optum, Inc., Change Healthcare LLC, Oxford Finance LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Finance Solutions Market Strategic Shifts & Innovations
Machine learning architectures are embedding directly into financial workflows, transforming retrospective reporting into prospective intervention. Platform vendors are racing to deploy predictive models that anticipate denial patterns before claim submission.
Natural language processing engines are digitizing prior authorization workflows by extracting clinical documentation requirements from payer policies. Specialty practices with high prior authorization volumes are adopting these tools to reduce administrative burden. The technology is digitizing what previously required dedicated staff hours of manual chart review and form completion.
CMS reimbursement rulemaking is forcing continuous recalibration of patient access and estimation tools. The No Surprises Act implementation requires platforms to generate good-faith estimates for scheduled services, including out-of-network scenario modeling. Hospital systems in the United States are upgrading estimation modules to comply with federal price transparency mandates while managing state-level balance billing variations.
Hospital procurement teams are unbundling after-sales service from software licensing, demanding modular pricing for implementation, training, and ongoing support. This pattern concentrates among mid-size health systems seeking cost visibility and vendor accountability. The shift is most pronounced in the United States where integrated delivery networks negotiate enterprise agreements spanning dozens of facilities.
Healthcare Finance Solutions Market Segmentation
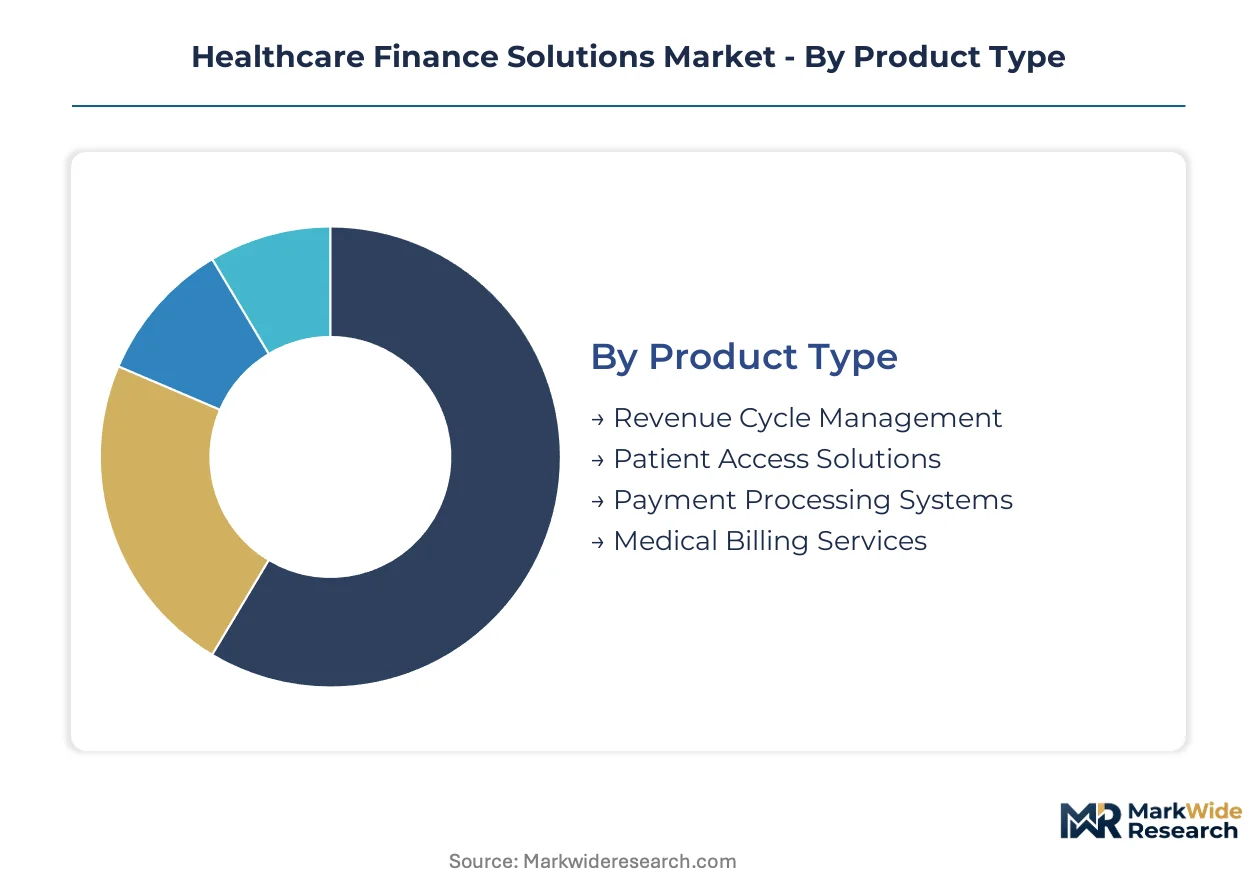
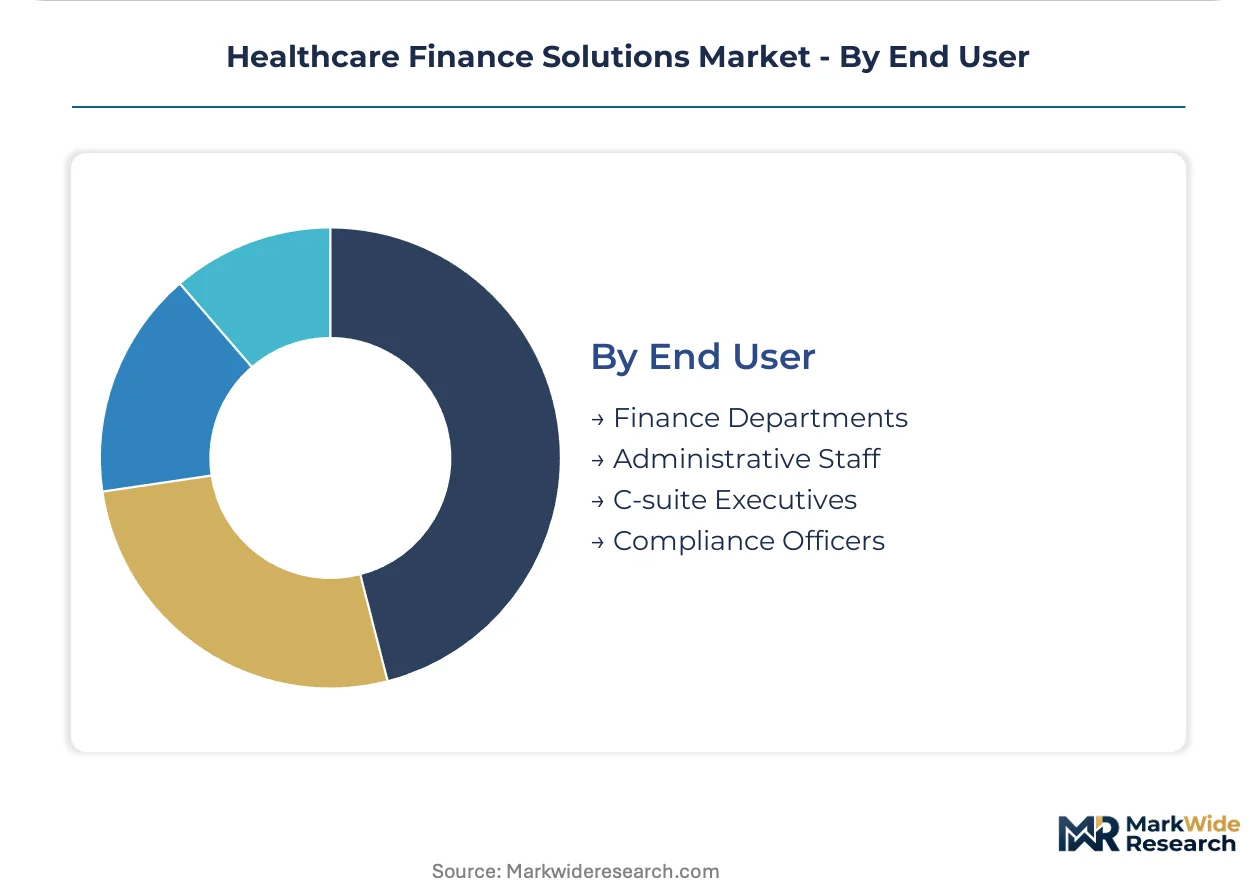
Healthcare finance solutions segment along four critical dimensions that determine deployment complexity and vendor selection criteria. Product type distinctions drive integration requirements with existing hospital infrastructure. Client type and end-user variations shape pricing models and implementation timelines across the market.
Product Type:
After-sales-service intensity varies sharply across product categories, with implementation support and ongoing optimization consuming disproportionate resources for certain modules.
- Revenue Cycle Management:Comprehensive platforms integrating claims processing, denial management, and accounts receivable automation. United States hospital networks prioritize these systems as consolidation creates multi-facility financial operations requiring centralized visibility. HL7 FHIR interoperability mandates accelerate replacement cycles for legacy installations.
- Patient Access Solutions:Front-end systems managing scheduling, registration, and real-time eligibility verification. Demand concentrates in mid-size health systems seeking to reduce bad debt through point-of-service collections and transparent cost estimation tools. The No Surprises Act implementation forces continuous recalibration of estimation modules.
- Payment Processing Systems:Infrastructure handling patient payments, payer remittances, and financial clearinghouse operations.
- Medical Billing Services:Outsourced or co-sourced revenue capture functions spanning coding, submission, and appeals management.
Revenue Cycle Management holds the largest share; momentum sits with Patient Access Solutions.
Client Type:
Cost tier stratification separates enterprise deployments from scaled-down implementations, with procurement authority and budget cycles diverging significantly across client categories.
- Hospitals:Acute care facilities requiring comprehensive platforms spanning inpatient, outpatient, and emergency revenue streams. Integrated delivery networks in the United States negotiate enterprise agreements covering dozens of facilities, demanding modular pricing for implementation and training.
- Clinics:Ambulatory settings with streamlined workflows and lower transaction volumes. Physician practices prioritize cloud-based solutions with minimal IT overhead, though specialized talent scarcity complicates configuration for hybrid clinical-technical requirements.
- Insurance Providers:Payer organizations requiring real-time adjudication capabilities and provider network management tools.
- Healthcare Systems:Multi-entity organizations spanning hospitals, clinics, and post-acute facilities.
Hospitals command the deepest vendor relationships; clinics are expanding most quickly as cloud migration compresses deployment cycles.
Technology:
Application maturity separates proven architectures from emerging capabilities, with compliance requirements and integration complexity determining adoption velocity.
- Cloud-Based Solutions:Scalable infrastructure displacing legacy on-premise deployments across North American provider networks. Hospital systems abandon decade-old installations as cloud migration compresses implementation timelines and reduces capital expenditure requirements.
- On-Premise Solutions:Locally hosted systems maintained by compliance-sensitive academic medical centers. HIPAA security requirements and institutional review board protocols preserve demand despite higher total cost of ownership.
- AI-Driven Analytics:Predictive models embedding into denial management and revenue forecasting workflows.
- Mobile Applications:Point-of-care tools enabling real-time patient financial engagement and administrative workflow management.
Cloud-Based Solutions dominate current procurement; AI-Driven Analytics shows the steepest expansion trajectory as predictive denial management penetrates mid-size markets.
End User:
Customer type specialization determines interface complexity and training requirements, with workflow integration challenges varying by organizational role.
- Finance Departments:Revenue cycle teams requiring granular visibility into claims status, payer contracts, and cash flow forecasting. These users drive platform selection criteria and negotiate service level agreements with vendors.
- Administrative Staff:Front-desk and scheduling personnel interacting with patient access modules. Staff turnover creates continuous training demands and favors intuitive interface design over feature depth.
- C-suite Executives:Leadership requiring consolidated dashboards spanning financial performance across multiple facilities.
- Compliance Officers:Risk management personnel monitoring adherence to CMS reimbursement rulemaking and state-level balance billing prohibitions.
Finance Departments anchor purchasing decisions; Compliance Officers are gaining influence fastest as regulatory fragmentation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial services surplus in healthcare finance technology, exporting revenue cycle management platforms while importing specialized diagnostic equipment financing. Germany and Japan maintain complementary positions in medical device captive finance. China's domestic software sector is displacing foreign platforms across tier-two hospital networks.
United States
Integrated delivery networks in Texas and Florida are consolidating financial operations across dozens of facilities, driving enterprise procurement of cloud-native revenue cycle platforms. CMS price transparency mandates and the No Surprises Act force continuous recalibration of patient estimation modules. The Nashville health services cluster anchors vendor development activity, with multiple platform providers maintaining implementation centers there.
Germany
Siemens Financial Services leverages captive finance structures to anchor long-term equipment relationships with university hospitals across Bavaria and North Rhine-Westphalia. EMA medical device regulations and national hospital financing frameworks shape procurement timelines for diagnostic imaging modalities. The Munich-Stuttgart corridor concentrates vendor engineering resources for healthcare lending program development.
Japan
METI digital health initiatives accelerate FHIR interoperability adoption among Tokyo and Osaka metropolitan hospital systems. PMDA oversight of software-as-medical-device billing modules extends quality management requirements to financial platform vendors. The Nagoya medical device manufacturing belt generates demand for integrated subscription models bundling equipment with performance-linked financing.
United Kingdom
NHS England's procurement frameworks prioritize cloud-based revenue cycle solutions that reduce capital expenditure for cash-constrained trusts across London and the Midlands. GDPR and NHS Digital security requirements preserve hybrid deployment preferences at academic medical centers. The Cambridge-Oxford-London health tech triangle attracts platform vendors seeking proximity to clinical research institutions.
India
CDSCO medical device regulations and RBI digital lending guidelines shape vendor entry strategies for hospital networks in Maharashtra and Karnataka. PLI scheme incentives for domestic manufacturing extend to diagnostic equipment financing structures. The Hyderabad-Bengaluru corridor hosts emerging health tech platforms targeting mid-tier hospital chains with subscription-based revenue cycle tools.
Healthcare Finance Solutions Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in lending and equipment finance. The vendor base stratifies across three tiers: diversified conglomerates with captive finance arms, pure-play revenue cycle software vendors, and specialized healthcare lenders. Two dominant competitive moves define current positioning: subscription bundling that merges device financing with performance contracts, and cloud migration partnerships that compress implementation timelines for mid-size health systems.
Among diversified technology conglomerates, Koninklijke Philips N.V., General Electric Company, and Siemens Financial Services occupy positions exemplifying the captive finance archetype. These entities leverage equipment manufacturing relationships to anchor long-term hospital contracts. Philips represents the integrated subscription model, GE exemplifies specialized healthcare lending programs, and Siemens anchors equipment-heavy financing structures with tier-one health systems.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| General Electric Company |
| Siemens Financial Services, Inc. |
| Commerce Bancshares, Inc. |
| Thermo Fisher Scientific, Inc. |
| Stryker |
| Optum, Inc. |
| Change Healthcare LLC |
| Oxford Finance LLC |
| Others |
Cost & Logistics Intelligence
The Nashville health services cluster anchors North American platform development capacity, concentrating vendor engineering resources and implementation centers. This geographic concentration grants established revenue cycle management providers pricing leverage over mid-size hospital systems seeking rapid cloud migration timelines. Tier-one integrated delivery networks exploit this supply-side clustering through enterprise-wide negotiations that compress per-facility licensing costs.
Pricing Analysis
Hospital procurement teams anchor pricing dynamics through unbundling demands that separate software licensing from implementation and training modules. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, FHIR interoperability certification status, and after-sales service intensity. Pricing pressure stems from cloud-native entrants offering modular subscription terms without legacy migration overhead. Mid-size health systems exhibit highest price sensitivity due to capital constraints and competing IT priorities, while academic medical centers prioritize compliance-grade configurations over cost minimization.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Siemens Financial Services and GE Healthcare anchor equipment-heavy procurement workflows for diagnostic imaging modalities. Software development concentrates in the United States, India, and Germany, with cloud infrastructure drawing from hyperscaler networks across multiple jurisdictions. Supply chain risk centers on single-source vulnerability for HL7 FHIR compliance certification and FDA 510(k) pathway navigation. Distribution runs through direct enterprise sales teams for hospital networks and channel partners for ambulatory clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare finance solutions represent a service-attach opportunity where recurring-revenue streams from denial management automation and patient engagement platforms expand faster than one-time software licensing. After-sales optimization and ongoing FHIR compliance updates capture expanding margin pools as regulatory mandates proliferate.
For Market Incumbents: Build switching-cost moats through deep integration with hospital EHR systems and payer contract databases. Incumbents should consolidate position by acquiring specialized AI analytics firms that enhance predictive denial capabilities, countering cloud-native entrants with superior implementation speed. Captive financing arms at equipment manufacturers like Philips and Siemens should expand subscription bundling to lock out independent software vendors.
For New Entrants and Emerging Players: Pursue white-space opportunities in patient financial engagement platforms for mid-size health systems lacking dedicated revenue cycle staff. The most penetrable segment spans ambulatory surgery centers and specialty practices with high prior authorization volumes. A direct-to-practice go-to-market angle leveraging intuitive mobile interfaces can bypass entrenched hospital procurement committees.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform vendors with native FHIR compliance and established payer connectivity. Long-term viability favors acquisition targets combining cloud-native architecture with regulatory workflow expertise. The signal to watch is CMS reimbursement rulemaking velocity, as accelerated mandates compress vendor upgrade cycles and favor agile platforms over legacy installations.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Interoperability Certification | CMS mandates accelerate replacement cycles for non-compliant legacy revenue cycle installations. |
| Cloud-Native Platform Migration | Mid-size hospital systems abandon decade-old on-premise infrastructure for compressed deployment timelines. |
| AI-Driven Denial Management | Predictive analytics reduce days in accounts receivable for revenue cycle teams. |
| Subscription Bundling Models | Equipment manufacturers shift hospital capital expenditure to operational budgets through performance-linked financing. |
| Patient Financial Engagement Platforms | Point-of-service collection tools address rising patient responsibility for healthcare costs. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with revenue cycle executives, hospital CIOs, payer contract managers, and GPO procurement leads; and secondary validation against CMS Medicare cost reports, hospital procurement databases, SEC 10-K healthcare IT disclosures, and FDA 510(k) clearance records. Bottom-up facility-level deployment estimates triangulated against top-down vendor revenue segmentation across product type, client category, and technology deployment model.
Forecast inputs incorporated cloud migration velocity, HL7 FHIR adoption curves, and regulatory mandate implementation timelines across the projection horizon. Segmentation dimensions modeled include revenue cycle management versus patient access solutions, hospital versus clinic client types, cloud-based versus on-premise deployment, and AI analytics penetration rates. CAGRs derived from facility count expansion, software pricing trends, and service-attach rate assumptions specific to denial management automation and patient engagement modules.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles, CMS reimbursement rulemaking velocity, or cloud infrastructure cost curves would shift the trajectory. Forecasts reflect documented assumptions about interoperability mandate enforcement and payer-provider data exchange maturity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Global Financial Consulting Software Market
Financial Services
Legal Management Consulting Service Market
Financial Services
Australia Online Gambling Market
Financial Services
LAMEA Financial Services Software Market
Financial Services
South Korea Trade Finance Market
Financial Services
Spain E-Brokerage Market
Financial Services
Multivendor ATM Software Market
Financial Services
China Factoring Services Market
Financial Services
Commodity Services Market
Financial Services
Southeast Asia E-Invoicing Market
Financial Services
Currency Management Market
Financial Services
E-Brokerage Market
Financial Services
Investment Trading Software Market
Financial Services
United States Payroll Services Market
Financial Services
E-KYC Market
Financial Services
Canada Credit Cards Market