
 Automotive Finance Market | 2026-2036
Automotive Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Finance Market Analysis
ISO 22241 certification for AdBlue-compatible diesel financing programs is reorganizing which captive lenders qualify for manufacturer-backed contracts in Europe. Toyota Financial Services leverages its captive structure to anchor lease penetration across Asian markets. Ford Motor Credit Company sustains dominant floorplan financing control through dealership inventory lending networks.
Automotive finance encompasses credit instruments, lease structures, and insurance products that enable vehicle acquisition by consumers and commercial operators, typically involving interest rate spreads of 2-8 percentage points above central bank benchmarks and loan-to-value ratios calibrated against depreciation curves. Its primary purpose channels capital from institutional investors to mobility assets while managing residual value exposure across vehicle lifecycles. New vehicle financing commands the deepest margin pools due to manufacturer subsidy programs and bundled warranty revenue, while used vehicle financing is accelerating fastest as certified pre-owned programs extend lender relationships into secondary ownership cycles. Fleet operator lending concentrates among specialist underwriters who differentiate through telematics-integrated risk scoring.
The US Consumer Financial Protection Bureau enforces Truth in Lending Act disclosures that shape payment structure transparency, while the EU Consumer Credit Directive mandates standardized annual percentage rate presentations across member states. The Basel III framework constrains bank capital allocation toward automotive asset-backed securities, redirecting origination volume toward non-bank specialists. Stakeholders must monitor how embedded vehicle connectivity data reshapes residual value forecasting and collateral risk models.
Market Dynamics
Embedded vehicle connectivity is fragmenting residual value forecasting models across automotive finance, forcing lenders to rebuild collateral risk frameworks around real-time telematics data streams rather than static depreciation tables.
Growth Catalysts
- EU Consumer Credit Directive revision:Standardized annual percentage rate presentations are reducing information asymmetry between lenders and borrowers across member states, accelerating loan origination velocity.
- Electric vehicle fleet procurement:Logistics operators are expanding battery-electric truck and van acquisitions, creating specialized asset-backed financing instruments with battery health monitoring clauses.
- Telematics-integrated risk scoring:Fleet underwriters are embedding IoT sensors into commercial vehicle contracts to price usage-based premiums and dynamic interest rate adjustments.
Market Restraints
- Basel III capital constraints:Bank allocation toward automotive asset-backed securities faces tightened risk-weighting requirements, compressing institutional participation in securitization pools.
- Lithium-ion battery residual uncertainty:Rapid degradation curves and replacement cost volatility are inflating loss-given-default assumptions for electric vehicle lease portfolios.
- China rare earth processing concentration:Magnet supply bottlenecks for electric drivetrains are delaying manufacturer subsidy programs that anchor captive finance profitability.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for electric vehicle manufacturing are drawing foreign captive lenders into joint venture structures with domestic non-bank financial companies.
- Subscription-to-ownership conversion models:Flexible mobility-as-a-service contracts are creating bridge financing products that capture customers before traditional loan eligibility.
- ISO 22241 certification expansion:AdBlue-compatible diesel programs are opening manufacturer-backed contract eligibility for secondary lenders previously excluded from European captive networks.
Industry Challenges
- Data science talent scarcity:Residual value modeling teams lack sufficient actuaries trained in machine learning interpretation of connected vehicle telemetry streams.
- Legacy core system integration:Mainframe-based loan servicing platforms require multimillion-dollar middleware investments to interface with API-driven fintech origination channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Finance Market |
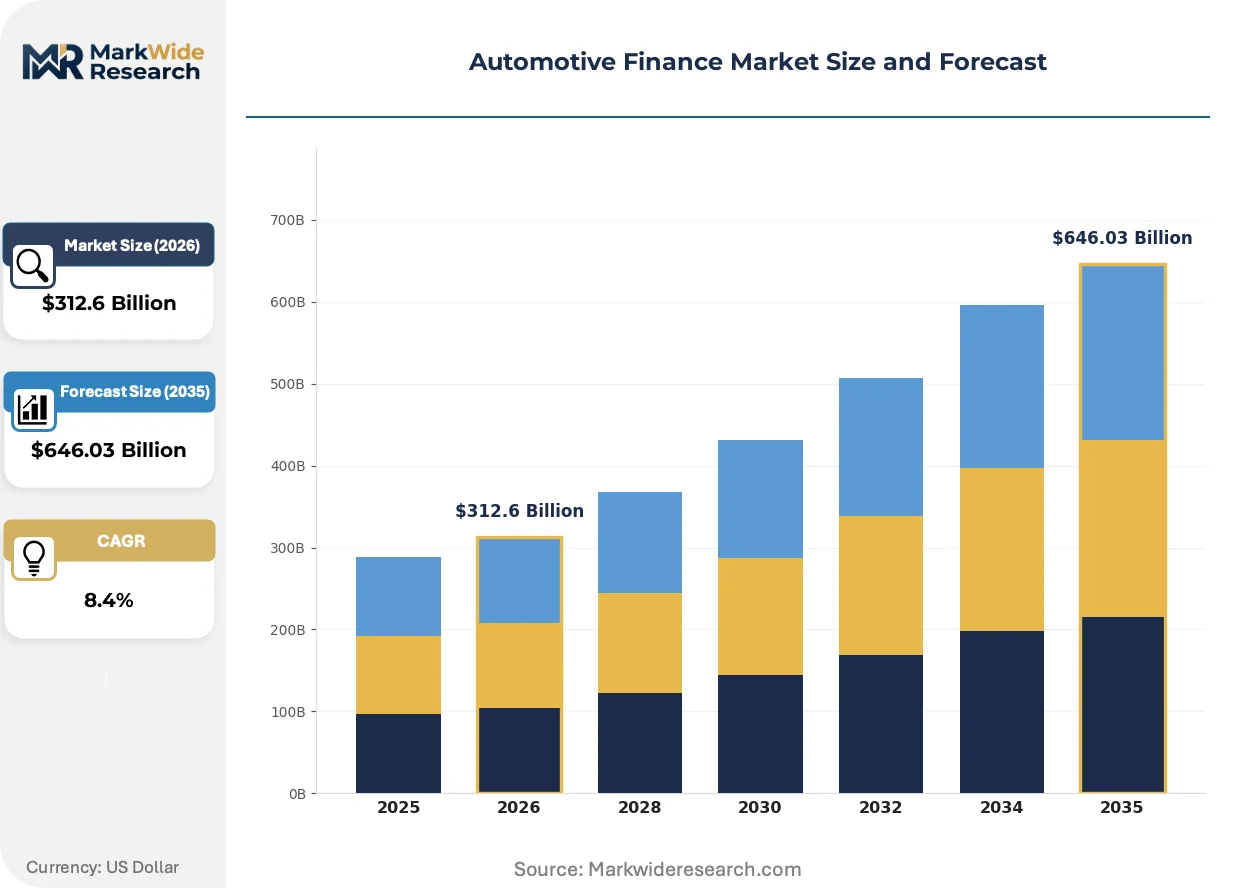
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $646.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Type: Loan, Lease, Trade-in, Cash Payment Customer Type: Individual Buyers, Fleet Operators, Dealerships, Corporates Service Type: New Financing, Used Financing, Refinancing, Auction Financing Insurance Type: Comprehensive, Third-Party Liability, Gap Insurance, Collision |
| Companies Covered | Toyota Financial Services, Ford Motor Credit Company, General Motors Financial Company, Volkswagen Financial Services, Ally Financial, Bank of America, Daimler Financial Services, Capital One, Hitachi Capital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Finance Market Emerging Trajectories
Artificial intelligence is penetrating automotive finance through three distinct vectors: predictive underwriting engines, automated residual value forecasting, and real-time fraud detection systems that flag anomalous loan application patterns.
Blockchain-based smart contracts are fragmenting title transfer and lien registration processes across distributed ledger platforms. Captive lenders in Germany and the United States are piloting Ethereum-compatible systems for instantaneous collateral verification upon payment completion. This disintermediation is compressing notary and state registry fee structures while introducing cryptographic key management complexity into recovery operations.
The EU AI Act's risk classification framework is mandating human oversight loops for automated credit decisioning algorithms above defined threshold values. Lenders deploying machine learning scoring models must maintain explainability documentation and bias audit trails. German and French automotive finance subsidiaries are restructuring data science teams to embed compliance officers within model development pipelines.
Fleet procurement departments are consolidating vendor relationships around total cost of mobility metrics rather than sticker price financing. Logistics operators in the Netherlands and California are demanding bundled packages spanning vehicles, charging infrastructure, maintenance, and energy costs under single master lease agreements. This unbundling of traditional asset finance from operational expenditure is compressing standalone loan margins while expanding service revenue pools.
Automotive Finance Market Segmentation
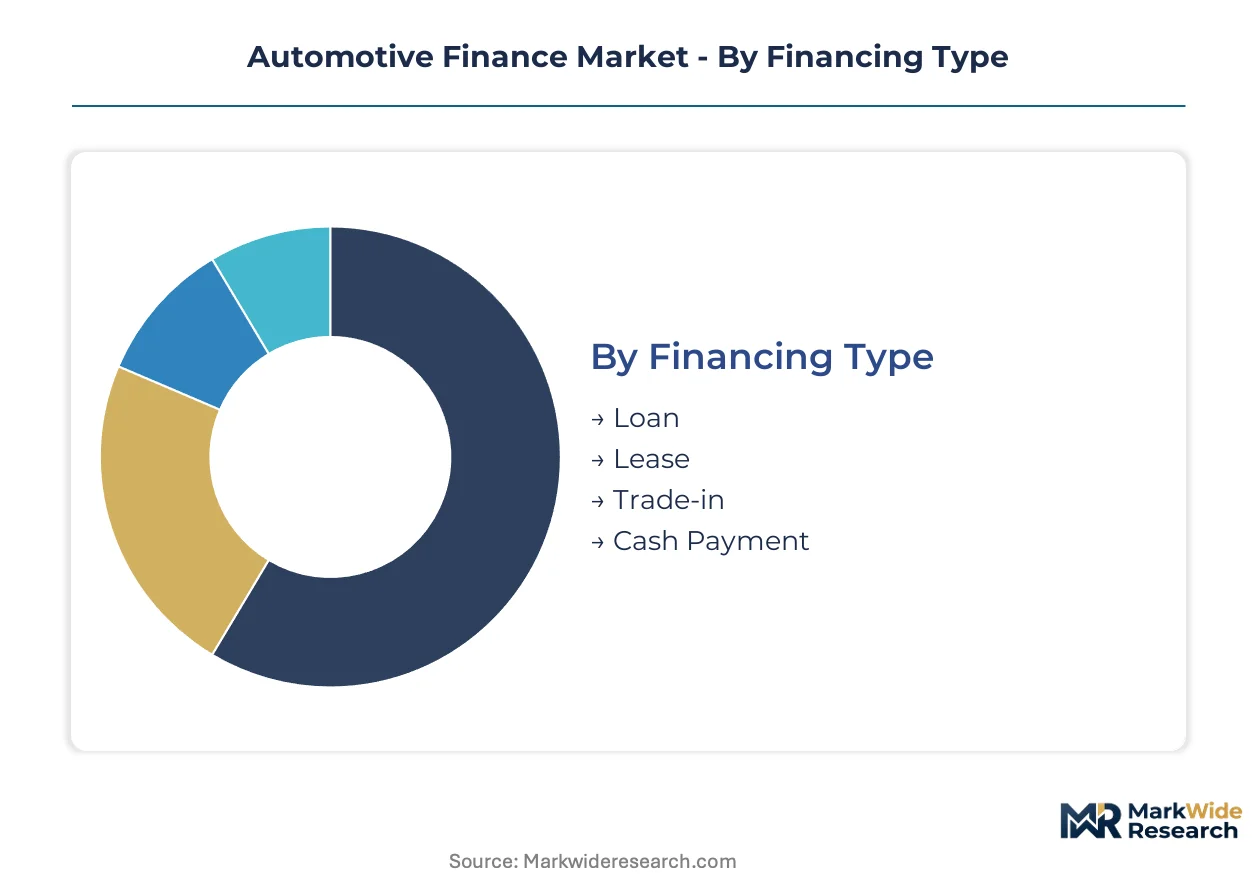
Segmentation in automotive finance determines capital allocation efficiency across divergent risk profiles and margin structures. Lenders calibrate pricing models, residual value assumptions, and servicing infrastructure around these category boundaries.
Financing Type:
Margin pools concentrate in lease structures where captive manufacturers subsidize rates to drive vehicle sales velocity.
- Loan:Fixed-term installment contracts with interest rate spreads calibrated against central bank benchmarks and borrower credit tiers. Demand concentrates among individual buyers in Germany's automotive manufacturing corridor, where manufacturer-backed rate subsidies compress origination margins but deepen customer lifetime value through repeat purchase cycles.
- Lease:Closed-end contracts transferring residual value risk to lenders while capturing monthly payments below equivalent loan installments. Fleet operators in the Netherlands are consolidating procurement around battery-electric van leases with battery health monitoring clauses, creating specialized asset-backed instruments with telematics-integrated pricing.
- Trade-in:Equity rollover financing that bridges outstanding loan balances into replacement vehicle contracts. Captive lenders leverage manufacturer subsidy programs to absorb negative equity positions.
- Cash Payment:Self-funded acquisition bypassing interest income pools but generating insurance and warranty attachment opportunities. Wealthy individual segments in urban China favor this route to avoid credit documentation requirements.
The dominant share belongs to Loan, while Lease is closing the gap fastest as fleet electrification accelerates specialized contract structures.
Customer Type:
Volume concentration varies sharply by origination channel, with fleet operators demanding bundled service packages that reshape traditional asset finance economics.
- Individual Buyers:Retail consumers accessing standard credit scoring frameworks with loan-to-value ratios calibrated against depreciation curves. California logistics operators purchasing personal vehicles for commercial use are blurring underwriting boundaries between retail and commercial risk pools.
- Fleet Operators:Commercial entities procuring multiple units under master lease agreements with usage-based pricing terms. Specialist underwriters in the United States differentiate through telematics-integrated risk scoring that prices dynamic interest rate adjustments against real-time vehicle utilization data.
- Dealerships:Inventory financing recipients dependent on floorplan credit lines to maintain new vehicle stock. Ford Motor Credit Company sustains dominant position through dealership inventory lending networks that anchor manufacturer distribution control.
- Corporates:Enterprise mobility programs spanning executive vehicles, sales fleets, and service operations. German automotive subsidiaries structure these around total cost of mobility metrics rather than sticker price financing.
Individual Buyers retain the largest origination volume, though Fleet Operators are expanding most quickly as electrification demands specialized underwriting capabilities.
Service Type:
Customer lifecycle positioning determines margin sustainability, with refinancing and used financing extending relationships into secondary ownership cycles.
- New Financing:First-owner contracts commanding deepest margin pools through manufacturer subsidy programs and bundled warranty revenue. Toyota Financial Services leverages captive structure to anchor lease penetration across Asian markets.
- Used Financing:Secondary market credit instruments accelerating fastest as certified pre-owned programs extend lender relationships. India's PLI scheme for automotive manufacturing is drawing foreign captive lenders into joint venture structures with domestic non-bank financial companies targeting this segment.
- Refinancing:Rate reduction or term extension contracts capturing customers from competing lenders. Embedded vehicle connectivity data enables real-time collateral monitoring that supports competitive pricing.
- Auction Financing:Dealer-to-dealer inventory credit supporting wholesale vehicle transactions. Floorplan specialists provide 30-90 day credit lines against auction purchase invoices.
New Financing holds the dominant position, while Used Financing is gaining share fastest as vehicle supply constraints extend asset lifecycles.
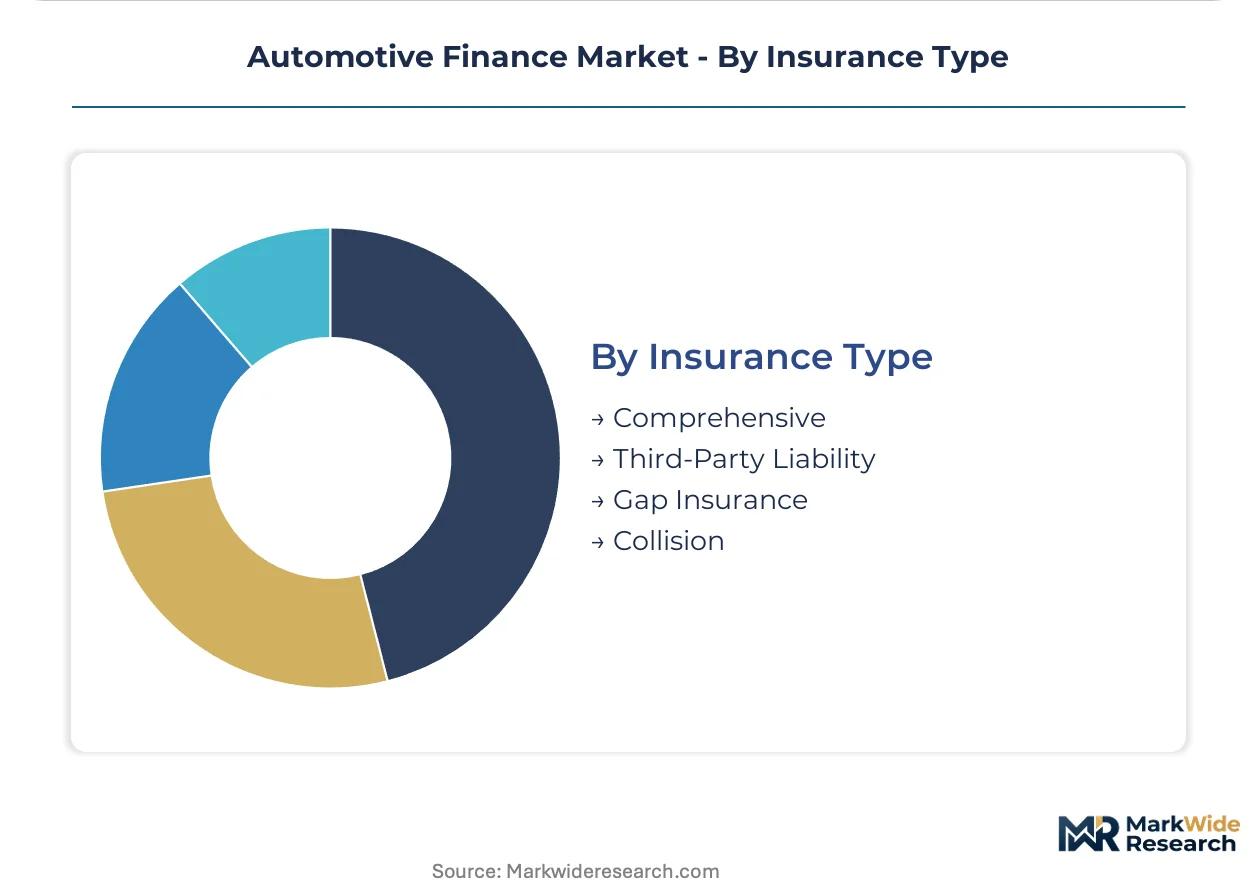
Insurance Type:
Risk transfer products generate ancillary revenue streams that offset compressed loan margins in competitive origination environments.
- Comprehensive:Full-spectrum coverage combining collision, theft, and liability protection into single premium structures. European lenders embed these into lease contracts to protect residual value exposure.
- Third-Party Liability:Mandatory minimum coverage meeting jurisdictional legal requirements. India's central bank regulations mandate disclosure of bundled insurance costs under revised consumer credit frameworks.
- Gap Insurance:Depreciation protection covering outstanding loan balances exceeding actual cash value at total loss. Battery-electric vehicle leases incorporate modified gap terms addressing rapid lithium-ion degradation curves.
- Collision:Physical damage coverage for at-fault accidents. Fleet underwriters price this dynamically through telematics-integrated usage data from IoT sensors.
Comprehensive coverage dominates attachment rates, though Gap Insurance is climbing fastest as electric vehicle residual uncertainty inflates loss-given-default assumptions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives in India and China's dual carbon goals are redirecting captive finance flows toward electric vehicle manufacturing clusters. Germany's automotive corridor maintains dense lender concentration around OEM headquarters. Brazil's central bank rate adjustments are compressing loan spreads for imported vehicle financing.
Germany
BMW Group and Volkswagen Group headquarters anchor captive finance concentration in Munich and Wolfsburg. The EU Consumer Credit Directive revision mandates standardized annual percentage rate presentations across all member states. The Baden-Württemberg manufacturing belt around Stuttgart sustains dense floorplan lending networks serving Porsche and Mercedes-Benz dealership clusters.
United States
Logistics operators in California and Texas are consolidating procurement around battery-electric truck leases with telematics-integrated pricing. The Consumer Financial Protection Bureau enforces Truth in Lending Act disclosures shaping payment structure transparency. Michigan's Detroit-Warren corridor retains dominant captive finance origination volume through Ford Motor Credit Company and General Motors Financial Company headquarters operations.
China
Domestic EV manufacturers BYD and NIO are expanding captive finance arms to capture lease penetration in tier-one cities. The Ministry of Industry and Information Technology regulates embedded vehicle connectivity data usage under national cybersecurity frameworks. The Yangtze River Delta around Shanghai concentrates fintech-lender joint ventures targeting subscription-to-ownership conversion models.
India
Maruti Suzuki and Tata Motors are drawing foreign captive lenders into joint venture structures with domestic non-bank financial companies. The Reserve Bank of India mandates disclosure of bundled insurance costs under revised consumer credit frameworks. The Gujarat automotive manufacturing zone near Sanand anchors production-linked incentive flows for electric vehicle financing programs.
Brazil
Fleet operators in São Paulo state are demanding bundled packages spanning vehicles, maintenance, and fuel costs under single master lease agreements. The central bank's Selic rate trajectory compresses interest rate spreads for vehicle financing portfolios. The ABC automotive cluster in Greater São Paulo sustains dense dealership inventory lending networks serving Fiat and Volkswagen distribution channels.
Automotive Finance Market Vendor Landscape
Listed leaders compete with private specialists across capital access and regulatory compliance capabilities. Captive finance arms of major OEMs maintain structural advantages through manufacturer subsidy programs and residual value risk absorption. Three archetypes dominate: bank-owned diversified lenders, OEM-captive specialists, and independent non-bank underwriters. M&A activity concentrates on fintech origination platform acquisitions and telematics data partnership formations.
Within the captive specialist tier, Toyota Financial Services exemplifies Asia-Pacific lease penetration strategies, Ford Motor Credit Company anchors North American floorplan financing dominance, and Volkswagen Financial Services represents European manufacturer-backed contract scale. These entities occupy positions where OEM relationships provide preferential access to residual value data and bundled warranty revenue streams.
| Leading Market Players |
|---|
| Toyota Financial Services |
| Ford Motor Credit Company |
| General Motors Financial Company |
| Volkswagen Financial Services |
| Ally Financial |
| Bank of America |
| Daimler Financial Services |
| Capital One |
| Hitachi Capital |
| Others |
Supply Flow & Price Mechanics
Forty-five-day floorplan credit cycles anchor working capital velocity for dealership inventory networks, concentrating pricing power among captive lenders with manufacturer-backed subsidy programs while compressing margins for independent non-bank underwriters lacking origination scale.
Pricing Analysis
Certification level creates the primary spread between manufacturer-captive and independent lender rate sheets, with ISO 22241-compliant diesel programs and Basel III capital adequacy tiers differentiating access to subsidized funding pools. Three-tier pricing structure across premium captive-subsidized, standard bank-sponsored, and economy non-bank segments reflects origination channel control and residual value risk absorption capacity. Pricing pressure stems from telematics-integrated fleet contracts demanding usage-based rate adjustments that compress traditional fixed-spread models. Fleet operators exhibit highest price sensitivity due to total-cost-of-mobility procurement consolidation, while individual retail buyers show lowest sensitivity where manufacturer rate subsidies obscure true cost differentials.
Supply Chain Analysis
Just-in-time securitization pipelines dominate automotive finance, with lenders minimizing warehouse facility exposure through rapid onward sale to institutional ABS investors rather than strategic balance-sheet stockpiling. Capital concentration centers on Germany, the United States, and Japan, where captive finance headquarters cluster around OEM engineering centers and dealership networks. Funding draws from institutional ABS markets, central bank repo facilities, and manufacturer liquidity backstops. Single-source vulnerability concentrates in credit scoring data providers and residual value forecasting vendors. Distribution runs through dealer floorplan networks, direct-to-consumer digital channels, and fleet procurement master lease agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive finance sits at a high-growth disruption inflection as embedded vehicle connectivity and battery-electric fleet procurement force reconstruction of collateral risk frameworks around real-time telematics rather than static depreciation tables.
For Market Incumbents: Shield residual value exposure by embedding battery health monitoring clauses into electric vehicle lease contracts and consolidating telematics data partnerships before independent fintech platforms capture fleet underwriting relationships. Prioritize certification investment in ISO 22241 AdBlue programs to maintain manufacturer-backed contract eligibility against secondary lender encroachment. For New Entrants and Emerging Players: Differentiate on subscription-to-ownership conversion models targeting pre-loan-eligible mobility-as-a-service customers in India's PLI scheme corridors and China's tier-one city subscription markets. White-space concentration sits in used electric vehicle financing for certified pre-owned programs, where incumbent captives lack secondary market infrastructure. Pursue joint venture structures with domestic non-bank financial companies to bypass balance-sheet scale requirements. For Investors and Strategic Acquirers: Long-term, this sits as a data-asset play because residual value forecasting accuracy will determine lender profitability as connected vehicle telemetry displaces traditional actuarial tables. Acquisition target archetype: telematics-integrated fleet underwriters with proprietary IoT sensor partnerships and machine-learning scoring infrastructure. Watch for inflection when battery-electric vehicle lease portfolio loss-given-default assumptions stabilize.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Data Partnership Formation | Embedded IoT sensors from fleet operators enable usage-based pricing that compresses traditional fixed-rate margins. |
| Battery Supply Agreement Structuring | Lithium-ion cell procurement contracts anchor electric vehicle lease residual value assumptions and manufacturer subsidy continuity. |
| Software-Defined Vehicle Investment | Over-the-air update capabilities reshape collateral monitoring and enable dynamic contract modification. |
| Geographic Manufacturing Footprint Expansion | India's PLI scheme corridors attract foreign captive lender joint ventures with domestic non-bank financial companies. |
| Charging Infrastructure Partnership | Bundled energy-cost master lease agreements consolidate fleet procurement around total-cost-of-mobility metrics. |
Methodological Framework
Initial hypotheses were tested against primary input from captive finance executives, fleet procurement directors, dealership operations managers, and fintech platform engineers and refined through secondary validation across vehicle production databases, IHS Markit registration data, central bank securitization disclosures, and EU Consumer Credit Directive implementation reports. Bottom-up origination volume modeling triangulated against top-down ABS issuance flow analysis.
Variance decomposition across the projection horizon isolates volume, pricing, and mix effects within segmentation dimensions spanning financing type, customer archetype, service lifecycle position, and propulsion architecture. CAGRs derive from logistic diffusion curves fitted to electric vehicle fleet penetration rates and manufacturer subsidy program trajectories. Forecast inputs incorporate battery degradation curve assumptions and telematics adoption elasticity by commercial operator segment.
Material uncertainties — regulatory revision of Basel III risk-weighting, lithium-ion residual value volatility, and rare earth supply concentration — sit outside the modeled envelope. Forecasts reflect assumptions around subsidy program continuity and connectivity data access frameworks. Revision becomes warranted when battery-electric lease loss-given-default assumptions cross threshold stability bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Commercial Lending Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
United States Digital Lending Market
Loans and Leasing
Working Capital Loan Market
Loans and Leasing
Finance Lease Market
Loans and Leasing
United States Material Handling Leasing and Financing Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Montenegro Home Mortgage Finance Market
Loans and Leasing
Europe Car Loan Market
Loans and Leasing
Automobile Rental and Leasing Market
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
Loan Brokers Market