
 Norway Payments Market | 2026-2036
Norway Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Payments Market Analytics
Real-time settlement standards are redrawing competitive benchmarks across Norwegian digital commerce. Vipps AS leverages its domestic mobile wallet dominance to anchor person-to-person transaction volume. Nets A/S specializes in merchant acquiring infrastructure that controls point-of-sale integration across Nordic retail networks. Mastercard Inc competes through contactless tokenization protocols that extend acceptance at transit and parking terminals nationwide.
The Norway Payments sector encompasses electronic fund transfer systems, card networks, digital wallets, and account-to-account infrastructure that process consumer, commercial, and government transactions through encrypted authorization protocols. Bank transfers and e-wallets process through open application programming interfaces that enable instant settlement between depository institutions. Debit cards occupy the largest transaction volume pool among payment type segments due to Norwegian consumer preference for direct-account linkage. Merchant services within the service model dimension generate concentrated margin pools from interchange fee structures and value-added analytics. Enterprise users represent the fastest-expanding user segment as corporations adopt automated payable and receivable platforms.
Finanstilsynet enforces anti-money laundering protocols and operational resilience standards that shape product development timelines for domestic payment providers. The EU Payment Services Directive and GDPR compliance requirements from the European Data Protection Board constrain cross-border data routing and customer authentication architectures. Norway's implementation of the EEA financial services passport determines market access parameters for Swedish and Danish operators. Stakeholders must monitor forthcoming central bank digital currency consultations from Norges Bank that could restructure retail payment rails and deposit dynamics.
Market Dynamics
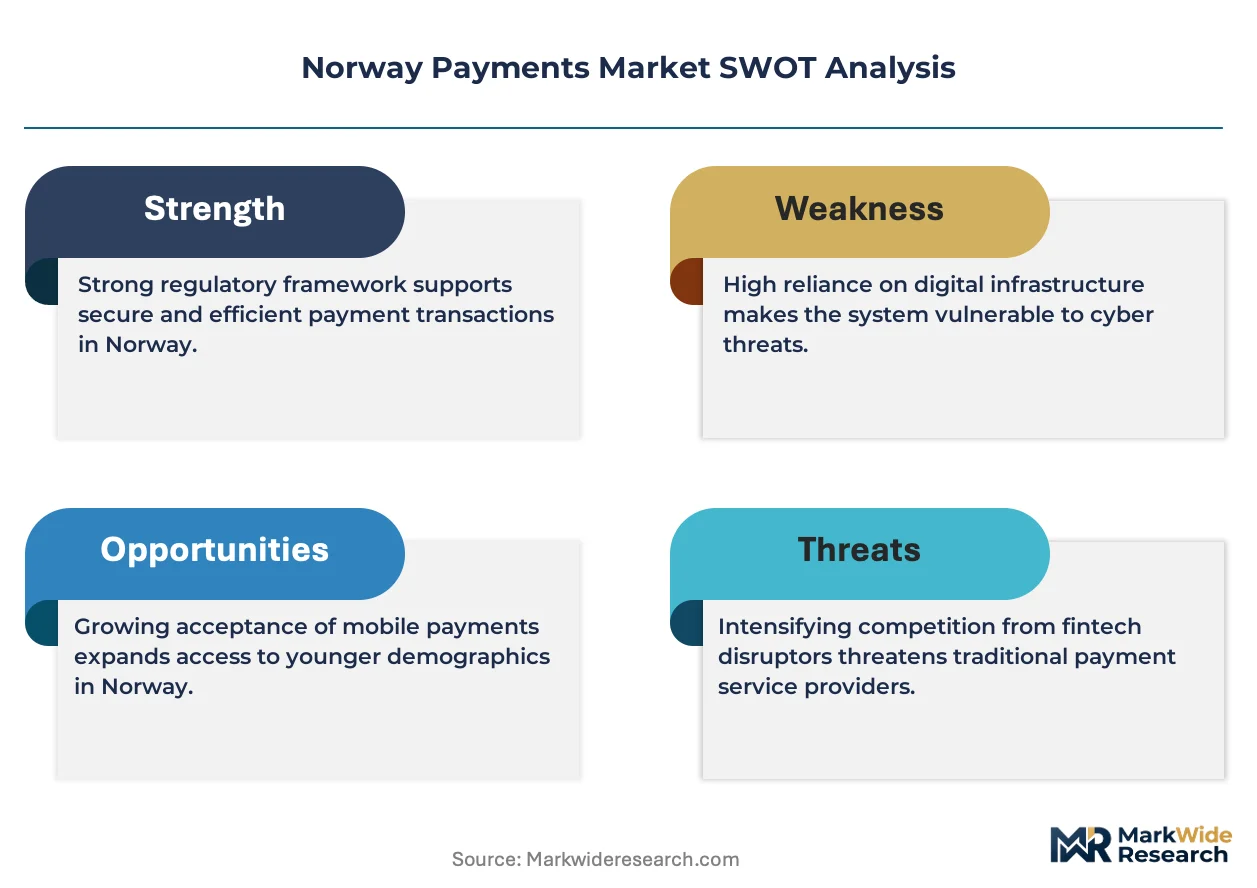
Norges Bank's real-time gross settlement infrastructure is compressing clearing cycles from T+2 to instant settlement, forcing acquirers to rebuild core processing architectures around 24/7 availability mandates.
Growth Catalysts
- Open Banking APIs:PSD2-mandated data sharing protocols enable third-party payment initiation services to embed checkout flows directly into merchant applications, bypassing traditional redirect authentication.
- Transit Sector Digitalization:Entur's nationwide ticketing platform integrates account-to-account rail payments, expanding wallet use cases beyond retail into multimodal mobility chains.
- Contactless Terminal Rollout:Norwegian merchant acquirers deploy NFC-enabled POS hardware across fuel stations and convenience stores, eliminating signature requirements for sub-NOK 500 transactions.
Market Restraints
- Interchange Rate Compression:EU interchange fee caps constrain acquirer revenue pools on domestic debit transactions, squeezing margin structures for merchant service providers.
- Data Localization Requirements:GDPR Article 44 restrictions on cross-border data transfers force payment processors to maintain Norwegian-resident transaction records, raising infrastructure duplication costs.
- Legacy Core Dependencies:Domestic banks operate on decades-old mainframe architectures that resist API-native integration, delaying real-time settlement adoption timelines.
Strategic Opportunities
- Arctic Merchant Corridors:Tromsø and Bodø logistics hubs lack integrated payment infrastructure, creating first-mover openings for mobile wallet providers serving fishing and shipping verticals.
- Request-to-Pay Protocols:EPC's SEPA Instant Credit Transfer scheme enables invoice-based push payments that displace traditional e-invoicing workflows in B2B receivables.
- Biometric Authentication Convergence:FIDO2 standards integration with BankID enables passwordless checkout flows that reduce cart abandonment rates in mobile commerce channels.
Industry Challenges
- API Talent Scarcity:Payment service providers compete for developers fluent in ISO 20022 message formats and OAuth 2.0 security frameworks, driving compensation inflation in Oslo's fintech corridor.
- Certification Bottlenecks:Finanstilsynet's operational resilience assessments impose 12-18 month licensing timelines for new e-money institutions, delaying market entry for fintech challengers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Payments Market |
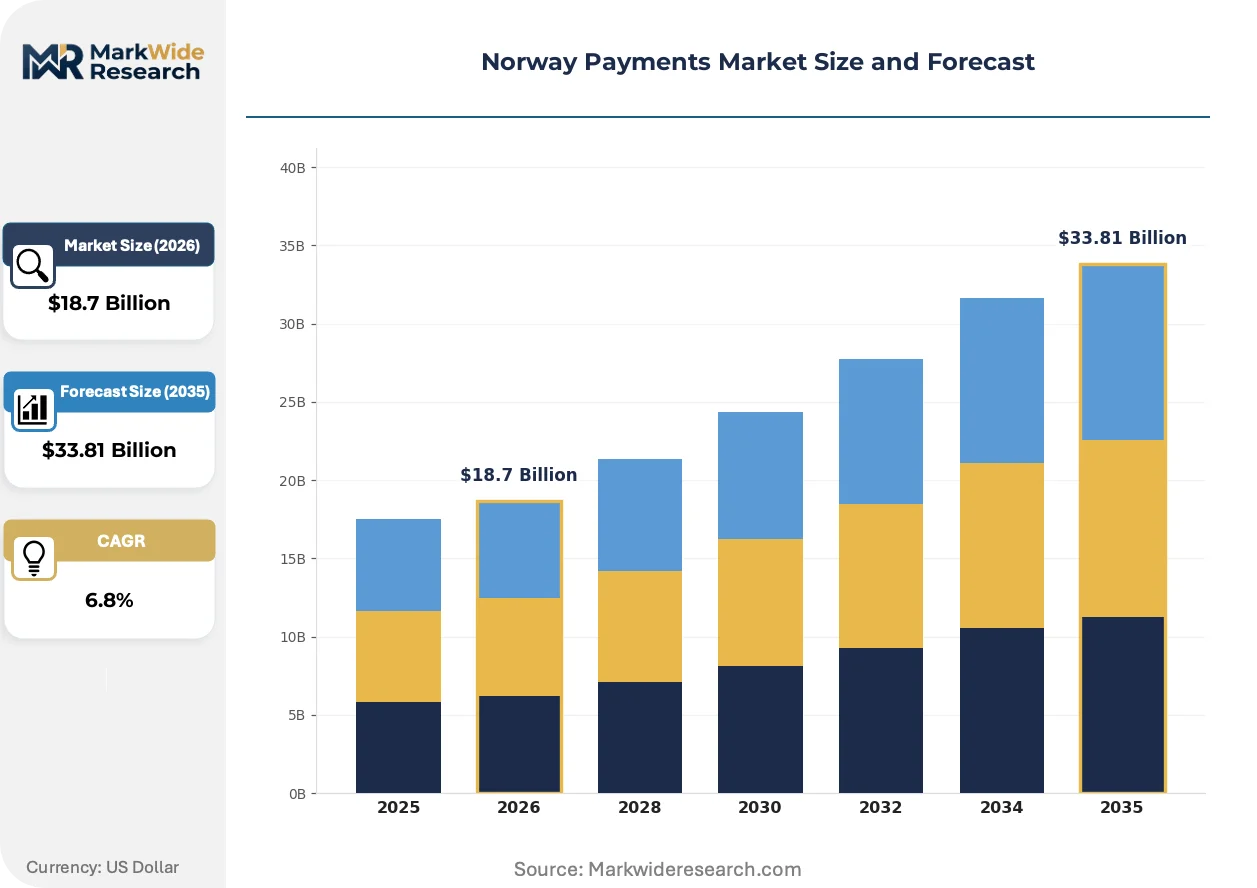
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Type: Credit Cards, Debit Cards, E-Wallets, Bank Transfers Service Model: Peer-to-Peer, Merchant Services, Payment Processing, Subscription Services Transaction Value: Micro Transactions, Small Transactions, Medium Transactions, Large Transactions User Segment: Consumers, Small Businesses, Enterprises, Government |
| Companies Covered | Visa Inc, Klarna Bank AB, Vipps AS, DNB Bank ASA, Bank Norwegian, Nets A/S, BankAxept, Nordea Bank Abp, Mastercard Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Payments Market Evolving Landscape
Tokenization architectures and embedded finance models are collapsing the distinction between banking infrastructure and commerce platforms, enabling non-financial merchants to capture payment flows natively.
Host card emulation technology is miniaturizing secure element requirements for mobile wallet provisioning. Transit authorities in Bergen and Stavanger deploy smartphone-based tap-to-ride systems without dedicated transit cards. This compression eliminates hardware issuance costs while expanding wallet penetration into occasional-use customer segments previously resistant to dedicated app downloads.
Finanstilsynet's forthcoming operational resilience framework mandates 99.99% uptime guarantees for critical payment systems. Domestic acquirers must implement geographically distributed data centers with sub-second failover capabilities. Small merchant service providers face disproportionate compliance burdens relative to their transaction volumes, accelerating consolidation toward scaled infrastructure operators.
Corporate treasury departments compress supplier payment cycles through automated payable platforms that trigger settlement upon delivery confirmation. Manufacturing and wholesale distributors in Trøndelag adopt API-connected ERP modules that replace batch-file invoicing with real-time liquidity management. This behavioral shift concentrates demand for cash-flow forecasting tools that integrate payment timing with working capital optimization.
Norway Payments Market Segmentation
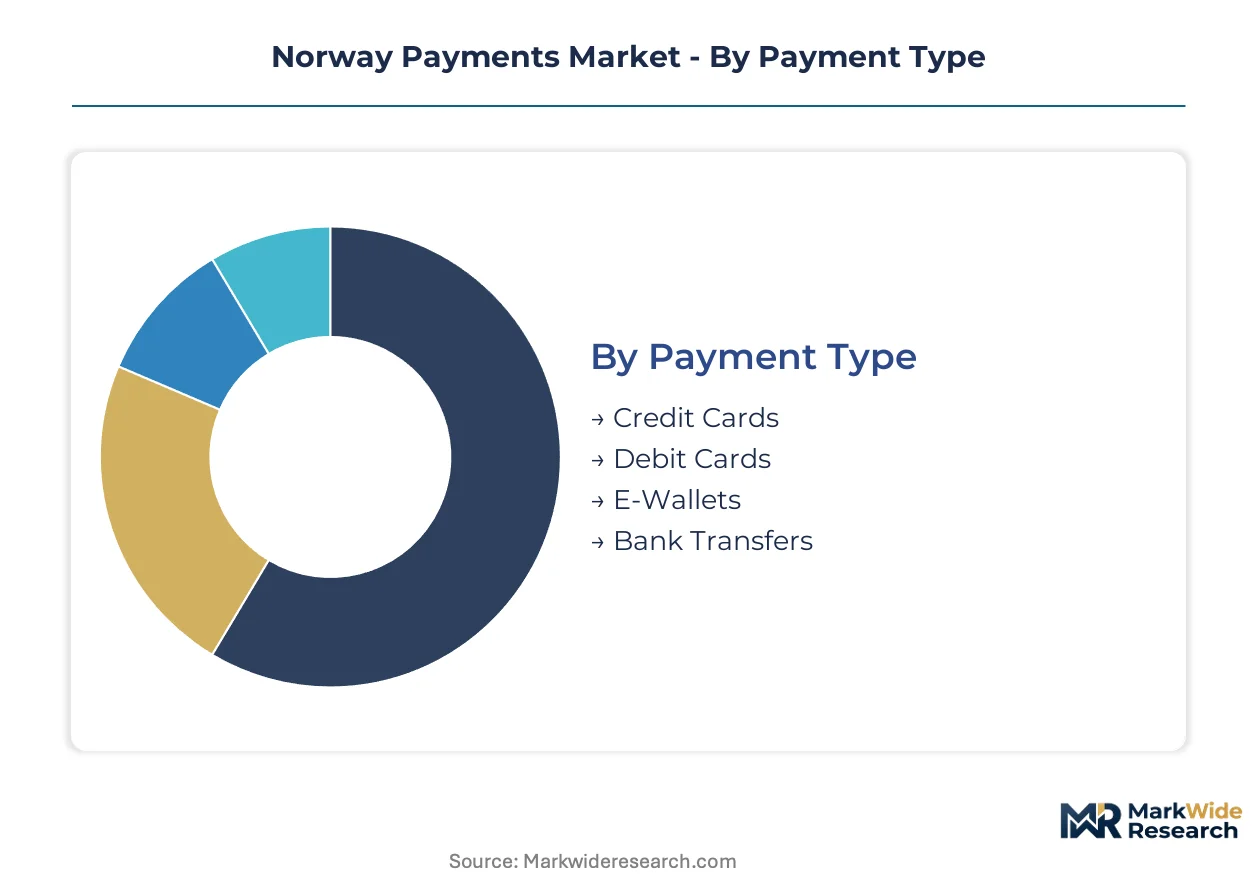
Segmentation in the Norway Payments Market reveals how transaction flows concentrate across distinct infrastructure layers. Each dimension—payment instrument, service delivery mechanism, transaction scale, and user category—commands specialized technology stacks and regulatory treatment.
Payment Type:
Channel-mix dynamics show debit and credit instruments dominating point-of-sale acceptance, while account-to-account rails capture B2B and government disbursement flows. E-wallets penetrate transit and parking verticals through tokenized mobile credentials.
- Debit Cards:Direct-account linkage through BankAxept and international scheme networks processes the largest transaction volume pool. Norwegian consumer preference for spend-what-you-have behavior concentrates demand in grocery, fuel, and pharmacy retail channels. Interchange fee caps under EU regulation constrain issuer margins on domestic transactions.
- E-Wallets:Mobile-native provisioning through host card emulation enables tap-to-pay without physical card issuance. Vipps AS anchors person-to-person volume, while transit integrations in Bergen and Stavanger expand use cases into occasional-ride customer segments. Tokenization architectures reduce fraud exposure compared to mag-stripe fallback.
- Credit Cards:Revolving credit products from domestic banks and international schemes serve travel, hospitality, and cross-border e-commerce purchases. Higher interchange rates support reward program funding.
- Bank Transfers:Account-to-account settlement through Norges Bank's real-time gross settlement infrastructure serves B2B invoices, payroll, and tax disbursements. PSD2-mandated APIs enable third-party payment initiation.
Debit cards dominate installed base. E-wallets are where expansion concentrates.
Service Model:
Margin structures vary sharply across service layers, with merchant acquiring generating concentrated fee pools while peer-to-peer services compete on user acquisition economics.
- Merchant Services:Acquirers deploy NFC-enabled terminals and value-added analytics to capture interchange-plus spreads. Nets A/S controls point-of-sale integration across Nordic retail networks. PCI-DSS compliance and Finanstilsynet operational resilience mandates raise barriers for new entrants.
- Payment Processing:Gateway and switch infrastructure handles authorization, clearing, and settlement across card and account-to-account rails. Real-time gross settlement compression from T+2 to instant cycles forces core system rebuilds around 24/7 availability.
- Peer-to-Peer:Mobile number-based routing enables instant transfers between individuals without account detail exchange. Network effects concentrate volume in dominant domestic platforms.
- Subscription Services:Recurring billing platforms manage credential-on-file transactions for SaaS, media, and utility verticals. SCA exemptions for merchant-initiated transactions reduce friction in repeat payment flows.
Merchant services command the deepest margin pools. Payment processing infrastructure is climbing the fastest as real-time mandates force capital deployment.
Transaction Value:
Authentication intensity and settlement speed requirements scale inversely with transaction size, shaping infrastructure economics across the value spectrum.
- Micro Transactions:Sub-NOK 500 contactless purchases execute without signature or PIN verification. Fuel stations and convenience stores eliminate friction for low-value, high-frequency purchases.
- Small Transactions:NOK 500-5,000 range covers routine retail, dining, and household services. Soft declines and retry logic manage authorization success rates.
- Medium Transactions:NOK 5,000-50,000 bracket includes B2B supplier payments and professional services. Request-to-Pay protocols under EPC's SEPA Instant Credit Transfer scheme displace traditional e-invoicing workflows.
- Large Transactions:Above NOK 50,000 transfers require enhanced due diligence and manual verification for anti-money laundering compliance. Real estate, vehicle purchases, and corporate acquisitions concentrate in this tier.
Small transactions dominate daily volume. Medium transactions are gaining share fastest as corporate treasuries automate payable cycles.
User Segment:
Customer sophistication and integration depth determine service packaging, with enterprises demanding API-native ERP connectivity that consumers neither need nor tolerate.
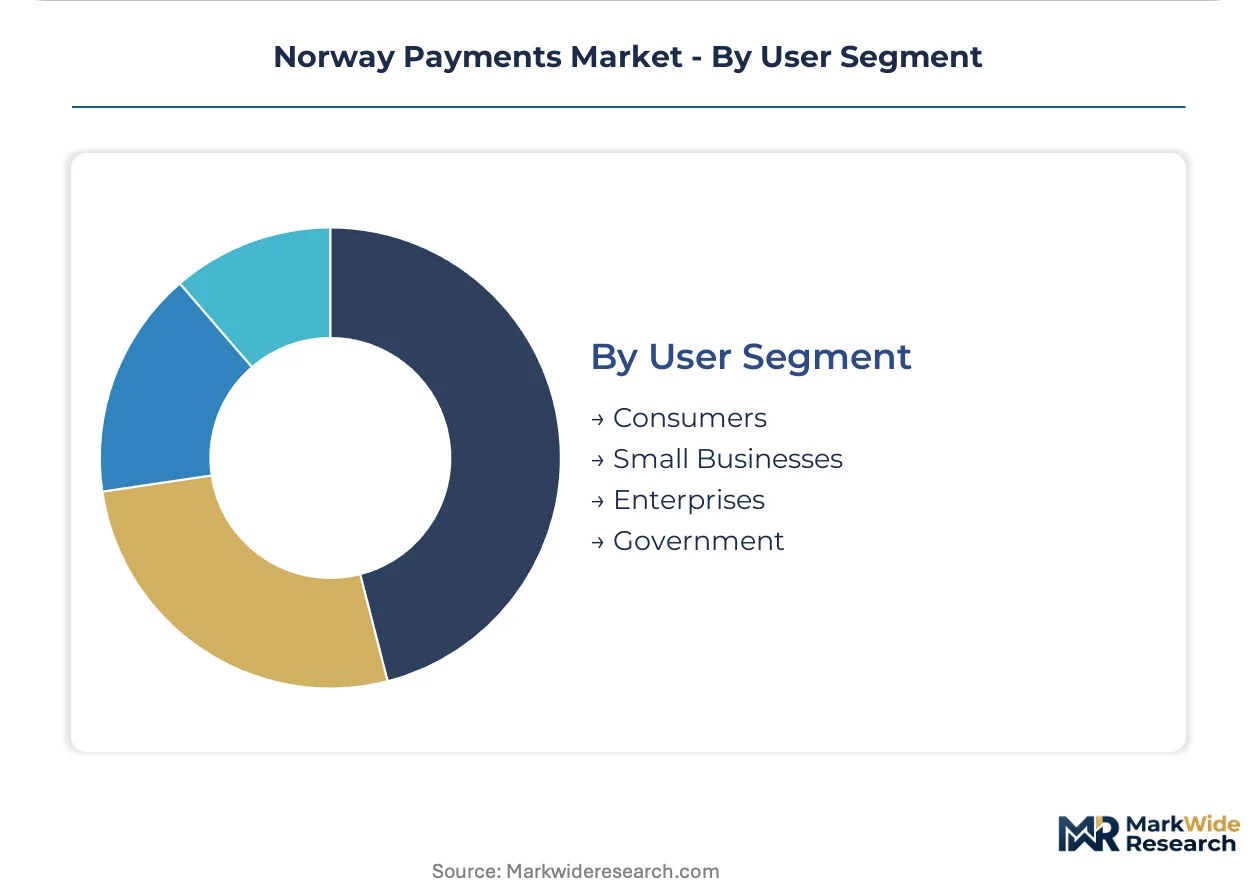
- Enterprises:Automated payable and receivable platforms integrate with SAP, Oracle, and Microsoft Dynamics environments. Manufacturing and wholesale distributors in Trøndelag adopt API-connected modules for real-time liquidity management. Cash-flow forecasting tools link payment timing to working capital optimization.
- Consumers:Mobile-first interfaces prioritize speed and simplicity over feature depth. Biometric authentication through BankID FIDO2 integration enables passwordless checkout flows.
- Small Businesses:Sole proprietors and micro-enterprises blend personal and business transaction flows, creating KYC complexity for providers. Simple invoicing and QR-code payment acceptance satisfy most requirements.
- Government:Tax refunds, benefits disbursements, and procurement payments require highest operational resilience standards. Norges Bank infrastructure ensures settlement finality for sovereign obligations.
Consumers anchor transaction count. Enterprises are where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway's payments sector maintains a modest trade surplus in financial technology services, exporting authentication protocols and merchant acquiring infrastructure to Nordic neighbors while importing specialized tokenization hardware and cloud processing capacity from Germany and the United States.
Oslo
Vipps AS anchors mobile wallet innovation from headquarters in Norway's capital, processing person-to-person transfers that displace cash circulation. Finanstilsynet's operational resilience assessments shape product development timelines for fintech challengers seeking e-money licenses. The Oslo fintech corridor concentrates API talent pools and venture funding for real-time settlement startups.
Bergen
Merchant services clusters in Norway's second city deploy NFC-enabled terminals across fuel stations and convenience stores. Nets A/S maintains point-of-sale integration infrastructure serving regional retail networks. The Bergen-Stavanger corridor drives contactless adoption in transit and parking verticals through host card emulation deployments.
Trøndelag
Corporate treasury automation concentrates in this central Norwegian region where manufacturing and wholesale distributors adopt API-connected ERP modules. Norges Bank's real-time gross settlement infrastructure enables instant supplier payments upon delivery confirmation. Trondheim's logistics hubs generate demand for cash-flow forecasting tools linked to working capital optimization.
Tromsø
Arctic merchant corridors in northern Norway lack integrated payment infrastructure, creating first-mover openings for mobile wallet providers. Fishing and shipping verticals require ruggedized terminal hardware resistant to extreme temperatures. Tromsø's port logistics generate cross-border transaction flows demanding multi-currency settlement capabilities.
Bodø
Aviation and maritime services in this northern hub drive specialized B2B payment flows for fuel bunkering and crew provisioning. Request-to-Pay protocols under EPC's SEPA Instant Credit Transfer scheme displace traditional e-invoicing workflows. Bodø's military-civilian dual-use infrastructure demands highest operational resilience standards for critical payment systems.
Norway Payments Market Competitive Landscape
Listed leaders compete with private specialists across merchant acquiring and mobile wallet distribution. The vendor base clusters around three concentration points: domestic banking conglomerates with captive payment arms, Nordic-wide infrastructure operators, and international scheme networks with tokenization protocols. Strategic archetypes include vertically integrated bank-owned processors, independent merchant acquirers, and mobile-native wallet platforms. Competitive moves center on API talent acquisition and geographic expansion into underpenetrated Arctic corridors.
Within the domestic infrastructure tier, Vipps AS exemplifies mobile-first wallet platforms that leverage network effects to concentrate person-to-person volume. Nets A/S occupies a position representing independent merchant acquirers with scaled terminal deployment capabilities. DNB Bank ASA anchors the bank-owned processor archetype, integrating payment flows with core deposit relationships. These three entities collectively illustrate how Norwegian market structure rewards first-mover positioning in real-time settlement and open banking connectivity.
| Leading Market Players |
|---|
| Visa Inc |
| Klarna Bank AB |
| Vipps AS |
| DNB Bank ASA |
| Bank Norwegian |
| Nets A/S |
| BankAxept |
| Nordea Bank Abp |
| Mastercard Inc |
| Others |
Value Network & Pricing Analysis
Host card emulation's displacement of dedicated secure elements redraws procurement geography for Norwegian payment terminals while compressing hardware margins across Nordic acquirer networks. This substitution shifts supplier leverage from semiconductor foundries toward software-integrating terminal OEMs, simultaneously enabling cloud-native pricing models that undercut legacy device economics.
Pricing Analysis
Industrial OEM buyers anchor interchange-plus pricing structures across Norwegian merchant acquiring, with acquirers layering value-added analytics fees atop scheme-mandated interchange floors. Price differentiation rests on PCI-DSS certification tier and terminal deployment volume, with fuel station chains commanding spread compression unavailable to independent grocers. Pricing pressure stems from EU interchange caps squeezing domestic debit margins, forcing acquirers to recover revenue through software subscription tiers. Small merchants exhibit highest price sensitivity, while enterprise retail networks negotiate dedicated pricing through multi-year terminal refresh commitments.
Supply Chain Analysis
Inventory cycles for NFC-enabled POS hardware stretch 8-14 weeks from Taiwan and China assembly facilities, with Norwegian terminal distributors buffering stock in Oslo and Bergen logistics hubs. Taiwan Semiconductor Manufacturing anchors chip supply for secure elements and contactless controllers, while Chinese contract manufacturers handle final device integration. Single-source vulnerability concentrates in EMV kernel licensing from international scheme providers. Distribution runs through Nets A/S terminal leasing programs and independent value-added reseller networks serving regional merchant clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's payments sector enters a cyclical recovery phase as Norges Bank's real-time settlement infrastructure drives replacement demand for legacy core banking systems. Corporate treasury automation and transit sector digitalization provide the demand foundation for this upswing.
For Market Incumbents: Shield merchant acquiring margins by deepening API-native ERP integrations with Trøndelag manufacturing distributors before open banking challengers capture automated payable workflows. Prioritize certification investment in Finanstilsynet's forthcoming operational resilience framework to create licensing barriers against fintech entrants. Terminal deployment density in Bergen-Stavanger transit corridors offers defensive moat construction against mobile wallet disintermediation.
For New Entrants and Emerging Players: Lead with Arctic corridor specialization in Tromsø and Bodø, where fishing and shipping verticals lack integrated payment infrastructure and incumbent terminal coverage remains sparse. Target B2B Request-to-Pay protocols displacing traditional e-invoicing in corporate treasury departments. Go-to-market leverage rests on ruggedized hardware partnerships addressing extreme-temperature operational requirements unique to northern logistics hubs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed merchant acquirers holding concentrated Nordic terminal fleets but lacking real-time settlement API capabilities. Long-term viability over a five-to-ten year horizon hinges on open banking infrastructure ownership rather than transaction volume aggregation. Monitor Norges Bank central bank digital currency consultations as inflection signal that could restructure deposit dynamics and retail payment rail economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Settlement API Development | Enables 24/7 transaction processing aligned with Norges Bank infrastructure mandates. |
| Arctic Corridor Terminal Deployment | Captures first-mover position in Tromsø and Bodø logistics hubs before incumbent expansion. |
| BankID FIDO2 Biometric Integration | Reduces cart abandonment through passwordless checkout flows in mobile commerce channels. |
| Request-to-Pay Protocol Implementation | Displaces traditional e-invoicing workflows under EPC's SEPA Instant Credit Transfer scheme. |
| Operational Resilience Certification | Secures Finanstilsynet licensing advantage as 99.99% uptime mandates raise compliance barriers. |
Research Methodology
Operator-level perspectives from payment platform architects, merchant acquiring executives, Finanstilsynet regulatory leads, and corporate treasury managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through Norges Bank settlement statistics, EU PSD2 implementation reports, and Nordic payment scheme disclosures. Bottom-up transaction volume modeling triangulated against top-down infrastructure capacity assessments across the analysis window.
Sensitivity analysis tested forecast robustness across interchange rate compression scenarios and real-time adoption curve variations. Segmentation dimensions modeled include payment instrument type, service delivery mechanism, transaction value tier, and user segment sophistication, with additional weighting for open banking API maturity. CAGRs derived from infrastructure deployment timelines and merchant terminal refresh cycles, incorporating PSD2-mandated data sharing protocol diffusion rates.
Forecasts assume regulatory continuity in EU Payment Services Directive and GDPR enforcement regimes; material policy shifts would require re-modeling. Central bank digital currency consultations from Norges Bank represent specific revision trigger. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
In-Vehicle Payment System Market
Payments
United States Payments Market
Payments
India Buy Now Pay Later Services Market
Payments
Japan Mobile Payments Market
Payments
Cash Management System Market
Payments
Canada Prepaid Cards Market
Payments
Enterprise Payment Software Market
Payments
Consumer Mobile Payment Market
Payments
Forex Cards Market
Payments
Canada Mobile Payments Market
Payments
Payment Orchestration Platform Market
Payments
Netherlands Mobile Payments Market
Payments
Saudi Arabia Payments Market
Payments
Mobile Payment Data Protection Market
Payments
Blockchain Payments Software Market
Payments
Brazil Real Time Payments Market