
 E-KYC Market | 2026-2036
E-KYC Market Size, Share, and Industry Trends Forecast 2026-2036
E-KYC Market Intelligence
India is narrowing the gap between regulatory mandate and technical deployment for remote identity verification. Trulioo leverages its global data network to sustain cross-border verification scale. Sumsub anchors its position through document verification specialization across high-risk jurisdictions. Onfido competes on AI-powered liveness detection that differentiates synthetic identity fraud from legitimate applicants.
Electronic Know Your Customer refers to the digital verification of individual identity through automated document analysis, biometric matching against government databases, and real-time risk scoring against watchlists. The process replaces physical branch visits with API-orchestrated checks using OCR-extracted data fields, facial geometry comparison, and device fingerprinting to establish trust in remote commercial relationships. AI-based solutions are capturing disproportionate R&D investment as neural architectures improve accuracy on low-quality document images and edge-case demographics. Banking applications dominate transaction volume, though cryptocurrency on-ramps represent the fastest-expanding addressable base as exchanges face intensified AML enforcement. Biometric authentication concentrates margin pools where hardware-software integration creates switching costs for enterprise clients.
The Reserve Bank of India mandates video-KYC protocols, while the EU's AMLD6 framework tightens beneficial ownership verification standards for financial institutions. The US Treasury's FinCEN rules extend customer due diligence to virtual asset service providers, reshaping product roadmaps for domestic vendors. Stakeholders must monitor divergence between privacy-preserving biometric standards and law enforcement access demands as jurisdictions calibrate competing policy priorities.
Market Dynamics
Video-based authentication protocols mandated by India's RBI are compressing deployment timelines across Southeast Asian banking networks, forcing vendors to rearchitect liveness detection pipelines for low-bandwidth environments.
Growth Catalysts
- AML Enforcement Intensification:FinCEN rules extending customer due diligence to virtual asset service providers are forcing cryptocurrency exchanges to deploy automated verification stacks.
- Biometric Hardware Cost Curves:CMOS sensor commoditization is enabling tier-2 banks in Indonesia and Vietnam to adopt facial geometry matching previously limited to top-tier institutions.
- API-First Architecture:Open banking frameworks in Singapore and Thailand are standardizing real-time identity verification as a core infrastructure layer for fintech orchestration.
Market Restraints
- Document Image Quality Variance:Low-resolution smartphone cameras in rural India and the Philippines introduce false rejection rates that degrade user experience and increase manual review costs.
- Data Localization Mandates:Indonesia's GR 71/2019 and Vietnam's Cybersecurity Law require biometric data storage within national borders, fragmenting vendor cloud architectures.
- Watchlist Coverage Gaps:Sanctions screening against OFAC, UN, and HMT lists lacks standardization across ASEAN member states, creating compliance blind spots for cross-border remittance providers.
Strategic Opportunities
- Microfinance Digital Onboarding:Unbanked populations in Myanmar and Cambodia represent addressable demand for lightweight KYC using national ID databases and SIM registration records.
- Insurance Policy Activation:Instant verification at point-of-sale for term life and health products is displacing paper-based agent-collected documentation in Malaysia's bancassurance channels.
- Converged Fraud Stacks:Integration of device fingerprinting with behavioral biometrics creates bundled offerings for e-commerce marketplaces combating synthetic identity abuse.
Industry Challenges
- Deepfake Detection Arms Race:Generative adversarial networks producing synthetic video submissions are forcing continuous retraining of neural liveness models, consuming R&D bandwidth.
- Legacy Core Banking Integration:COBOL-based account management systems at established Southeast Asian institutions resist API orchestration, requiring costly middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-KYC Market |
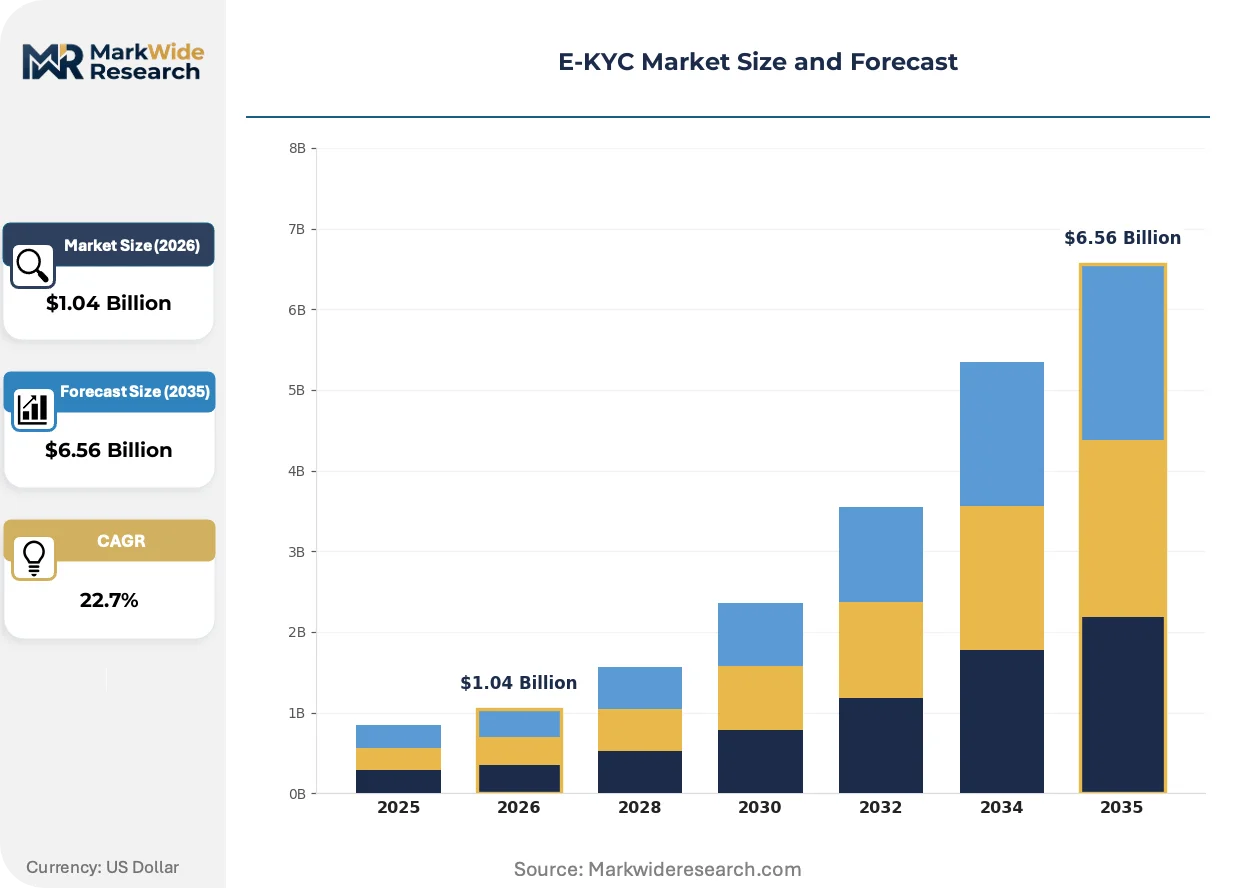
| Market Size in 2026 | $1.04 Billion |
| Market Size in 2035 | $6.56 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Banking, Insurance, Telecom, Cryptocurrency Technology: Facial Recognition, Document Verification, Biometric Authentication, AI-Based Solutions End User: Financial Institutions, Telecom Operators, Government Agencies, Online Retailers Service Type: Identity Verification, Age Verification, Risk Assessment, Fraud Detection |
| Companies Covered | Trulioo, Sumsub, IDwise, Onfido, iDenfy, FraudNet, FOCAL, Identomat, SEON, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-KYC Market Strategic Shifts & Innovations
Neural architectures trained on low-quality document images are compressing the accuracy gap between premium and mid-tier verification solutions, reshaping competitive positioning across vendor tiers.
Passive liveness detection using single-frame analysis is collapsing the hardware requirements for remote identity proofing. Microfinance institutions in Bangladesh and rural India are adopting this approach to bypass dedicated depth-sensor dependencies. The structural consequence is margin compression for vendors previously differentiating on specialized camera integration.
Indonesia's GR 71/2019 data localization mandate is forcing cloud-native verification providers to establish domestic server infrastructure. This regulatory friction is advantaging local system integrators with established data center relationships. Foreign vendors are responding through joint ventures with Indonesian telecommunications operators to satisfy residency requirements.
Subscription-based verification pricing is displacing per-transaction models among high-volume fintech lenders. Neobanks in Singapore and digital lending platforms in the Philippines are negotiating unlimited-check tiers to flatten operational cost curves. This shift is most visible in markets where customer acquisition velocity outweighs marginal verification economics.
E-KYC Market Segmentation
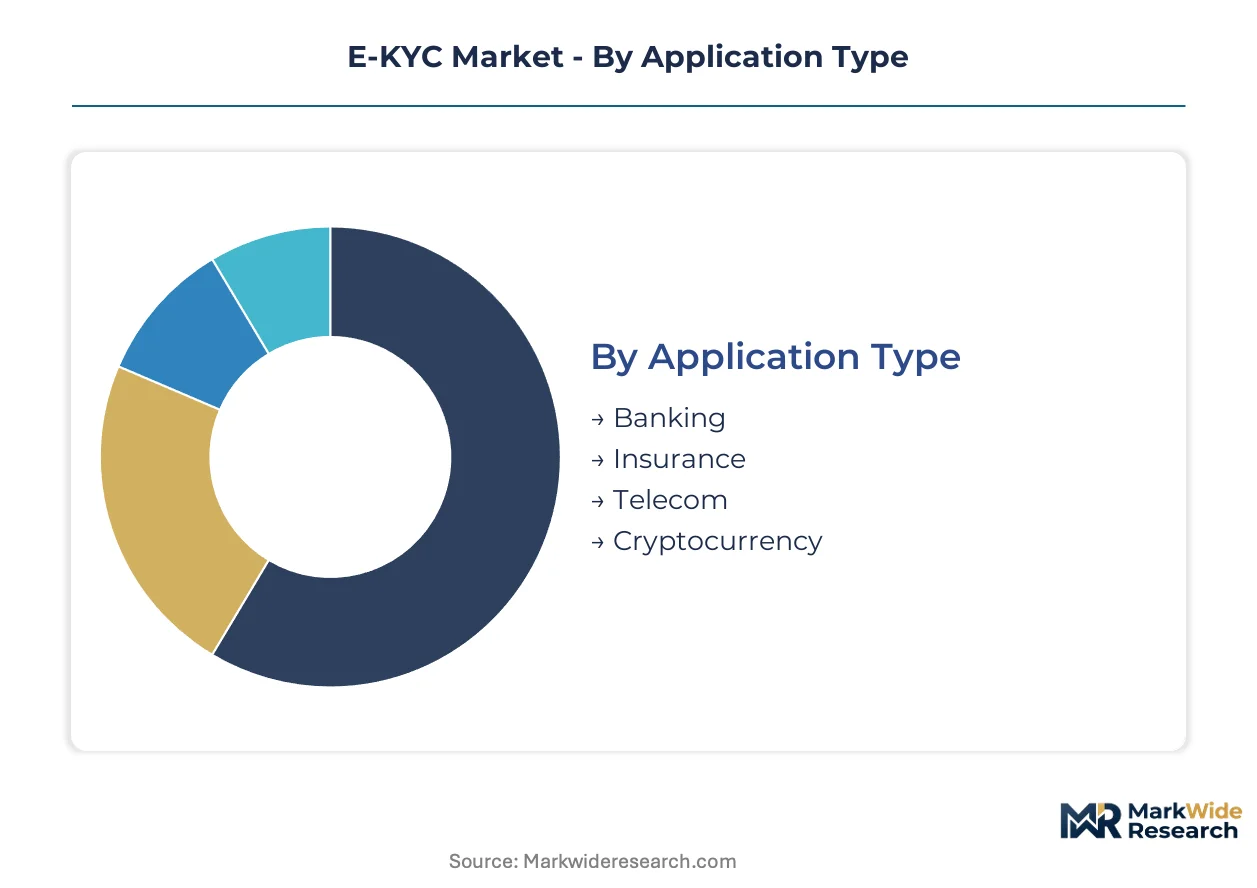
E-KYC segmentation reveals how verification workloads distribute across risk profiles and infrastructure maturity. Banking deployments demand perpetual model retraining and compliance attestation, while cryptocurrency applications prioritize speed over depth. Understanding these fault lines enables vendors to align R&D spend with margin concentration.
Application Type:
After-sales service intensity varies sharply across these verticals, with banking clients requiring continuous model updates and regulatory attestation cycles that consume vendor operational bandwidth.
- Banking:Document verification pipelines process national ID cards, PAN cards, and utility bills against RBI-mandated video-KYC protocols. Tier-1 institutions in Mumbai and Bangalore negotiate dedicated engineering support and quarterly algorithm retraining. Regulatory audit trails and consent management frameworks drive service contract values upward.
- Cryptocurrency:Exchanges deploy lightweight verification stacks emphasizing transaction velocity over documentary depth. FinCEN compliance deadlines compress deployment timelines, yet per-user support demands remain minimal once API integration completes. Margin structures favor volume-scaled pricing over premium service tiers.
- Insurance:Bancassurance channels in Malaysia activate policies through instant verification at point-of-sale, displacing agent-collected paper documentation.
- Telecom:SIM registration drives bulk verification contracts with standardized document templates and reduced exception-handling overhead.
Banking holds the largest share; momentum sits with cryptocurrency as AML enforcement tightens.
Technology:
Cost tier stratification separates hardware-dependent modalities from software-native approaches, with facial recognition commanding premium pricing due to sensor integration requirements.
- AI-Based Solutions:Neural architectures trained on low-quality document images narrow accuracy gaps between premium and mid-tier offerings. Passive liveness detection using single-frame analysis collapses hardware dependencies for rural microfinance deployments in Bangladesh and India. Continuous retraining against generative adversarial threats consumes disproportionate R&D investment.
- Facial Recognition:CMOS sensor commoditization enables tier-2 Indonesian and Vietnamese banks to adopt facial geometry matching previously limited to top-tier institutions. Hardware-software integration creates switching costs that protect vendor margin pools.
- Document Verification:OCR-extracted data fields power API-orchestrated checks against government databases, with accuracy variance across smartphone camera quality tiers.
- Biometric Authentication:Fingerprint and iris modalities concentrate in government identity programs with dedicated enrollment infrastructure.
Facial recognition dominates transaction volume; AI-based solutions are climbing the fastest as neural architectures improve edge-case handling.
End User:
Customer type determines procurement sophistication, with financial institutions negotiating enterprise frameworks while government agencies mandate data localization and domestic infrastructure.
- Financial Institutions:Neobanks in Singapore and digital lending platforms in the Philippines negotiate unlimited-check subscription tiers to flatten operational cost curves. Open banking frameworks standardize real-time identity verification as core infrastructure. Procurement teams prioritize API latency and exception-handling SLAs over per-transaction pricing.
- Government Agencies:Indonesia's GR 71/2019 and Vietnam's Cybersecurity Law require biometric data storage within national borders, fragmenting vendor cloud architectures. Domestic system integrators with established data center relationships capture procurement preference.
- Telecom Operators:SIM registration mandates drive bulk verification contracts with standardized exception-handling protocols.
- Online Retailers:E-commerce marketplaces deploy converged fraud stacks integrating device fingerprinting with behavioral biometrics.
Financial institutions command the largest contract values; government agencies are expanding most quickly as data localization mandates proliferate.
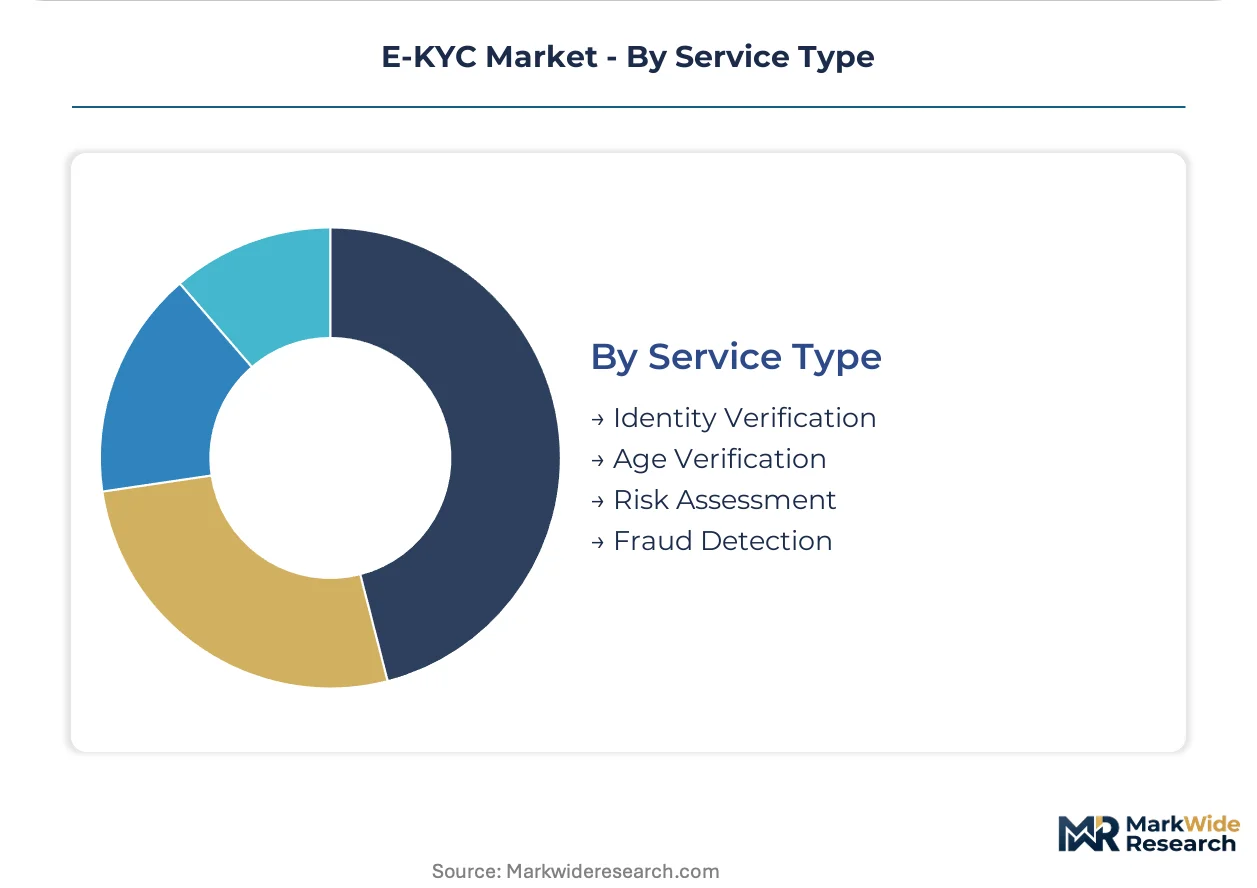
Service Type:
Margin concentration follows risk assessment depth, with fraud detection commanding premium pricing due to continuous model retraining requirements against evolving attack vectors.
- Fraud Detection:Synthetic identity abuse and deepfake video submissions force continuous neural model retraining, consuming vendor R&D bandwidth. Device fingerprinting integration creates bundled offerings for e-commerce marketplaces. Perpetual adaptation to generative adversarial threats justifies subscription pricing over transactional models.
- Identity Verification:API-orchestrated document analysis and biometric matching establish trust in remote commercial relationships. Banking applications dominate volume, though deployment complexity varies across legacy core banking integration challenges.
- Age Verification:Gaming and alcohol e-commerce drive regulatory compliance demand with standardized document templates.
- Risk Assessment:Watchlist screening against OFAC, UN, and HMT lists lacks ASEAN standardization, creating compliance blind spots for cross-border remittance providers.
Identity verification holds the largest share; fraud detection is gaining share fastest as synthetic identity attacks intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes E-KYC verification through RBI-mandated video protocols that compress deployment timelines, while Indonesia and Vietnam prioritize biometric hardware cost curves for tier-2 banking expansion. Southeast Asian markets fragment between high-bandwidth urban corridors and low-bandwidth rural deployments.
India
The Reserve Bank of India's video-KYC mandate drives banking digitization across Mumbai and Bangalore's fintech corridor. RBI protocols require real-time liveness detection against government databases, forcing vendors to rearchitect pipelines for low-bandwidth rural penetration. Maharashtra and Karnataka host concentrated neobank procurement teams negotiating unlimited-check subscription tiers.
Indonesia
GR 71/2019 data localization requirements fragment cloud architectures for biometric storage. The central bank's digital banking licensing framework accelerates tier-2 institution adoption of CMOS-commoditized facial geometry matching. Jakarta and Surabaya anchor domestic system integrator relationships with established data center infrastructure.
Vietnam
The Cybersecurity Law mandates biometric data residency within national borders, advantaging local vendors with domestic server infrastructure. State Bank of Vietnam guidelines on remote customer verification drive document-image quality investments for rural smartphone penetration. Ho Chi Minh City concentrates fintech orchestration platforms integrating open banking APIs.
Singapore
Monetary Authority of Singapore open banking frameworks standardize real-time identity verification as core infrastructure. The city-state's digital banking license regime attracts neobanks negotiating API latency SLAs over per-transaction pricing. Singapore anchors regional headquarters for vendors serving ASEAN cross-border remittance compliance.
Philippines
Bangko Sentral ng Pilipinas digital lending regulations compress onboarding timelines for unbanked populations. SIM registration mandates drive bulk verification contracts with standardized exception-handling protocols. Metro Manila and Cebu host microfinance institutions adopting passive liveness detection to bypass depth-sensor dependencies.
E-KYC Market Key Industry Players
Capability concentration sits with specialized document verification and AI-powered liveness detection vendors; scale advantage sits with global data network operators sustaining cross-border verification throughput. The market structures around three tiers: premium-tier providers with dedicated engineering support, mid-tier vendors competing on neural architecture accuracy, and regional specialists navigating data localization mandates. Dominant competitive moves include strategic partnerships with telecommunications operators and subscription-based pricing displacement of per-transaction models.
Within the global data network tier, Trulioo occupies a position exemplifying cross-border verification scale. Document verification specialists include Sumsub, representing the archetype of high-risk jurisdiction focus. AI-powered liveness detection capabilities anchor Onfido within the premium tier for synthetic identity fraud differentiation. These three vendors collectively illustrate the competitive fault lines between geographic coverage depth, regulatory specialization, and biometric technology advancement.
| Leading Market Players |
|---|
| Trulioo |
| Sumsub |
| IDwise |
| Onfido |
| iDenfy |
| FraudNet |
| FOCAL |
| Identomat |
| SEON |
| Others |
Cost & Logistics Intelligence
Singapore-Jakarta fiber routes carry latency-sensitive API traffic that compresses pricing power for cloud-native verification vendors while amplifying margin pools for domestic system integrators with established data center relationships in Indonesia and Vietnam.
Pricing Analysis
Long-term enterprise contracts anchor revenue for tier-1 banking clients in Mumbai and Bangalore, while subscription-based unlimited-check tiers displace per-transaction models among high-volume fintech lenders in Singapore and the Philippines. Price differentiation stems from API latency SLAs and dedicated engineering support commitments, with premium tiers commanding threefold multiples over standard API access. Cost compression in mid-tier facial recognition modules is intensifying because CMOS sensor commoditization collapses hardware dependencies. Neobanks exhibit lowest price sensitivity due to customer acquisition velocity priorities; rural microfinance institutions in Bangladesh and Cambodia remain most price-constrained.
Supply Chain Analysis
Extended payment terms from Indonesian telecommunications operators are restructuring cash flow dynamics for foreign verification vendors establishing domestic server infrastructure under GR 71/2019 mandates. Hardware concentration centers on China, South Korea, and Taiwan for CMOS sensors and edge AI chips, while software development clusters in India and Singapore. The supply chain rests on NVIDIA GPU allocations for neural model training and government database API access permits. Single-source vulnerability in cloud infrastructure partnerships creates exposure for vendors without multi-region failover architectures. Distribution runs through direct enterprise sales teams for banking clients and channel partnerships with system integrators for government procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a switching-cost fortress where regulatory entrenchment and API integration depth create defensive moats that compound with each additional banking client deployment.
For Market Incumbents: Build data-localization compliance moats through joint ventures with Indonesian telecommunications operators and Vietnamese data center providers to preempt foreign vendor entry under Cybersecurity Law mandates. Deepen API orchestration layers for COBOL-based legacy core banking systems at established Southeast Asian institutions to heighten replacement friction. Threat vectors include passive liveness detection commoditization collapsing hardware differentiation; lever R&D toward continuous neural retraining against generative adversarial attacks. For New Entrants and Emerging Players: Myanmar and Cambodia's unbanked populations represent the most penetrable white-space for lightweight KYC using national ID databases and SIM registration records. Target microfinance digital onboarding with passive single-frame liveness detection that bypasses depth-sensor dependencies and capitalizes on low-bandwidth rural penetration. Go-to-market angle: partner with domestic system integrators in Jakarta and Ho Chi Minh City to satisfy data residency requirements without direct infrastructure investment. For Investors and Strategic Acquirers: Document verification specialists with high-risk jurisdiction regulatory specialization command scarcity premia as AML enforcement tightens across ASEAN cryptocurrency exchanges. Long-term viability hinges on neural architecture differentiation sustaining accuracy gaps as commodity solutions proliferate. Signal to watch: RBI protocol amendments mandating additional biometric modalities, which would force R&D recalibration across vendor tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Data Center Joint Venture | GR 71/2019 compliance unlocks Indonesian government procurement contracts previously closed to foreign cloud-native vendors. |
| Passive Liveness Detection Product Launch | Single-frame analysis collapses hardware requirements for rural microfinance deployments in Bangladesh and rural India. |
| Unlimited-Check Subscription Tier Introduction | Flat-fee pricing captures high-volume fintech lenders in Singapore prioritizing customer acquisition velocity over marginal verification economics. |
| Legacy Core Banking Integration Partnership | COBOL middleware layers create switching costs that protect margin pools at established Southeast Asian institutions. |
| Deepfake Detection R&D Expansion | Continuous neural retraining against generative adversarial threats sustains premium positioning as synthetic identity attacks intensify. |
Research Approach
Operator-level perspectives from neobank CTOs, digital lending platform product heads, regulatory compliance officers at tier-1 banks, and biometric system procurement leads at Indonesian telecommunications operators anchored the qualitative base. Secondary validation drew from RBI circulars on video-KYC protocols, Indonesia's GR 71/2019 implementation guidelines, State Bank of Vietnam remote verification directives, and ASEAN cross-border remittance compliance frameworks. SEC filings from publicly traded verification vendors and hyperscaler AI infrastructure capex disclosures provided quantitative anchors. Bottom-up transaction volume estimates triangulated against top-down banking digitization spend projections.
Scenario-bracketing around RBI protocol amendments, CMOS sensor cost curve trajectories, and data localization mandate proliferation shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include application type (banking, cryptocurrency, insurance, telecom), technology modality (AI-based solutions, facial recognition, document verification, biometric authentication), and end-user procurement sophistication (financial institutions, government agencies, telecom operators, online retailers). CAGRs derived from regression against banking digitization indices and cryptocurrency exchange registration velocity. Neural architecture improvement rates and biometric hardware commoditization curves served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler cloud providers entering verification-as-a-service would shift outcomes through pricing disruption and data center scale advantages. Macroeconomic deviation in Southeast Asian banking credit cycles, regulatory fragmentation in ASEAN cross-border data flows, or breakthrough advances in generative adversarial attack sophistication would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Financial Services Software Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Contract for Difference Broker Market
Financial Services
Middle East Islamic Finance Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
Smart Finance Services Market
Financial Services
Reverse Factoring Market
Financial Services
Currency Management Market
Financial Services
Source to Pay Market
Financial Services
China Trade Finance Market
Financial Services
Solar Powered ATM Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Commodity Trade Finance Market
Financial Services
Canada Credit Cards Market
Financial Services
Europe Insurance Brokerage Market
Financial Services
Saas Escrow Services Market