
 Canada Credit Cards Market | 2026-2036
Canada Credit Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Credit Cards Market Insights
Buyer concentration among Canadian credit card holders is broadening beyond traditional high-income professionals to encompass gig economy workers and digital-native consumers. Royal Bank of Canada leverages its branch network dominance to sustain portfolio growth across diversified borrower profiles. Toronto-Dominion Bank anchors its position through deep integration with Canadian mortgage and deposit relationships. Neo Financial differentiates via pure-digital onboarding and real-time rewards architecture that competes with incumbent infrastructure.
Credit cards constitute revolving unsecured credit instruments issued by chartered banks and non-bank lenders, typically featuring variable interest rates pegged to prime benchmarks, embedded chip security protocols, and interchange fee structures governing merchant acceptance. Their primary commercial purpose is to facilitate deferred consumer spending while generating interest income and transaction fee revenue for issuers. Rewards and cash back card types command the largest active portfolio share, though fintech solutions within the service model dimension are capturing the fastest application velocity among under-35 demographics. Contactless transaction methods now dominate point-of-sale volume, displacing chip-and-PIN frequency as tap limits rise and transit integration expands.
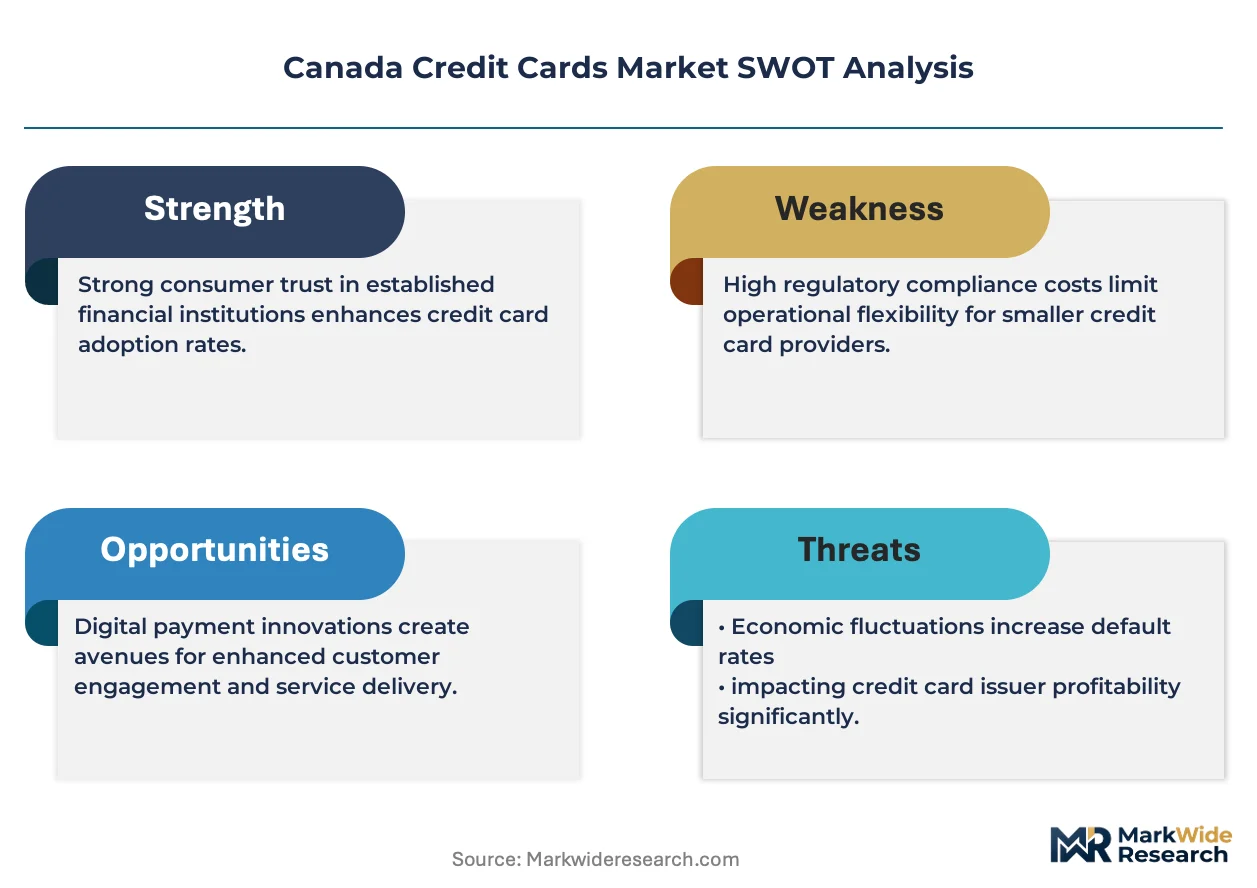
Health Canada does not directly govern credit instruments, leaving oversight to the Financial Consumer Agency of Canada and provincial securities regulators who enforce disclosure standards and fair lending practices. The Office of the Superintendent of Financial Institutions sets capital adequacy requirements that constrain issuer risk appetite and product innovation velocity. OSFI's evolving guidelines on unsecured consumer credit limits directly shape maximum exposure thresholds and underwriting automation. Stakeholders must monitor how open banking framework implementation alters data portability and issuer-switching friction across the Canadian payments ecosystem.
Market Dynamics
The Financial Consumer Agency of Canada's disclosure mandates are compressing product development cycles while open banking frameworks alter data portability rules. This regulatory compression forces issuers to rebuild transparency infrastructure ahead of compliance deadlines.
Growth Catalysts
- Transit integration:Municipal transit authorities across Ontario and British Columbia are embedding credit card tap functionality directly into fare gates. This eliminates friction for daily commuters and expands transaction frequency among urban professionals.
- FCAC disclosure mandates:The Financial Consumer Agency of Canada's standardized fee disclosure requirements are accelerating product simplification. Issuers now compete on clarity rather than hidden terms, reducing consumer switching friction.
- Gig economy payment rails:Platform workers in ride-sharing and food delivery require instant fund access. Prepaid-to-credit product bridges are capturing this segment through real-time earnings integration.
Market Restraints
- OSFI capital adequacy thresholds:The Office of the Superintendent of Financial Institutions maintains strict unsecured consumer credit limits. These requirements constrain automated underwriting velocity and maximum exposure per borrower profile.
- Interchange fee compression:Merchant acceptance costs face downward pressure from retailer associations. Small business lobbying threatens the revenue foundation of rewards-funded card programs.
- Prime rate volatility:Variable interest rate structures expose issuers to margin compression when central bank policy shifts. Borrower delinquency risk amplifies during rate hiking cycles.
Strategic Opportunities
- Alberta and Prairie provinces:These regions show lower fintech penetration relative to Ontario and British Columbia. Digital-native onboarding platforms can capture underserved borrower segments before incumbent branch networks adapt.
- Subscription management tools:Embedded spend controls for recurring payments address consumer pain points. Issuers bundling cancellation assistance and spend caps differentiate beyond raw rewards rates.
- Open banking data portability:The forthcoming consumer-directed finance framework enables seamless account switching. First movers in consent-based data sharing will reduce customer acquisition costs.
Industry Challenges
- Legacy core system migration:Mainframe-dependent issuers face multi-year timelines to enable real-time rewards and instant issuance. Cloud-native competitors exploit this capability gap.
- Fraud model recalibration:Contactless transaction volume growth requires behavioral biometric overlays. False decline rates damage customer relationships when security thresholds misalign with legitimate spend patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Credit Cards Market |
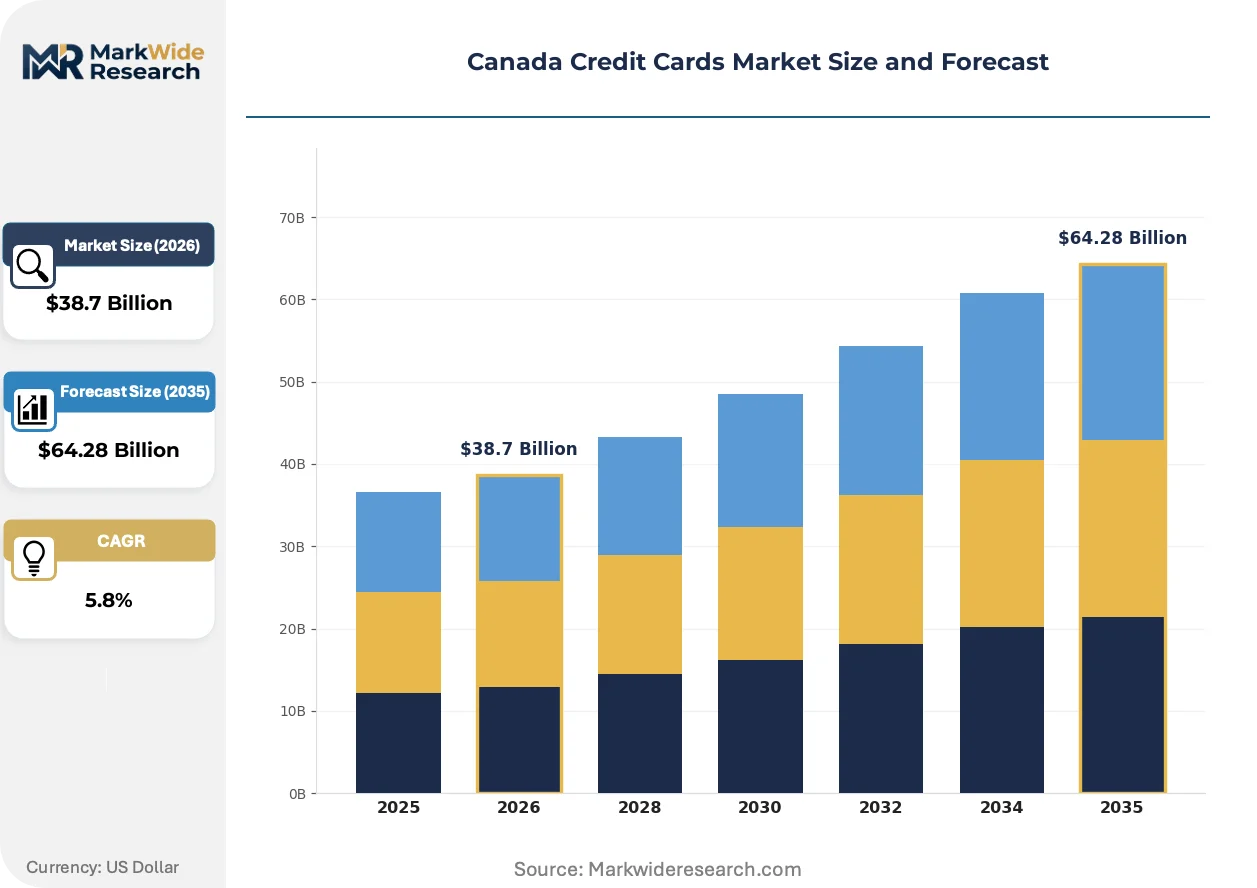
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Card Type: Cash Back, Rewards, Low Interest, Premium User Category: Students, Professionals, Families, Retirees Service Model: Online Banking, Mobile Wallet, Traditional Banking, Fintech Solutions Transaction Method: Contactless, Chip & Pin, Online Transactions, International Transactions |
| Companies Covered | Canadian Imperial Bank of Commerce, American Express, Royal Bank of Canada, Mastercard, Visa, Toronto-Dominion Bank, Bank of Montreal, Neo Financial, Scotiabank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Credit Cards Market Trends and Innovations
Real-time infrastructure is compressing the gap between transaction authorization and reward redemption. Issuers now compete on latency rather than annual percentage rates alone.
Biometric authentication is unifying physical and digital payment experiences across Canadian transit and retail networks. Younger demographics expect facial or fingerprint verification at point-of-sale terminals. This convergence eliminates password fatigue and reduces card-not-present fraud exposure for e-commerce merchants.
The Financial Consumer Agency of Canada's evolving disclosure templates are forcing product standardization across variable rate and fee structures. Issuers must rebuild marketing materials and digital interfaces to meet plain-language requirements. Smaller non-bank lenders face disproportionate compliance burdens relative to established chartered banks with dedicated regulatory teams.
Subscription spend management is displacing traditional category-based rewards as the primary card selection criterion. Digital-native consumers prioritize automated cancellation tools and merchant-specific spend controls over raw cash back percentages. This preference shift is most visible among under-35 demographics in Toronto and Vancouver, where platform subscription density exceeds national averages.
Canada Credit Cards Market Segmentation
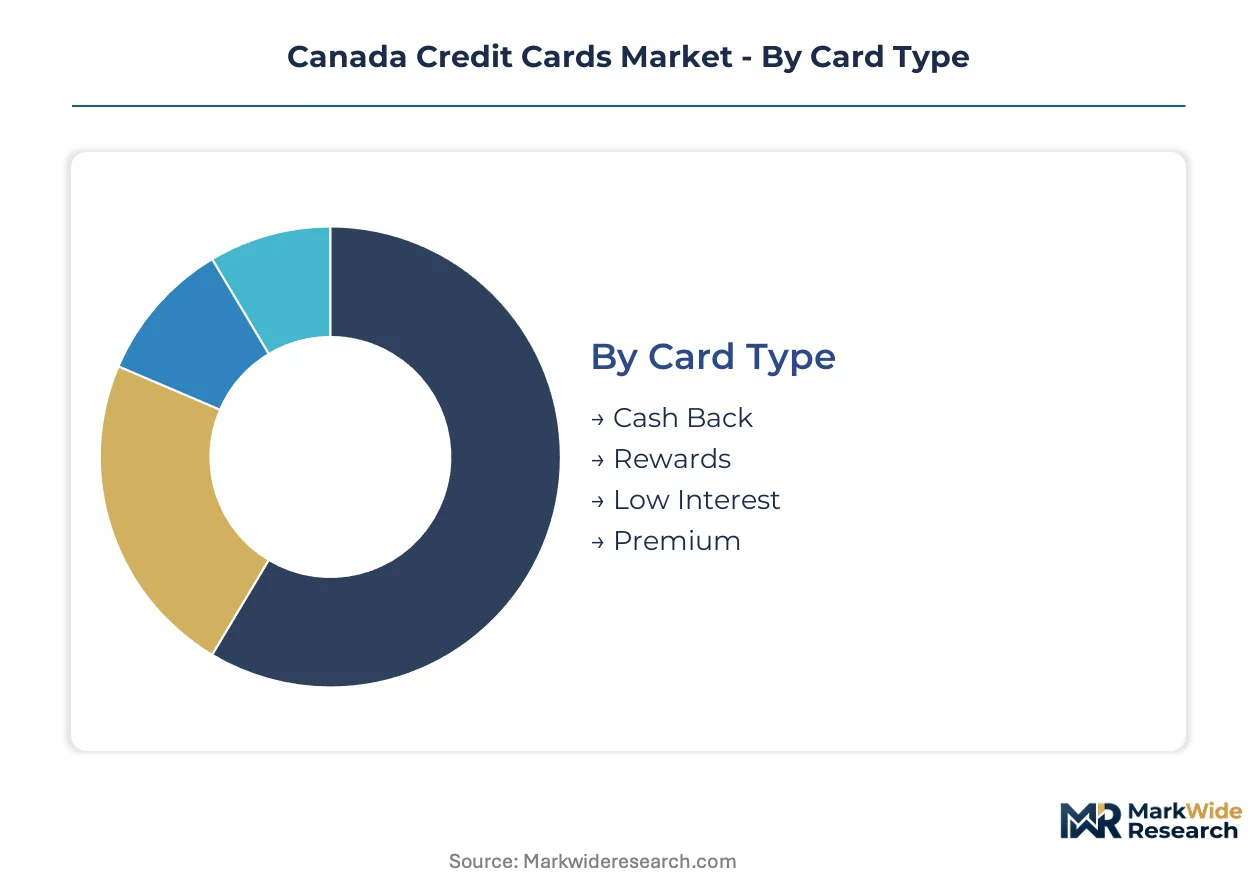
Credit card segmentation in Canada reveals how issuers architect product portfolios around distinct spending behaviors and technology preferences. Each dimension shapes underwriting automation, reward funding mechanics, and customer acquisition channel selection.
Card Type:
Cash back and rewards products operate as standalone revenue centers with dedicated marketing budgets, while low-interest and premium offerings embed within broader banking relationships to reduce churn.
- Cash Back:Flat-rate or tiered percentage returns on eligible spend dominate portfolio originations in Ontario and British Columbia. FCAC disclosure mandates compress fee complexity, forcing issuers to compete on headline earn rates rather than hidden terms.
- Rewards:Points-based programs with travel and merchandise redemption options anchor premium customer relationships. Demand concentrates among urban professionals in Toronto and Vancouver where platform subscription density exceeds national benchmarks.
- Low Interest:Products targeting debt consolidation carry compressed interchange revenue and rely on balance retention economics.
- Premium:Annual fee cards bundle insurance products and airport lounge access for high-net-worth segments.
Volume placements concentrate in Cash Back; the faster expansion belongs to Rewards.
User Category:
Segment economics vary sharply by credit bureau file thickness and income verification automation potential.
- Professionals:Stable employment records enable instant approval algorithms and highest credit limit assignments. This segment drives contactless transaction volume through transit-integrated daily commuting patterns in Montreal and Calgary.
- Students:Thin-file borrowers require co-signer frameworks or secured product on-ramps. Neo Financial and digital-native platforms capture this demographic through pure-mobile onboarding before incumbent branch networks adapt.
- Families:Multi-card household structures favor supplementary card economics and pooled reward redemption.
- Retirees:Fixed-income profiles trigger manual underwriting overrides and conservative limit assignments.
Professionals dominate current receivables; Students are climbing the fastest as fintech penetration deepens.
Service Model:
Distribution architecture determines cost-to-serve and real-time capability deployment.
- Fintech Solutions:Cloud-native infrastructure enables instant issuance and real-time rewards redemption. These platforms gain share fastest among under-35 demographics in Prairie provinces where branch density lags Ontario and British Columbia.
- Mobile Wallet:Apple Pay and Google Pay integration eliminates physical card dependency for transit and retail tap transactions. Demand concentrates in Vancouver and Toronto where merchant terminal upgrade cycles completed earliest.
- Online Banking:Web-first application flows with automated income verification reduce acquisition cost per approved account.
- Traditional Banking:Branch-mediated origination retains dominance for mortgage-bundled credit products and retiree segments.
Traditional Banking holds the largest active base; Fintech Solutions show the steepest expansion trajectory.
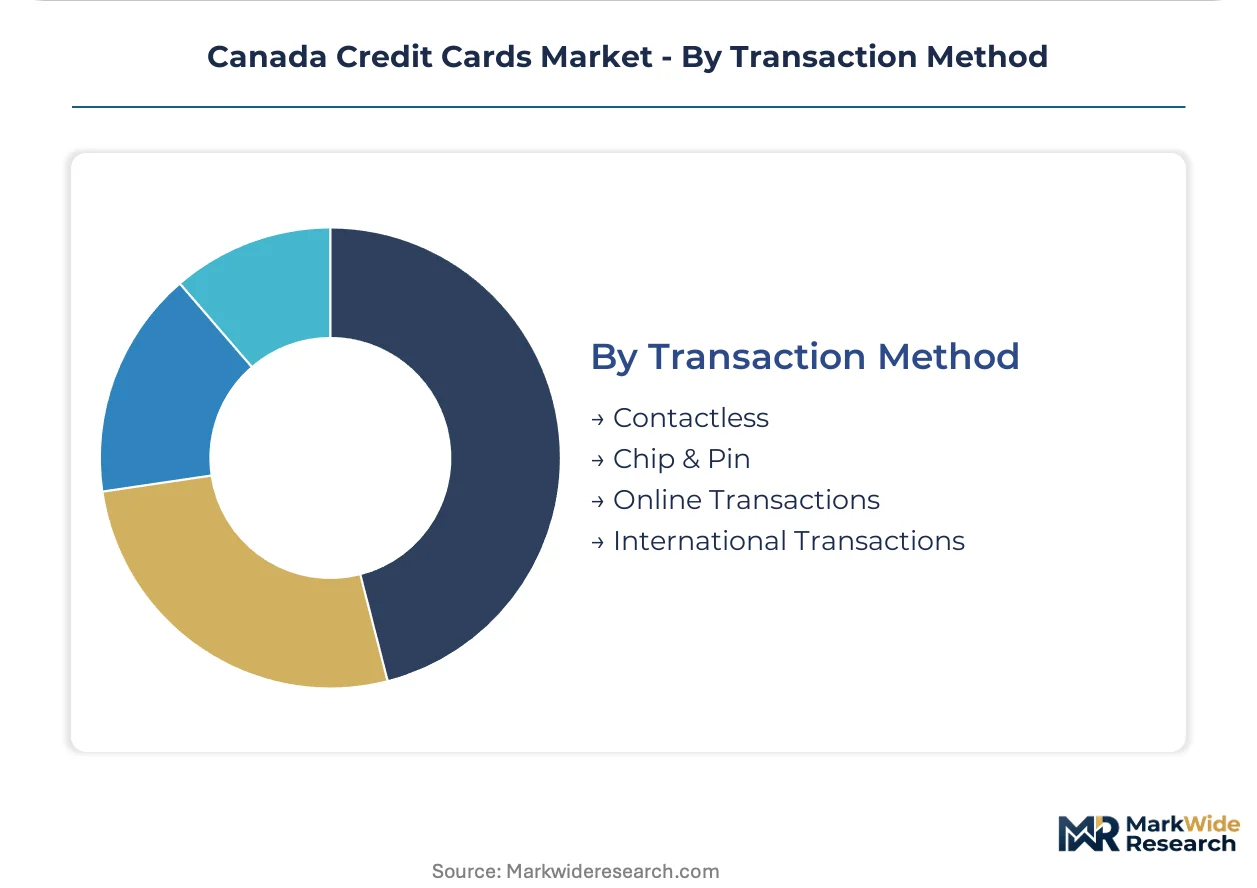
Transaction Method:
Authorization infrastructure investments follow method-specific fraud exposure and latency requirements.
- Contactless:Tap-to-pay dominates point-of-sale volume as transit integration expands across Ontario and British Columbia municipal networks. Rising tap limits displace chip-and-PIN frequency for everyday purchases.
- Online Transactions:Card-not-present volume requires behavioral biometric overlays and tokenization infrastructure. E-commerce merchant acceptance costs face downward pressure from retailer association lobbying.
- Chip & Pin:Fallback authentication for high-value transactions and merchant categories with elevated chargeback risk.
- International Transactions:Foreign exchange markup revenue funds travel reward program economics.
Contactless captures the highest transaction count; Online Transactions are expanding most quickly as subscription service density rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Ontario and British Columbia, where urban payment infrastructure and fintech penetration are deepest. The Financial Consumer Agency of Canada's disclosure mandates apply uniformly, yet regional adoption patterns diverge sharply based on transit integration and branch density.
Ontario
Toronto anchors the highest contactless transaction volume through municipal transit integration and dense merchant terminal networks. The Financial Consumer Agency of Canada's standardized fee disclosure requirements accelerate product simplification among issuers headquartered here. Royal Bank of Canada and Toronto-Dominion Bank leverage their branch network dominance to sustain portfolio growth across diversified borrower profiles in the Greater Toronto Area.
British Columbia
Vancouver exhibits the deepest fintech penetration and platform subscription density among Canadian metropolitan areas. Transit-integrated tap payments dominate daily commuting patterns, expanding transaction frequency among urban professionals. Neo Financial captures under-35 demographics through pure-digital onboarding before incumbent branch networks adapt to coastal consumer preferences.
Alberta
Calgary and Edmonton show lower fintech penetration relative to coastal provinces, creating whitespace for digital-native onboarding platforms. The Office of the Superintendent of Financial Institutions maintains uniform capital adequacy thresholds that constrain automated underwriting velocity across all provinces equally. Regional energy sector employment patterns influence borrower income verification automation potential.
Quebec
Montreal drives contactless volume through transit-integrated daily commuting patterns comparable to Toronto. Provincial securities regulators enforce disclosure standards that complement federal Financial Consumer Agency of Canada mandates. Bilingual product interfaces and marketing materials create compliance complexity distinct from other provinces.
Prairie Provinces
Manitoba and Saskatchewan present underserved borrower segments where branch density lags Ontario and British Columbia. Cloud-native platforms gain share fastest among younger demographics frustrated with legacy onboarding friction. Agricultural employment patterns and seasonal income variability trigger manual underwriting overrides more frequently than in urban centers.
Canada Credit Cards Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pure-digital disruption of branch-dependent origination. The market structure reflects a bifurcated landscape where chartered banks with legacy infrastructure compete against cloud-native challengers. Three archetypes dominate: incumbent branch networks with mortgage-bundled relationships, payment network operators controlling interchange infrastructure, and fintech platforms enabling instant issuance. Competitive moves concentrate on M&A to acquire digital capabilities and strategic partnerships to embed cards within transit and gig economy platforms.
Within the incumbent tier, Royal Bank of Canada and Toronto-Dominion Bank exemplify branch-network dominance sustained through diversified borrower relationships and deep integration with Canadian mortgage and deposit products. Among payment network operators, Visa and Mastercard occupy positions controlling the interchange fee structures that govern merchant acceptance economics. Neo Financial represents the fintech archetype, differentiating through pure-digital onboarding and real-time rewards architecture that competes directly with incumbent infrastructure constraints.
| Leading Market Players |
|---|
| Canadian Imperial Bank of Commerce |
| American Express |
| Royal Bank of Canada |
| Mastercard |
| Visa |
| Toronto-Dominion Bank |
| Bank of Montreal |
| Neo Financial |
| Scotiabank |
| Others |
Pricing and Supply Chain Analysis
FCAC disclosure mandates compressing product development cycles force issuers to rebuild transparency infrastructure ahead of compliance deadlines, elevating compliance costs and squeezing margin structures across reward-funded programs.
Pricing Analysis
High-volume interchange-funded programs subsidize low-margin premium offerings, with revenue concentration in cash back and rewards tiers. Price differentiation hinges on reward earn rates and embedded insurance bundling rather than interest rate spreads. Cost compression in merchant acceptance fees intensifies as retailer associations lobby for interchange reductions. Gig economy workers exhibit highest price sensitivity to annual fees, while high-net-worth segments prioritize concierge service tiers over raw percentage returns.
Supply Chain Analysis
Domestic-content requirements in payment network infrastructure reshape sourcing toward Canadian data residency standards. Card manufacturing draws from China, Taiwan, and South Korea for EMV chip modules and contactless antenna substrates. Supply chain risk centers on single-source vulnerability in secure element production. Distribution runs through chartered bank branch networks, direct-to-consumer digital channels, and third-party affiliate partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over real-time rewards infrastructure and transit-embedded payment rails determines competitive durability.
For Market Incumbents: Deploy cloud-native core system migration to close the latency gap with fintech challengers. Royal Bank of Canada and Toronto-Dominion Bank must accelerate instant issuance capabilities before Neo Financial captures under-35 demographics in Alberta and Prairie provinces. Deepen mortgage-bundled credit relationships to reduce churn from subscription management tools.
For New Entrants and Emerging Players: Pure-digital onboarding platforms unlock whitespace in Calgary and Edmonton where branch density lags Vancouver and Toronto. Target gig economy workers through prepaid-to-credit bridges with real-time earnings integration. Capture student segments through mobile-first application flows before incumbents adapt co-signer frameworks.
For Investors and Strategic Acquirers: The window for entry favors cloud-native fintech platforms with transit-embedded distribution partnerships. Long-term viability rests on open banking data portability readiness and consent-based switching infrastructure. Monitor FCAC compliance timeline acceleration as inflection signal for consolidation pressure on non-bank lenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Rewards Infrastructure Buildout | Cloud-native platforms reduce redemption latency to compete with incumbent mainframe constraints. |
| Transit System Integration Partnership | Municipal fare gate embedding expands transaction frequency among daily urban commuters. |
| Open Banking Consent Framework Development | First-mover data portability reduces customer acquisition costs across the analysis window. |
| Subscription Management Tool Bundling | Automated cancellation assistance differentiates beyond raw cash back percentage competition. |
| Gig Economy Payment Rail Embedding | Platform worker earnings integration captures thin-file borrowers outside traditional underwriting. |
Research Methodology
Multi-period observation of contactless transaction volume, fintech application velocity, and transit integration deployment anchored the trend analysis, supplemented by interviews with credit card product executives, FCAC compliance officers, transit authority procurement managers, and merchant acquiring specialists. Secondary validation drew from OSFI regulatory filings, Financial Consumer Agency disclosure templates, payment network interchange reports, and municipal transit authority technology procurement records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Segment-weighting across card type, user category, service model, and transaction method dimensions shaped the analytical framework. CAGRs derived from trend extrapolation adjusted for regulatory compression effects and open banking implementation timelines. Forecast inputs incorporated prime rate volatility scenarios and merchant acceptance cost trajectories.
Inputs from payment network operators and chartered bank regulatory disclosures were available through the study window; gaps in real-time fintech profitability data introduce uncertainty bands around emerging entrant market share projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Europe Insurance Brokerage Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
North America Trade Finance Market
Financial Services
China Trade Finance Market
Financial Services
Intellectual Property Valuation Market
Financial Services
Africa Factoring Services Market
Financial Services
Saas Escrow Services Market
Financial Services
India Legal Services Market
Financial Services
Global Treasury Software Market
Financial Services
Cash Flow Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
China Financial Services Software Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Reconciliation Software Market
Financial Services
Hyperinflation System Market
Financial Services
E-Brokerage Market