
 E-Brokerage Market | 2026-2036
E-Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
E-Brokerage Market Analysis
The gap between premium wealth management and zero-commission retail execution is expanding as platforms fragment by service intensity and fee architecture. Interactive Brokers leverages its global market access and margin lending infrastructure to anchor institutional-grade capabilities for sophisticated traders. Charles Schwab sustains hybrid dominance through its branch network paired with digital scale, while Robinhood competes on streamlined mobile UX and payment-for-order-flow economics.
E-brokerage denotes the electronic execution of financial securities orders through internet-based platforms, typically operating via FIX protocol connectivity, sub-second order routing, and API-accessible account management. The primary commercial purpose is to disintermediate traditional broker-dealers, compress transaction costs, and democratize market participation for non-professional capital holders. Discount brokerage and robo-advisors command the fastest expansion trajectories as fee compression and algorithmic portfolio construction displace human advisory hours; full-service segments retain margin concentration among high-net-worth cohorts demanding tax optimization and estate planning integration. Retail investor participation dominates volume generation, though institutional flow sustains platform economics through payment-for-order-flow arrangements and securities lending programs.
SEC Regulation Best Execution and FINRA suitability standards shape product availability and disclosure obligations for US-domiciled platforms, while EU MiFID II transparency requirements govern cross-border service provision. The UK's FCA consumer duty rules and Japan's FIEA amendments are extending comparable safeguards across developed jurisdictions. Stakeholders must monitor evolving payment-for-order-flow restrictions and custody asset segregation mandates as regulatory arbitrage opportunities narrow.
Market Dynamics
Payment-for-order-flow economics and SEC best-execution scrutiny are compressing revenue models while forcing platforms to differentiate through margin lending depth and API sophistication.
Growth Catalysts
- SEC Regulation Best Execution:Tighter disclosure mandates drive platform investment in order-routing transparency and execution quality analytics, raising barriers for subscale entrants.
- Mobile-first retail penetration:Smartphone-native trading interfaces in India and Brazil are onboarding first-time equity participants without legacy desktop dependencies.
- FIX protocol standardization:Sub-second connectivity protocols reduce latency costs and enable direct market access for algorithmic retail strategies previously reserved for institutional desks.
Market Restraints
- Clearing and custody concentration:Depository Trust & Clearing Corporation infrastructure dominance in the United States creates single-point systemic exposure for platform settlement operations.
- Interest rate sensitivity:Margin lending spreads and cash sweep yields compress when central bank policy rates decline, directly eroding net interest income contributions.
- Payment-for-order-flow restrictions:Proposed SEC rulemaking on order-flow compensation threatens zero-commission pricing architectures dependent on wholesale market-maker arrangements.
Strategic Opportunities
- India's demat account expansion:Regulatory push for financial inclusion and simplified KYC protocols is opening access to 140 million underbanked households seeking equity participation.
- Crypto-asset integration:Convergence of traditional securities rails with digital asset custody creates unified wallet architectures attracting cross-asset traders.
- API ecosystem monetization:Third-party developer marketplaces for algorithmic strategy deployment generate recurring SaaS revenue atop core execution volumes.
Industry Challenges
- Quantitative risk modeling talent:Shortage of practitioners capable of building real-time margin and options risk engines limits platform leverage extension.
- Multi-jurisdiction compliance layering:Simultaneous adherence to SEC, FINRA, FCA, and EU MiFID II frameworks fragments product availability and extends legal review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Brokerage Market |
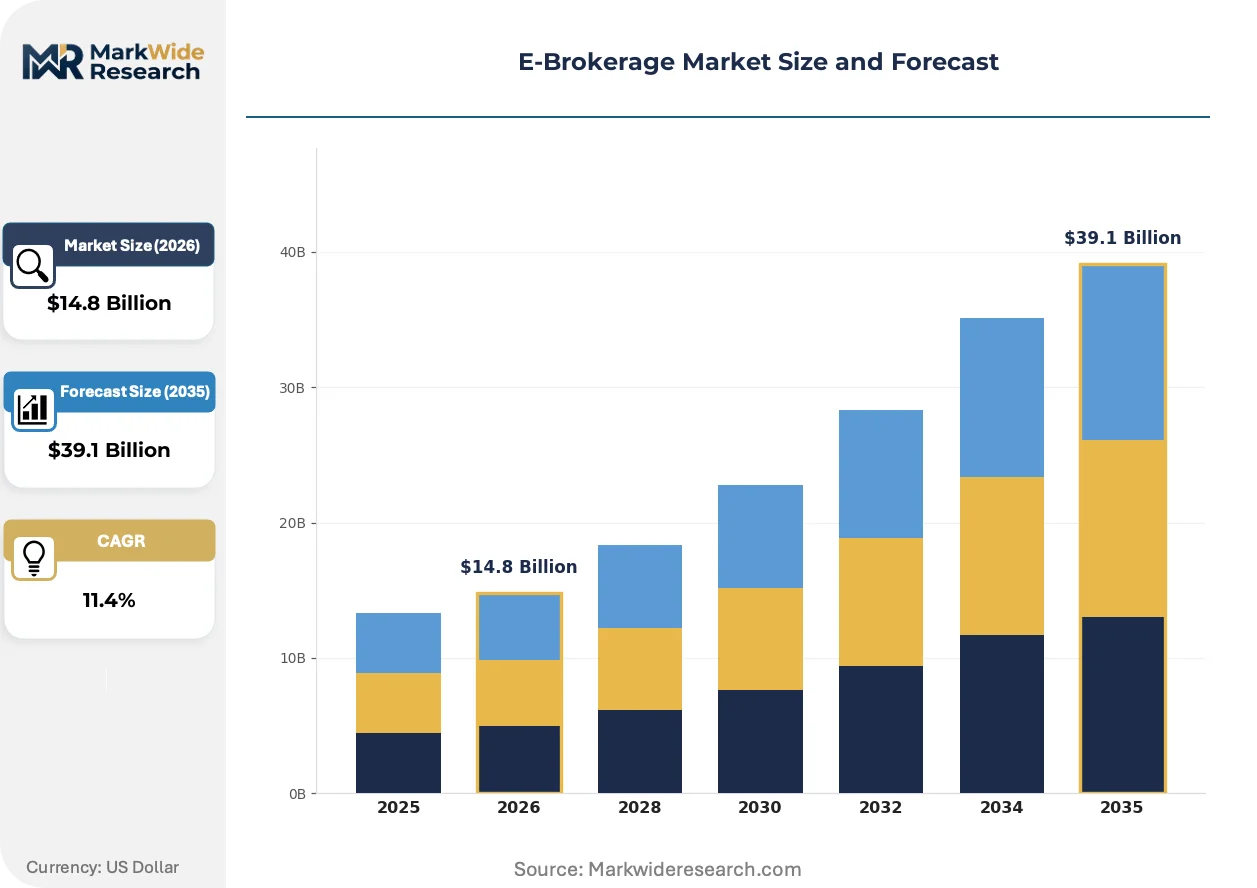
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Brokerage, Discount Brokerage, Robo-Advisors, Online Trading Customer Type: Retail Investors, Institutional Investors, Hedge Funds, Wealth Management Firms Product Type: Stocks, Bonds, Mutual Funds, ETFs Technology: Trading Platforms, Mobile Applications, Algorithmic Trading, Blockchain |
| Companies Covered | Vanguard, Interactive Brokers, Fidelity, Merrill Edge, Webull, Charles Schwab, Robinhood, SoFi, E*TRADE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Brokerage Market Emerging Trajectories
Artificial intelligence is reshaping how platforms personalize risk management and automate portfolio construction for mass-affluent segments previously served by human advisors.
Natural language processing engines are electrifying client service architectures by parsing unstructured trade intent from chat and voice inputs. Retail platforms deploy these systems to reduce ticket resolution times from hours to seconds. The compression of support costs is enabling freemium tier expansion without proportional headcount growth.
EU MiFID II transparency requirements are mandating granular cost and performance disclosure across packaged retail investment products. Asset managers must now unbundle advisory fees from product costs, shifting competitive emphasis to explicit value demonstration. European-domiciled platforms are responding by building automated cost-comparison dashboards that surface total expense ratios against peer benchmarks.
Self-directed investors are rotating from passive fund accumulation toward single-stock and options strategies, compressing platform revenue per account while elevating risk-engineering demands. Mobile interfaces now dominate initial account funding and trade placement, displacing desktop-based research workflows. This behavioral pivot is most pronounced among cohorts under 35 in the United States and South Korea, where gamified option spread builders attract speculative capital.
E-Brokerage Market Segmentation
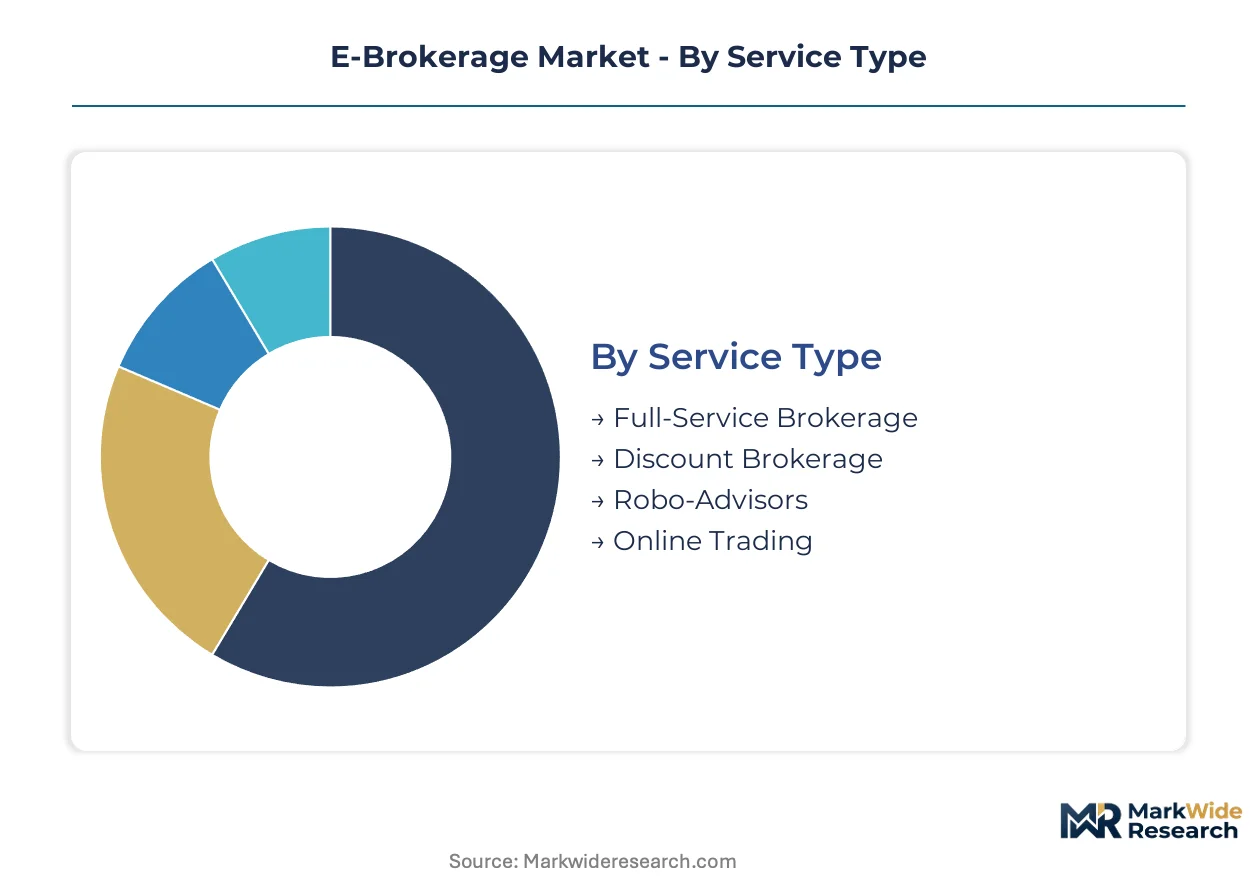
E-brokerage platforms fragment across four structural dimensions that determine capital requirements, regulatory exposure, and revenue per account. Service intensity and customer sophistication drive the steepest differences in platform economics and technology investment.
Service Type:
Capital intensity peaks in segments requiring human advisory infrastructure and proprietary research capacity rather than pure digital execution rails.
- Full-Service Brokerage:Hybrid models combining human advisors with digital tools command the highest fixed-cost bases. Demand concentrates among high-net-worth households in the United States seeking tax-loss harvesting and estate planning integration, constrained by advisor compensation inflation and compliance training overhead.
- Discount Brokerage:Zero-commission execution platforms operate on leaner cost structures with payment-for-order-flow revenue subsidizing account services. Retail participation in India and Brazil is accelerating onboarding velocity, though SEC best-execution scrutiny threatens wholesale market-maker economics.
- Robo-Advisors:Algorithmic portfolio construction reduces marginal advisory costs to near-zero. Mass-affluent millennials in the United States and United Kingdom drive subscription revenue growth.
- Online Trading:Browser-based execution interfaces without advisory overlay represent the lowest capital barrier to entry. First-time equity participants across Southeast Asia favor these stripped-down platforms.
Discount Brokerage absorbs the bulk of installed capacity; Robo-Advisors are expanding most quickly.
Customer Type:
Revenue concentration and regulatory complexity diverge sharply between unsophisticated retail flows and institutional-grade execution requirements.
- Retail Investors:Individual account holders executing self-directed strategies generate volume but thin margins per transaction. Mobile-first penetration in South Korea and Brazil is elevating options and single-stock speculation, compressing platform risk-engineering capacity.
- Institutional Investors:Pension funds and asset managers demand FIX protocol connectivity and sub-second order routing with explicit transaction cost analysis. Compliance with SEC Rule 606 disclosure mandates raises platform infrastructure investment thresholds.
- Hedge Funds:Leveraged strategies require sophisticated margin and derivatives risk engines. Prime brokerage relationships concentrate in platforms with securities lending depth.
- Wealth Management Firms:Independent advisors seeking white-label platform infrastructure drive B2B SaaS revenue streams with stickier contract terms.
Retail Investors dominate account volume generation; Institutional Investors command the steepest expansion trajectory in revenue per flow.
Product Type:
Platform technology stacks and clearing relationships vary substantially across asset class complexity and settlement infrastructure requirements.
- Stocks:Equity execution represents the foundational capability with T+1 settlement compression in the United States reducing capital tie-up. Direct indexing strategies are displacing mutual fund wrappers among taxable accounts.
- Bonds:Fixed-income trading demands fragmented dealer connectivity and inventory management systems. Institutional demand for municipal bond ladders drives customization complexity.
- Mutual Funds:Load-waived share classes on no-transaction-fee platforms face fee compression from ETF substitution. Recordkeeping infrastructure absorbs platform technology investment.
- ETFs:Exchange-traded products command the fastest product innovation cycles with thematic and leveraged structures attracting speculative retail capital.
Stocks retain the largest share of transactional volume; ETFs are climbing the fastest in product launches and platform shelf expansion.
Technology:
Platform differentiation increasingly depends on proprietary technology ownership versus third-party vendor reliance.
- Trading Platforms:Desktop and web-based execution interfaces with advanced charting and options analytics require continuous UX investment. Sophisticated traders in Germany and Japan demand multi-monitor workspace customization.
- Mobile Applications:Smartphone-native interfaces with biometric authentication and push-notification alerts dominate account funding among cohorts under 35. Gamification features attract regulatory scrutiny from the SEC and FCA.
- Algorithmic Trading:API-accessible strategy deployment enables retail participants to automate execution previously reserved for institutional desks. Python and C++ SDK availability distinguishes platform technical depth.
- Blockchain:Distributed ledger infrastructure for settlement compression and crypto-asset custody integration remains experimental. Regulatory uncertainty from the SEC and EU MiCA framework delays mainstream adoption.
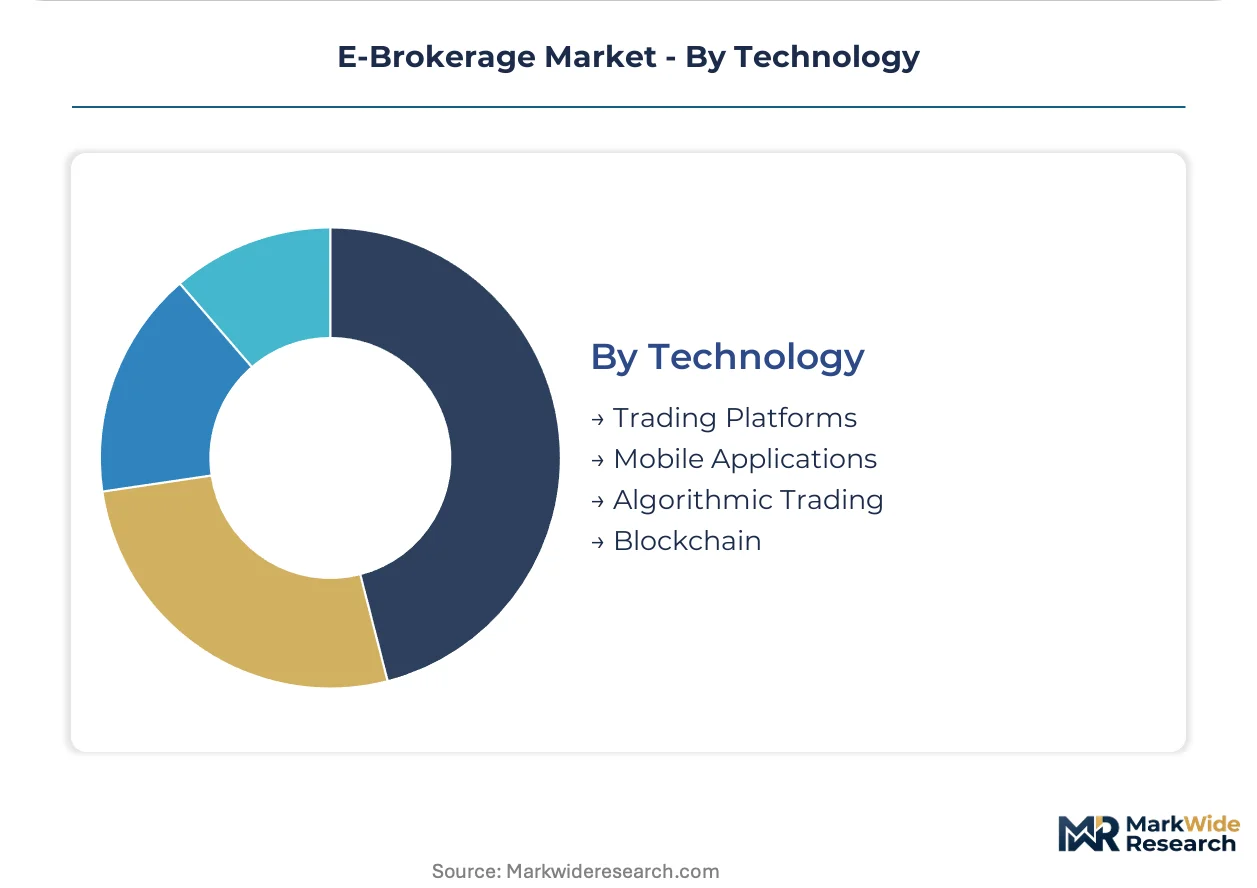
Trading Platforms retain the deepest installed base; Mobile Applications are gaining share fastest in new account origination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City's financial district anchors the deepest concentration of e-brokerage infrastructure, housing FIX protocol connectivity hubs and prime brokerage operations that serve North American retail and institutional flows.
United States
SEC Regulation Best Execution and FINRA suitability standards drive platform investment in order-routing transparency. Payment-for-order-flow economics sustain zero-commission models while attracting regulatory scrutiny. Chicago's derivatives exchanges and clearing infrastructure support sophisticated options and futures execution for retail traders.
China
Mobile-first trading penetration among 200 million retail investors accelerates platform onboarding velocity. SAMR oversight of fintech platforms and the central bank's digital yuan pilots shape custody and settlement architectures. Shanghai's Pudong financial zone hosts domestic brokerage technology development centers serving mass-affluent demand.
India
SEBI's simplified KYC protocols and demat account expansion target 140 million underbanked households for equity market participation. The regulatory push for financial inclusion compresses account opening friction. Mumbai's BSE and NSE technology corridors concentrate domestic platform engineering talent.
Germany
BaFin's MiFID II implementation and retail investor protection frameworks mandate granular cost disclosure across packaged products. Frankfurt's trading infrastructure supports direct market access for algorithmic retail strategies. The country's savings bank sector fragments distribution while neobrokers capture mobile-native cohorts.
United Kingdom
FCA consumer duty rules extend suitability and value-for-money obligations across self-directed investment platforms. London's fintech clusters incubate API-accessible brokerage infrastructure serving European cross-border flows. The regulatory perimeter shapes product availability as platforms navigate post-Brexit equivalence uncertainties.
E-Brokerage Market Vendor Landscape
Premium-margin players sit above commodity-margin players across service intensity and technology depth, with hybrid advisory models commanding higher revenue per account than pure execution platforms. The vendor base stratifies into three tiers: institutional-grade infrastructure providers, mass-market zero-commission operators, and algorithmic-focused API platforms. Consolidation pressures intensify as scale requirements for compliance technology and clearing relationships rise. Dominant competitive moves include strategic API ecosystem expansion and geographic licensing partnerships for regulatory market entry.
Within the institutional-grade tier, Interactive Brokers and Charles Schwab represent archetypes of global market access paired with margin lending depth. Robinhood occupies a position exemplifying mobile-native UX simplification and payment-for-order-flow economics. Among hybrid advisory platforms, Fidelity and Vanguard anchor the convergence of human advisor networks with digital scale, serving high-net-worth tax optimization demand.
| Leading Market Players |
|---|
| Vanguard |
| Interactive Brokers |
| Fidelity |
| Merrill Edge |
| Webull |
| Charles Schwab |
| Robinhood |
| SoFi |
| E*TRADE |
| Others |
Supply Flow & Price Mechanics
FIX protocol standardization and sub-second order routing infrastructure are compressing transaction cost economics while concentrating clearing and custody functions among platforms with scale to absorb compliance technology investments. This dual shift simultaneously reshapes platform revenue models and supplier qualification requirements across the e-brokerage value chain.
Pricing Analysis
Execution quality metrics serve as the primary value-based pricing anchor for institutional-grade platforms, with transaction cost analysis and order-routing transparency commanding premium positioning. Pricing stratifies across premium advisory tiers, standard self-directed execution, and economy zero-commission models, with differentiation driven by margin lending depth and API sophistication. Cost compression in the zero-commission tier is intensifying because SEC best-execution scrutiny threatens payment-for-order-flow economics. Retail investors exhibit highest price sensitivity, while hedge funds and wealth management firms prioritize execution infrastructure over fee minimization.
Supply Chain Analysis
Dual-sourcing requirements for clearing and settlement infrastructure mandate multi-provider qualification among platforms seeking operational resilience. Supply concentration centers on the United States, Ireland, and India for core custody technology and compliance software development. Raw material dependencies include FIX protocol connectivity licenses, real-time market data feeds, and cloud compute capacity for risk-engineering workloads. Single-source vulnerability concentrates in Depository Trust & Clearing Corporation settlement infrastructure. Distribution runs through direct platform onboarding, white-label B2B partnerships with wealth management firms, and API marketplace integrations for algorithmic strategy deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-accessible algorithmic trading infrastructure is displacing legacy desktop-based execution interfaces, compressing platform differentiation timelines and forcing accelerated technology transitions across incumbent and challenger business models.
For Market Incumbents: Anchor market position through securities lending depth expansion and captive clearing infrastructure investment. Payment-for-order-flow regulatory restriction represents the primary threat to zero-commission economics. Vertical integration into proprietary risk-engineering software development preserves margin leverage against API-native challengers.
For New Entrants and Emerging Players: Begin with India's demat account expansion corridor, where simplified KYC protocols and 140 million underbanked households create the most penetrable retail onboarding environment. Mobile-first UX simplification with localized language interfaces offers the strongest go-to-market angle against established global platforms.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation to incumbent financial institutions seeking digital transformation acceleration. Long-term viability favors hybrid advisory models with sticky high-net-worth relationships over pure execution volume dependence. The signal to watch is SEC rulemaking finalization on payment-for-order-flow compensation structures.
| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Python and C++ SDK availability attracts algorithmic retail traders from institutional desks. |
| Crypto-Asset Custody Integration | Unified wallet architectures capture cross-asset flows amid EU MiCA framework development. |
| Margin Lending Infrastructure Buildout | Interest rate sensitivity hedging stabilizes net interest income through policy cycles. |
| Geographic Licensing Partnership | SEBI and BaFin regulatory market entry accelerates without direct authorization timelines. |
| AI-Driven Risk Engine Development | Real-time options and margin modeling addresses quantitative talent scarcity constraints. |
Methodological Framework
SEC 10-K filings, FINRA regulatory notices, and SEBI circulars formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with platform CTOs, compliance officers at clearing firms, retail trading operations heads, and API marketplace product managers validated technology adoption timelines and infrastructure investment patterns. Bottom-up account origination modeling and top-down revenue aggregation triangulated segment-level estimates.
Historical trendline analysis of account growth velocity and revenue per user trajectories informed projection frameworks across the modeling period. Segmentation dimensions modeled include service intensity tier, customer sophistication level, asset class complexity, and technology deployment architecture. CAGRs derived from regression analysis of mobile penetration curves and regulatory implementation schedules, with inputs from central bank policy rate sensitivity and demat account expansion targets.
Underlying measurement precision varies by segment; discount brokerage account volumes carry tighter precision than robo-advisor subscription retention estimates. Forecasts reflect assumptions on payment-for-order-flow regulatory continuity and interest rate normalization pathways. Deviation in SEC best-execution rulemaking finalization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
India Legal Services Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Commodity Trade Finance Market
Financial Services
Intermediary Service Market
Financial Services
Europe B2B Legal Services Market
Financial Services
Europe Insurance Brokerage Market
Financial Services
Account Aggregators Market
Financial Services
Banknote Counters Market
Financial Services
Financial Advisory Services Market
Financial Services
Legal Management Consulting Service Market
Financial Services
Credit Rating Software Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
Healthcare Finance Solutions Market
Financial Services
North America B2B Legal Services Market
Financial Services
Reconciliation Software Market