
 Australia Online Gambling Market | 2026-2036
Australia Online Gambling Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Online Gambling Market Intelligence
The Australian online gambling sector is rebalancing as premium live-dealer and proprietary platform tiers pull away from commodity white-label offerings. Flutter Entertainment leverages its global technology stack to sustain market presence across multiple product verticals. Tabcorp anchors its position through deep integration with retail wagering infrastructure and exclusive state partnerships. PointsBet Holdings differentiates via proprietary risk-management algorithms and in-house trading capabilities.
Australia online gambling encompasses digital wagering platforms enabling real-money betting on sports, casino games, poker, and bingo through internet-connected devices, typically requiring sub-second latency for live in-play betting and AES-256 encryption for payment processing. Its primary commercial purpose is to capture consumer entertainment expenditure while generating taxable revenue for state and federal governments. Sports betting leads product type segmentation due to embedded cultural attachment to Australian Rules Football, rugby, and cricket, while mobile users represent the fastest-expanding end-user category as smartphone penetration exceeds ninety percent nationally. Casino games concentrate margin pools through higher house-edge mechanics and extended session durations compared to event-driven sports wagering.
The Australian Communications and Media Authority enforces Interactive Gambling Act prohibitions on unlicensed offshore operators, while state regulators including Liquor and Gaming NSW and the Victorian Gambling and Casino Control Commission mandate location verification and self-exclusion protocols. These frameworks shape demand by restricting market access to domestically licensed entities and compelling continuous investment in compliance infrastructure. Stakeholders must monitor evolving national harm-minimization standards and potential federal licensing harmonization that would reshape competitive barriers across state boundaries.
Market Dynamics
The Australian online gambling market is compressing around real-time data infrastructure as in-play wagering latency requirements drop below 500 milliseconds. Operators must rebuild core trading engines to maintain price integrity during high-velocity sports events. This technical imperative is reshaping capital allocation across the sector.
Growth Catalysts
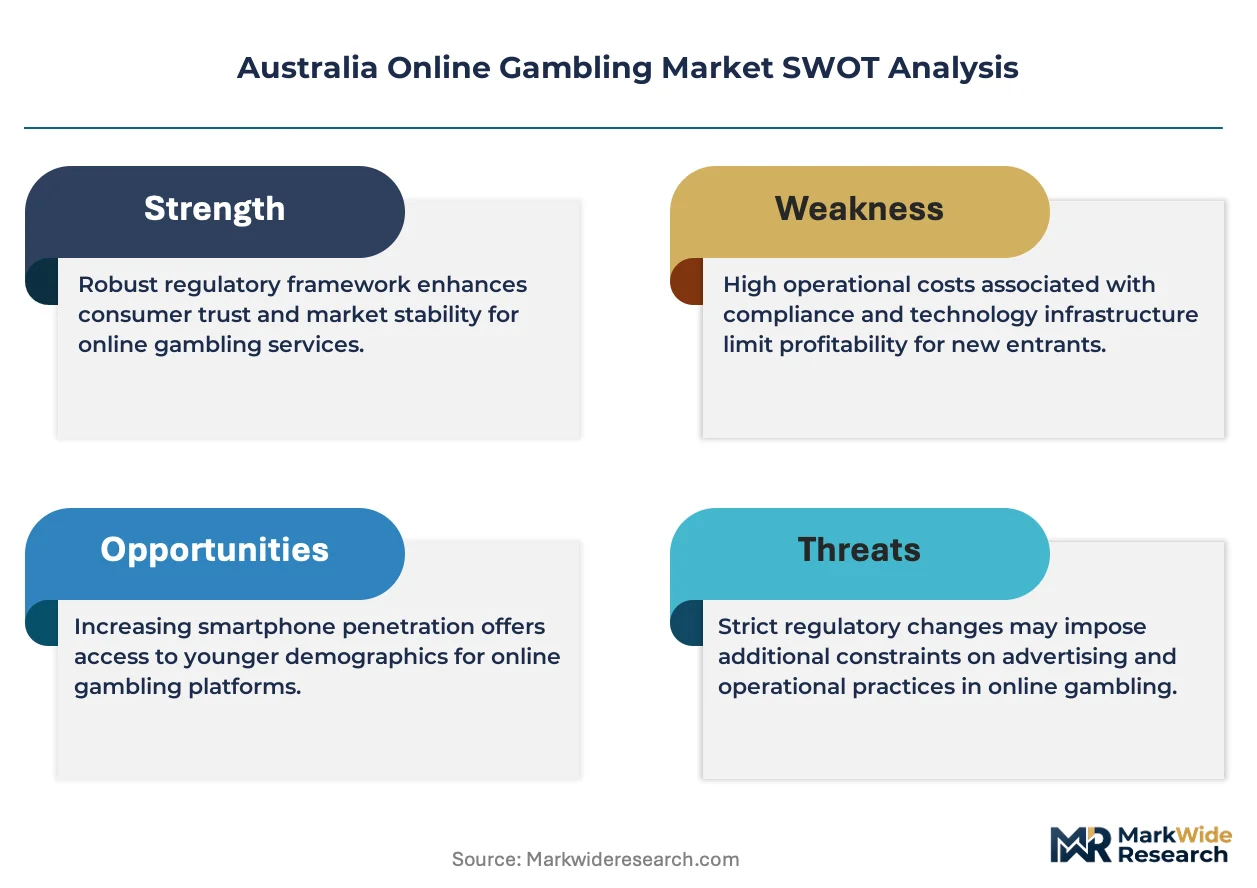
- Interactive Gambling Act enforcement:ACMA blocking orders against unlicensed offshore platforms redirect wagering volume toward domestically regulated operators with verified harm-minimization protocols.
- Smartphone penetration saturation:Mobile-first product development captures session fragmentation as Australian users shift from desktop to native app environments for live betting.
- Victoria and New South Wales wagering infrastructure:Dense metropolitan populations with embedded retail betting networks create natural conversion funnels from physical to digital channels.
Market Restraints
- Payment processor concentration:Domestic banking restrictions on gambling transactions limit deposit method diversity and increase reliance on POLi and BPAY integrations.
- State licensing fragmentation:Separate compliance obligations across Liquor and Gaming NSW, VGCCC, and other state regulators multiply administrative overhead for national operators.
- Harm-minimization technology mandates:Mandatory pre-commitment systems and self-exclusion registries require continuous platform redevelopment without direct revenue attribution.
Strategic Opportunities
- Western Australia market development:Lower digital wagering penetration relative to eastern states offers expansion runway for licensed operators building localized marketing infrastructure.
- Esports betting verticals:Regulatory clarity on skill-based gaming classifications could unlock dedicated product lines targeting demographics underrepresented in traditional sports betting.
- API-driven B2B platform licensing:Proprietary trading and risk management technology can monetize through white-label supply to smaller state-based bookmakers lacking in-house development capacity.
Industry Challenges
- Quantitative trading talent scarcity:Specialized skills in stochastic modeling and real-time odds compilation command premium compensation, constraining mid-tier operator technical capabilities.
- Legacy core banking system integration:Mainframe-dependent financial institutions create friction in instant withdrawal processing, degrading user experience against fintech-native competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Online Gambling Market |
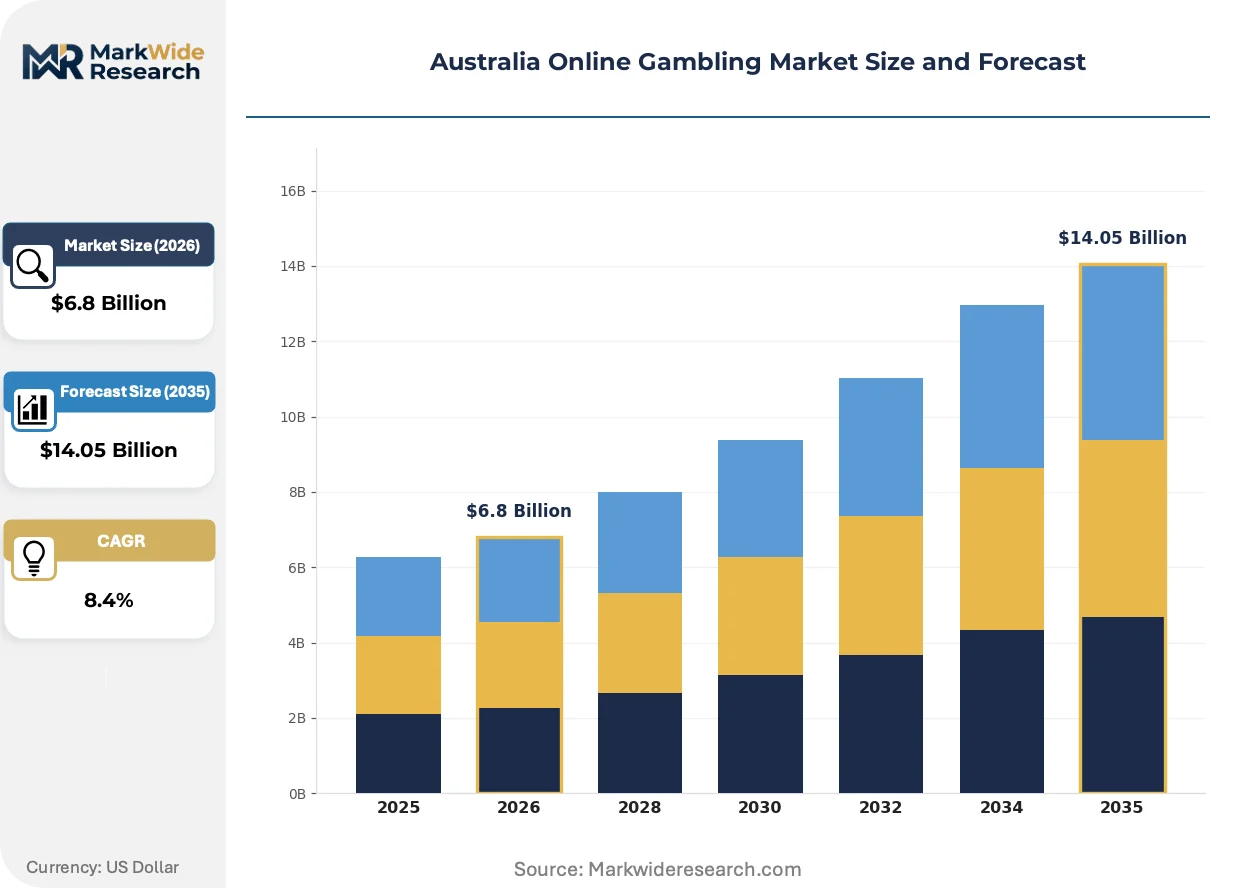
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Betting, Casino Games, Poker, Bingo End User: Casual Gamblers, High Rollers, Mobile Users, Online Enthusiasts Payment Method: Credit Cards, E-Wallets, Bank Transfers, Cryptocurrency Regulatory Compliance: Licensed Operators, Self-Exclusion Programs, Responsible Gambling Measures, Age Verification |
| Companies Covered | The Lottery Corporation, Tabcorp, Aristocrat, Flutter Entertainment, Sportsbet, PointsBet Holdings, Lotterywest, Federal Group, The Stars Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Online Gambling Market Strategic Shifts & Innovations
Artificial intelligence deployment is redistributing competitive advantage from scale to prediction accuracy in Australian wagering markets. Operators now differentiate through proprietary models rather than marketing spend alone.
Machine learning-driven risk pricing is converging with real-time player behavior analytics to enable dynamic margin adjustment during live events. Tier-one operators deploy these systems to manage exposure on volatile in-play markets. The technology is compressing the viability window for manual trading desk configurations.
National Self-Exclusion Register mandates under Interactive Gambling Act amendments require biometric verification integration across all licensed platforms. Operators must rebuild registration flows to comply with identity-matching standards enforced by ACMA. Smaller state-based bookmakers face disproportionate compliance cost burdens relative to national platforms with existing identity infrastructure.
Aggregated content consumption patterns show Australian bettors consolidating activity with single-platform providers offering seamless sports-casino-lottery transitions. Multi-product loyalty architectures are displacing standalone sportsbook or casino-only propositions. This concentration is most visible in Victoria and New South Wales metropolitan markets where platform switching costs have risen through wallet integration and personalized promotion engines.
Australia Online Gambling Market Segmentation
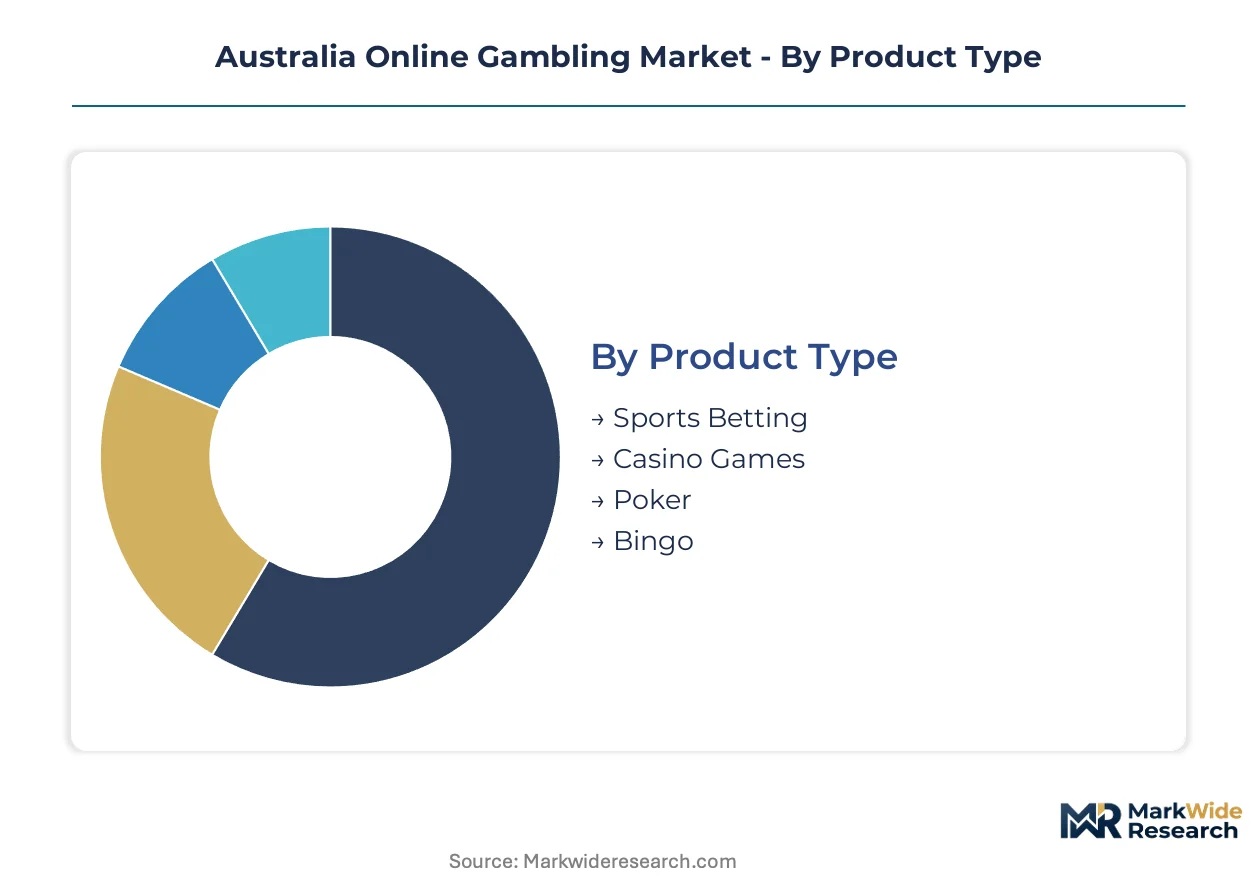
Australian operators segment their addressable market across product verticals, user behavioral profiles, payment infrastructure, and compliance tiers. These divisions determine platform architecture investments and licensing strategy. Each segment carries distinct margin profiles and regulatory exposure.
Product Type:
Volume concentrates in event-driven wagering with thin margins, while premium tiers extract value through extended session mechanics and higher house-edge mathematics.
- Sports Betting:Real-time odds compilation across Australian Rules Football, rugby, and cricket requires sub-500 millisecond latency infrastructure. Victorian and New South Wales metropolitan markets dominate wagering volume due to embedded retail-to-digital conversion funnels and dense sporting calendars.
- Casino Games:Live-dealer streaming and proprietary slot mathematics generate superior margin pools through extended session durations compared to event-driven sports products. High roller concentration in premium table variants sustains VIP acquisition economics despite elevated compliance costs for enhanced due diligence.
- Poker:Peer-to-peer rake models depend on liquidity pool depth across tournament and cash game formats.
- Bingo:Community-chat functionality and fixed-odds prize structures attract demographic segments outside core sports betting.
Mature deployment sits with sports betting. Newer deployment is concentrated in live-dealer casino tiers.
End User:
Behavioral segmentation separates impulse-driven mobile sessions from planned desktop engagement and VIP relationship-managed accounts.
- Casual Gamblers:Fragmented session patterns across smartphone devices drive product development toward single-tap bet placement and wallet consolidation. New South Wales and Victoria urban corridors show highest casual penetration due to public transport commuting patterns and embedded retail betting culture.
- High Rollers:Dedicated account management and bespoke credit lines require enhanced AML monitoring and source-of-wealth verification under AUSTRAC guidelines. This segment sustains margin through reduced price sensitivity and cross-vertical play.
- Mobile Users:Native application performance and biometric authentication now table stakes for acquisition.
- Online Enthusiasts:Multi-platform comparison shopping and promotional arbitrage compress lifetime value.
Established revenue bases reside with high rollers. Climbing the fastest is mobile-first casual engagement.
Payment Method:
Deposit infrastructure fragmentation reflects banking sector risk appetite and regulatory pressure on transaction traceability.
- Credit Cards:Major Australian banks increasingly restrict gambling-coded transactions, forcing operator reliance on indirect routing and higher decline rates. This compression accelerates migration toward alternative rails with superior authorization economics.
- E-Wallets:PayPal and domestic POLi integrations dominate through instant settlement and lower chargeback exposure. Regulatory clarity on stored-value licensing under Anti-Money Laundering Act amendments shapes provider concentration.
- Bank Transfers:BPAY batch processing introduces friction versus real-time alternatives.
- Cryptocurrency:Offshore-only availability limits licensed operator adoption pending regulatory framework development.
Legacy volume rests with credit cards. Steepest expansion trajectory belongs to e-wallet rails.
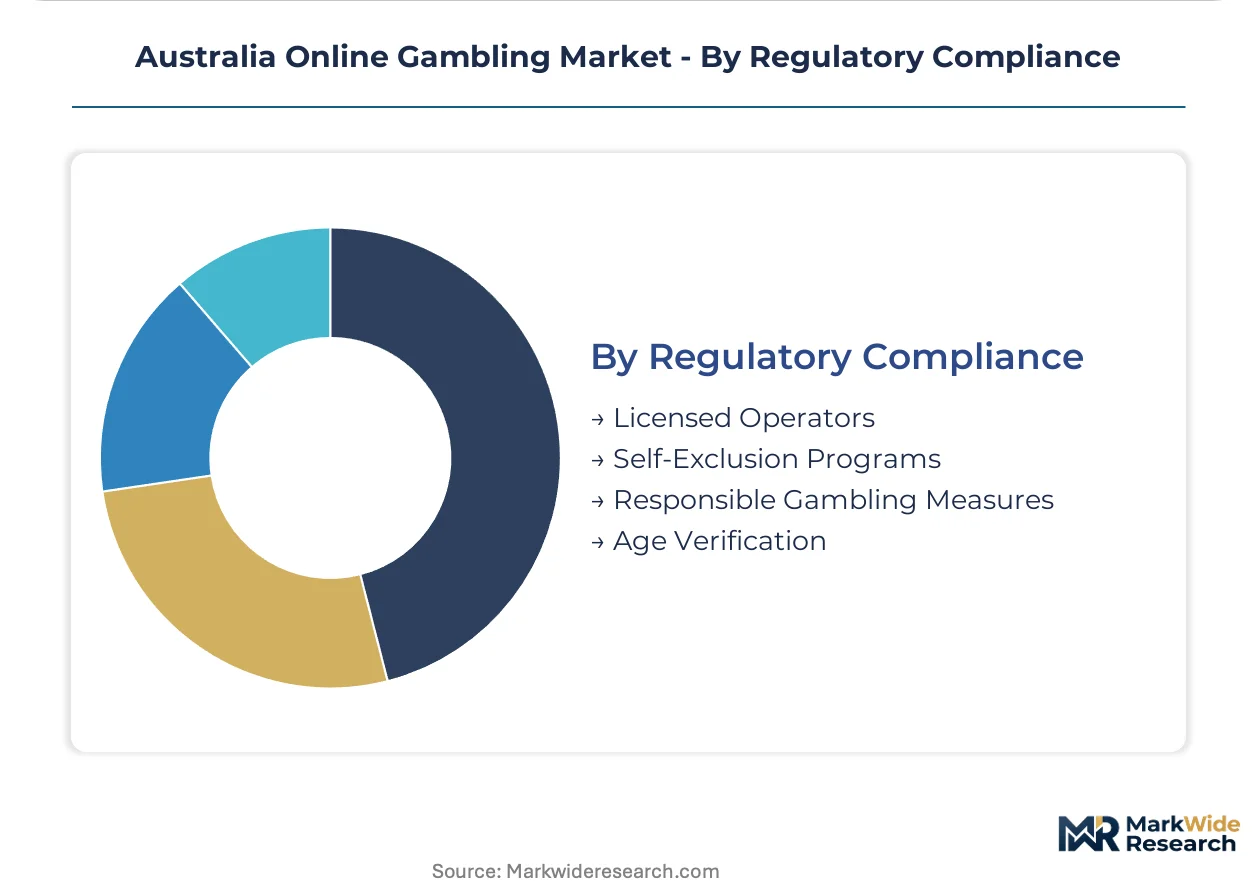
Regulatory Compliance:
Compliance tier segmentation determines market access eligibility and ongoing platform redevelopment obligations.
- Licensed Operators:ACMA-authorized status enables domestic payment processing and excludes unlicensed offshore competition through ISP blocking orders. State-level licensing with Liquor and Gaming NSW and VGCCC mandates location verification and continuous harm-minimization investment.
- Self-Exclusion Programs:National Register integration requires biometric identity matching and real-time account flagging across all licensed platforms. Smaller state-based bookmakers face disproportionate rebuild costs versus national platforms with existing identity infrastructure.
- Responsible Gambling Measures:Mandatory pre-commitment and deposit limit functionality shape UX architecture.
- Age Verification:Document verification and liveness detection add friction to registration funnels.
Baseline compliance concentrates in licensed operator status. Emerging investment priority is self-exclusion registry integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sydney anchors Australian online gambling activity through its dense metropolitan wagering infrastructure and embedded retail-to-digital conversion networks across New South Wales.
New South Wales
Metropolitan Sydney and Newcastle corridors concentrate mobile betting volume through public transport commuting patterns and established retail betting culture. Liquor and Gaming NSW mandates location verification and continuous harm-minimization investment from licensed operators. The Greater Sydney region sustains premium-tier platform economics through high roller concentration and cross-vertical play patterns.
Victoria
Melbourne's sporting calendar density drives real-time in-play wagering demand across Australian Rules Football and cricket seasons. The Victorian Gambling and Casino Control Commission enforces self-exclusion registry integration and biometric identity matching protocols. Metropolitan Melbourne and Geelong clusters show highest casual gambler penetration due to embedded digital payment infrastructure.
Queensland
Brisbane-Gold Coast metropolitan zones exhibit growing mobile-first adoption among younger demographic segments. State-level licensing through the Queensland Office of Liquor and Gaming Regulation imposes parallel compliance obligations to southern jurisdictions. Southeast Queensland's tourism economy creates seasonal wagering volume fluctuations distinct from year-round eastern state patterns.
Western Australia
Perth metropolitan area presents underpenetrated digital wagering opportunity relative to saturation levels in New South Wales and Victoria. The Western Australian Department of Local Government, Sport and Cultural Industries maintains separate regulatory frameworks with distinct licensing timelines. Isolated geography limits retail betting network density, accelerating pure-digital acquisition strategies for market entrants.
South Australia
Adelaide metropolitan market operates under Consumer and Business Services regulatory oversight with harmonized harm-minimization standards to eastern states. Smaller population scale concentrates competitive activity among national platform operators with existing compliance infrastructure. The Adelaide cluster represents testing ground for product innovations before eastern state deployment.
Australia Online Gambling Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the Australian online gambling sector as proprietary platform development separates from white-label distribution. The market structure consolidates around three tiers: global technology stacks with multi-vertical presence, retail-anchored domestic incumbents with state partnership networks, and specialized risk-management boutiques. Strategic differentiation concentrates on real-time trading engine capability and harm-minimization technology integration rather than marketing expenditure alone. Dominant competitive moves include proprietary technology licensing to smaller state-based operators and continuous platform redevelopment for regulatory compliance.
Among ASX-listed operators, Tabcorp anchors the retail-integrated archetype through exclusive state partnerships and physical wagering infrastructure. PointsBet Holdings exemplifies the algorithmic trading specialist model with in-house risk management development. Flutter Entertainment occupies the global technology tier with multi-vertical platform architecture spanning sports, casino, and lottery products. These three representations illustrate the strategic segmentation compressing market structure around capability depth rather than scale alone.
| Leading Market Players |
|---|
| The Lottery Corporation |
| Tabcorp |
| Aristocrat |
| Flutter Entertainment |
| Sportsbet |
| PointsBet Holdings |
| Lotterywest |
| Federal Group |
| The Stars Group |
| Others |
Cost & Logistics Intelligence
Captive technology development anchors supply positioning and pricing power for Australian online gambling operators, with proprietary trading engines and compliance infrastructure determining margin sustainability against white-label competitors. This integration choice separates tier-one platforms from commodity providers dependent on outsourced risk management and third-party platform licensing.
Pricing Analysis
Outcome-based pricing tied to player lifetime value and cross-vertical engagement anchors operator revenue models across sports betting and casino verticals. Three-tier pricing structure across premium live-dealer, standard automated casino, and economy sportsbook tiers reflects latency infrastructure investment and harm-minimization compliance depth. Pricing pressure stems from mandatory self-exclusion registry integration costs without direct revenue attribution. Casual mobile users exhibit highest price sensitivity through promotional arbitrage, while high rollers demonstrate reduced elasticity via dedicated account management and bespoke credit arrangements.
Supply Chain Analysis
Real-time data infrastructure feeds from United Kingdom trading technology providers, Israeli cybersecurity specialists, and domestic biometric verification developers. Critical dependencies include sub-500 millisecond latency networks, AES-256 encryption modules, and ACMA-compliant identity-matching systems. Single-source vulnerability concentrates in quantitative trading talent pools for stochastic modeling and odds compilation. Distribution runs through native mobile applications, browser-based platforms, and retail-integrated digital channels across state licensing boundaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantitative trading talent scarcity props pricing power for operators with captive algorithmic development, constraining mid-tier competitors to outsourced risk management and compressed margins.
For Market Incumbents: To counter fintech-native competitors with instant withdrawal capabilities, incumbents must rebuild legacy banking integrations and accelerate real-time payment rail adoption. Backward integration into proprietary harm-minimization technology reduces compliance cost burdens relative to state-based bookmakers lacking existing identity infrastructure. Channel control through exclusive retail wagering partnerships in Victoria and New South Wales reinforces conversion funnel density. For New Entrants and Emerging Players: Western Australia casual mobile users represent the most penetrable buyer archetype given lower digital wagering saturation and isolated geography limiting retail network competition. Localized marketing infrastructure targeting Perth metropolitan demographics unlocks pure-digital acquisition without incumbent retail anchor dependencies. Esports betting verticals offer regulatory clarity arbitrage pending skill-based gaming classification determinations. For Investors and Strategic Acquirers: Exit pathways concentrate in algorithmic trading specialists with proprietary risk-management capabilities and ACMA-authorized licensing status. Long-term viability across the analysis window favors platforms with multi-vertical architecture spanning sports, casino, and lottery products. The signal to watch is federal licensing harmonization proposals that would reshape competitive barriers across state boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Trading Engine Development | In-house stochastic modeling reduces latency below 500 milliseconds for Victorian and New South Wales in-play markets. |
| Biometric Identity Infrastructure | National Self-Exclusion Register compliance enables ACMA-authorized domestic payment processing. |
| Multi-Vertical Platform Integration | Seamless sports-casino-lottery transitions consolidate wallet share in metropolitan Sydney and Melbourne clusters. |
| Western Australia Market Entry | Localized acquisition infrastructure targets underpenetrated Perth metropolitan demographics. |
| Esports Betting Product Line | Skill-based gaming classification clarity unlocks demographic segments outside traditional sports betting. |
Research Approach
Document review covered ACMA enforcement determinations, state regulator licensing frameworks, and ASX-listed operator disclosures, complemented by interviews with platform engineering directors, compliance officers at Liquor and Gaming NSW and VGCCC, trading desk managers, and payment integration specialists. Secondary validation drew from Interactive Gambling Act amendments, AUSTRAC guidance documents, and telecommunications infrastructure filings. Bottom-up segmentation modeling triangulated against top-down market sizing from wagering turnover data and smartphone penetration statistics.
Market value and volume trajectories across the projection horizon reflect integrated assessment of product vertical adoption curves, regulatory compliance cost absorption, and mobile-first user migration patterns. Segmentation dimensions encompassed product type, end-user behavioral profiles, payment infrastructure preferences, and state-level regulatory tiers. CAGRs derived from trend extrapolation of wagering turnover growth, cross-referenced against harm-minimization technology investment cycles and real-time data infrastructure deployment timelines.
Revisions become necessary when federal licensing harmonization proposals advance, major payment processor restrictions expand, or quantitative trading talent migration accelerates beyond replacement rates. Forecasts reflect documented assumptions regarding ACMA enforcement continuity and state regulatory framework stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Banknote Counters Market
Financial Services
Latin America Factoring Services Market
Financial Services
Factoring Services Market
Financial Services
Europe Insurance Brokerage Market
Financial Services
Global Management Consulting Services Market
Financial Services
E-KYC Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Commodity Trade Finance Market
Financial Services
Global Alternative Data Market
Financial Services
Financial Services Application Market
Financial Services
China Supply Chain Financing Market
Financial Services
US Healthcare Finance Solutions Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
North America Trade Finance Market