
 United States Payroll Services Market | 2026-2036
United States Payroll Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Payroll Services Market Insights
Modular bundling of HR, benefits, and compliance tools is shifting how mid-sized employers evaluate payroll platforms. ADP leverages its scale across tax filing and workforce management to anchor enterprise accounts. Paychex competes through localized service density and dedicated support representatives. Gusto differentiates by targeting sub-fifty-employee businesses with simplified onboarding and integrated benefits administration.
Payroll services encompass the calculation, disbursement, and tax remittance of employee wages, typically delivered through software platforms that automate withholdings for federal income tax, FICA, and state unemployment insurance. The primary commercial purpose is to ensure accurate compensation while maintaining regulatory compliance across multiple jurisdictions. Full-service payroll retains the largest revenue pool by absorbing compliance liability for employers, yet cloud-based payroll represents the fastest structural expansion as SaaS delivery models reduce implementation friction. Small businesses constitute the deepest addressable segment, though large corporations generate higher per-account margins through multi-integration requirements spanning ERP and timekeeping systems.
The Internal Revenue Service governs federal withholding schedules and penalty structures, while the Department of Labor enforces overtime and minimum wage standards that cascade into payroll configuration. State revenue agencies and unemployment insurance funds create additional compliance layers that vary by jurisdiction. Employers must monitor evolving state paid family leave programs and real-time reporting mandates that alter vendor capability requirements.
Market Dynamics
Real-time payment infrastructure and multi-jurisdiction compliance automation are compressing vendor switching costs while elevating platform stickiness through embedded tax engine depth.
Growth Catalysts
- State Paid Leave Mandates:California, New York, and Massachusetts require employers to administer contributions and benefits tracking. This regulatory layering forces mid-sized employers toward full-service platforms.
- Healthcare Systems:Hospital networks and multi-site clinics outsource payroll to manage Affordable Care Act reporting complexity and variable shift compensation across nursing staff.
- API-First Architecture:Native integrations with timekeeping, accounting, and benefits systems reduce implementation friction for sub-200-employee businesses.
Market Restraints
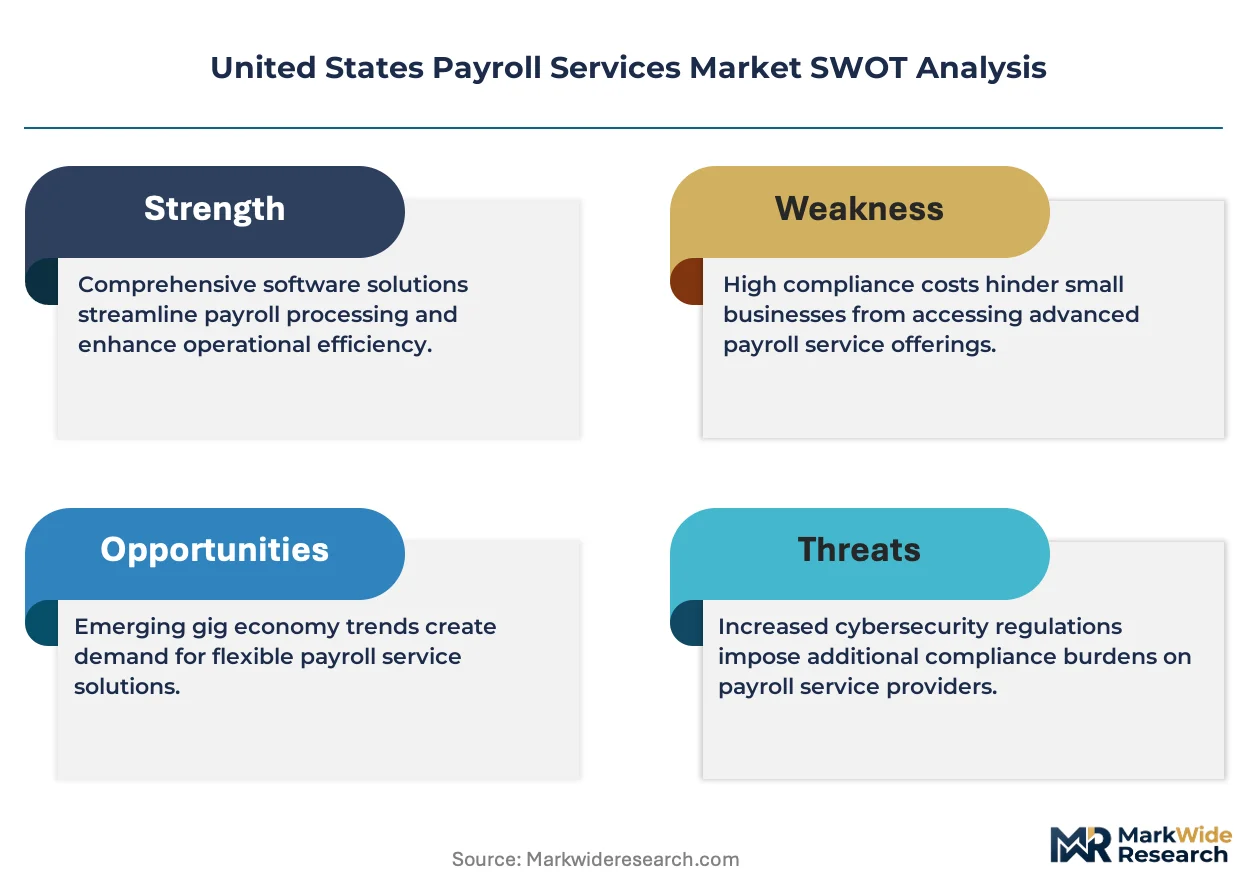
- Tax Engine Maintenance Costs:Annual updates to federal withholding tables and state unemployment insurance rates require dedicated engineering resources that squeeze mid-tier vendor margins.
- Banking Partner Concentration:Direct deposit and wage payment rails depend on relationships with a narrow set of national banks, creating single-point-of-failure exposure.
- Legacy ERP Lock-In:Large enterprises face high migration costs from on-premise systems to cloud-native platforms, slowing replacement cycles.
Strategic Opportunities
- Gig Economy Expansion:Platform companies and staffing firms require 1099 contractor management alongside W-2 payroll, creating demand for hybrid classification tools.
- Earned Wage Access:Integration of on-demand pay advances with payroll cycles attracts hospitality and retail employers seeking reduced turnover.
- State-Level Real-Time Reporting:Pennsylvania and Connecticut mandates for immediate wage reporting to unemployment agencies reward vendors with pre-built state connectors.
Industry Challenges
- Certified Payroll Expertise Gap:Prevailing wage compliance for government contractors demands specialized knowledge of Davis-Bacon Act requirements that few account managers possess.
- Multi-State Nexus Complexity:Remote work arrangements trigger withholding obligations across jurisdictions, requiring clients to maintain accurate employee location data.
- Data Migration Friction:Historical pay records and deduction histories must transfer cleanly between platforms, often revealing format incompatibilities that delay go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Payroll Services Market |
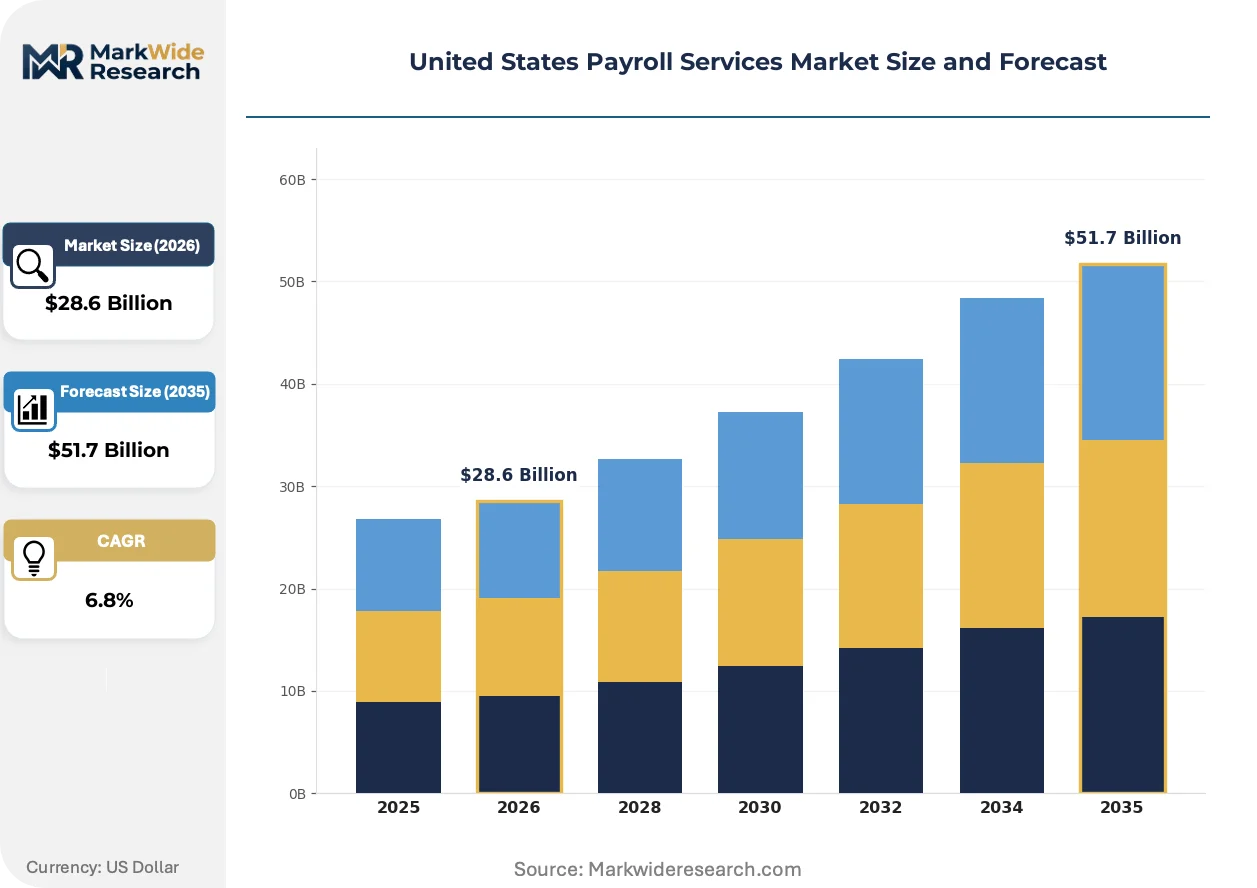
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Payroll, Self-Service Payroll, Managed Payroll, Cloud-Based Payroll Delivery Model: On-Premise, SaaS, Hybrid, Outsourced End User: Small Businesses, Medium Enterprises, Large Corporations, Non-Profits Integration Level: Single Integration, Multi-Integration, API Integration, Custom Integration |
| Companies Covered | Paylocity, Rippling, ADP, Justworks, TriNet, Paychex, Gusto, Dayforce, Paycor, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Payroll Services Market Trends and Innovations
Artificial intelligence and embedded finance capabilities are reconfiguring how payroll platforms capture revenue beyond per-employee-per-month fees.
Machine learning is integrating into anomaly detection engines that flag irregular withholding patterns before tax filing deadlines. Mid-sized employers with 50-500 employees are adopting these tools fastest, driven by penalty avoidance. This capability is compressing the advantage of legacy audit services by embedding compliance checks directly into payroll runs.
The Internal Revenue Service continues tightening penalty structures for late federal tax deposits, with escalating percentages based on delay duration. This enforcement posture pushes employers toward platforms offering automatic remittance scheduling and liability absorption. Small businesses with limited accounting staff show the highest sensitivity to these policy changes.
Subscription bundling now combines payroll with adjacent HR functions at price points that undercut standalone vendors. Professional employer organizations and industry-specific vertical software are capturing share from pure-play payroll providers by wrapping compliance advisory into the core fee. This pattern concentrates most visibly in construction and healthcare, where certified payroll and ACA reporting create stickier relationships.
United States Payroll Services Market Segmentation
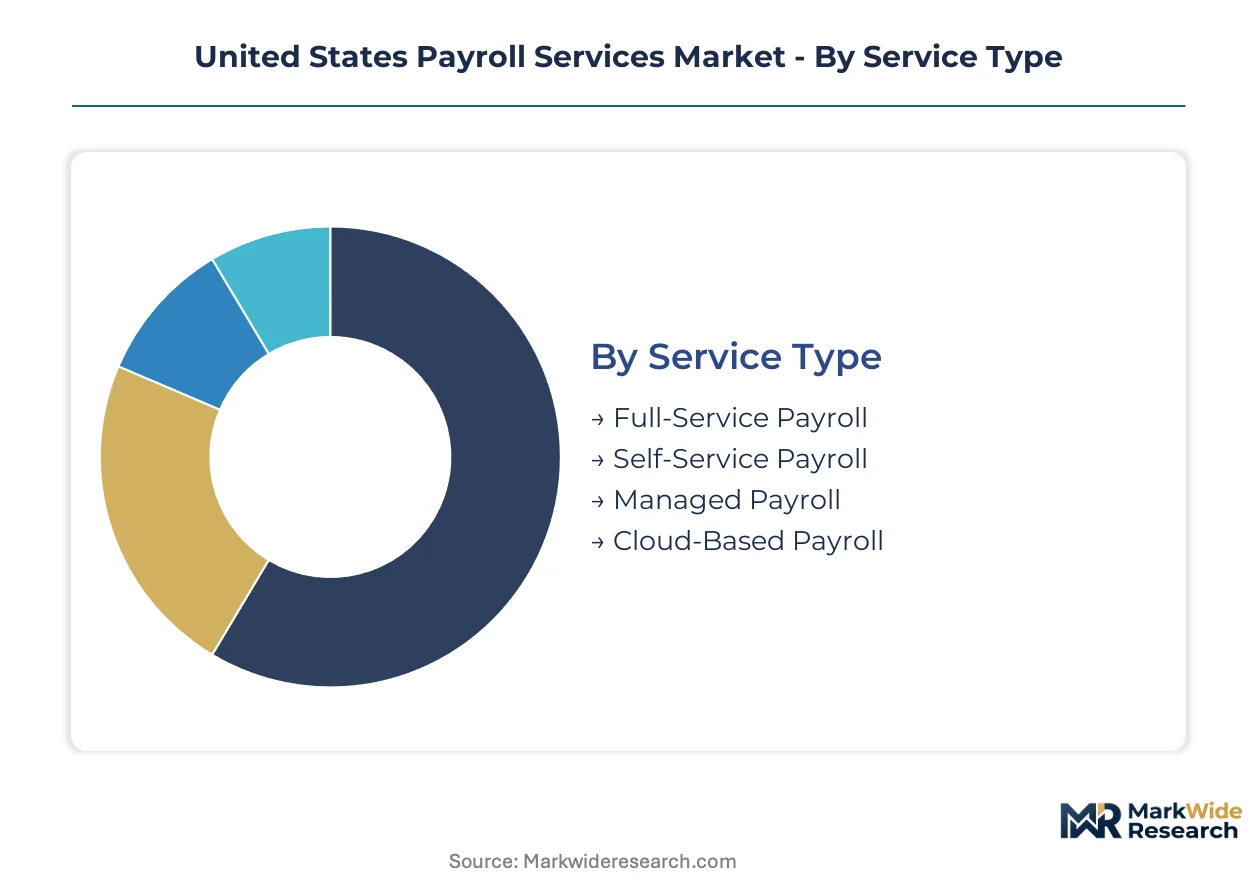
Payroll services fragment across service intensity, technical architecture, and employer scale. Each segmentation axis reveals distinct vendor capability requirements and margin structures that shape competitive positioning.
Service Type:
Customization versus standardization tension peaks in this category, with full liability absorption at one extreme and self-directed tool access at the other.
- Full-Service Payroll:Vendors assume complete liability for tax calculation, remittance timing, and penalty coverage. Healthcare systems in California and New York gravitate here due to ACA reporting complexity and multi-site nursing compensation variability.
- Cloud-Based Payroll:Native SaaS delivery reduces implementation friction through automated updates and remote accessibility. Sub-200-employee businesses across Texas metropolitan areas adopt this fastest as API-first architectures mature.
- Self-Service Payroll:Employers retain direct control over data entry and filing schedules while accessing vendor software tools. This tier attracts cost-conscious businesses with dedicated accounting staff.
- Managed Payroll:Hybrid arrangements where vendors handle compliance-critical functions while employers manage routine data inputs. Mid-sized enterprises use this to balance control with risk transfer.
Leading the category by volume: Full-Service Payroll. Expanding most quickly: Cloud-Based Payroll.
Delivery Model:
Technical ownership patterns divide employers between captive infrastructure and externalized operations, with migration costs dictating switching behavior.
- SaaS:Browser-based platforms with subscription pricing and automatic feature updates. This model captures the fastest-growing employer segment as implementation timelines compress from months to weeks.
- On-Premise:Licensed software running on employer-managed servers with annual maintenance contracts. Legacy ERP lock-in preserves this segment among large corporations despite higher total cost of ownership.
- Hybrid:Combinations of cloud accessibility for routine processing with on-premise data storage for sensitive records. Financial services firms favor this architecture for audit trail control.
- Outsourced:Complete functional delegation to third-party providers with defined service level agreements. Non-profits and small businesses without internal payroll expertise concentrate here.
Dominant by employer count: SaaS. Slowest replacement cycle: On-Premise.
End User:
Scale-based segmentation correlates directly with integration complexity and per-account revenue concentration.
- Small Businesses:Employers with fewer than 50 workers seeking simplified onboarding and basic compliance coverage. Gusto and similar platforms target this segment with integrated benefits administration.
- Large Corporations:Multi-division enterprises requiring ERP synchronization and multi-state withholding management. This segment generates the highest per-account margins through complex integration requirements.
- Medium Enterprises:Organizations with 50-500 employees balancing growth with compliance scalability. State paid leave mandates in Massachusetts and Connecticut push this group toward full-service platforms.
- Non-Profits:Tax-exempt organizations with unique reporting obligations and grant-funded compensation structures. Specialized compliance advisory creates stickier vendor relationships in this segment.
Deepest addressable pool: Small Businesses. Highest margin concentration: Large Corporations.
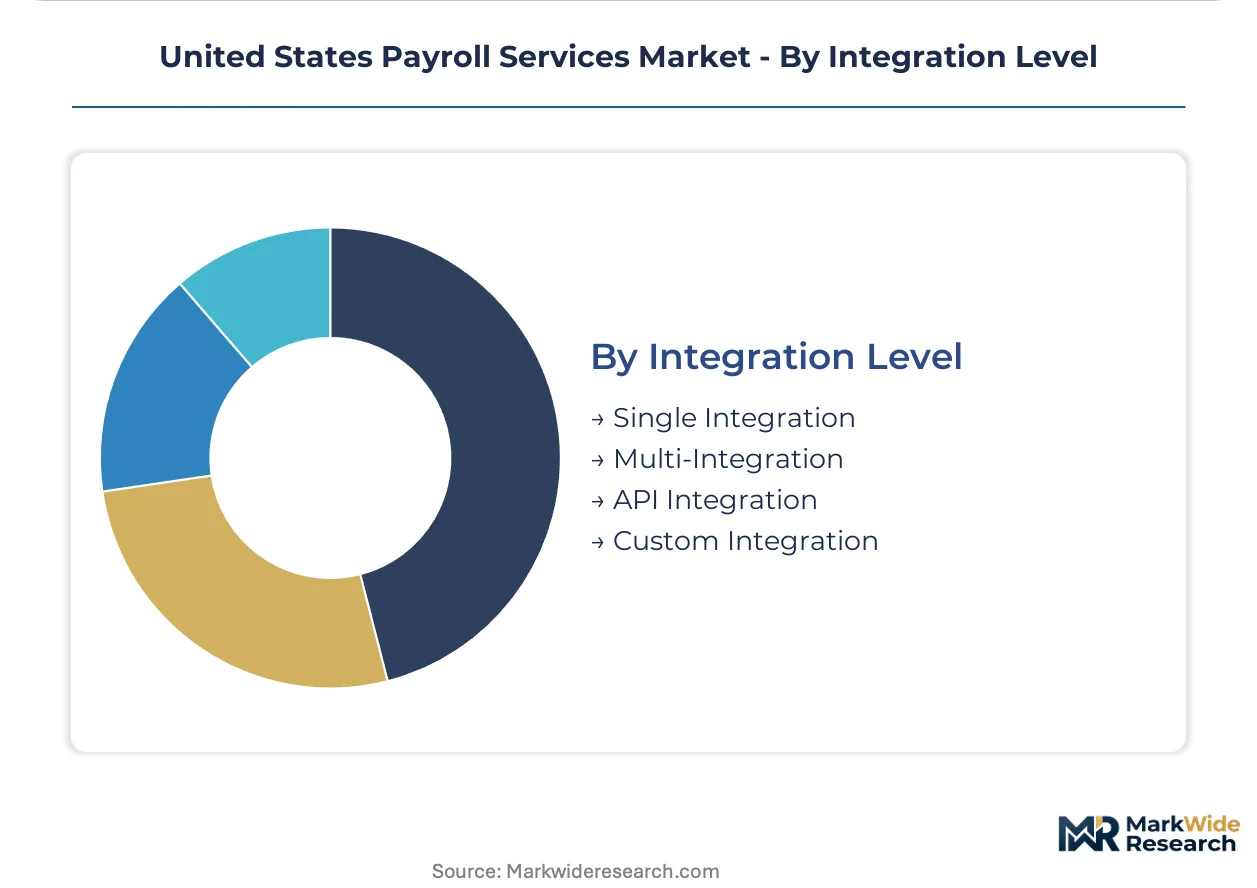
Integration Level:
Connectivity depth determines platform stickiness and switching cost economics across the employer base.
- API Integration:Native programmatic connections to timekeeping, accounting, and benefits systems. This tier attracts technology-forward employers seeking real-time data synchronization.
- Multi-Integration:Simultaneous connections to five or more external systems including ERP and workforce management tools. Large corporations with complex operational footprints require this capability.
- Single Integration:One primary connection, typically to accounting software or basic timekeeping. Small businesses with straightforward operational needs populate this segment.
- Custom Integration:Bespoke development for proprietary systems or industry-specific software. Government contractors with certified payroll requirements often necessitate this approach.
Widest adoption: Single Integration. Steepest capability gap: Custom Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payroll service consumption concentrates in employer-dense metropolitan corridors while production of platform technology clusters around venture capital and engineering talent pools. California, Texas, and New York generate the highest service demand due to regulatory layering and workforce scale. The following state-level analysis examines sub-regional dynamics driving vendor selection and platform deployment.
California
Healthcare systems and technology firms drive outsized demand for full-service payroll administration. The state's paid family leave mandate and CalSavers retirement program create compliance complexity that pushes mid-sized employers toward platforms with native state connectors. The San Francisco Bay Area and Los Angeles Basin concentrate the deepest vendor penetration, with hospital networks outsourcing ACA reporting and multi-site nursing compensation management.
Texas
Energy sector employers and rapidly scaling technology startups fuel adoption of cloud-based payroll platforms. The Texas Workforce Commission's unemployment insurance requirements and absence of state income tax simplify withholding configuration relative to coastal peers. Dallas-Fort Worth and Houston metropolitan areas exhibit the fastest migration from legacy on-premise systems to SaaS delivery models among sub-200-employee businesses.
New York
Financial services firms and professional services partnerships sustain demand for hybrid deployment models combining cloud accessibility with on-premise data control. The state's paid family leave program and New York City-specific mandates elevate compliance automation requirements. Manhattan and Brooklyn technology corridors host the densest concentration of API-first platform adoption, driven by real-time integration needs with trading and accounting systems.
Florida
Hospitality chains and real estate development firms prioritize earned wage access features to reduce seasonal turnover. The Department of Economic Opportunity administers reemployment assistance programs that require precise wage reporting timing. South Florida metropolitan clusters from Miami to West Palm Beach demonstrate accelerating adoption of contractor management tools for 1099-heavy construction and property management workforces.
Illinois
Manufacturing enterprises and logistics operators balance legacy ERP systems with modern compliance automation requirements. The Illinois Department of Employment Security enforces strict unemployment insurance contribution schedules that reward platforms with automated remittance. The Chicago metropolitan area anchors Midwest payroll service demand, with suburban industrial corridors driving multi-integration requirements spanning timekeeping and workforce management systems.
United States Payroll Services Market Competitive Landscape
The competitive structure tilts toward scale-driven incumbents with tax engine depth and compliance liability absorption capabilities. National platforms with dedicated regulatory engineering teams capture enterprise accounts through penalty coverage guarantees. Three strategic archetypes dominate: full-service legacy providers with banking partnerships, cloud-native challengers with API-first architectures, and professional employer organizations bundling HR advisory. M&A activity concentrates on vertical software acquisitions, while R&D investment flows toward real-time payment infrastructure and AI-powered anomaly detection.
Among the scale-driven tier, ADP and Paychex occupy positions defined by decades of tax filing infrastructure and localized service density. Gusto exemplifies the cloud-native archetype targeting sub-fifty-employee businesses with simplified onboarding workflows. Rippling represents the platform-expansion model, extending payroll into adjacent IT and finance automation categories.
| Leading Market Players |
|---|
| Paylocity |
| Rippling |
| ADP |
| Justworks |
| TriNet |
| Paychex |
| Gusto |
| Dayforce |
| Paycor |
| Others |
Pricing and Supply Chain Analysis
Certified payroll engineers concentrated in California and New York command compensation premiums that compress mid-tier vendor margins and widen pricing spreads between full-service and self-service tiers. Labor-cost differentials between compliance-specialist hubs and generalist markets directly stratify platform pricing, with tax-engine depth determining premium positioning.
Pricing Analysis
Margin tightening in cloud-native tiers reflects engineering investment requirements for real-time state-connector maintenance. Three-tier pricing structure across premium, standard, and economy levels segments by compliance liability absorption depth and integration complexity. Price differentiation hinges on tax-engine certification tier and API integration count. Small businesses with sub-fifty employees exhibit highest price sensitivity, while healthcare systems demonstrate lowest sensitivity due to penalty avoidance priorities.
Supply Chain Analysis
Direct-to-employer channels dominate downstream distribution, with banking partnerships serving as critical infrastructure anchors. Platform engineering concentrates in California, Texas, and Washington state, drawing from specialized compliance software talent pools. Raw material dependencies include cloud compute capacity, banking payment rails, and regulatory data feeds. Single-source vulnerability in national banking partner relationships creates concentration risk for wage disbursement operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States payroll services market sits in a technology-transition phase, with API-first architectures displacing legacy on-premise systems through reduced implementation friction and native integration capabilities.
For Market Incumbents: Lock in enterprise accounts through expanded penalty coverage guarantees and dedicated regulatory engineering teams that neutralize cloud-native challenger advantages. Deepen vertical integration into state tax-engine maintenance to preserve margin structure against SaaS compression. Prioritize certified payroll expertise acquisition to defend government contractor segments from specialized compliance advisory competitors. For New Entrants and Emerging Players: Embedded finance partnerships with regional banks offer white-space entry routes outside incumbent banking concentration. Target hospitality and retail sub-200-employee segments with earned wage access differentiation to bypass established platform stickiness. API-first positioning with pre-built state connectors captures mid-sized employers facing Massachusetts and Connecticut real-time reporting mandates. For Investors and Strategic Acquirers: Re-rating potential sits with vertical software acquirers given healthcare and construction regulatory layering acceleration. Long-term viability favors platforms combining tax-engine depth with adjacent HR advisory bundling. Monitor state paid leave mandate expansion as inflection indicator for full-service platform demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Payment Infrastructure Investment | Reduces employer switching costs while elevating platform stickiness through embedded wage access capabilities. |
| State Connector Pre-Build Program | Captures Massachusetts and Connecticut real-time reporting mandates before competitor technical deployment. |
| Certified Payroll Advisory Acquisition | Addresses Davis-Bacon Act expertise gaps that constrain government contractor market penetration. |
| API-First Architecture Expansion | Compresses implementation timelines from months to weeks for sub-200-employee technology-forward employers. |
| Healthcare Vertical Specialization | Locks hospital networks through ACA reporting complexity absorption and multi-site nursing compensation management. |
Research Methodology
Independent corroboration across payroll operations executives, regulatory compliance officers, HR technology procurement leads, and benefits administration directors underwrites the qualitative findings. Secondary validation draws from IRS penalty structure disclosures, Department of Labor enforcement data, state revenue agency reporting requirements, and SEC filings of publicly traded platform providers. Bottom-up employer adoption modeling triangulates against top-down market sizing from service revenue aggregation.
Comparable-period anchoring to historical regulatory implementation timelines structured the forecast window across the projection horizon. Segmentation dimensions modeled include service type intensity, technical architecture deployment, employer scale tier, and integration complexity level. CAGRs derive from employer growth projections weighted by per-account revenue concentration and compliance mandate expansion trajectories. State-level regulatory rollout schedules and API adoption curves serve as industry-specific forecast inputs.
The model holds under steady regulatory enforcement posture and banking partnership stability; deviation in federal penalty structure escalation or regional bank consolidation would shift platform demand distribution. Forecasts reflect documented assumptions regarding employer outsourcing propensity and technology replacement cycles. Periodic stress-testing of base assumptions is recommended against state mandate acceleration or real-time payment infrastructure disruption scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
China Financial Services Software Market
Financial Services
Latin America Factoring Services Market
Financial Services
North America B2C Legal Services Market
Financial Services
Trade Finance Market
Financial Services
Global Alternative Data Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
Europe E-Brokerages Market
Financial Services
Solar Powered ATM Market
Financial Services
Intermediary Service Market
Financial Services
Europe E-Invoicing Market
Financial Services
Hyperinflation System Market
Financial Services
Europe Financial Advisory Services Market
Financial Services
Power Bank Sharing Services Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Digital Transformation in BFSI Market