
 Legal Management Consulting Service Market | 2026-2036
Legal Management Consulting Service Market Size, Share, and Industry Trends Forecast 2026-2036
Legal Management Consulting Service Market Insights
Asset-light partnership models and contingent-fee consulting structures are rewriting competitive dynamics in legal advisory services. Deloitte leverages its integrated audit and tax platform to anchor large-scale compliance transformation programs for Fortune 500 legal departments. McKinsey & Company competes at the intersection of strategy and legal operations, while EY sustains momentum through its forensic technology and regulatory risk capabilities.
Legal management consulting services encompass the application of structured operational frameworks, data analytics, and process engineering to improve the efficiency, cost structure, and risk posture of legal functions within organizations. These services deploy workflow automation tools, matter management platforms, and predictive spend analytics to reduce outside counsel expenditure and accelerate contract cycle times. Compliance advisory and legal process optimization represent the most mature revenue pools, while outcome-based engagement models are capturing disproportionate growth as general counsel shift from hourly relationships to value-aligned fee structures. Corporate legal departments and government agencies constitute the deepest client segments, with hybrid delivery models now dominating implementation architecture.
The SEC, EU AI Act, and GDPR collectively shape demand by mandating documented governance procedures, algorithmic accountability, and cross-border data handling protocols that internal legal teams cannot staff independently. HIPAA and FERC rules add sector-specific layers that require specialized consulting expertise in healthcare and energy verticals. Stakeholders must monitor how generative AI tooling alters the staffing economics of legal departments and whether regulators impose certification requirements on automated legal analysis systems.
Market Dynamics
Generative AI tooling is compressing the staffing economics of legal departments, forcing consultancies to restructure engagement models around automated document analysis and predictive risk scoring rather than traditional hourly advisory.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision-making governance requirements are creating sustained advisory demand for algorithmic accountability frameworks and documentation protocols.
- SEC disclosure rule expansion:Enhanced reporting obligations for public companies are driving Fortune 500 legal departments to external consultants for regulatory interpretation and implementation.
- Litigation finance proliferation:Third-party funding growth in the United States is expanding matter volume and complexity, requiring specialized consulting support for portfolio risk assessment.
Market Restraints
- Talent scarcity in forensic data analytics:The shallow pool of consultants combining legal domain expertise with machine learning implementation skills limits service scalability.
- Client concentration in financial services:Overreliance on banking and insurance verticals creates demand volatility during sector-specific downturns or regulatory pauses.
- Substitution by captive legal ops teams:Mature corporate legal departments are building internal transformation capabilities, reducing reliance on external strategic advisory.
Strategic Opportunities
- Algorithmic certification services:Anticipated regulatory requirements for validated AI legal analysis systems position consultancies to develop proprietary audit methodologies.
- Healthcare compliance vertical:HIPAA enforcement intensification and clinical trial data governance create specialized advisory demand from pharmaceutical and provider networks.
- Hybrid delivery platformization:Integrated workflow tools combining matter management with spend analytics enable consultancies to capture recurring technology licensing revenue.
Industry Challenges
- Legacy system integration complexity:Enterprise legal departments operate fragmented technology stacks that resist seamless deployment of unified consulting solutions.
- Outcome-based pricing calibration:Defining measurable value metrics for legal transformation engagements remains contested between clients and advisory firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Legal Management Consulting Service Market |
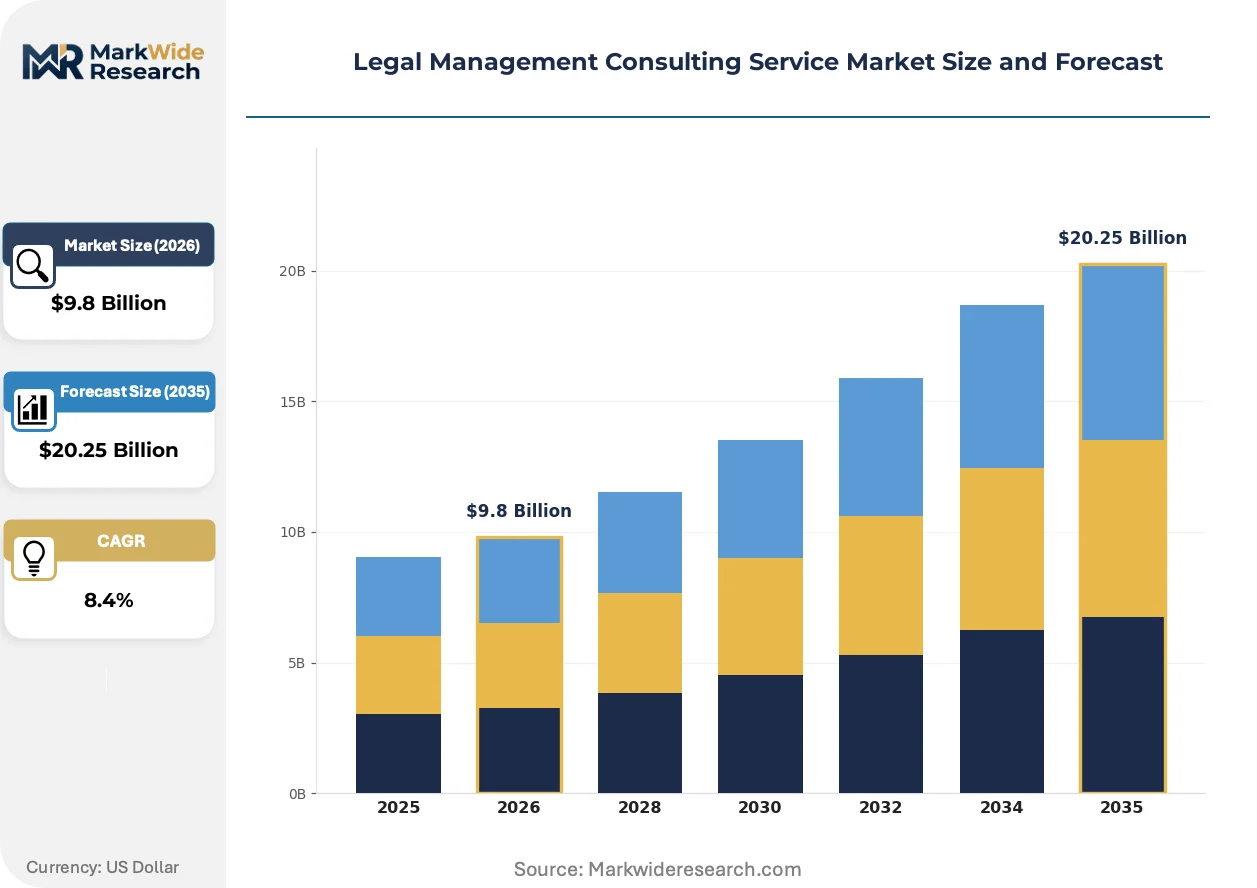
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Compliance Advisory, Risk Management, Legal Process Optimization, Intellectual Property Consulting, Contract Management Client Type: Law Firms, Corporate Legal Departments, Government Agencies, Non-Profit Organizations, Startups Engagement Model: Project-Based, Retainer-Based, Outcome-Based, Hourly Billing, Fixed Fee Delivery Model: Onsite Consulting, Remote Support, Hybrid Model, Workshop Sessions, Training Programs |
| Companies Covered | Deloitte, PwC, Ernst & Young (EY), KPMG, Accenture, McKinsey & Company, Boston Consulting Group (BCG), Bain & Company, Oliver Wyman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Legal Management Consulting Service Market Trends and Innovations
Advisory delivery is pivoting from episodic project engagements toward embedded operational partnerships, with technology platforms serving as the primary interface between consultants and client legal functions.
Contract lifecycle management software is virtualizing the traditional role of junior attorneys in document review and clause extraction. Corporate legal departments in technology and manufacturing sectors are deploying these tools at enterprise scale, compressing cycle times from weeks to days. This virtualization is enabling consultancies to restructure staffing models toward higher-margin strategic advisory.
The EU AI Act's risk-based classification system for automated decision-making is mandating documented governance procedures that internal legal teams cannot staff independently. Financial services and insurance verticals face the steepest compliance burden, driving sustained demand for external algorithmic accountability advisory. European-headquartered multinationals are responding by establishing dedicated AI governance officer roles supported by retained consulting relationships.
General counsel are unbundling after-sales advisory from traditional hourly relationships, instead procuring transformation support through fixed-fee outcome contracts. This reconfiguration displaces incumbent law firm consulting arms that lack operational metrics and process engineering capabilities. The shift is most visible in United States-based Fortune 500 legal departments with mature spend management functions.
Legal Management Consulting Service Market Segmentation
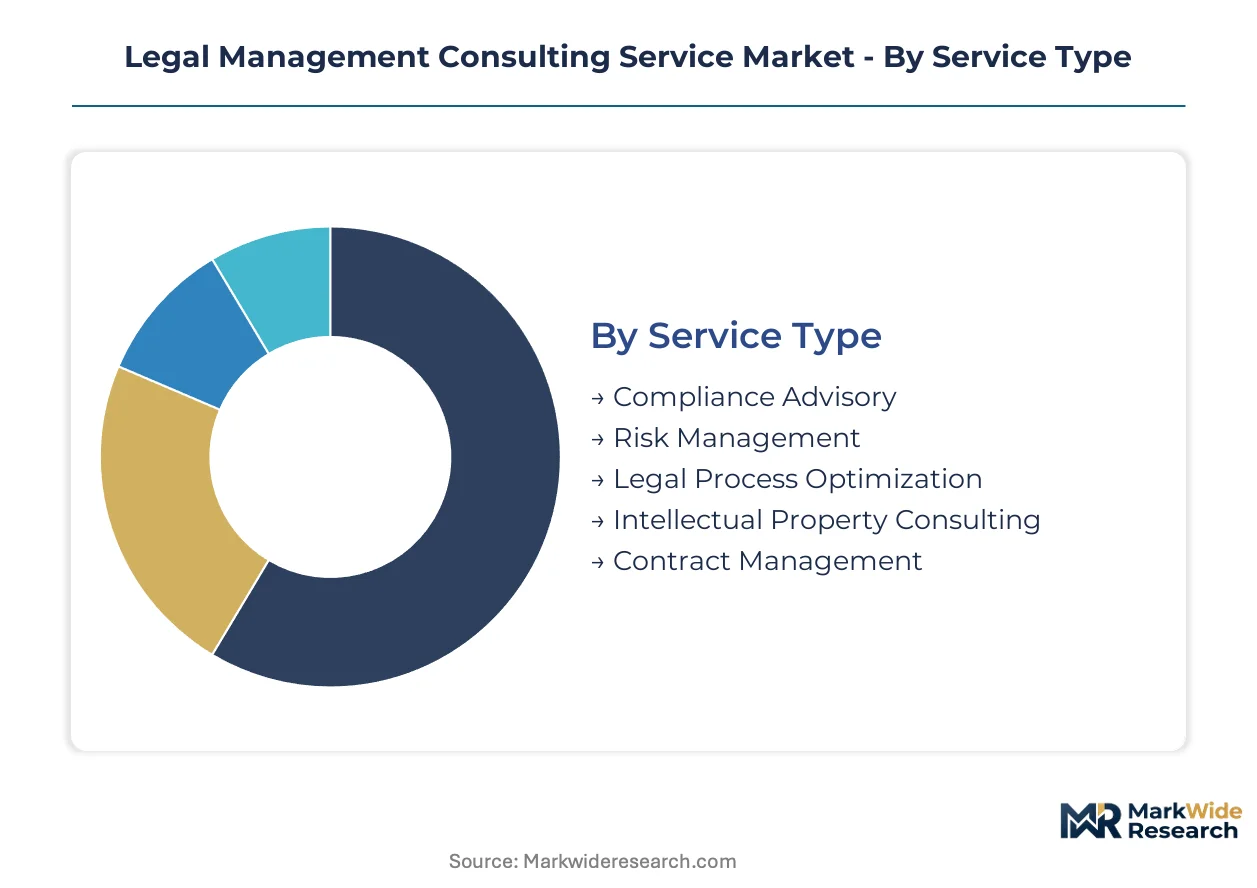
Legal management consulting services fragment across four critical dimensions that determine pricing architecture, contract duration, and client retention patterns. Each segmentation layer reveals distinct operational rhythms and margin profiles that shape how advisory firms allocate talent and technology investments.
Service Type:
Compliance Advisory and Legal Process Optimization turn over fastest with quarterly renewal cycles, while Intellectual Property Consulting extends across multi-year retainer structures.
- Compliance Advisory:Structured frameworks for regulatory interpretation and implementation span SEC disclosure rules, EU AI Act mandates, and sector-specific HIPAA protocols. Financial services legal departments in New York and London generate sustained demand as algorithmic governance requirements intensify.
- Legal Process Optimization:Workflow engineering and matter management platform deployment reduce outside counsel spend through predictive analytics and contract cycle compression. Technology sector corporate legal departments deploy these services at enterprise scale to virtualize document review functions.
- Risk Management:Portfolio assessment for litigation finance and regulatory exposure.
- Intellectual Property Consulting:Patent strategy and licensing optimization for pharmaceutical and technology verticals.
- Contract Management:Lifecycle automation and clause standardization for procurement legal functions.
Legal Process Optimization anchors the volume base while Compliance Advisory gains share at the steepest rate.
Client Type:
Corporate Legal Departments command premium pricing tiers with annual spend commitments, whereas Startups cluster at entry-level fixed-fee arrangements with minimal customization.
- Corporate Legal Departments:Fortune 500 legal functions with mature spend management infrastructure procure transformation support through outcome-based contracts. United States-based manufacturing and technology sectors unbundle after-sales advisory from traditional hourly relationships.
- Law Firms:AmLaw 200 firms and regional practices seeking operational benchmarking and alternative fee structure design. London and Singapore legal markets concentrate demand for competitive positioning advisory.
- Government Agencies:Federal and state procurement for regulatory modernization and public legal service efficiency.
- Non-Profit Organizations:Mission-aligned legal capacity building with constrained budget parameters.
- Startups:Venture-backed companies requiring scalable legal infrastructure without captive headcount.
Law Firms generate the deepest recurring revenue while Corporate Legal Departments demonstrate the steepest expansion trajectory.
Engagement Model:
Hourly Billing retains the longest client relationships through embedded advisory roles, while Outcome-Based contracts compress initial sales cycles but demand intensive metric definition.
- Outcome-Based:Fixed-fee contracts tied to measurable legal transformation metrics such as contract cycle time reduction or outside counsel spend optimization. General counsel at United States industrial conglomerates favor this structure for compliance transformation programs.
- Retainer-Based:Monthly recurring access to dedicated consulting teams with priority response guarantees. European-headquartered multinationals deploy this model for sustained AI governance officer support.
- Project-Based:Defined-scope engagements for technology implementation or regulatory readiness assessment.
- Hourly Billing:Traditional time-and-materials structure for episodic advisory and crisis response.
- Fixed Fee:Predetermined pricing for standardized service packages with limited scope variation.
Retainer-Based engagements anchor the volume base while Outcome-Based structures are climbing the fastest.
Delivery Model:
Hybrid Model deployments concentrate in complex regulatory environments requiring both on-site stakeholder management and distributed analytics capabilities.
- Hybrid Model:Integrated delivery combining onsite client presence with remote technology platform access and distributed specialist teams. Financial services legal departments in Frankfurt and Chicago adopt this architecture for EU AI Act implementation.
- Onsite Consulting:Embedded consultants operating within client legal department premises for transformation program execution.
- Remote Support:Cloud-based advisory through virtual collaboration platforms and asynchronous workflow tools.
- Workshop Sessions:Intensive facilitated engagements for strategy alignment and capability building.
- Training Programs:Structured curriculum delivery for legal operations skill development and technology adoption.
Hybrid Model deployments anchor the volume base while Remote Support is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The export-import balance of legal advisory services tilts heavily toward net-importing jurisdictions where regulatory complexity outpaces domestic consulting capacity. Jurisdictions with dense financial services clusters and active enforcement regimes generate sustained cross-border demand for external legal transformation expertise.
United States
Fortune 500 legal departments in New York and Chicago drive demand for SEC disclosure compliance and litigation finance portfolio assessment. The SEC's enhanced climate and cybersecurity reporting mandates force corporate legal functions to externalize implementation support. Manhattan-based financial services legal departments unbundle after-sales advisory from traditional hourly relationships at accelerating rates.
United Kingdom
London's concentration of international law firms and insurance headquarters creates dual demand streams for operational benchmarking and regulatory interpretation. The FCA's operational resilience requirements and post-Brexit regulatory divergence generate sustained advisory spend. The City of London legal market concentrates procurement of competitive positioning advisory for AmLaw 200 firms.
Germany
Frankfurt's banking legal departments face the steepest EU AI Act compliance burden among continental European jurisdictions. BaFin's algorithmic governance expectations for automated credit decisions mandate documented accountability frameworks. Bavaria-based automotive and industrial conglomerates establish dedicated AI governance officer roles supported by retained consulting relationships.
France
Paris-headquartered multinational insurers and asset managers confront overlapping GDPR, EU AI Act, and ACPR prudential requirements. The CNIL's enforcement intensification around automated decision-making drives demand for forensic data analytics capabilities. Île-de-France legal departments procure hybrid delivery models combining onsite transformation leadership with remote technology platform access.
Singapore
Regional headquarters for Asia-Pacific financial services concentrate demand for cross-border regulatory harmonization advisory. MAS guidelines on AI governance in financial services create implementation mandates that outpace local consulting supply. Marina Bay legal functions deploy outcome-based contracts for compliance transformation programs at accelerating rates.
Legal Management Consulting Service Market Competitive Landscape
On the supply side, the industry is consolidating around integrated professional services platforms that combine audit, tax, and advisory capabilities under unified delivery architectures. The competitive terrain stratifies into three distinct tiers: the Big Four accounting networks anchoring large-scale compliance transformation, strategy-focused pure-play consultancies competing at the intersection of legal operations and corporate strategy, and boutique legal technology specialists capturing niche workflow automation mandates. M&A activity concentrates on acquiring forensic data analytics capabilities and legal technology platforms, while strategic partnerships with contract lifecycle management software vendors reshape implementation economics.
Within the integrated platform tier, Deloitte and PwC exemplify the audit-anchored model that captures Fortune 500 legal department transformation programs through cross-selling compliance advisory. McKinsey & Company occupies a position at the premium strategy intersection, competing for legal operations mandates that require board-level engagement and operational metrics design. These three anchors represent the dominant competitive archetypes that structure pricing and talent acquisition dynamics across the market.
| Leading Market Players |
|---|
| Deloitte |
| PwC |
| Ernst & Young (EY) |
| KPMG |
| Accenture |
| McKinsey & Company |
| Boston Consulting Group (BCG) |
| Bain & Company |
| Oliver Wyman |
| Others |
Pricing and Supply Chain Analysis
Transatlantic data transmission corridors connecting Frankfurt and New York drive cost dynamics that concentrate supply among integrated professional services networks while forcing tiered pricing differentiation between algorithmic governance mandates and commoditized compliance documentation.
Pricing Analysis
Fortune 500 legal departments anchor value-based pricing structures that stratify across premium advisory, standard implementation, and economy-tier technology licensing levels. Price differentiation hinges on certification depth for EU AI Act compliance and geographic delivery complexity for cross-border regulatory harmonization. Cost compression in commoditized contract lifecycle management is intensifying because generative AI tooling virtualizes junior attorney functions. Mid-market corporate legal departments exhibit the highest price sensitivity, while banking and insurance verticals demonstrate the lowest due to regulatory penalty exposure.
Supply Chain Analysis
Tariff exposure between the United States and European Union jurisdictions dominates supply chain risk for regulatory advisory services requiring dual-registered expertise. Talent concentration rests on the United States, United Kingdom, and Germany as primary sourcing markets for forensic data analytics and algorithmic governance specialists. Raw material dependencies include proprietary matter management platforms, predictive spend analytics engines, and contract lifecycle management software licenses. Single-source vulnerability permeates the shallow pool of consultants combining legal domain expertise with machine learning implementation skills. Distribution runs through embedded operational partnerships with technology platforms serving as the primary client interface.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Legal management consulting represents a service-attach opportunity where recurring technology licensing and retained advisory relationships expand faster than episodic project engagements.
For Market Incumbents: Build switching-cost moats through proprietary algorithmic certification methodologies that anticipate EU AI Act enforcement requirements. Deepen captive supply of forensic data analytics talent through targeted acquisition of boutique legal technology specialists. The threat of mature corporate legal departments building internal transformation capabilities demands preemptive platform integration that embeds consultants within client workflows. Certification investment in automated legal analysis systems represents the critical defensive lever. For New Entrants and Emerging Players: Mid-market healthcare providers in the United States facing HIPAA enforcement intensification represent the most penetrable entry point for specialized compliance advisory. European-headquartered multinationals establishing dedicated AI governance officer roles offer a secondary white-space target for retainer-based support services. A go-to-market angle anchored to outcome-based contracts with measurable contract cycle time reduction metrics bypasses incumbent hourly billing relationships. For Investors and Strategic Acquirers: Boutique legal technology specialists with embedded workflow automation platforms and established pharmaceutical vertical relationships constitute the priority acquisition archetype. Long-term viability across the analysis window depends on algorithmic accountability mandates hardening into certification requirements rather than discretionary advisory demand. The signal to watch is regulatory movement toward mandatory validation protocols for automated legal analysis systems deployed in financial services credit decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Certification Methodology Development | Anticipated EU AI Act enforcement creates proprietary audit standard opportunities for first movers. |
| Healthcare Compliance Vertical Expansion | HIPAA enforcement intensification drives specialized advisory demand from pharmaceutical and provider networks. |
| Hybrid Delivery Platformization | Integrated workflow tools combining matter management with spend analytics enable recurring technology licensing revenue capture. |
| Forensic Data Analytics Capability Acquisition | Talent scarcity in machine learning-legal hybrid skills limits service scalability without targeted specialist purchases. |
| Outcome-Based Contract Structure Design | General counsel unbundling hourly relationships favor fixed-fee transformation metrics over traditional time-and-materials billing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with general counsel at Fortune 500 legal departments, managing partners at AmLaw 200 firms, regulatory affairs directors at European-headquartered multinationals, and legal operations heads at financial services institutions. Secondary validation drew from SEC disclosure filings, EU AI Act implementation guidance, BaFin algorithmic governance circulars, and matter management platform vendor documentation. Bottom-up service line sizing and top-down macroeconomic calibration were triangulated across the analysis window.
Calibration against historical regulatory implementation cycles and technology adoption curves anchored the analytical framework across service type, client segment, engagement model, and delivery architecture dimensions. CAGRs were derived from regression analysis of consulting spend patterns against enforcement intensity indices and algorithmic governance mandate rollout schedules. Inputs included litigation finance portfolio growth trajectories and corporate legal department technology procurement data.
Stress conditions across regulatory pause scenarios, generative AI disruption velocities, and talent pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EU AI Act enforcement timing and SEC disclosure rule expansion scope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
South Korea Factoring Services Market
Financial Services
Currency Management Market
Financial Services
Global Management Consulting Services Market
Financial Services
Financial Services Software Market
Financial Services
ATM Management Service Market
Financial Services
ATM Managed Services Market
Financial Services
Australia Online Trading Platform Market
Financial Services
Investment Trading Software Market
Financial Services
Healthcare Finance Solutions Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
United States Credit Agency Market
Financial Services
Global Product Cost Management Market
Financial Services
Middle Office Outsourcing Market
Financial Services
White Glove Services Market
Financial Services
Middle East Islamic Finance Market
Financial Services
Commodity Trade Finance Market