
 Investment Trading Software Market | 2026-2036
Investment Trading Software Market Size, Share, and Industry Trends Forecast 2026-2036
Investment Trading Software Market Insights
The capital-intensity divergence between cloud-native entrants and legacy infrastructure incumbents is unwinding competitive stability in trading software. Interactive Brokers leverages its proprietary order-routing technology to sustain direct market access dominance across asset classes. Charles Schwab anchors its position through integrated wealth management-trading workflows that span advisory and self-service channels. Fidelity competes on research depth and fractional share capabilities that extend its retail capture rate.
Investment trading software comprises algorithmic order execution systems, real-time market data processing engines, and portfolio analytics platforms engineered for sub-millisecond latency and regulatory audit trails. These systems process FIX protocol messages, normalize multi-venue pricing feeds, and generate post-trade reporting for clearing compliance. Cloud-based deployment leads solution architecture as broker-dealers abandon data center overhead for elastic compute scaling. Execution software and risk management modules command concentrated margin pools, while analytics solutions represent the fastest-growing solution category as quantitative strategies proliferate.
The SEC, FINRA, and CFTC impose trade reporting, best execution, and market manipulation surveillance requirements that shape platform development roadmaps and vendor procurement criteria. MiFID II equivalence debates and emerging EU AI Act scrutiny for algorithmic trading systems create additional compliance layer complexity for cross-border operators. Stakeholders must monitor how real-time settlement acceleration through distributed ledger infrastructure reshapes clearing integration requirements and vendor consolidation incentives.
Market Dynamics
Cloud-native architectures are decomposing the capital barriers that historically protected incumbent trading software vendors, enabling broker-dealers to shift from fixed data center commitments to consumption-based compute scaling. This infrastructure transition accelerates vendor switching and compresses implementation timelines across retail and institutional channels.
Growth Catalysts
- Regulatory Reporting Mandates:SEC Rule 613 (Consolidated Audit Trail) and FINRA surveillance requirements compel broker-dealers to upgrade execution infrastructure for comprehensive order lifecycle tracking.
- Retail Self-Direction:Fractional share trading and zero-commission models expand platform adoption among individual investors seeking direct market access without advisory intermediation.
- API-First Architectures:Open banking standards and FIX protocol extensions enable third-party developers to build customized trading workflows atop established clearing infrastructure.
Market Restraints
- Latency Arbitrage Compression:Co-location fees at major exchanges and specialized hardware requirements for sub-microsecond execution create persistent cost disadvantages for non-specialized entrants.
- Clearing Concentration:Dependence on DTCC and OCC for post-trade processing limits vendor differentiation and creates single-point-of-failure exposure across the settlement chain.
- Cross-Border Regulatory Friction:MiFID II best execution requirements and divergent SEC disclosure standards force dual-compliance architectures that inflate development overhead.
Strategic Opportunities
- Emerging Market Penetration:Brazil's B3 exchange and India's NSE present underdeveloped retail brokerage infrastructure with accelerating smartphone-based trading adoption.
- Embedded Finance Convergence:Banking-as-a-Service platforms integrate trading modules into neobank and fintech super-app offerings, expanding distribution beyond traditional broker-dealer channels.
- Real-Time Settlement Infrastructure:Distributed ledger pilots at DTCC and ECB wholesale experiments create early-mover advantages for vendors building T+0 compatible clearing interfaces.
Industry Challenges
- Quantitative Talent Scarcity:Shortage of engineers proficient in low-latency C++ and kernel-bypass networking limits development velocity for execution system upgrades.
- Legacy System Integration:COBOL-based back-office systems at established broker-dealers resist API modernization, forcing expensive middleware layers for cloud connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Investment Trading Software Market |
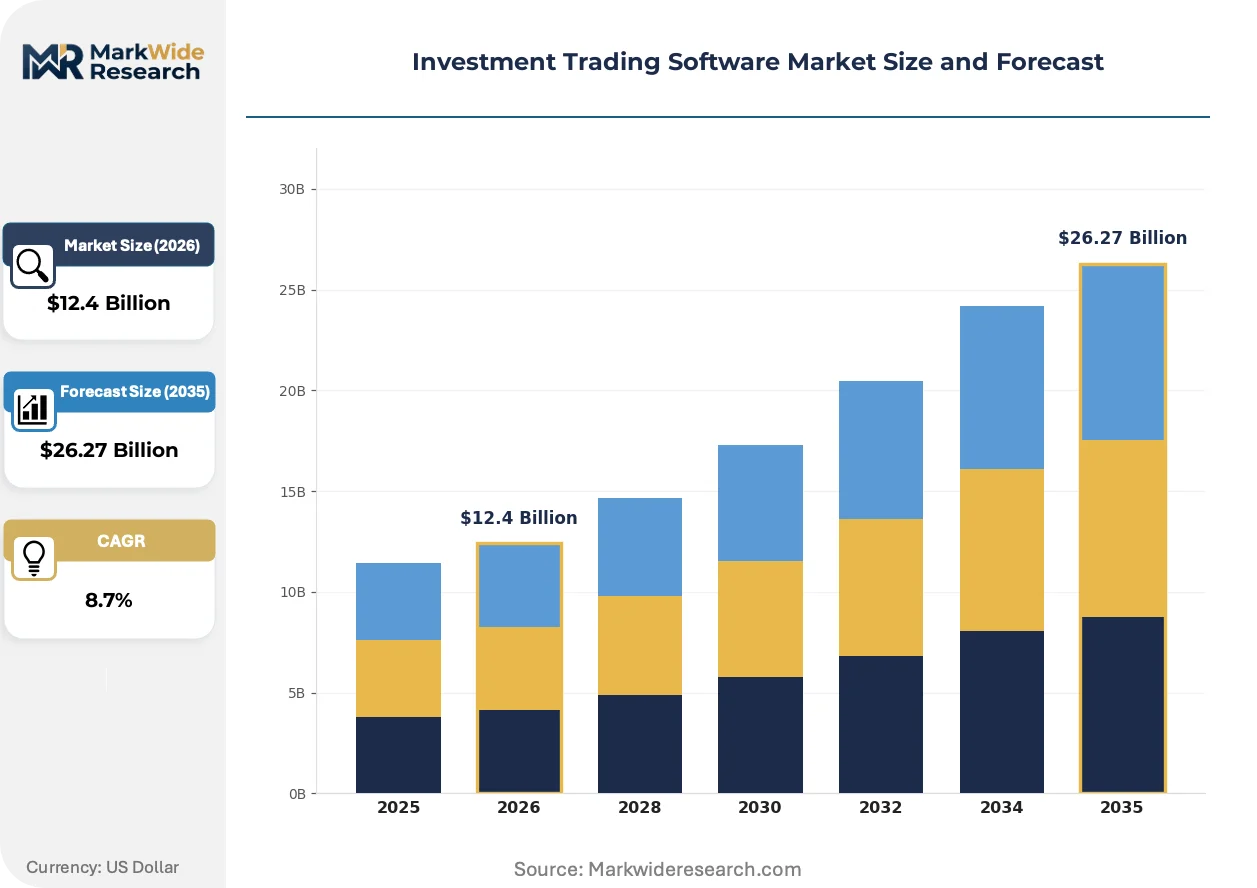
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Retail Investors, Institutional Investors, Hedge Funds, Brokers Solution: Execution Software, Risk Management, Portfolio Management, Analytics Service Type: Trading Platforms, Market Data Services, Support Services, Compliance Solutions |
| Companies Covered | Interactive Brokers, Charles Schwab, Fidelity, E*TRADE, Robinhood, Webull, Oracle, SAP, HCLTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Investment Trading Software Market Trends and Innovations
Algorithmic decision-making is migrating from proprietary black-box systems to transparent, configurable frameworks that satisfy emerging regulatory scrutiny. This shift reconfigures competitive advantage from pure speed to auditability and explainability.
Microservices-based execution engines are decomposing monolithic trading architectures into discrete, containerized functions for order routing, risk checks, and market data normalization. Tier-two broker-dealers adopt these modular systems to bypass multi-year vendor implementation cycles. The decomposition enables selective component replacement without platform-wide overhaul, compressing upgrade timelines from quarters to weeks.
The EU AI Act's risk classification framework for algorithmic trading systems imposes documentation and human oversight requirements on high-frequency strategies. European operators must maintain algorithmic logs and conduct regular stress testing against market manipulation scenarios. Asset managers deploying systematic strategies face expanded compliance costs that favor vendors with pre-built audit trail modules.
Self-directed investors now expect research and execution tools previously reserved for institutional desks, compressing the feature gap between retail and professional platforms. Robo-advisory channels unbundle from pure allocation engines to incorporate active trading modules with tax-loss harvesting. This demand rotation is most visible in the United States, where IRA contribution flows increasingly route through brokerage rather than mutual fund direct channels.
Investment Trading Software Market Segmentation
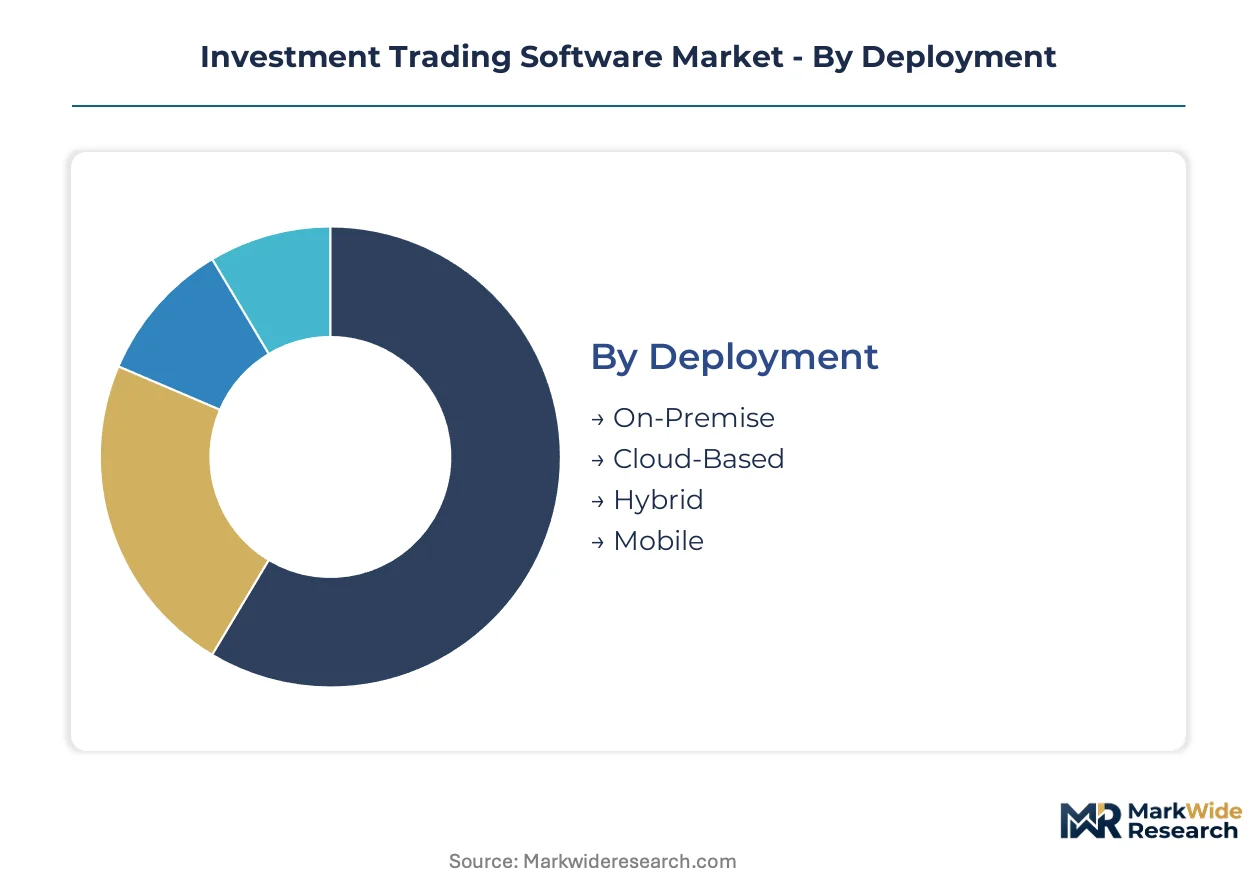
Trading software vendors architect product portfolios around deployment economics, user sophistication, and regulatory workload intensity. Segment boundaries increasingly blur as cloud elasticity enables modular service bundling across investor types.
Deployment:
Margin pools concentrate in cloud-native infrastructure where consumption-based pricing replaces capital-intensive data center commitments.
- Cloud-Based:Elastic compute scaling supports volatile trading volumes without fixed overhead. Broker-dealers in the United States dominate adoption, driven by SEC audit trail mandates requiring scalable order lifecycle storage.
- On-Premise:Latency-sensitive strategies demand co-located hardware at exchange matching engines. Specialized high-frequency operations sustain this segment despite shrinking share.
- Hybrid:Combines cloud analytics with on-premise execution for risk-controlled flexibility. Mid-tier broker-dealers favor this architecture for gradual migration paths.
- Mobile:Smartphone-native interfaces capture self-directed retail flows. Fractional share trading and push-alert execution drive volume concentration.
The dominant share belongs to Cloud-Based deployment, while Mobile is closing the gap fastest.
End User:
Commercial significance tracks regulatory burden complexity and trade size distribution across participant categories.
- Brokers:Multi-venue order routing and client segregation compliance create sustained platform investment. FINRA surveillance obligations in the United States drive recurring software refresh cycles.
- Institutional Investors:Block execution algorithms and transition management workflows require customized infrastructure. Pension funds and asset managers concentrate demand.
- Hedge Funds:Systematic strategies demand low-latency data feeds and proprietary alpha generation tools. Quantitative talent scarcity limits vendor switching velocity.
- Retail Investors:Zero-commission brokerage expansion democratizes access to tools once reserved for professionals. IRA contribution flows increasingly route through self-directed channels.
Brokers command the largest installed base, though Retail Investors are expanding most quickly.
Solution:
Revenue concentration follows regulatory touchpoints and algorithmic intensity in trading operations.
- Execution Software:Order routing engines process FIX protocol messages across fragmented liquidity venues. Sub-millisecond latency requirements sustain premium pricing for direct market access modules.
- Risk Management:Pre-trade credit checks and position limit surveillance prevent regulatory breaches. Real-time margin calculation demands dominate institutional procurement.
- Portfolio Management:Rebalancing engines and tax-loss harvesting modules integrate advisory and self-service workflows. Robo-advisory convergence expands addressable market.
- Analytics:Quantitative research platforms and alternative data integration support systematic strategy development. Python-based backtesting frameworks gain adoption.
Execution Software retains the dominant position, while Analytics gains share fastest.
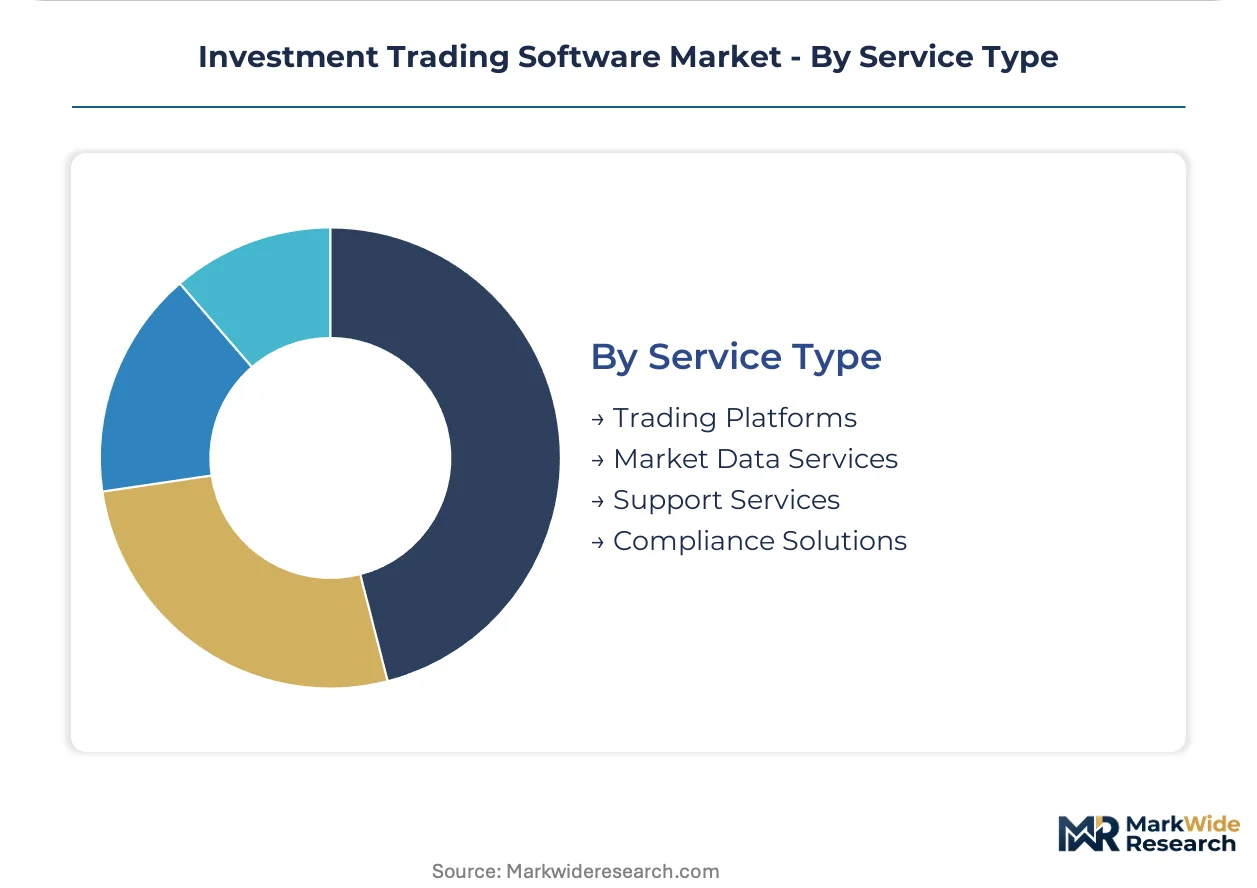
Service Type:
Customer lifetime value correlates with data feed stickiness and compliance workflow embedding.
- Trading Platforms:Integrated order entry, charting, and account management form the core brokerage interface. API extensibility differentiates vendor offerings.
- Market Data Services:Normalized pricing feeds from exchanges and alternative venues require expensive licensing. Consolidated tape products compete with direct exchange connections.
- Compliance Solutions:Post-trade reporting and surveillance automation address SEC Rule 613 and FINRA requirements. Audit trail completeness determines vendor selection.
- Support Services:Implementation consulting and ongoing technical assistance reduce internal IT burden. Cloud migration projects drive consulting attach rates.
Trading Platforms hold the dominant share, while Compliance Solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates demand for cloud-native execution infrastructure, while European markets prioritize MiFID II-compliant audit frameworks and Asian markets emphasize mobile-first retail penetration at lower price points.
United States
SEC Rule 613 Consolidated Audit Trail mandates and zero-commission brokerage expansion drive sustained platform investment. FINRA surveillance requirements compel broker-dealers to maintain comprehensive order lifecycle tracking systems. New York and Chicago financial centers host dense clusters of execution technology vendors serving both retail and institutional channels.
United Kingdom
Post-Brexit regulatory divergence from EU frameworks creates demand for dual-compliance trading architectures. The Financial Conduct Authority's market abuse surveillance guidelines shape vendor procurement criteria for London-based asset managers. The City of London remains a concentration point for FX and derivatives execution technology development.
Germany
EU AI Act algorithmic trading risk classifications impose documentation and human oversight requirements on Frankfurt-based systematic strategies. BaFin's implementation of MiFID II best execution standards drives compliance solution procurement. The Frankfurt Rhine-Main metropolitan area anchors continental Europe's largest concentration of institutional trading infrastructure.
Japan
FSA pressure to accelerate T+2 settlement cycles toward T+1 creates demand for real-time clearing integration modules. METI's fintech sandbox initiatives enable pilot deployments of distributed ledger-based settlement infrastructure. Tokyo's Otemachi financial district houses dense concentrations of broker-dealer technology operations serving regional pension fund flows.
India
SEBI's mandate for interoperability between exchanges and accelerated settlement timelines drives retail brokerage platform modernization. The RBI's digital payment infrastructure expansion enables smartphone-native trading penetration beyond metropolitan centers. Mumbai's Bandra-Kurla Complex and Bangalore's Electronic City host emerging clusters of cloud-native trading technology development.
Investment Trading Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in trading software, with scale advantages in clearing integration and regulatory compliance separating the two levels. The upper tier commands premium positioning through captive order-routing technology and direct market access infrastructure. Strategic archetypes include full-service wealth-integrated platforms, pure-play retail brokerages with zero-commission models, and enterprise software vendors supplying execution modules to financial institutions. Competitive moves concentrate on API ecosystem expansion and cloud migration partnerships that compress implementation timelines for mid-tier broker-dealers.
Within the integrated platform tier, Interactive Brokers and Charles Schwab exemplify divergent approaches to capturing self-directed investor flows, while Fidelity anchors the research-intensive advisory channel. Interactive Brokers represents the direct market access archetype with proprietary order-routing infrastructure spanning multiple asset classes. Charles Schwab occupies a position at the intersection of advisory services and self-directed trading workflows. Fidelity exemplifies the research-anchored model where fractional share capabilities and tax-loss harvesting modules extend retail capture rates. These three entities collectively illustrate how competitive positioning in trading software now depends on workflow integration depth rather than execution speed alone.
| Leading Market Players |
|---|
| Interactive Brokers |
| Charles Schwab |
| Fidelity |
| E*TRADE |
| Robinhood |
| Webull |
| Oracle |
| SAP |
| HCLTech |
| Others |
Pricing and Supply Chain Analysis
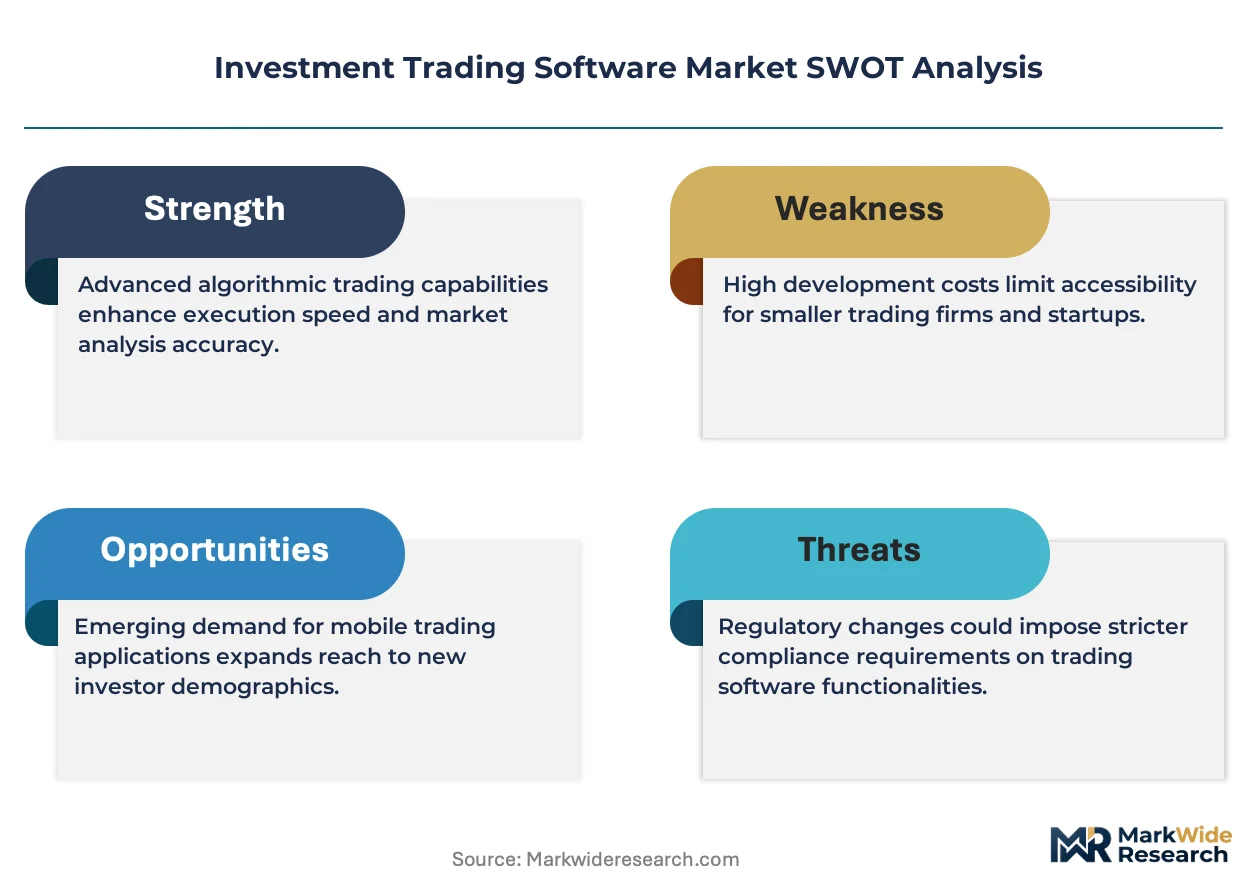
SEC Rule 613 Consolidated Audit Trail compliance gates both vendor qualification and price stratification in trading software procurement, forcing broker-dealers to absorb premium costs for audit-ready cloud infrastructure while squeezing margins on legacy on-premise maintenance contracts.
Pricing Analysis
Long-term SaaS subscriptions dominate trading software contracting, with consumption-based pricing replacing perpetual licenses as broker-dealers shift from fixed data center commitments to elastic compute scaling. Three-tier pricing structure across premium, standard, and economy levels separates institutional-grade execution modules with sub-millisecond latency guarantees from mid-tier hybrid deployments and basic retail brokerage interfaces. Cost compression in the economy tier is intensifying because cloud-native entrants undercut legacy vendors on implementation timelines. Retail broker-dealers exhibit highest price sensitivity due to zero-commission margin pressure, while hedge funds accept premium pricing for proprietary alpha-generation toolkits.
Supply Chain Analysis
Inbound logistics costs for co-located server hardware at exchange matching engines fluctuate with port congestion at Shanghai and Shenzhen, where specialized networking equipment for kernel-bypass architectures originates. Supply concentrates in the United States for cloud-native development talent, Taiwan for semiconductor components in low-latency hardware, and Ireland for EU regulatory compliance engineering. Raw material dependencies span FPGA chips from Xilinx, high-frequency networking gear from Mellanox, and FIX protocol middleware licenses. Single-source vulnerability persists in DTCC clearing integration modules. Distribution runs through direct enterprise sales teams for institutional clients and API marketplace partnerships for retail-facing platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Trading software demand follows capital markets transaction cyclicality, with platform investment accelerating during retail self-direction surges and institutional rebalancing waves.
For Market Incumbents: Fortify regulatory compliance moats by pre-building SEC Rule 613 and EU AI Act audit trail modules before enforcement deadlines tighten. Deepen captive order-routing technology through backward integration into exchange co-location infrastructure. Cloud-native entrants with API-first architectures threaten installed base stickiness. For New Entrants and Emerging Players: SOC 2 Type II certification fast-tracks procurement with mid-tier broker-dealers lacking internal compliance engineering. White-space concentrates in Brazil's B3 exchange and India's NSE retail infrastructure, where smartphone-native trading penetration lags US benchmarks. Embedded finance partnerships with neobank platforms bypass traditional broker-dealer channel costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed execution technology vendors carrying 2018-2021 vintage cloud migration debt. Long-term viability hinges on T+0 settlement infrastructure readiness as DTCC distributed ledger pilots advance. Monitor real-time clearing integration contract wins as the inflection signal distinguishing acquisition targets from stranded legacy plays.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Open FIX protocol extensions enable third-party developers to build customized workflows atop established clearing infrastructure. |
| Cloud Migration Partnership | Strategic alliances with hyperscalers compress implementation timelines for mid-tier broker-dealers abandoning data centers. |
| Regulatory Compliance Pre-Build | Pre-constructed SEC Rule 613 and EU AI Act modules accelerate procurement cycles with audit-constrained buyers. |
| Embedded Finance Integration | Banking-as-a-Service partnerships distribute trading modules through neobank and fintech super-app channels. |
| Real-Time Settlement Infrastructure | T+0 compatible clearing interfaces capture early-mover advantage as DTCC pilots distributed ledger settlement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with broker-dealer CTOs, exchange technology officers, regulatory compliance leads, and cloud infrastructure procurement managers. Secondary validation drew from SEC Rule 613 implementation filings, FINRA surveillance guidance updates, DTCC clearing infrastructure disclosures, and hyperscaler financial services vertical revenue reports. Bottom-up vendor revenue triangulation against top-down capital markets IT spending estimates anchored market sizing.
Across the analysis window, forecasts model deployment mode transitions, end-user segment growth differentials, and solution category expansion patterns. Segmentation dimensions span cloud-native versus hybrid architectures, retail versus institutional user bases, and execution versus analytics solution mixes. CAGRs derive from elasticity-adjusted adoption curves and regulatory mandate implementation schedules. Forecast inputs incorporate exchange trading volume trajectories and clearing infrastructure modernization timelines.
Underlying assumptions cover sustained retail self-direction trends and cloud migration acceleration, with deviation risk concentrated in interest rate shocks dampening trading volumes and regulatory delay postponing compliance procurement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Reverse Factoring Market
Financial Services
Capital Restructuring Services Market
Financial Services
ATM Management Service Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Financial Services Software Market
Financial Services
Virtual Account Management Software Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
Currency Management Market
Financial Services
Online Investment Platform Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
India Payroll Services Market
Financial Services
North America B2B Legal Services Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Trade Finance Market
Financial Services
Hyperinflation System Market