
 Asia-Pacific Used Car Financing Market | 2026-2036
Asia-Pacific Used Car Financing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Used Car Financing Market Outlook
India's PLI scheme for automotive manufacturing is decoupling used car residual values from new vehicle price volatility, which redraws the cost-of-entry calculus for financiers entering the collateral-backed lending space. HDFC Bank Ltd leverages its branch density across 3,000-plus Indian towns to sustain origination leadership in dealer financing partnerships. Cholamandalam Investment and Finance Company Limited anchors its southern India stronghold with captive used vehicle appraisal infrastructure that reduces default recovery costs. Bajaj Finserv competes through digital-first underwriting that compresses loan disbursement timelines to under 48 hours.
Used car financing encompasses secured and unsecured lending instruments collateralized by pre-owned passenger vehicles, commercial transport assets, and two-wheelers, with loan-to-value ratios typically calibrated against depreciated manufacturer suggested retail prices and independent inspection assessments. The primary commercial purpose is to convert illiquid automotive assets into tradable credit instruments while generating interest income spreads over benchmark rates. Dealer financing occupies the dominant structural position across the Asia-Pacific landscape because original equipment manufacturer-certified pre-owned programs standardize vehicle condition documentation and streamline lender due diligence. Personal loans represent the fastest-growing financing type as fintech platforms disintermediate traditional branch-based origination with algorithmic credit scoring that incorporates alternative data streams such as utility payments and mobile wallet histories.
The Reserve Bank of India governs non-banking financial company capital adequacy and exposure norms that directly constrain Mahindra Finance and Sundaram Finance Ltd lending books, while China's National Financial Regulatory Administration supervises auto finance company leverage limits including BYD Auto Finance Company Limited and Changan Auto Finance Co. Ltd. BIS certification requirements for vehicle valuation equipment in India add compliance costs to lender-operated inspection networks but simultaneously reduce information asymmetry between borrowers and underwriters. Stakeholders must monitor how regulatory technology mandates reshape origination economics as central banks across the region impose granular data reporting on subprime and flexible-term loan performance.
Market Dynamics
Digital underwriting platforms are compressing loan origination timelines from weeks to hours across Southeast Asian markets, fundamentally altering how lenders compete for first-time car buyers outside traditional branch networks.
Growth Catalysts
- PLI Scheme for Automotive Manufacturing:India's production-linked incentive program is strengthening residual value confidence for pre-owned vehicles. Lenders now deploy more aggressive collateral assessment models in tier-2 and tier-3 cities.
- First-Time Buyer Expansion:Indonesia and Vietnam are generating origination volume growth as formal credit penetration extends beyond urban centers. Digital platforms capture borrowers previously excluded by branch-based underwriting.
- Algorithmic Credit Scoring:Fintech platforms incorporate mobile wallet histories and utility payment data into risk models. Alternative data streams expand addressable borrower pools without traditional credit bureau files.
Market Restraints
- Steel Price Volatility:Input cost fluctuations for vehicle manufacturing create residual value uncertainty. Lenders must recalibrate loan-to-value ratios quarterly to protect collateral coverage.
- RBI Capital Adequacy Norms:India's central bank imposes exposure limits on non-banking financial companies that constrain balance sheet expansion. Mahindra Finance and Sundaram Finance face binding capital constraints during high-growth periods.
- Used Vehicle Information Asymmetry:Inconsistent condition documentation across independent dealers elevates default recovery costs. Lenders operating without captive appraisal infrastructure bear higher due diligence burdens.
Strategic Opportunities
- Vietnam's Underpenetrated Tier-3 Cities:Formal financing penetration remains below fifteen percent in provincial automotive markets. Early entrants can establish dealer financing relationships before incumbent banks extend branch networks.
- Two-Wheeler Financing Convergence:Commercial transport assets and personal mobility vehicles share increasingly standardized digital underwriting infrastructure. Platforms built for passenger cars are adapting algorithms for motorcycle collateral assessment.
- BIS Certification Mandates:India's Bureau of Indian Standards requirements for vehicle valuation equipment reduce information asymmetry. Compliant lenders gain competitive advantage in borrower trust and regulatory inspection readiness.
Industry Challenges
- Legacy Core System Integration:Traditional financiers must reconcile decades-old loan management platforms with real-time digital origination interfaces. API-layer solutions introduce latency and reconciliation errors during high-volume disbursement periods.
- Field Appraiser Certification Bottlenecks:BIS-compliant valuation equipment requires trained operators, but certification programs produce insufficient talent pipeline. Lenders face six-month hiring delays for qualified inspection personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Used Car Financing Market |
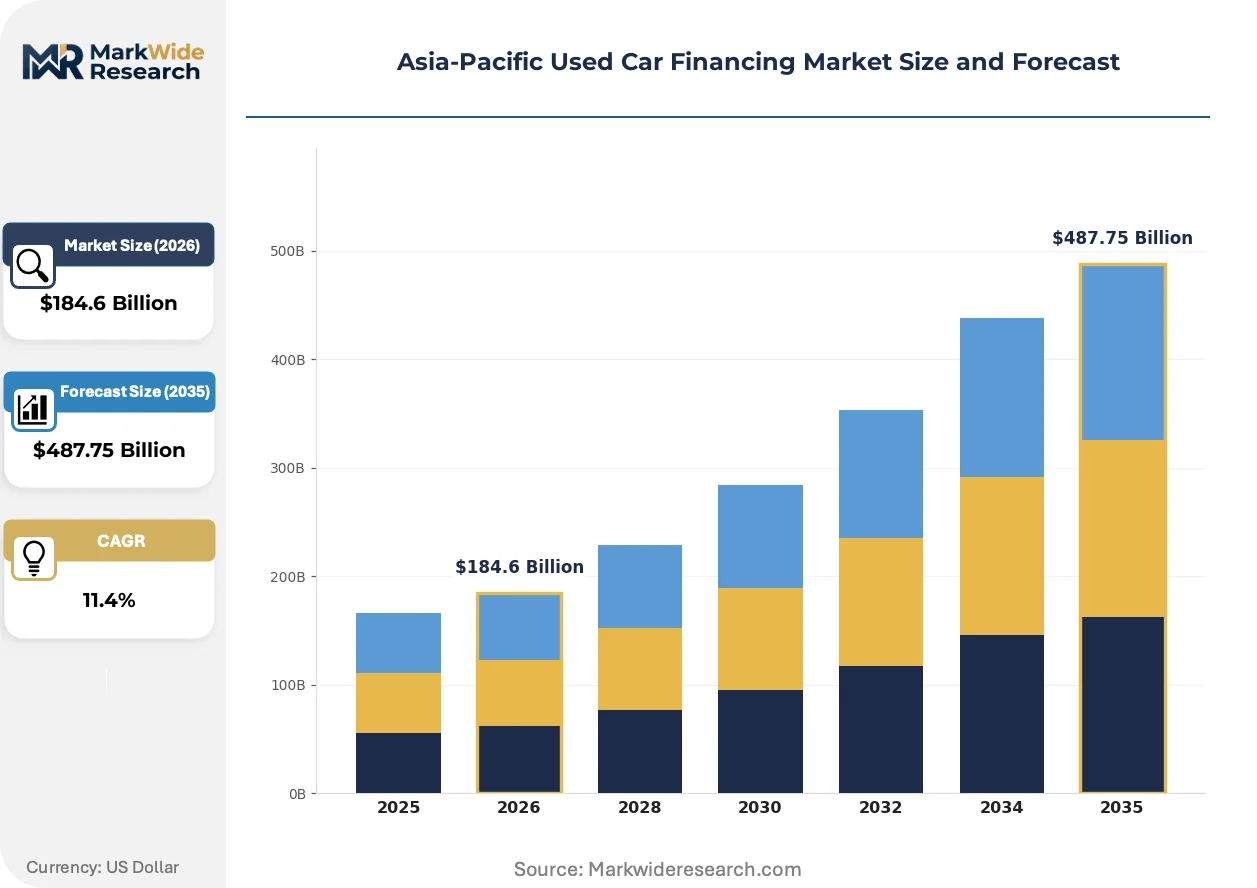
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $487.75 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Financing Type: Personal Loans, Dealer Financing, Credit Unions, Peer-to-Peer Lending Customer Segment: Individuals, Small Businesses, B2B Resellers, Fleet Operators Loan Term: Short-Term, Medium-Term, Long-Term, Flexible-Term Credit Type: Secured Loans, Unsecured Loans, Subprime Loans, Prime Loans |
| Companies Covered | The Bank of China, Sundaram Finance Ltd, HDFC Bank Ltd, Cholamandalam Investment and Finance Company Limited, BYD Auto Finance Company Limited, Mahindra Finance, Bajaj Finserv, Changan Auto Finance Co. Ltd, Ford Motor Credit Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Used Car Financing Market Strategic Shifts
API-based loan origination stacks are displacing monolithic banking platforms across the Asia-Pacific used car financing landscape, enabling modular assembly of credit decision engines from specialized vendors.
Telematics-enabled collateral monitoring is modularizing risk management for commercial vehicle portfolios. Fleet operators in Indonesia and Vietnam now adopt GPS-integrated financing packages that transmit real-time asset location and utilization data. Lenders compress insurance premiums and tighten recovery timelines through continuous collateral visibility rather than periodic physical inspection.
RBI's granular data reporting mandates for subprime and flexible-term loan performance are forcing portfolio transparency upgrades. Non-banking financial companies must restructure data warehouses to capture forty-plus fields per loan for regulatory submission. Smaller lenders without captive technology teams are outsourcing compliance infrastructure to cloud-native regtech providers.
Dealer financing partnerships are fragmenting as direct-to-consumer digital platforms capture borrower relationships. OEM-certified pre-owned programs in India and China still dominate standardized documentation, but fintech originators now disintermediate dealers entirely in used vehicle transactions. First-time buyers in Philippine provincial markets increasingly complete full loan applications through mobile interfaces before visiting showrooms.
Asia-Pacific Used Car Financing Market Segmentation
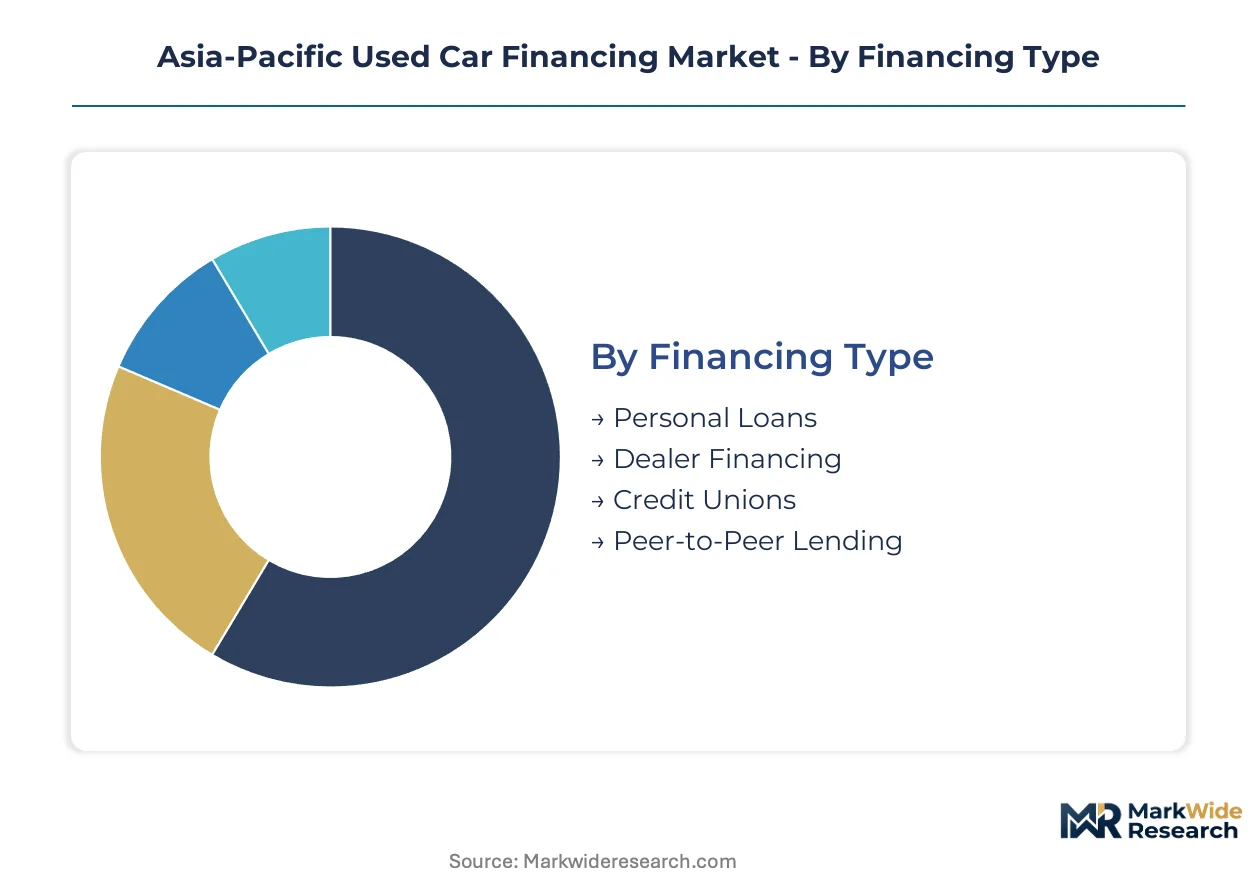
Financing type and customer segment classifications determine origination infrastructure requirements across Asia-Pacific markets. Lenders configure underwriting algorithms, dealer partnerships, and capital allocation differently for each segment combination.
Financing Type:
Technology deployment intensity varies by origination channel sophistication.
- Personal Loans:Fintech platforms deploy algorithmic credit scoring with alternative data streams including mobile wallet histories and utility payments. Demand concentrates in Indonesia and Vietnam where first-time buyers outside branch networks seek sub-48-hour disbursement timelines. Digital-first underwriting is displacing traditional documentation requirements.
- Dealer Financing:OEM-certified pre-owned programs standardize vehicle condition documentation through captive appraisal infrastructure. HDFC Bank leverages branch density across 3,000-plus Indian towns to sustain origination leadership in dealer partnerships. Collateral assessment models rely on manufacturer residual value confidence.
- Credit Unions:Member-owned structures in Australia and South Korea emphasize relationship-based underwriting with lower interest rate spreads.
- Peer-to-Peer Lending:Platform-mediated matching connects retail investors with borrowers, operating primarily in regulatory sandbox environments in Singapore and Malaysia.
Mature deployment sits with Dealer Financing. Newer deployment is concentrated in Personal Loans.
Customer Segment:
Application use case drives collateral monitoring intensity and recovery cost structures.
- Individuals:First-time car buyers in India's tier-2 and tier-3 cities generate volume growth as formal credit penetration remains comparatively low. RBI capital adequacy norms constrain non-banking financial company balance sheet expansion during high-growth periods.
- Fleet Operators:Commercial transport assets require telematics-enabled collateral monitoring with GPS-integrated financing packages transmitting real-time asset location. Indonesia and Vietnam fleet operators compress insurance premiums through continuous visibility rather than periodic inspection.
- Small Businesses:Mixed-use vehicle financing blends personal mobility with commercial transport, creating hybrid risk profiles.
- B2B Resellers:Inventory floorplan financing supports dealer working capital with revolving credit structures against vehicle stock.
Volume concentration favors Individuals. Margin expansion potential sits with Fleet Operators.
Loan Term:
Duration calibration reflects residual value depreciation curves and borrower cash flow patterns.
- Short-Term:12-24 month structures align with two-wheeler collateral lifecycles and commercial vehicle replacement cycles in Vietnam's provincial markets.
- Medium-Term:36-48 month passenger vehicle financing dominates India and China origination volumes with standardized EMI structures.
- Long-Term:60-72 month structures for prime borrowers with established credit bureau files and stable employment documentation.
- Flexible-Term:Seasonal repayment schedules match agricultural income patterns in India's rural markets. RBI granular data reporting mandates force portfolio transparency upgrades for these structures.
Standardized deployment centers on Medium-Term. Customization complexity clusters in Flexible-Term.
Credit Type:
Risk tiering determines capital allocation intensity and regulatory scrutiny levels.
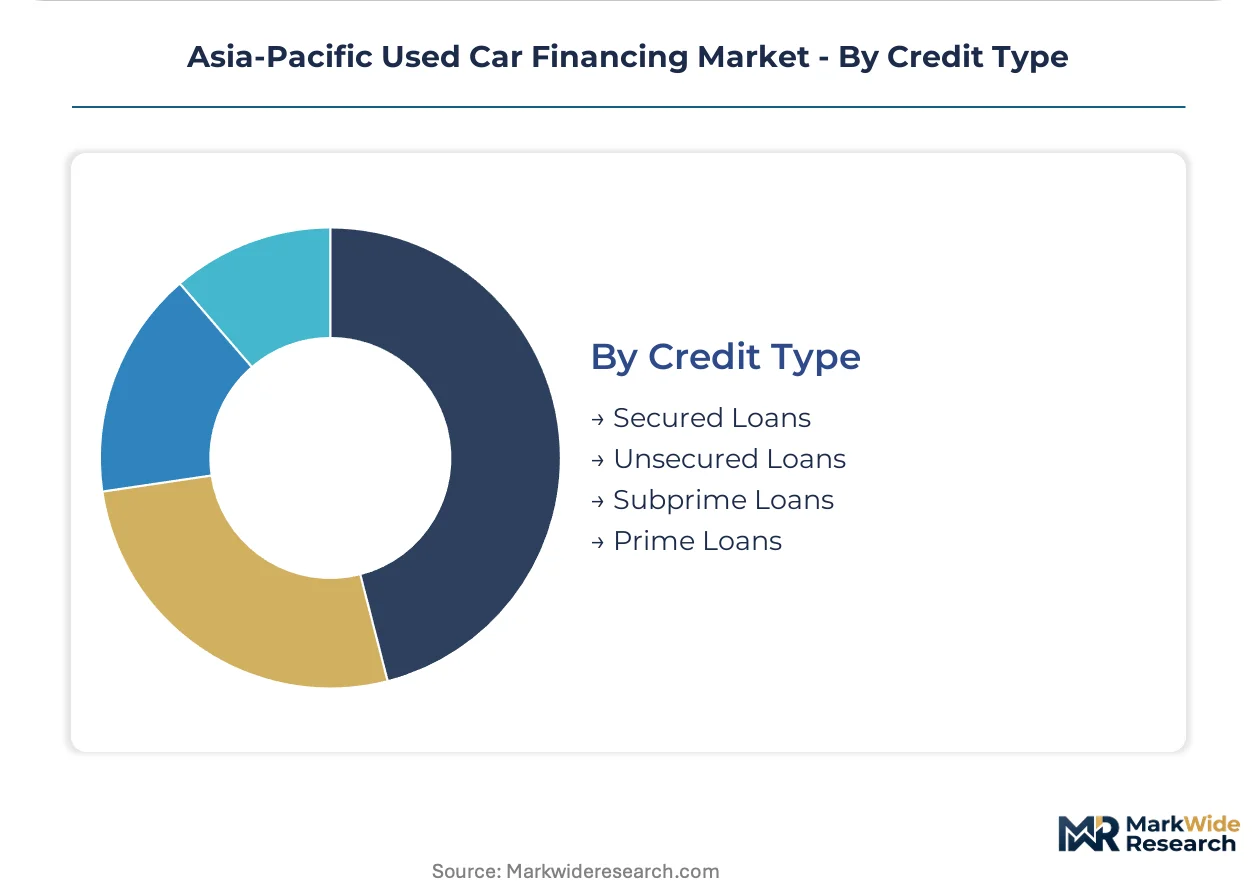
- Secured Loans:Collateral-backed instruments with loan-to-value ratios calibrated against depreciated manufacturer suggested retail prices and independent inspection assessments. BIS certification requirements for vehicle valuation equipment in India add compliance costs but reduce information asymmetry.
- Subprime Loans:Alternative data streams including mobile wallet histories expand addressable borrower pools without traditional credit bureau files. Steel price volatility creates residual value uncertainty requiring quarterly loan-to-value recalibration.
- Unsecured Loans:Personal credit extensions without vehicle collateral command higher interest rate spreads.
- Prime Loans:Established credit bureau files with conventional documentation and lowest default probability.
Capital efficiency peaks with Secured Loans. Addressable market expansion concentrates in Subprime Loans.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for automotive manufacturing creates concentrated financing demand across its tier-2 and tier-3 industrial corridors. Special economic zones in Vietnam and Indonesia channel first-time buyer origination into digital underwriting platforms.
India
HDFC Bank leverages branch density across 3,000-plus towns to sustain dealer financing partnerships in tier-2 cities. RBI capital adequacy norms constrain non-banking financial company balance sheet expansion during high-growth periods. Maharashtra and Gujarat industrial corridors concentrate captive appraisal infrastructure that reduces default recovery costs.
China
BYD Auto Finance and Changan Auto Finance dominate OEM-certified pre-owned programs with standardized vehicle condition documentation. SAMR leverage limits shape auto finance company capital allocation across the Yangtze River Delta. Shanghai and Shenzhen clusters drive telematics-enabled collateral monitoring for commercial vehicle portfolios.
Vietnam
Formal financing penetration below fifteen percent in provincial automotive markets generates origination volume growth. The country's central bank supervises digital platform expansion beyond traditional branch networks. Ho Chi Minh City and Hanoi corridors concentrate fintech algorithmic credit scoring with mobile wallet data integration.
Indonesia
First-time car buyers outside urban centers drive demand for sub-48-hour disbursement timelines. National financial regulators impose exposure limits on multi-finance companies that constrain lending book expansion. Jakarta and Surabaya industrial zones anchor GPS-integrated financing packages for fleet operators.
Australia
Credit unions emphasize relationship-based underwriting with lower interest rate spreads in member-owned structures. ASIC disclosure requirements govern alternative data stream usage in algorithmic credit models. Sydney and Melbourne metropolitan clusters concentrate peer-to-peer lending platform development in regulatory sandbox environments.
Asia-Pacific Used Car Financing Market Competitive Environment
Indian financiers anchor one tier; Chinese auto-captive specialists hold another. The market structures around three distinct player categories: universal banks with dense branch networks, non-banking financial companies with captive appraisal infrastructure, and OEM-captive auto finance subsidiaries. Consolidation pressures favor scale-driven originators with integrated inspection capabilities. Strategic moves center on API-layer technology partnerships and telematics-enabled collateral monitoring deployment.
Among Indian non-banking financial companies, Cholamandalam Investment and Finance Company Limited and Mahindra Finance exemplify the captive infrastructure archetype with southern and rural strongholds respectively. Bajaj Finserv occupies a position within the digital-first underwriting tier, compressing loan disbursement timelines through algorithmic platforms. These three entities represent divergent competitive vectors: geographic density, sectoral specialization, and technology velocity.
| Leading Market Players |
|---|
| The Bank of China |
| Sundaram Finance Ltd |
| HDFC Bank Ltd |
| Cholamandalam Investment and Finance Company Limited |
| BYD Auto Finance Company Limited |
| Mahindra Finance |
| Bajaj Finserv |
| Changan Auto Finance Co. Ltd |
| Ford Motor Credit Company |
| Others |
Value Chain & Pricing Dynamics
Steel input costs transmit downstream through loan-to-value recalibration cycles, with quarterly repricing pressure from residual value uncertainty reshaping lender collateral models across India and Vietnam. This cost pathway splits financing offerings into premium-speed digital disbursement, standard dealer-anchored products, and economy-tier branch-based alternatives.
Pricing Analysis
Lead-time compression commands premium positioning, with sub-48-hour digital disbursement carrying wider interest spreads than branch-based alternatives requiring weeks. Pricing stratifies across premium algorithmic platforms, standard OEM-certified dealer programs, and economy-tier credit union offerings with relationship-based rate discounts. Cost compression in the economy tier is intensifying because BIS certification mandates add fixed compliance overhead to appraisal infrastructure. First-time buyers in provincial Indonesian markets exhibit highest price sensitivity, while fleet operators in Jakarta and Surabaya prioritize telematics integration over rate minimization.
Supply Chain Analysis
Single-source vulnerability sits with GPS telematics hardware concentrated in Chinese and South Korean manufacturing clusters, creating procurement risk for Indonesian and Vietnamese fleet financing packages. Vehicle valuation equipment draws from Indian domestic production under BIS certification requirements, with sensor components sourced from Japanese and Taiwanese electronics suppliers. Tariff exposure on semiconductor inputs threatens telematics-enabled collateral monitoring deployment timelines. Distribution runs through OEM-captive finance subsidiaries and non-banking financial company branch networks, with fintech platforms disintermediating traditional dealer channels in Philippine and Vietnamese urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scale-driven consolidation is accelerating as RBI capital adequacy norms force smaller non-banking financial companies into acquisition or exit, concentrating origination capacity among branch-dense universal banks and technology-integrated captives.
For Market Incumbents: Deploy captive appraisal infrastructure as the defensive anchor, expanding BIS-certified inspection networks into Vietnam's tier-3 cities before digital-native competitors establish algorithmic underwriting relationships. HDFC Bank and Cholamandalam Investment must accelerate API-layer partnerships to neutralize Bajaj Finserv's disbursement velocity advantage in personal loan segments. For New Entrants and Emerging Players: PLI scheme incentives in India open a window for residual value modeling specialization, targeting tier-2 city dealer financing relationships where formal credit penetration remains below comparable urban benchmarks. Vietnam's sub-fifteen-percent provincial financing penetration offers the most penetrable geography, with mobile wallet data integration as the decisive go-to-market wedge against branch-constrained incumbents. For Investors and Strategic Acquirers: Telematics-enabled portfolio scaling by Indonesian fleet operators is the leading indicator that collateral monitoring technology is crossing from premium to standard-tier deployment, signaling platform consolidation opportunity. Long-term viability favors acquirers of southern India captive infrastructure with inspection network density, with BIS certification completion rates as the critical inflection signal for operational readiness.| Strategic Initiative | Industry Significance |
|---|---|
| API-Layer Origination Partnership | Compresses disbursement timelines to under 48 hours for first-time buyers in tier-3 cities. |
| Telematics Infrastructure Deployment | Enables real-time collateral monitoring for Indonesian and Vietnamese commercial fleet portfolios. |
| BIS Certification Compliance Program | Reduces information asymmetry and accelerates regulatory inspection readiness across Indian operations. |
| Dealer Network Consolidation | Captures origination volume in underpenetrated tier-2 corridors before digital platforms disintermediate relationships. |
| Alternative Data Integration | Expands subprime addressable pools using mobile wallet and utility payment histories in Southeast Asia. |
Study Parameters
Multi-period observation of loan origination timelines, residual value depreciation curves, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with chief risk officers at non-banking financial companies, digital platform product heads, dealer operations managers, and RBI compliance leads. Secondary validation drew from central bank exposure norm circulars, BIS equipment certification registries, vehicle registration databases, and auto finance company leverage disclosures. Bottom-up origination volume modeling triangulated against top-down credit penetration benchmarks by geography.
Segment-weighting across financing type, customer segment, loan term, and credit type dimensions structured the analytical framework, with CAGRs derived from fitted growth curves calibrated to observed origination velocity shifts. Alternative data adoption rates, PLI scheme implementation phases, and telematics penetration curves served as industry-specific forecast inputs throughout the projection horizon.
The model assumes a particular technology adoption path for algorithmic underwriting platforms; alternative pathways for legacy core system modernization would alter the outlook for incumbent competitive positioning. Forecasts reflect assumptions on regulatory technology mandate pacing and residual value confidence stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
Canada Student Loan Market
Loans and Leasing
Student Loan Market
Loans and Leasing
UK Car Loan Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Enterprise Asset Leasing Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Digital Lending Platform Market
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
United Kingdom Auto Loan Market