
 China Factoring Services Market | 2026-2036
China Factoring Services Market Size, Share, and Industry Trends Forecast 2026-2036
China Factoring Services Market Insights
Modular service bundling is broadening buyer choice across the China factoring landscape. ICBC China Limited leverages its state-backed balance sheet to anchor large-ticket domestic factoring. China Merchants Bank competes through digital onboarding platforms that reduce documentation friction for mid-market clients. Agricultural Bank of China Limited extends its rural branch network to occupy agricultural supply chain financing corridors others underserve.
China factoring services encompass the purchase of trade receivables at a discount, where specialized financiers assume collection risk against invoices typically maturing within 90 to 180 days, providing immediate liquidity to sellers without balance sheet debt recognition. Recourse factoring dominates transaction volume among state-owned banks due to lower capital reserve requirements, while non-recourse factoring captures widening margin pools as private insurers develop domestic trade credit risk models. Small and medium enterprises represent the fastest-growing client segment as regulatory pressure on informal lending channels redirects borrowers toward licensed factoring arrangements.
SAMR licensing requirements and PBOC macro-prudential guidelines on supply chain finance shape product structures and capital adequacy thresholds for market participants. The dual carbon goals are filtering into sectoral eligibility criteria, with green supply chain receivables receiving preferential rediscount windows. Stakeholders must monitor how NMPA-style data governance standards migrate into financial services, determining which platforms can sustain automated invoice verification at scale.
Market Dynamics
Regulatory pressure from SAMR licensing and PBOC macro-prudential guidelines is compressing informal lending channels, redirecting SME working capital demand toward licensed factoring arrangements and reshaping competitive positioning among state-backed and private financiers.
Growth Catalysts
- Dual carbon goals:Green supply chain receivables now access preferential rediscount windows through the People's Bank of China, accelerating adoption among export-oriented manufacturers seeking lower-cost working capital.
- Yangtze River Delta concentration:Export-oriented manufacturers cluster around Shanghai, creating dense invoice volumes that attract specialized factoring servicers and reduce due diligence unit costs.
- Blockchain verification:Distributed ledger technology is streamlining invoice authentication processes, reducing documentation friction for mid-market clients and compressing onboarding timelines.
Market Restraints
- Trade credit insurance scarcity:Domestic underwriters lack mature risk models for non-recourse factoring, limiting margin expansion beyond state-owned bank recourse products.
- Rural branch network gaps:Agricultural supply chains in western provinces remain underserved due to physical infrastructure concentration in coastal manufacturing belts.
- NMPA-style data governance migration:Evolving data localization requirements are increasing compliance overhead for automated invoice verification platforms.
Strategic Opportunities
- Western province agricultural corridors:Rural supply chain financing remains underpenetrated, offering first-mover positioning for platforms with distributed collection capabilities.
- Convergence of IoT and trade finance:Sensor-enabled inventory monitoring is integrating with receivables financing, enabling dynamic credit limit adjustments based on real-time goods movement.
- SAMR streamlined licensing:Regulatory refinements on supply chain finance are reducing market access barriers for technology-enabled entrants.
Industry Challenges
- Automated verification talent scarcity:Platforms struggle to recruit data engineers capable of sustaining machine learning models for invoice fraud detection at scale.
- Legacy core banking integration:State-owned institutions face friction connecting modern digital onboarding platforms to decades-old settlement infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Factoring Services Market |
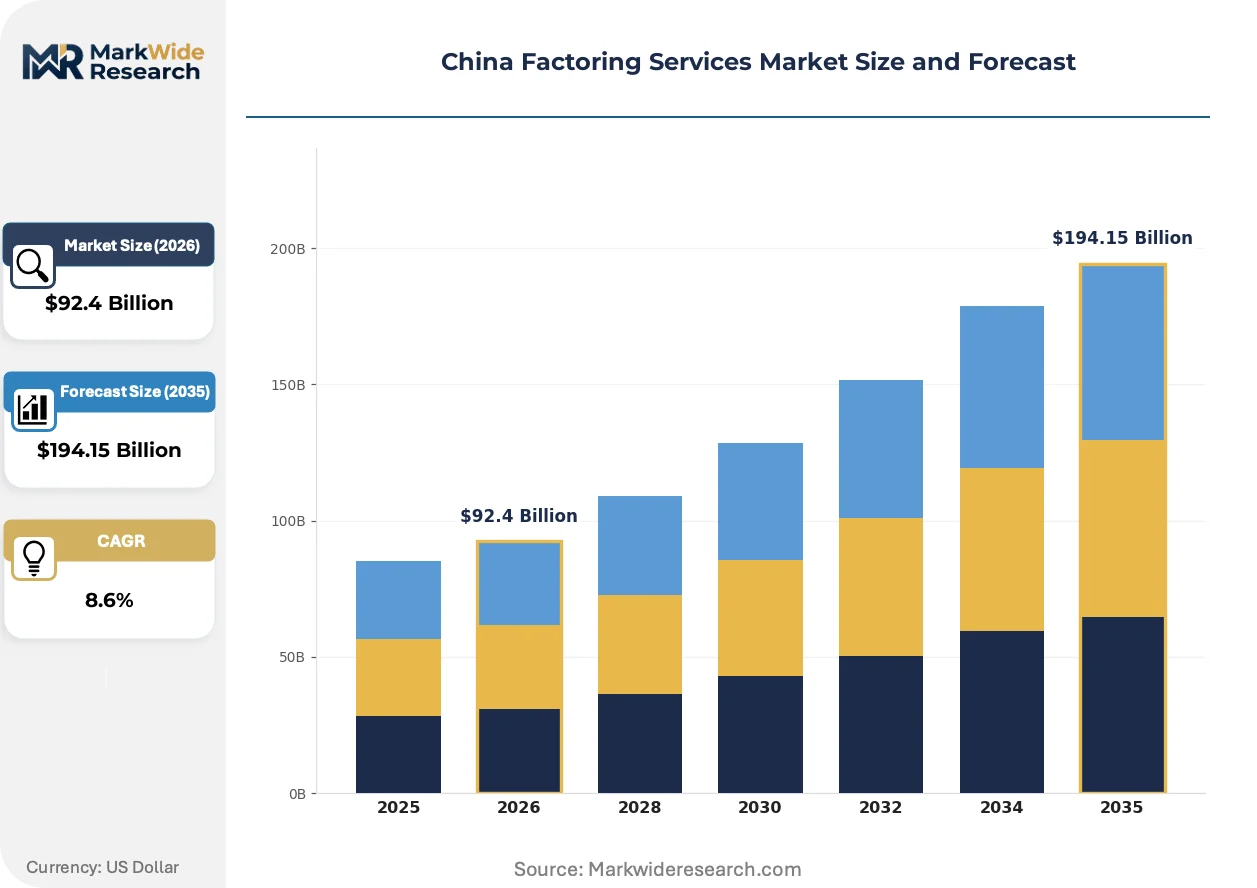
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $194.15 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recourse Factoring, Non-Recourse Factoring, Maturity Factoring, Invoice Discounting Client Type: Small Enterprises, Medium Enterprises, Large Enterprises, Freelancers, Exporters Industry Vertical: Manufacturing, Wholesale Trade, Construction, Transportation, Telecommunications Transaction Size: Below RMB 1 Million, RMB 1-5 Million, RMB 5-10 Million, Above RMB 10 Million |
| Companies Covered | Bank of China Limited, ICBC China Limited, Industrial and Commercial Bank of China, VTeam Financial Service, China Systems, China Construction Bank Corporation, China Merchants Bank, one PMF Capital, Agricultural Bank of China Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Factoring Services Market Trends and Innovations
Digital infrastructure investments are compressing documentation timelines and enabling real-time credit decisions, while regulatory data standards are determining which platforms can sustain automated operations.
Blockchain-based invoice verification is integrating trade documentation across multi-tier supply chains. Mid-market exporters in the Yangtze River Delta are adopting these platforms fastest, driven by pressure to reduce days sales outstanding. The technology is integrating previously siloed procurement and financing data, collapsing verification cycles from weeks to hours.
PBOC macro-prudential guidelines on supply chain finance are mandating enhanced disclosure standards for receivables-backed instruments. Industrial consequence includes elevated capital adequacy thresholds for non-bank factoring participants. Private insurers developing domestic trade credit risk models are most affected, responding by partnering with technology platforms for alternative data sourcing.
Buyer concentration among export-oriented manufacturers is compressing switching costs and intensifying price competition among servicers. Traditional relationship-based distribution through branch networks is losing share to API-enabled embedded finance integrations. This pattern is most visible in Guangdong and Jiangsu provinces, where manufacturing clusters demand seamless ERP-integrated liquidity solutions.
China Factoring Services Market Segmentation
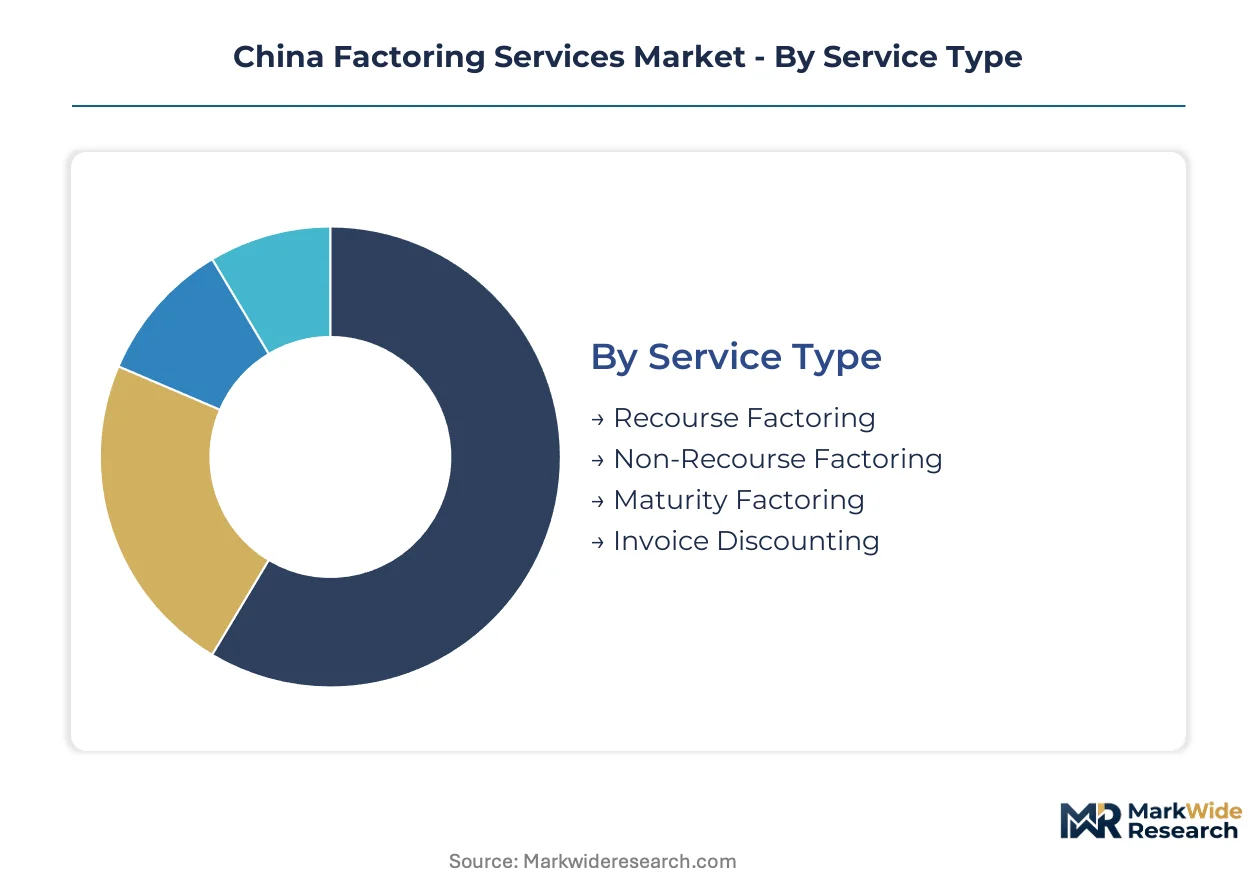
Service differentiation across the China factoring market reflects regulatory capital requirements and risk transfer preferences. SAMR licensing tiers and PBOC macro-prudential thresholds segment participants by balance sheet capacity and operational scope.
Service Type:
Recourse arrangements carry lighter SAMR capital reserve burdens than non-recourse products, shaping which institutions dominate each tier.
- Recourse Factoring:The financier retains collection rights against the seller if the debtor defaults, requiring minimal trade credit insurance overlay. State-owned banks anchor volume here due to lower capital adequacy thresholds under PBOC guidelines. Yangtze River Delta manufacturers favor this structure for working capital velocity.
- Non-Recourse Factoring:Credit risk transfers entirely to the factor, demanding sophisticated domestic risk models that private insurers are still developing. Margin pools widen as underwriting capabilities mature, though scarcity of mature trade credit models constrains expansion beyond coastal manufacturing belts.
- Maturity Factoring:Payment collection services without advance funding, suited to enterprises seeking administrative efficiency rather than liquidity.
- Invoice Discounting:Secured lending against receivables where the seller retains collection responsibility, blurring the line with traditional working capital finance.
Recourse Factoring sits at the top of the volume ranking, with Non-Recourse Factoring climbing the fastest.
Client Type:
Regulatory pressure on informal lending channels redirects borrower flows across enterprise size tiers, with licensing requirements filtering access.
- Small Enterprises:SAMR's streamlined licensing for supply chain finance has opened licensed channels previously blocked by documentation burdens. Agricultural supply chains in western provinces remain underserved due to branch network gaps.
- Medium Enterprises:Digital onboarding platforms from joint-stock banks reduce friction for this segment, with API-enabled ERP integrations gaining traction in Guangdong manufacturing clusters. Blockchain verification compresses onboarding timelines from weeks to hours.
- Large Enterprises:State-backed institutions anchor relationships through dedicated credit lines and multi-bank syndication capabilities.
- Freelancers:Platform economy workers generate invoice volumes too fragmented for traditional factoring economics, though gig-economy specialized servicers are emerging.
- Exporters:Cross-border receivables face dual regulatory compliance across SAMR and foreign exchange administration protocols.
Medium Enterprises command the deepest penetration rate, while Small Enterprises are expanding most quickly.
Industry Vertical:
Dual carbon goals filter eligibility criteria, with green supply chain receivables accessing preferential PBOC rediscount windows.
- Manufacturing:Export-oriented producers in Jiangsu and Zhejiang generate the densest invoice flows, attracting specialized servicers and compressing due diligence unit costs through scale. Green manufacturing certifications unlock lower-cost funding channels.
- Wholesale Trade:Inventory-heavy distributors leverage factoring to decouple payment cycles from goods movement, with IoT-enabled monitoring enabling dynamic credit limits.
- Construction:Extended project timelines and milestone-based billing create receivables maturity profiles stretching beyond standard 90-180 day windows.
- Transportation:Fleet operators and logistics providers face volatile fuel cost exposures that factoring stabilizes through predictable cash conversion.
- Telecommunications:Equipment procurement cycles and subscription receivables generate distinct documentation requirements from trade-focused verticals.
Manufacturing holds the dominant share position, with Wholesale Trade gaining share fastest.
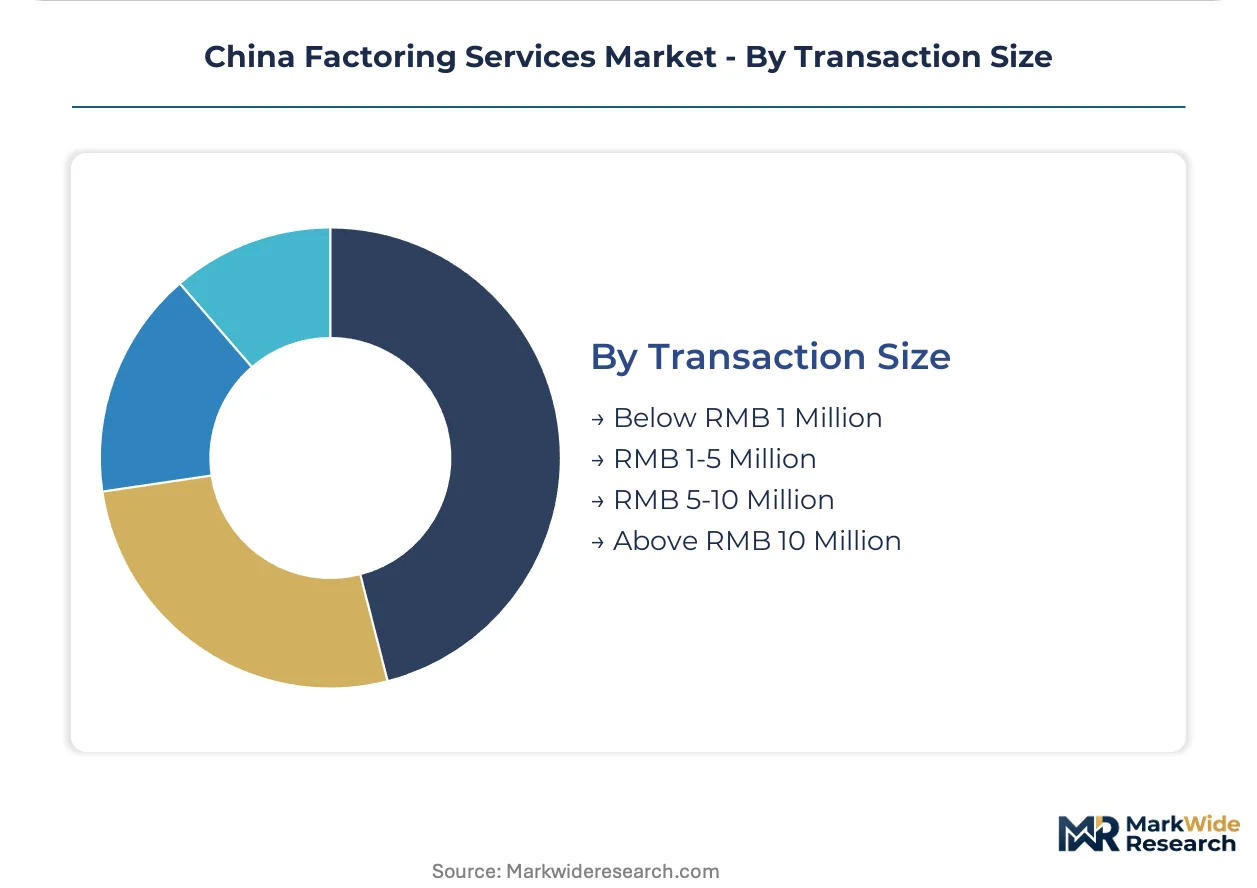
Transaction Size:
Scale thresholds align with institutional capabilities, from rural cooperative networks to state-backed balance sheets.
- Below RMB 1 Million:Agricultural Bank of China's rural branch network targets agricultural supply chains others underserve, though automated verification talent scarcity constrains platform scaling.
- RMB 1-5 Million:Mid-market sweet spot where digital onboarding platforms from China Merchants Bank and joint-stock competitors reduce documentation friction most aggressively.
- RMB 5-10 Million:Transition zone where relationship-based branch distribution competes with API-enabled embedded finance integrations.
- Above RMB 10 Million:ICBC China Limited leverages state-backed balance sheet capacity to anchor domestic large-ticket transactions with minimal credit enhancement requirements.
Above RMB 10 Million transactions dominate value flows, with Below RMB 1 Million showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factoring services in China trace their modern scale to post-2009 supply chain finance pilots led by state-owned banks in Shanghai. Provincial regulatory refinements and manufacturing cluster density now determine where specialized servicers concentrate operational resources.
Yangtze River Delta
Export-oriented manufacturers in Jiangsu and Zhejiang generate dense invoice volumes that attract blockchain-enabled verification platforms. SAMR licensing requirements filter market access, favoring institutions with automated documentation capabilities. Shanghai anchors large-ticket domestic factoring through concentrated credit committee infrastructure and PBOC rediscount window proximity.
Pearl River Delta
Guangdong's electronics and textile exporters drive mid-market demand for API-integrated ERP financing solutions. Dual carbon goals channel preferential funding toward green-certified manufacturing receivables. Shenzhen and Dongguan manufacturing clusters compress due diligence costs through supplier network transparency.
Beijing-Tianjin-Hebei
State-owned enterprise supply chains dominate transaction flow, with recourse factoring structures prevailing due to lower capital reserve requirements. PBOC macro-prudential guidelines on supply chain finance shape product structures for SOE procurement networks. Tianjin's port logistics corridors generate transportation sector receivables with distinct maturity profiles.
Sichuan-Chongqing
Western manufacturing relocation policies are diversifying invoice generation away from coastal belts. Agricultural Bank of China's rural branch network extends into agricultural supply chain financing corridors others underserve. Chongqing's automotive and electronics assembly plants create multi-tier supplier financing demand.
Shandong Peninsula
Chemical and heavy industry clusters generate extended-dated receivables requiring specialized maturity factoring structures. Provincial green finance incentives align with national dual carbon targets for qualifying supply chains. Qingdao's port economy supports cross-border receivables facing SAMR and foreign exchange administration dual compliance.
China Factoring Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across risk transfer sophistication and balance sheet scale. State-backed institutions anchor the upper tier through dedicated credit lines and minimal credit enhancement requirements, while technology-enabled joint-stock banks compete on documentation friction reduction. Three archetypes dominate: state-owned balance sheet anchors, digital onboarding specialists, and rural network extenders. Consolidation pressure manifests through API-enabled embedded finance partnerships and blockchain verification platform licensing.
Among state-backed institutions, ICBC China Limited and Bank of China Limited exemplify the balance sheet anchor archetype through large-ticket transaction capacity. China Merchants Bank occupies a position within the digital specialist tier, reducing onboarding timelines through platform investments. Agricultural Bank of China Limited represents the rural network extension model, leveraging physical branch infrastructure in corridors others bypass.
| Leading Market Players |
|---|
| Bank of China Limited |
| ICBC China Limited |
| Industrial and Commercial Bank of China |
| VTeam Financial Service |
| China Systems |
| China Construction Bank Corporation |
| China Merchants Bank |
| one PMF Capital |
| Agricultural Bank of China Limited |
| Others |
Pricing and Supply Chain Analysis
Export-oriented manufacturers in the Yangtze River Delta demanding seamless ERP-integrated liquidity solutions are compressing servicer margins and forcing state-backed institutions to modernize legacy settlement infrastructure. This procurement preference shift toward digital onboarding platforms is reshaping how factors price recourse versus non-recourse products.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the China factoring landscape, with premium tiers attaching to non-recourse arrangements backed by emerging domestic trade credit models. Price differentiation stems from balance sheet scale and automated verification capability, with state-owned banks commanding standard-tier spreads and rural network extenders occupying economy positioning. Cost compression in mid-market digital onboarding is intensifying because joint-stock banks are racing to reduce documentation friction. Small enterprises in western agricultural corridors exhibit highest price sensitivity, while large SOE supply chains anchored by ICBC show lowest elasticity due to relationship lock-in and syndication complexity.
Supply Chain Analysis
Trade credit insurance capacity rests on underwriters in Shanghai, Beijing, and Shenzhen developing domestic risk models for non-recourse factoring expansion. Raw material dependencies include invoice verification data feeds from blockchain platforms, SME credit scoring algorithms, and PBOC rediscount window liquidity. Single-source vulnerability concentrates in automated verification talent pools, where data engineers capable of machine learning fraud detection remain scarce. Distribution runs through API-enabled embedded finance integrations that bypass traditional branch networks, with ERP-integrated solutions gaining fastest adoption in Guangdong and Jiangsu manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China factoring services market reads as a late-cycle quality story where SME demand for licensed working capital solutions is shifting toward premium digital onboarding specifications and green supply chain certification.
For Market Incumbents: Lock in multi-bank syndication relationships with large SOE procurement networks before joint-stock banks complete API integration rollouts. Prioritize backward integration into blockchain verification platforms to sustain automated invoice authentication at scale against technology-enabled entrants. For New Entrants and Emerging Players: Enter via western province agricultural corridors where Agricultural Bank of China's branch network gaps leave rural supply chains underserved. Target sub-RMB 1 million transaction tiers with distributed collection capabilities and IoT-enabled inventory monitoring for dynamic credit limit adjustments. For Investors and Strategic Acquirers: Asymmetric upside sits with private insurers developing domestic trade credit risk models for non-recourse expansion. Long-term viability favors platforms with SAMR licensing and PBOC rediscount window access over unlicensed informal lenders. Watch for NMPA-style data governance standards migrating into financial services as the inflection trigger for compliance overhead consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Verification Platform Licensing | Reduces invoice authentication cycles from weeks to hours for Yangtze River Delta exporters. |
| Green Supply Chain Certification Program | Unlocks preferential PBOC rediscount windows for dual carbon goal-aligned receivables. |
| API-Enabled Embedded Finance Partnership | Integrates liquidity solutions directly into manufacturing ERP systems in Guangdong clusters. |
| Rural Branch Network Extension | Captures agricultural supply chain financing corridors in Sichuan-Chongqing others bypass. |
| Domestic Trade Credit Model Development | Enables non-recourse margin expansion beyond state-owned bank recourse products. |
Research Methodology
Bottom-up SME working capital demand modeling reconciled against top-down PBOC supply chain finance flow tracking forms the analytical core of this study. Primary interviews with factoring operations heads, SAMR licensing officers, agricultural cooperative finance managers, and blockchain platform engineers combined with secondary validation against PBOC macro-prudential reports, SAMR licensing databases, and joint-stock bank annual disclosures. Triangulation across these sources ensures segmentation integrity across service type, client tier, and regional concentration dimensions.
Input-output matrices map transaction volume flows through recourse and non-recourse channels across the analysis window, with CAGR derivation reflecting invoice generation rates in manufacturing clusters and regulatory velocity from SAMR guideline issuance. Segmentation dimensions modeled include service type risk transfer structure, enterprise size tier, industry vertical certification status, and transaction scale threshold. Forecast inputs incorporate PBOC rediscount window utilization trends and blockchain platform adoption curves in the Yangtze River Delta.
Inputs from PBOC statistical releases and SAMR licensing records were available through the study window; gaps in private insurer trade credit loss data introduce uncertainty bands around non-recourse expansion trajectories. Forecasts reflect documented assumptions on regulatory enforcement consistency and technology platform scaling feasibility. A small set of triggers—including NMPA data governance migration timing and rural branch network automation rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
BFSI A2P SMS Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Germany Factoring Services Market
Financial Services
Islamic Finance Market
Financial Services
ATM Software Market
Financial Services
Multivendor ATM Software Market
Financial Services
Europe B2C Legal Services Market
Financial Services
United States Credit Agency Market
Financial Services
Reconciliation Software Market
Financial Services
Global Treasury Software Market
Financial Services
Account Aggregators Market
Financial Services
Liquidation Service Market
Financial Services
Commercial Debt Collection Software Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Europe B2B Legal Services Market
Financial Services
Global Executive Search (Headhunting) Market