
 Global Financial Consulting Software Market | 2026-2036
Global Financial Consulting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Financial Consulting Software Market Analysis
The United States is fragmenting as cloud infrastructure providers and legacy ERP vendors compete for financial consulting software contracts. SAP SE leverages deep enterprise resource planning integration to anchor large-bank deployments across North America. Deloitte sustains competitive positioning through advisory-led software implementations that bundle compliance and risk analytics. IBM Corporation specializes in AI-infused regulatory reporting tools that appeal to institutions navigating complex disclosure frameworks.
Financial consulting software encompasses cloud-native and on-premises platforms that automate advisory workflows, risk quantification, regulatory reporting, and capital planning through embedded analytics and API-connected data fabrics. These systems process real-time transactional feeds, apply stochastic modeling engines, and generate audit-ready documentation for institutional finance teams. Cloud-based deployment leads structural growth as banks accelerate SaaS migration to reduce capital expenditure on legacy server estates. Risk Management and Compliance Solutions capture concentrated margin pools because regulatory complexity forces institutions toward specialized, high-refresh subscription modules rather than generic planning tools.
The SEC, EBA stress-testing protocols, and the EU AI Act collectively tighten algorithmic transparency and model-risk governance requirements for financial software vendors. HIPAA-aligned data handling and GDPR cross-border transfer rules further constrain how consulting platforms architect client-data residency. Stakeholders must monitor evolving algorithmic accountability standards to determine whether in-house model development or third-party validated platforms offer superior regulatory defensibility.
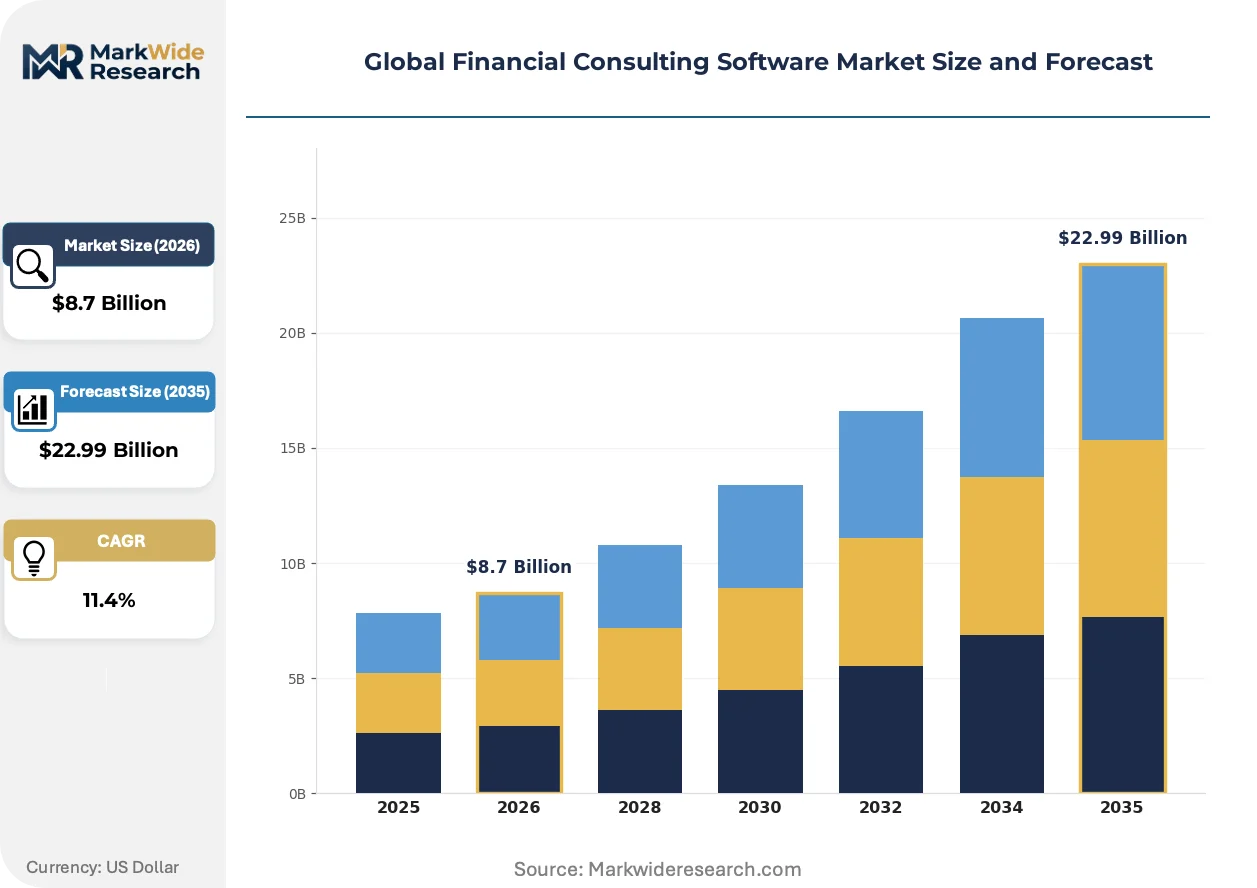
Market Dynamics
Cloud-native architectures are compressing deployment cycles for financial consulting platforms while regulators in the United States and European Union impose algorithmic transparency mandates that force vendors to re-engineer model governance frameworks.
Growth Catalysts
- EU AI Act algorithmic accountability mandates:European wealth managers must deploy explainable AI for credit-scoring and advisory tools, creating subscription demand for compliance-embedded platforms.
- Wealth management SaaS migration:North American private banks are retiring on-premises risk engines in favor of API-connected cloud suites that reduce data center capital expenditure.
- SEC climate disclosure rules:Asset managers require scenario-analysis modules that automate TCFD-aligned reporting, pulling specialized vendors into ESG data integration workflows.
Market Restraints
- GDPR cross-border data transfer friction:Cloud providers face structural constraints architecting client-data residency for multinational banks operating across Frankfurt, Singapore, and New York data centers.
- Specialized actuarial talent scarcity:Stochastic modeling expertise concentrates in London and Zurich, inflating implementation costs for vendors serving mid-tier regional banks.
- Legacy mainframe dependency:Core banking systems running COBOL transaction processing limit real-time API throughput for modern advisory platforms.
Strategic Opportunities
- India's IFSCA regulatory sandbox:GIFT City permits pilot deployments of AI-driven wealth advisory tools with relaxed capital requirements, attracting vendor testing for emerging-market product localization.
- Quantum risk simulation convergence:Monte Carlo engines paired with quantum-inspired algorithms promise portfolio stress-testing acceleration for sovereign wealth funds.
- Embedded finance distribution channels:Neobanks and e-commerce platforms in Brazil and Indonesia white-label robo-advisory modules, bypassing traditional wealth manager intermediation.
Industry Challenges
- Model Risk Management (MRM) certification timelines:SR 11-7 compliance documentation for Federal Reserve-supervised institutions extends sales cycles by eight to fourteen months.
- Multi-tenant data isolation complexity:SaaS vendors serving both competing bulge-bracket banks and their regional subsidiaries face architectural conflicts over co-mingled risk model training data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Financial Consulting Software Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Service Type: Advisory Services, Risk Management, Compliance Solutions, Financial Planning End User: Corporations, Banks, Insurance Companies, Non-Profits Pricing Model: Subscription, One-Time License, Freemium, Tiered Pricing |
| Companies Covered | SAP SE, Oracle Corporation, Accenture, Deloitte, IBM Corporation, Ernst & Young, Intuit, FIS Global, PricewaterhouseCoopers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Financial Consulting Software Market Emerging Trajectories
Generative AI is penetrating regulatory reporting workflows while distributed ledger infrastructure matures for settlement transparency. These shifts compress vendor differentiation cycles and elevate data architecture to primary competitive terrain.
Large language models fine-tuned on IFRS and GAAP corpora are rendering obsolete manual disclosure drafting for quarterly regulatory filings. Tier-one banks in the United States and United Kingdom pilot these systems for 10-K automation, compressing document production from weeks to days and reallocating compliance staff to exception-handling roles.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on high-risk credit-scoring algorithms. Vendors serving European retail banks must maintain technical documentation, human oversight protocols, and accuracy metrics that satisfy notified body review, forcing product roadmap prioritization toward audit-trail transparency.
Subscription pricing for risk analytics is displacing perpetual license models among North American asset managers. Chief investment officers favor operational expenditure treatment for model suites that require quarterly recalibration, particularly for interest rate and counterparty credit risk modules where vendor expertise substitutes for in-house quantitative research teams.
Global Financial Consulting Software Market Segmentation
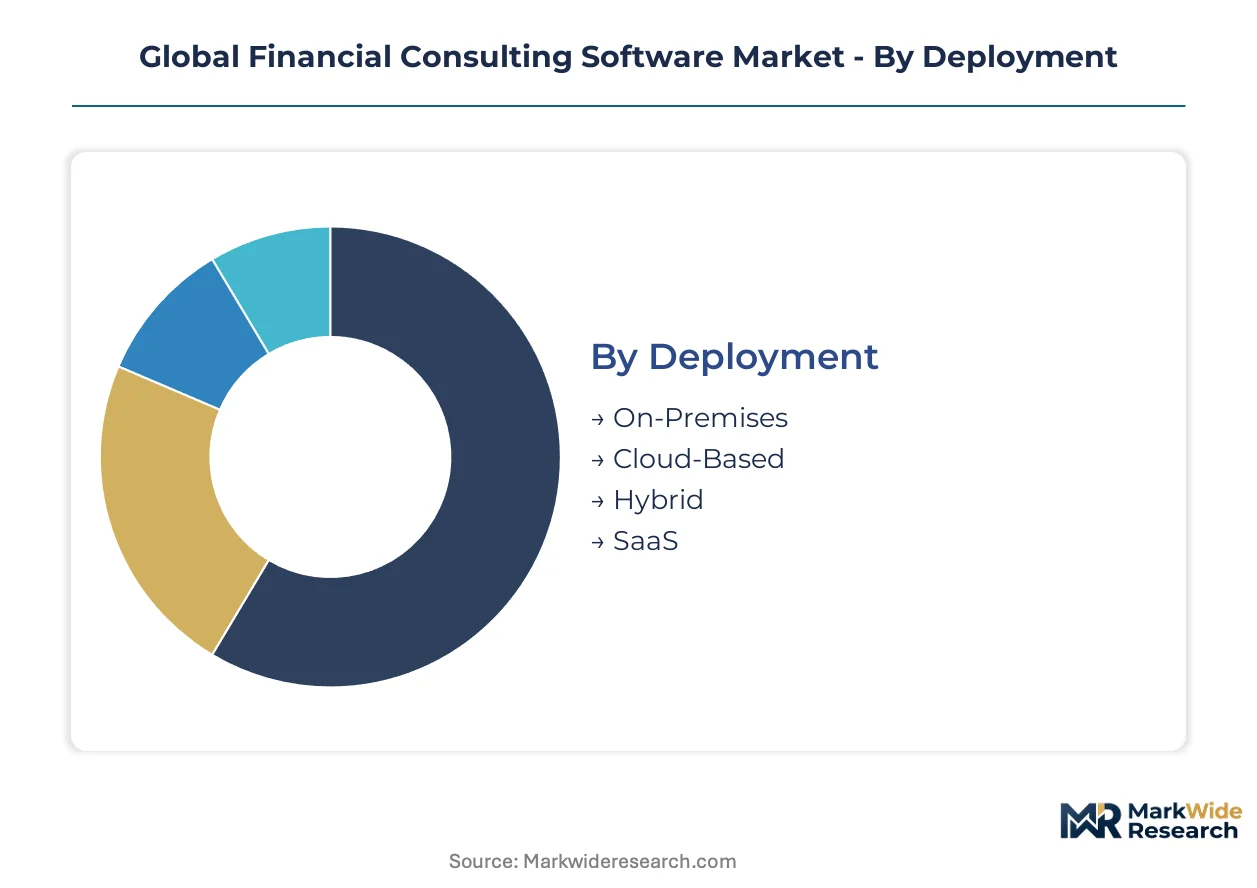
Financial consulting software vendors architect product portfolios around deployment flexibility and service modularity to capture divergent buyer risk appetites. Segmentation reveals where subscription economics displace perpetual licensing and which compliance verticals command premium pricing.
Deployment:
Post-sale service intensity peaks with on-premises installations requiring dedicated infrastructure support teams and quarterly patch management cycles.
- On-Premises:Deployed within client data centers with full hardware sovereignty. Demand concentrates among German and Swiss private banks navigating strict data residency requirements under GDPR and national banking secrecy laws.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning. North American wealth managers favor these platforms for rapid scaling without capital expenditure commitments to server estates.
- Hybrid:Sensitive risk models run on-premises while client-facing advisory portals operate in cloud environments. Appeals to UK institutions reconciling FCA operational resilience mandates with digital experience demands.
- SaaS:Browser-delivered applications with API-first integration patterns. Brazilian and Indonesian neobanks white-label these modules for embedded wealth advisory distribution.
By volume, SaaS leads. By growth pace, Hybrid is gaining share fastest as regulatory complexity forces architectural compromise.
Service Type:
Margin concentration follows regulatory enforcement intensity rather than functional sophistication.
- Advisory Services:Client-facing portfolio construction and wealth planning tools with stochastic simulation engines. Asset managers in Singapore and Hong Kong deploy these for family office clientele seeking tax-optimized cross-border structures.
- Risk Management:Counterparty credit, market, and liquidity risk quantification platforms with real-time data fabric connectivity. US Federal Reserve stress-testing protocols drive refresh cycles for SR 11-7 compliant model documentation.
- Compliance Solutions:Automated regulatory reporting and disclosure drafting modules. EU AI Act conformity assessment obligations for high-risk credit-scoring algorithms accelerate procurement among French and Dutch retail banks.
- Financial Planning:Capital allocation, scenario analysis, and long-term forecasting suites. Japanese regional banks adopt these for SME lending portfolio optimization under METI digital transformation incentives.
Compliance Solutions capture the steepest expansion trajectory as algorithmic accountability mandates proliferate across jurisdictions.
End User:
Procurement authority and implementation timelines diverge sharply across institutional categories.
- Corporations:Treasury management and capital structure optimization platforms with ERP integration requirements. Multinational manufacturers headquartered in the United States prioritize these for cross-currency hedging automation.
- Banks:Integrated risk-management suites spanning credit, market, and operational risk verticals. Tier-one institutions in London and New York drive premium deployments with customized model governance frameworks.
- Insurance Companies:Actuarial reserving and solvency capital requirement tools with heavy stochastic simulation demands. Zurich and Hartford carriers concentrate specialized talent for these implementations.
- Non-Profits:Simplified fund accounting and donor-restricted asset tracking with lightweight compliance modules. Demand clusters among US university endowments and healthcare foundations managing restricted gift portfolios.
Banks dominate absolute contract value. Non-Profits are expanding most quickly from a low base as SaaS pricing democratizes access.
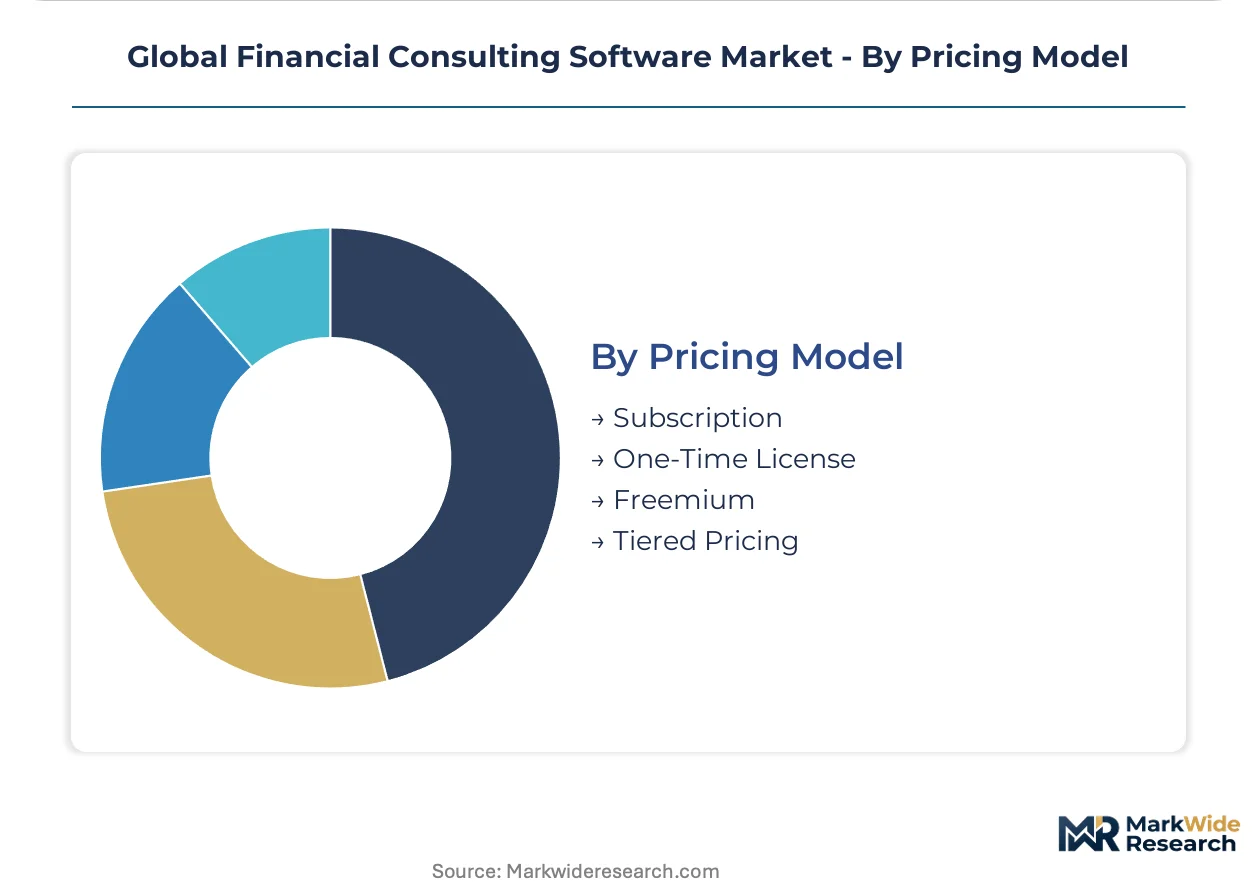
Pricing Model:
Revenue predictability and customer lifetime value calculations vary substantially across commercial structures.
- Subscription:Recurring revenue with quarterly model recalibration and feature updates. North American asset managers favor operational expenditure treatment for interest rate and counterparty credit risk modules.
- One-Time License:Perpetual deployment rights with annual maintenance fees. Japanese megabanks historically preferred this structure for core risk engine procurement.
- Freemium:Limited-functionality entry tiers converting to paid advisory modules. Brazilian fintechs leverage these for customer acquisition in embedded finance channels.
- Tiered Pricing:Premium, standard, and economy levels differentiated by data throughput and model complexity. Appeals to mid-tier regional banks in India and Australia seeking modular capability scaling.
Subscription structures displace perpetual licenses across all customer tiers as vendor expertise substitutes for in-house quantitative research teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States institutions favor cloud-native subscription suites, while German and Swiss banks insist on on-premises sovereignty for core risk engines. Asian wealth managers prioritize embedded finance distribution over standalone advisory platforms.
United States
Tier-one banks and asset managers drive premium deployments of integrated risk-management suites with real-time data fabric connectivity. SEC climate disclosure rules mandate TCFD-aligned scenario analysis modules, pulling vendors into ESG data integration workflows. New York and Boston financial centers concentrate procurement authority for enterprise SaaS migrations.
Germany
Private banks navigate strict data residency requirements under GDPR and national banking secrecy laws, sustaining demand for on-premises installations. BaFin operational resilience mandates force architectural compromises between legacy mainframe integration and digital experience demands. Frankfurt's banking cluster anchors specialized compliance-embedded platform procurement.
United Kingdom
Institutions reconcile FCA operational resilience mandates with client-facing digital transformation, favoring hybrid deployment architectures. SR 11-7 compliance documentation for Federal Reserve-supervised institutions extends sales cycles, though UK-specific model risk governance creates parallel certification requirements. London's City and Canary Wharf concentrate bulge-bracket bank headquarters driving customized model governance frameworks.
Singapore
Family office clientele seeking tax-optimized cross-border structures deploy client-facing portfolio construction and wealth planning tools with stochastic simulation engines. MAS regulatory sandbox permits pilot deployments of AI-driven wealth advisory tools, attracting vendor testing for emerging-market product localization. The financial district anchors regional headquarters for wealth managers serving Southeast Asian high-net-worth individuals.
Brazil
Neobanks and e-commerce platforms white-label robo-advisory modules, bypassing traditional wealth manager intermediation through embedded finance distribution channels. Central Bank of Brazil open banking regulations accelerate API-first integration patterns for browser-delivered applications. São Paulo's fintech corridor concentrates customer acquisition innovation for freemium pricing model deployment.
Global Financial Consulting Software Market Vendor Landscape
Capability concentration sits with specialized risk analytics vendors; scale advantage sits with enterprise resource planning incumbents. The vendor base organizes into three tiers: global consultancies bundling advisory-led implementations, cloud infrastructure providers offering elastic compute provisioning, and niche stochastic modeling specialists serving actuarial-intensive segments. Dominant competitive moves include vertical integration into data fabric infrastructure and strategic partnerships embedding compliance modules within core banking systems.
Within the enterprise software tier, SAP SE and Oracle Corporation anchor large-bank deployments through deep ERP integration, while IBM Corporation occupies a position among AI-infused regulatory reporting specialists. These three exemplify divergent archetypes: SAP represents legacy-system anchoring, Oracle exemplifies database-centric platform consolidation, and IBM sits within the algorithmic transparency tooling niche. Deloitte sustains competitive positioning through advisory-led software implementations that bundle compliance and risk analytics, representing the consultancy-archetype competitive vector.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Accenture |
| Deloitte |
| IBM Corporation |
| Ernst & Young |
| Intuit |
| FIS Global |
| PricewaterhouseCoopers |
| Others |
Supply Flow & Price Mechanics
Overcapacity in cloud infrastructure across North America is compressing margins for SaaS vendors while simultaneously enabling aggressive pricing postures among hyperscale providers serving financial institutions. This utilization dynamic forces specialized risk-analytics vendors toward value-based differentiation and away from compute-cost competition.
Pricing Analysis
Long-term subscription contracts anchor enterprise procurement for tier-one banks, while mid-tier regional institutions negotiate project-based implementations with quarterly recalibration clauses. Price differentiation hinges on model governance certification grade—SR 11-7 compliant documentation commands substantial premiums—and customization depth for legacy ERP integration. Pricing pressure stems from hyperscale cloud providers bundling advisory modules into infrastructure contracts. Asset managers exhibit highest price sensitivity due to operational expenditure constraints, whereas sovereign wealth funds demonstrate lowest sensitivity given mission-critical risk quantification requirements.
Supply Chain Analysis
Upstream specialized compute hardware concentrates in Taiwan, South Korea, and the United States, with NVIDIA GPUs and custom ASICs feeding stochastic modeling engine development. Cloud-native architectures draw from open-source frameworks, proprietary data fabrics, and API middleware layers sourced from California and Bangalore development centers. Single-source vulnerability in advanced semiconductor fabrication creates supply chain risk for real-time risk simulation platforms. Distribution runs through direct enterprise sales teams for tier-one banks, supplemented by systems integrator partnerships for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
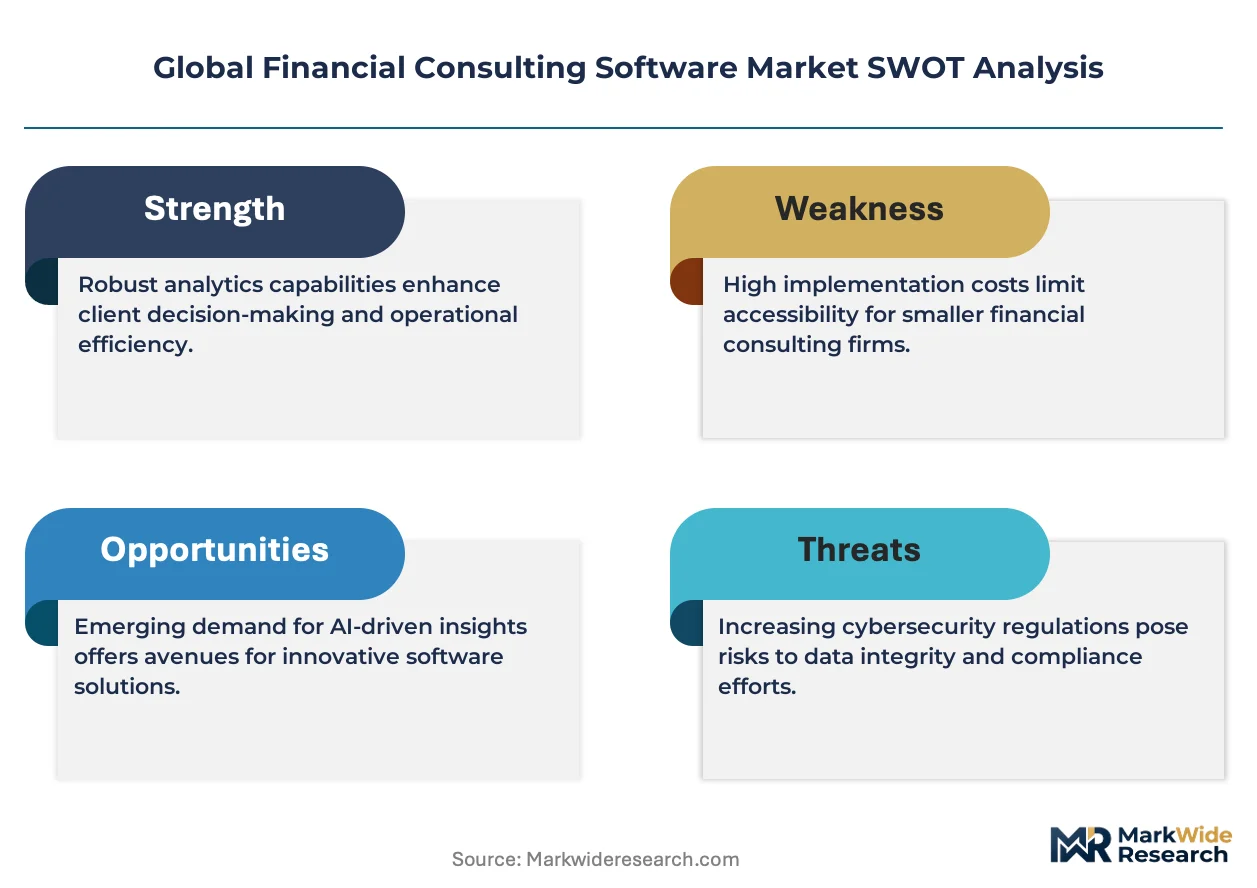
Financial consulting software is entering a cyclical recovery phase as Federal Reserve rate stabilization restores capital expenditure confidence among North American asset managers. Regulatory complexity acceleration—notably EU AI Act implementation and SEC climate disclosure enforcement—sustains demand visibility independent of macroeconomic volatility.
For Market Incumbents: Pre-empt hyperscale cloud encroachment by embedding compliance modules directly into core banking system partnerships, particularly for COBOL legacy integration where specialized expertise creates switching costs. Invest in model risk management certification automation to compress the eight-to-fourteen-month Federal Reserve sales cycle. Prioritize quantum-inspired algorithm development for sovereign wealth fund stress-testing contracts. For New Entrants and Emerging Players: India's IFSCA regulatory sandbox at GIFT City represents the most penetrable entry point for AI-driven wealth advisory localization, with relaxed capital requirements enabling pilot deployment without full-scale compliance investment. Brazilian neobank embedded finance channels offer second-mover advantage through white-label robo-advisory modules bypassing traditional wealth manager intermediation. Pursue freemium customer acquisition with API-first integration patterns. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures as containerization and serverless compute reduce infrastructure commitments. Long-term viability favors vendors with recurring revenue above seventy percent and embedded compliance workflows rather than standalone advisory tools. Target acquisition profiles should emphasize stochastic modeling specialists with London or Zurich talent concentration. Monitor Federal Reserve SR 11-7 audit frequency as inflection indicator for model governance platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep ERP connectivity with SAP and Oracle systems anchors large-bank retention and expands wallet share. |
| Regulatory Compliance Module Development | EU AI Act conformity assessment capabilities differentiate vendors serving French and Dutch retail banking. |
| Strategic Partnership | Systems integrator alliances with Deloitte and Accenture accelerate mid-market penetration and implementation velocity. |
| Acquisition of Specialist Firm | Stochastic modeling boutiques in London and Zurich add actuarial talent scarcity protection. |
| Geographic Expansion | GIFT City sandbox deployment enables India IFSCA-compliant product localization for emerging market scale. |
Methodological Framework
Desk research of SEC filings, EBA stress-testing protocols, EU regulatory databases, and vendor annual reports preceded structured interviews with chief risk officers, model validation executives, regulatory affairs leads, and cloud procurement officers at tier-one banks and asset managers. Primary fieldwork combined with secondary validation from hyperscaler capex disclosures and financial software trade associations. Bottom-up deployment volume estimates triangulated against top-down market sizing from subscription revenue aggregation.
Assumptions held fixed include regulatory enforcement timelines for EU AI Act and SEC climate disclosure rules, while cloud migration pace and quantum computing maturation were varied across sensitivity scenarios. Segmentation modeling spanned deployment architecture, service type, end-user institution category, and pricing model complexity. CAGRs derived from logistic adoption curves fitted to historical SaaS transition patterns in adjacent financial technology verticals, with stochastic modeling talent scarcity and mainframe dependency serving as constraint variables.
Practitioners should monitor Federal Reserve audit intensity, EU AI Act notified body accreditation delays, and hyperscale cloud bundling announcements for early signals of forecast revision. Cross-checking against vendor-reported subscription retention rates and implementation backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Europe Insurance Brokerage Market
Financial Services
Saas Escrow Services Market
Financial Services
Investment Trading Software Market
Financial Services
US Online Trading Platform Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
UK Islamic Finance Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
Factoring Services Market
Financial Services
BFSI Contact Center Analytics Market
Financial Services
Pawn Shop Market
Financial Services
Africa Factoring Services Market
Financial Services
Multivendor ATM Software Market
Financial Services
Power Bank Sharing Services Market
Financial Services
China Trade Finance Market
Financial Services
North America B2B Legal Services Market
Financial Services
Europe Factoring Services Market