
 Multivendor ATM Software Market | 2026-2036
Multivendor ATM Software Market Size, Share, and Industry Trends Forecast 2026-2036
Multivendor ATM Software Market Intelligence
The EU Green Deal's digital finance sustainability requirements is realigning how European banks evaluate ATM infrastructure procurement, pushing vendors toward energy-efficient software architectures. KAL ATM Software leverages its cloud-native platform to compete in this transitioning environment, while NCR Corporation anchors its position through extensive on-premises integration expertise across North American credit unions. Diebold Nixdorf differentiates by sustaining manufacturing scale that supports hybrid deployment models for large retail banking networks.
Multivendor ATM software comprises middleware and application layers that enable automated teller machines from different hardware manufacturers to operate under unified transaction processing, security, and management protocols, typically supporting XFS (Extensions for Financial Services) standards for peripheral device abstraction. Its primary purpose is to reduce bank dependency on single-vendor hardware lock-in while enabling centralized software updates and consistent user experiences across heterogeneous ATM fleets. Cloud-based software deployments are capturing the fastest expansion as banks prioritize remote management and reduced branch IT overhead, while proprietary software retains the largest installed base due to legacy system entrenchment and established vendor relationships. The independent ATM deployer segment within end users represents the most price-sensitive demand pool, driving interest in open-source and hybrid integration levels that lower total cost of ownership.
The European Banking Authority's operational resilience framework, the US Federal Reserve's FedNow instant payment infrastructure requirements, and India's RBI financial inclusion directives collectively shape compliance burdens and product certification pathways for ATM software vendors. PCI DSS version 4.0 mandates are forcing security architecture redesigns, particularly for standalone deployment models that lack centralized patch management. Stakeholders must monitor how real-time payment system integrations alter software stack requirements and whether cloud sovereignty regulations fragment previously unified product development roadmaps.
Market Dynamics
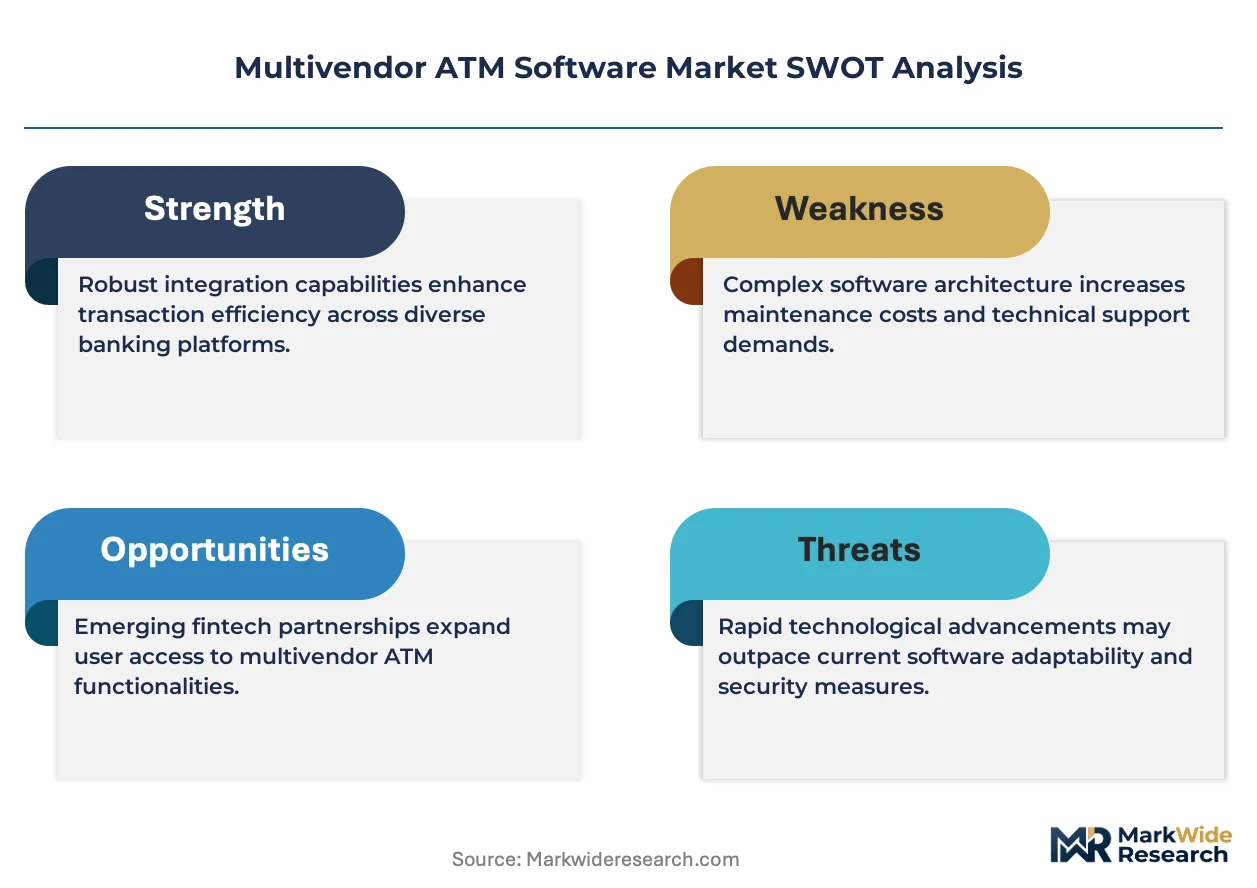
Cloud-native architecture migration is compressing deployment timelines and forcing incumbent vendors to restructure their engineering roadmaps around containerized microservices rather than monolithic legacy stacks.
Growth Catalysts
- RBI Financial Inclusion Mandates:India's central bank directives are expanding the independent ATM deployer base, creating procurement volume for interoperable software platforms across rural and semi-urban banking networks.
- XFS Standards Evolution:Peripheral device abstraction protocols are maturing, enabling hardware-agnostic transaction processing that reduces single-vendor dependency for retail banking fleets.
- Instant Payment Infrastructure:Real-time settlement systems like FedNow are requiring ATM software stack upgrades, pulling forward replacement cycles for financial institutions modernizing transaction endpoints.
Market Restraints
- Legacy System Entrenchment:Proprietary on-premises deployments retain substantial installed bases, creating switching friction and elongating sales cycles for cloud-native alternatives.
- PCI DSS 4.0 Compliance Burden:Security architecture redesigns for standalone deployment models without centralized patch management are inflating implementation costs and technical validation timelines.
- Specialized Engineering Talent Scarcity:Shortages of professionals skilled in both financial services security protocols and cloud-native development are constraining vendor delivery capacity.
Strategic Opportunities
- EU Green Deal Alignment:Energy-efficient software architectures are becoming procurement differentiators for European banks evaluating ATM infrastructure sustainability credentials under digital finance requirements.
- Open-Source Middleware Adoption:Price-sensitive independent ATM deployers are exploring hybrid integration levels that lower total cost of ownership without sacrificing security certification.
- ATM-as-a-Service Models:Channel innovation unbundling hardware ownership from software licensing is creating recurring revenue streams for vendors willing to absorb operational complexity.
Industry Challenges
- Multi-Cloud Sovereignty Fragmentation:Data localization requirements across jurisdictions are complicating unified product development roadmaps and forcing region-specific code branches.
- Real-Time Payment Stack Integration:Heterogeneous instant payment system protocols are demanding custom middleware development, stretching professional services teams and diluting margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multivendor ATM Software Market |
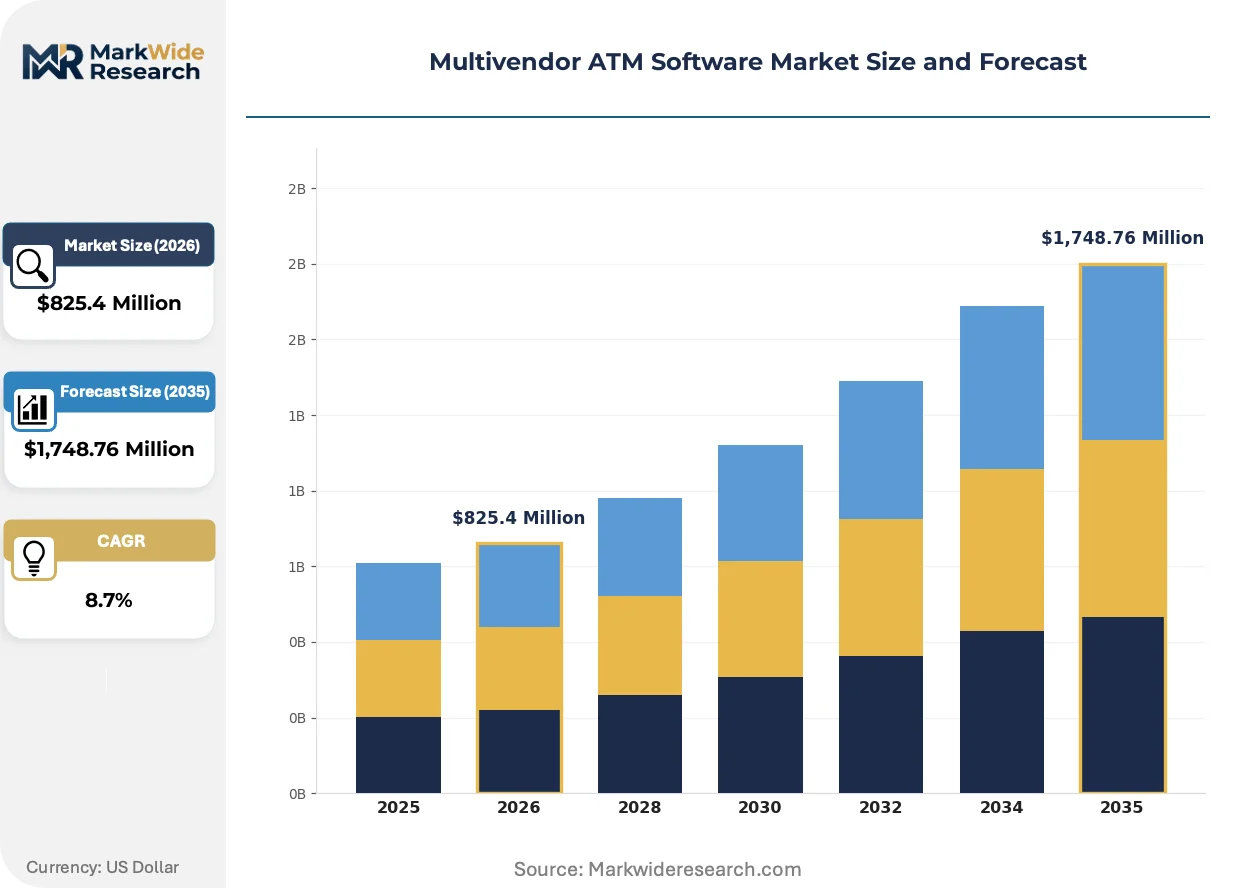
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,748.76 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proprietary Software, Open Source Software, Cloud-Based Software, Hybrid Software Deployment: On-Premises, Cloud, Hybrid, Virtualized End User: Banks, Credit Unions, Independent ATM Deployers, Retailers Integration Level: Standalone, Integrated, Full-Service, Custom Solutions |
| Companies Covered | KAL ATM Software, Verifone, NCR Corporation, ACI Worldwide, Auriga, Diebold Nixdorf, GRG Banking, Hyosung, FIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multivendor ATM Software Market Strategic Shifts & Innovations
ATM software architecture is pivoting from hardware-tethered monoliths toward API-first platforms that abstract peripheral control and enable remote fleet orchestration. This shift is compressing the traditional vendor lock-in model.
Containerized microservices architecture is rewriting how transaction processing logic gets deployed and updated across heterogeneous ATM fleets. Large retail banking networks in North America are piloting Kubernetes-orchestrated edge computing nodes that push security patches and feature releases without branch technician visits. This approach is collapsing the traditional six-month software release cycle into continuous delivery pipelines.
The European Banking Authority's operational resilience framework is mandating recovery time objectives and impact tolerance thresholds for critical financial infrastructure. ATM software vendors serving EU markets must now engineer automated failover capabilities and geographic redundancy into their platforms. Small and mid-sized banks lacking in-house resilience engineering expertise are outsourcing compliance validation to specialized consultancies.
Subscription-based licensing is displacing perpetual software purchases across the credit union segment in the United States. These institutions prioritize predictable operational expenditure over capital-intensive upfront deployments, favoring vendors offering bundled security updates and remote monitoring services. The shift is most pronounced among institutions with fewer than fifty ATM endpoints seeking to eliminate dedicated branch IT personnel.
Multivendor ATM Software Market Segmentation
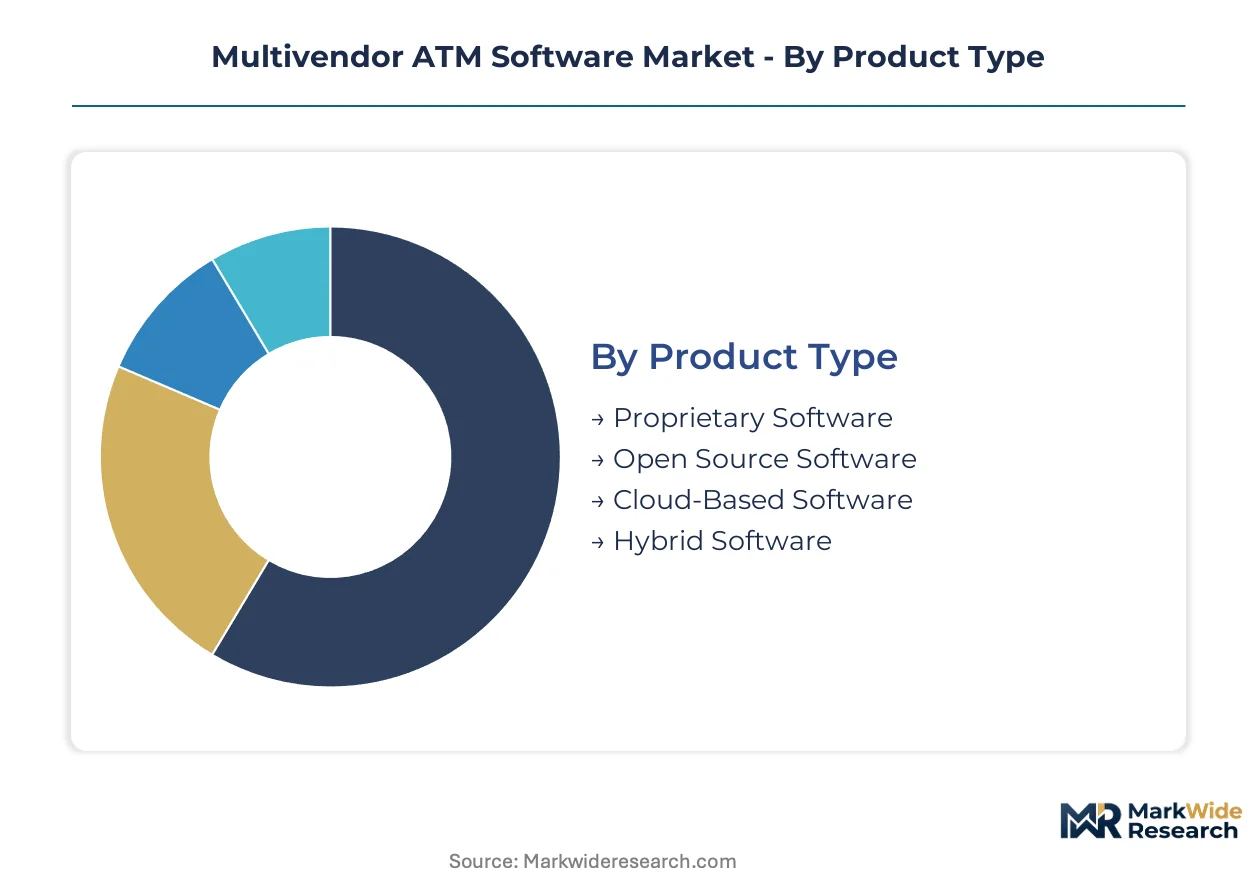
ATM software procurement patterns diverge sharply across deployment models and end-user sophistication levels. Upgrade cycles and integration complexity create distinct purchasing behaviors that vendors must address through tiered product architectures.
Product Type:
Replacement timelines stretch from three years for cloud-native platforms to over a decade for legacy proprietary installations, creating asynchronous demand pulses across the software base.
- Proprietary Software:Vendor-controlled codebases with locked peripheral drivers and certified security modules dominate legacy bank fleets. North American credit unions maintain substantial installed bases here, constrained by switching costs and re-certification burdens.
- Cloud-Based Software:Containerized microservices architectures enable remote fleet orchestration and continuous security patching. Indian independent ATM deployers are prioritizing these platforms under RBI financial inclusion mandates that demand rapid rural network scaling without branch IT overhead.
- Open Source Software:Community-maintained middleware stacks with XFS abstraction layers lower licensing costs for price-sensitive operators.
- Hybrid Software:Mixed proprietary-open source architectures balancing customization flexibility against certification requirements.
Proprietary software sits at the top of the volume ranking, with cloud-based platforms climbing the fastest.
Deployment:
Operational expenditure preferences among smaller financial institutions are compressing capital-intensive on-premises commitments toward subscription-based alternatives.
- On-Premises:Dedicated hardware installations with local transaction processing and air-gapped security architectures. Large retail banking networks in the United States retain these for regulatory audit trails and FedNow integration latency requirements.
- Cloud:Fully managed SaaS platforms with API-first transaction routing and automated PCI DSS compliance updates. European banks under EU Green Deal sustainability requirements favor these for reduced data center energy footprints.
- Hybrid:Split architectures keeping sensitive authentication local while pushing non-critical functions to hosted environments.
- Virtualized:Software-defined ATM stacks running on standardized server hardware, decoupling application logic from physical terminals.
On-premises deployment retains the largest installed footprint, though cloud configurations are gaining share fastest among institutions under fifty endpoints.
End User:
Procurement sophistication correlates inversely with fleet scale, driving vendors toward modular pricing that accommodates both enterprise tenders and single-machine operators.
- Banks:Tier-one financial institutions with dedicated ATM operations teams and bespoke integration requirements. Indian public sector banks are expanding procurement volumes under central bank directives for rural financial access.
- Independent ATM Deployers:Third-party operators managing outsourced terminal networks for multiple financial sponsors. These operators in India represent the most price-elastic demand segment, prioritizing open-source middleware and per-transaction pricing.
- Credit Unions:Member-owned institutions with limited IT staffing, favoring bundled remote monitoring and security update services.
- Retailers:Non-bank merchants deploying cash access points as customer service amenities, typically selecting turnkey managed service arrangements.
Banks command the highest absolute spending, while independent ATM deployers are expanding most quickly in emerging economies.
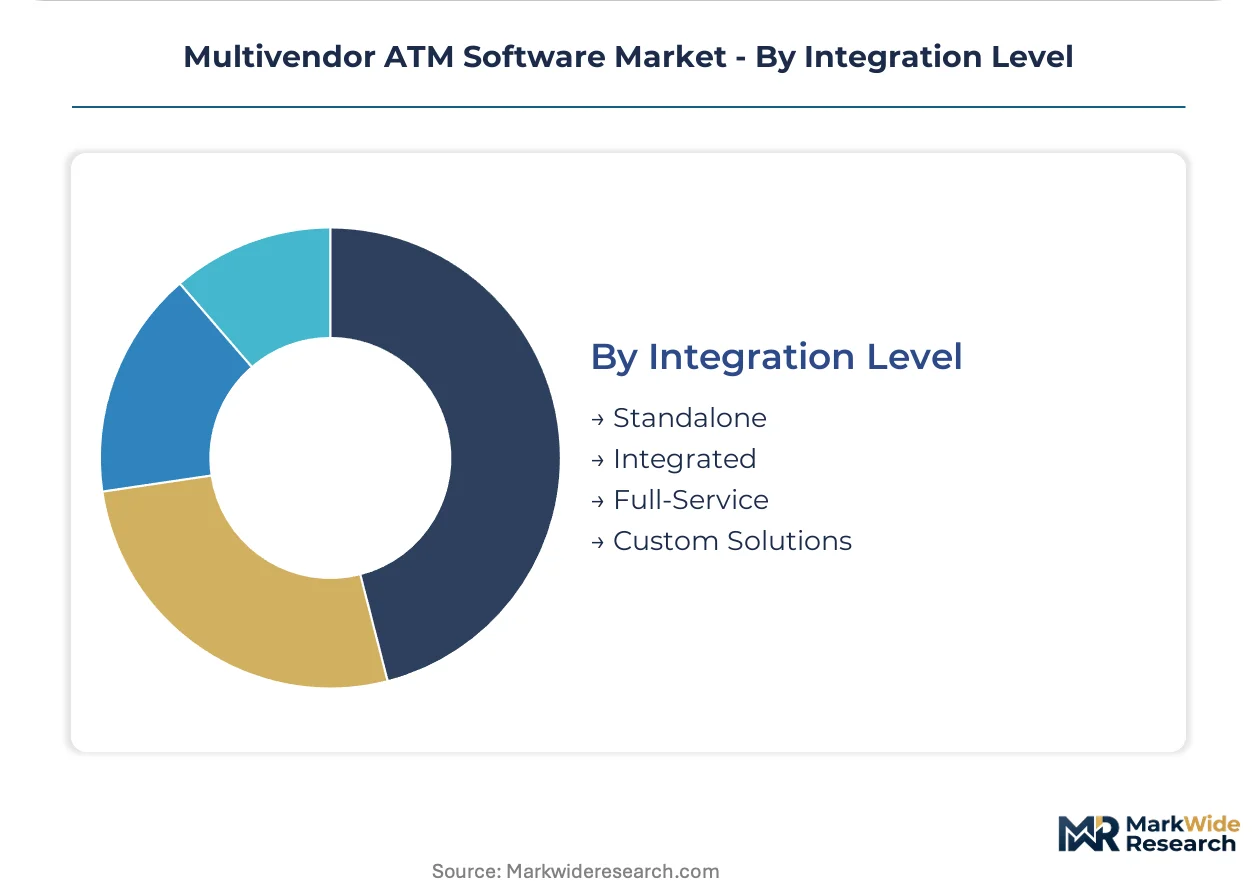
Integration Level:
Professional services intensity and margin structures vary dramatically across integration depth, with full-service engagements capturing recurring revenue streams at the cost of operational complexity.
- Full-Service:End-to-end vendor responsibility spanning software licensing, hardware integration, security certification, and ongoing fleet management. European banks facing EBA operational resilience mandates increasingly outsource compliance validation through these arrangements.
- Standalone:Basic software licensing with minimal vendor integration support, requiring substantial in-house engineering capacity. PCI DSS 4.0 compliance redesigns are inflating implementation costs for these deployments lacking centralized patch management.
- Integrated:Pre-certified connections to core banking systems and payment networks, reducing deployment timelines.
- Custom Solutions:Bespoke development for specialized transaction types or proprietary peripheral hardware.
Full-service integration commands the premium tier by revenue, with standalone solutions facing steepest competitive pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in financial technology hubs anchor regional deployment patterns for multivendor ATM software. Concentrations of payment systems expertise and central bank proximity determine procurement sophistication across major markets.
United States
FedNow instant payment infrastructure requirements are accelerating ATM software stack upgrades at credit unions and community banks. The Federal Reserve's real-time settlement mandates pull forward replacement cycles for transaction endpoints. Dallas and Charlotte banking clusters host concentrated vendor integration teams serving regional financial institutions.
India
RBI financial inclusion directives are expanding the independent ATM deployer base across rural and semi-urban networks. The central bank's mandates for interoperable rural banking infrastructure create procurement volume for cloud-native platforms. Mumbai and Bangalore fintech corridors concentrate software development capacity serving domestic deployment scale.
Germany
EU Green Deal sustainability requirements are realigning ATM infrastructure procurement toward energy-efficient software architectures. EBA operational resilience frameworks mandate automated failover capabilities and geographic redundancy for critical financial infrastructure. Frankfurt's financial services cluster drives compliance validation outsourcing among mid-sized banks lacking in-house engineering.
United Kingdom
Subscription-based licensing preferences among smaller financial institutions are displacing perpetual software purchases. FCA operational resilience expectations intersect with PCI DSS 4.0 security architecture redesigns. London's payment systems hub concentrates vendor professional services teams addressing heterogeneous instant payment protocol integration.
Japan
Aging ATM fleet modernization and cash access point consolidation are creating software procurement opportunities at regional banks. METI digital transformation incentives support cloud migration for financial infrastructure. Tokyo's banking technology corridor hosts concentrated integration expertise for XFS standards-compliant hardware abstraction layers.
Multivendor ATM Software Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the multivendor ATM software landscape. The vendor base separates between infrastructure owners maintaining manufacturing scale and software specialists delivering platform-agnostic middleware. Three archetypes dominate: cloud-native platform vendors, legacy hardware-integrated incumbents, and open-source middleware providers. Consolidation pressure operates through strategic partnerships bridging hardware and software capabilities, while geographic expansion targets emerging economy financial inclusion mandates.
Within the cloud-native platform tier, KAL ATM Software exemplifies asset-light specialization, while NCR Corporation anchors the legacy-integrated incumbent position through extensive on-premises expertise. Diebold Nixdorf occupies a hybrid archetype sustaining manufacturing scale that supports mixed deployment models. These three companies represent divergent strategic postures toward containerized microservices migration and ATM-as-a-service channel innovation.
| Leading Market Players |
|---|
| KAL ATM Software |
| Verifone |
| NCR Corporation |
| ACI Worldwide |
| Auriga |
| Diebold Nixdorf |
| GRG Banking |
| Hyosung |
| FIS |
| Others |
Cost & Logistics Intelligence
Independent ATM deployers in India anchor procurement volume for cloud-native platforms, compressing vendor margins through per-transaction pricing demands while subscription-based SaaS models displace perpetual licensing among credit unions seeking predictable operational expenditure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by integration depth and certification burden. Premium tiers capture full-service arrangements with automated PCI DSS compliance updates, while economy tiers serve standalone deployments with minimal vendor support. Pricing pressure stems from open-source middleware alternatives lowering licensing costs for price-sensitive independent operators. Credit unions with fewer than fifty endpoints exhibit highest price sensitivity, whereas tier-one banks prioritize resilience engineering over cost minimization.
Supply Chain Analysis
Dual-sourcing requirements for security modules and peripheral device drivers mandate multi-supplier qualification across hardware manufacturers. Software development concentrates in India, Germany, and the United States, drawing from specialized engineering talent pools in fintech corridors. Dependencies include XFS-compliant peripheral abstraction layers, certified cryptographic modules, and containerized orchestration platforms. Single-source vulnerability in legacy hardware-integrated security chips creates procurement risk. Distribution runs through direct vendor relationships with large banking networks and channel partners serving mid-tier institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized microservices migration compresses deployment costs while ATM-as-a-Service channel innovation shifts revenue toward recurring premium tiers, expanding margin capture for vendors absorbing operational complexity.
For Market Incumbents: Anticipate cloud-native challengers eroding proprietary installed bases through Kubernetes-orchestrated edge computing deployments. Defensive consolidation through backward integration into security certification services preserves margin structure. Incumbents should anchor position by sustaining manufacturing scale that supports hybrid deployment models for retail banking networks requiring FedNow latency compliance. For New Entrants and Emerging Players: Rural independent ATM deployers in India represent the most penetrable buyer archetype, underserved by legacy vendors with inflexible pricing structures. White-space targets include per-transaction SaaS platforms for operators under RBI financial inclusion mandates and API-first middleware for retailers deploying cash access points. Go-to-market execution should leverage open-source XFS abstraction layers to bypass certification timelines. For Investors and Strategic Acquirers: Cloud-native platform specialists are the most active acquirer in this space, seeking engineering talent and PCI DSS 4.0 compliance expertise. Long-term viability centers on vendors with demonstrated container orchestration capabilities and recurring revenue concentration above project-based licensing. The signal to watch is FedNow integration contract awards at regional credit unions, indicating replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Kubernetes-orchestrated edge computing collapses six-month release cycles into continuous delivery pipelines. |
| ATM-as-a-Service Channel Launch | Subscription bundling unbundles hardware ownership from software licensing, absorbing operational complexity for credit unions. |
| PCI DSS 4.0 Certification Investment | Automated compliance updates differentiate vendors serving standalone deployments lacking centralized patch management. |
| Strategic Partnership with Hardware OEMs | Pre-certified peripheral driver integration accelerates deployment timelines for heterogeneous ATM fleets. |
| Geographic Expansion into India | RBI financial inclusion mandates create procurement volume for interoperable rural banking infrastructure. |
Research Approach
Multiple input streams — primary interviews with ATM operations executives, software engineering directors, and independent deployer procurement leads; secondary validation against RBI circulars, EBA operational resilience frameworks, and PCI SSC security standards; plus SEC filings from listed vendors — were reconciled through bottom-up and top-down triangulation.
Historical deployment data cross-referenced against panel input from fintech corridor specialists anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, end-user sophistication tier, integration depth, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating cloud migration velocity, instant payment infrastructure rollout schedules, and financial inclusion mandate compliance timelines.
Underlying measurement precision varies by segment; cloud-based software deployments carry tighter precision than legacy proprietary installations due to vendor disclosure practices. Forecasts reflect assumptions about RBI mandate enforcement continuity, FedNow integration pull-forward effects, and EU Green Deal procurement realignment. Deviation in PCI DSS 4.0 compliance timeline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Commodity Services Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Credit Rating Software Market
Financial Services
ATM Outsourcing Services Market
Financial Services
Global Management Consulting Services Market
Financial Services
Reconciliation Software Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
Billing and Revenue Management Market
Financial Services
Digital Account Opening Market
Financial Services
Healthcare Finance Solutions Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
Cash Flow Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
Europe E-Brokerages Market
Financial Services
Liquidation Service Market