
 Spain E-Brokerage Market | 2026-2036
Spain E-Brokerage Market Size, Share, and Industry Trends Forecast 2026-2036
Spain E-Brokerage Market Insights
Spanish fintech engineering talent is bifurcating between legacy banking infrastructure and cloud-native brokerage stacks, constraining incumbents while unlocking neobroker growth. eToro leverages its social trading engine to sustain engagement among millennial retail accounts. Interactive Brokers anchors institutional-grade access for sophisticated traders seeking multi-currency execution. DEGIRO competes on flat-fee pricing across European equity markets.
Spain E-Brokerage denotes digitally intermediated securities and derivatives execution where orders route through web-based, mobile, or desktop platforms with sub-second latency and SEPA-integrated settlement. These systems automate trade matching, custody, and regulatory reporting for retail and professional clients. Mobile app platforms lead transaction volume growth as smartphone penetration drives account origination, while robo-advisory segments attract fee-conscious investors through algorithmic portfolio construction. Discount brokerage models capture the fastest account expansion by eliminating advisory overlays, though full-service channels retain margin concentration among high-net-worth individuals.
Spain's CNMV enforces MiFID II best-execution and cost transparency rules that shape platform disclosure architectures, while Banco de España oversight of payment integration affects fund-inflow velocities. The EU's DORA resilience standards will soon mandate operational continuity testing for critical trading infrastructure. Stakeholders must weigh whether to build proprietary clearing links or rely on third-party APIs as regulatory technical standards crystallize.
Market Dynamics
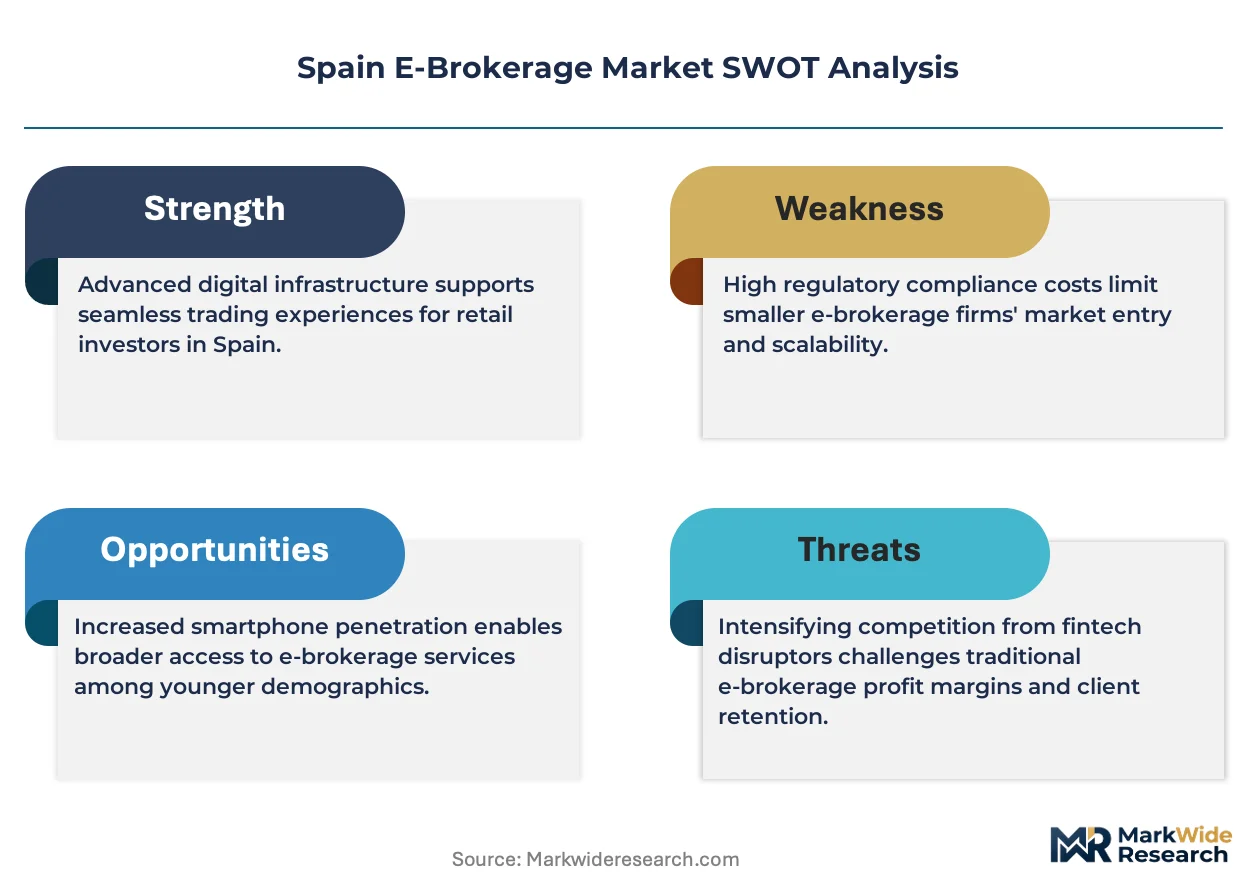
Spain's CNMV enforcement of MiFID II best-execution rules is compressing platform margins while accelerating consolidation among discount brokers unable to absorb compliance costs.
Growth Catalysts
- MiFID II cost transparency mandates:Retail investors in Madrid and Barcelona now demand itemized fee breakdowns, forcing platforms to compete on disclosed execution quality rather than hidden spreads.
- Cloud-native core banking migration:Neobrokers deploy microservices architectures that reduce order-routing latency below 50 milliseconds, attracting algorithmic retail traders.
- SEPA Instant integration:Eurozone payment rails enable same-day fund settlement, eliminating the three-day friction that previously drove account abandonment.
Market Restraints
- Clearing concentration risk:Iberclear and Euroclear dominate post-trade infrastructure, limiting platform negotiating leverage on custody fees.
- Regulatory capital requirements:Banco de España mandates minimum operational reserves that strain thin-margin discount models.
- Substitute product encroachment:Crypto-asset exchanges siphon younger retail cohorts seeking 24/7 trading access outside equity market hours.
Strategic Opportunities
- Andalusia and Valencia underpenetration:Self-directed investor penetration in southern and eastern Spain lags Madrid by 40 percentage points, offering greenfield acquisition economics.
- ESG scoring integration:EU Taxonomy alignment tools attract sustainability-focused portfolios seeking automated compliance screening.
- Embedded finance distribution:Neobanks and fintech apps white-label brokerage APIs, expanding platform reach without direct customer acquisition spend.
Industry Challenges
- Legacy system integration friction:Incumbents struggle to graft real-time risk engines onto 1990s-era core banking platforms without service disruption.
- Cybersecurity certification timelines:DORA operational resilience standards require penetration testing cycles that delay product launches by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain E-Brokerage Market |
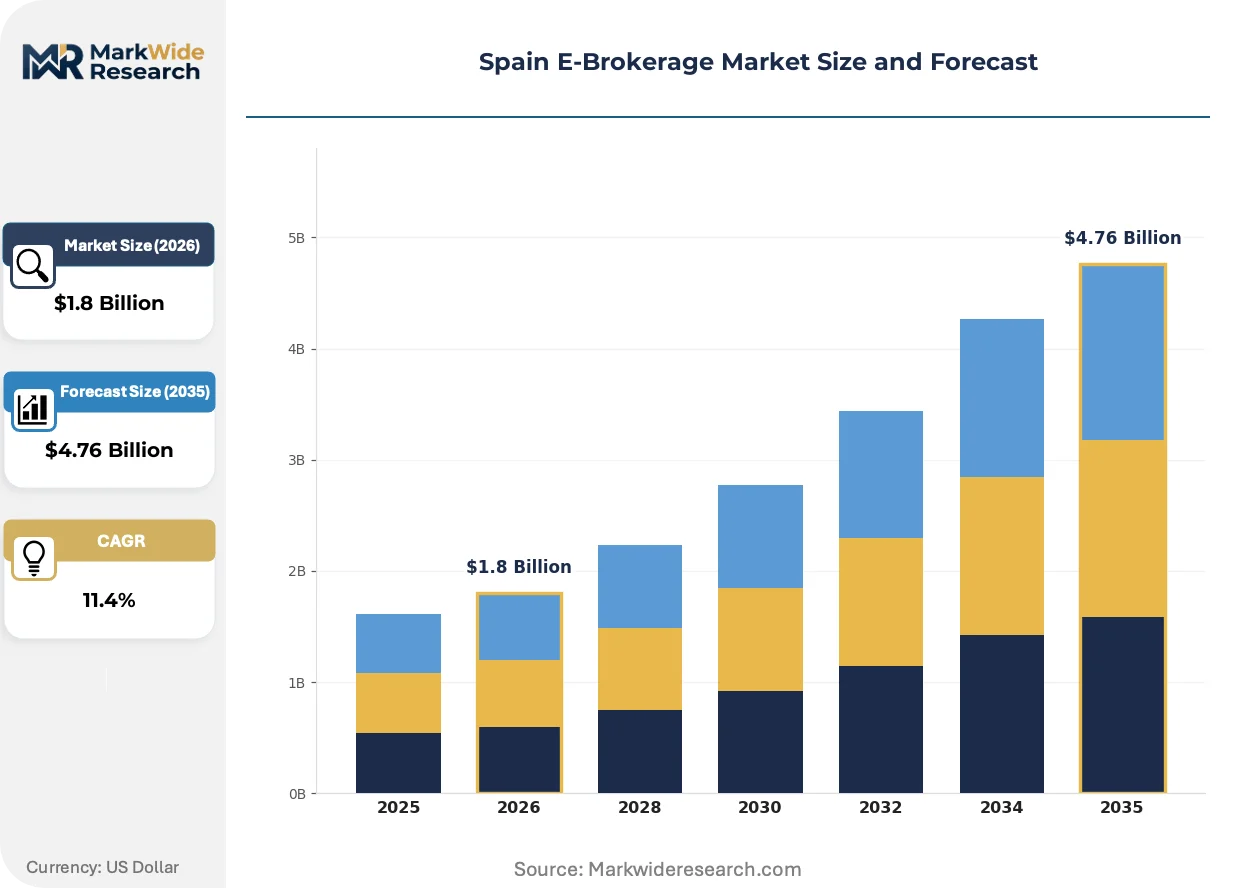
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Web-Based, Mobile App, Desktop Software, Hybrid Service Model: Full-Service Brokerage, Discount Brokerage, Robo-Advisory, Managed Account Customer Segment: Individual Investors, Institutional Traders, High-Net-Worth Individuals, Retail Traders Investment Product: Stocks, ETFs, Forex, Options |
| Companies Covered | eToro, Interactive Brokers, DEGIRO, Banco Santander, BBVA, Renta 4 Banco, XTB, Bankinter, Trade Republic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain E-Brokerage Market Trends and Innovations
Algorithmic execution tools and open-banking data feeds are compressing the information asymmetry between retail and professional traders across Spanish platforms.
Fractional share trading technology is fragmenting ownership structures across previously illiquid blue-chip equities. Madrid-based millennials deploy euro-denominated micro-positions into IBEX 35 constituents previously requiring minimum lot sizes of 100 shares. This capability is fragmenting traditional wealth management relationships as self-directed investors bypass advisory gatekeepers.
Spain's transposition of EU DORA standards mandates operational continuity testing for critical trading infrastructure by January 2025. Platform operators must demonstrate 48-hour recovery capabilities for order management systems or face restricted market access. Neobrokers with cloud-native disaster recovery architectures adapt faster than incumbent banks maintaining on-premise data centers.
Mobile-first account origination now dominates customer acquisition across Spanish brokerage platforms, displacing desktop onboarding flows and branch-based identity verification. Biometric KYC tools integrated into Android and iOS apps reduce account opening from days to minutes. This shift concentrates marketing spend on social media channels targeting Barcelona and Madrid metropolitan areas where smartphone penetration exceeds 94 percent.
Spain E-Brokerage Market Segmentation
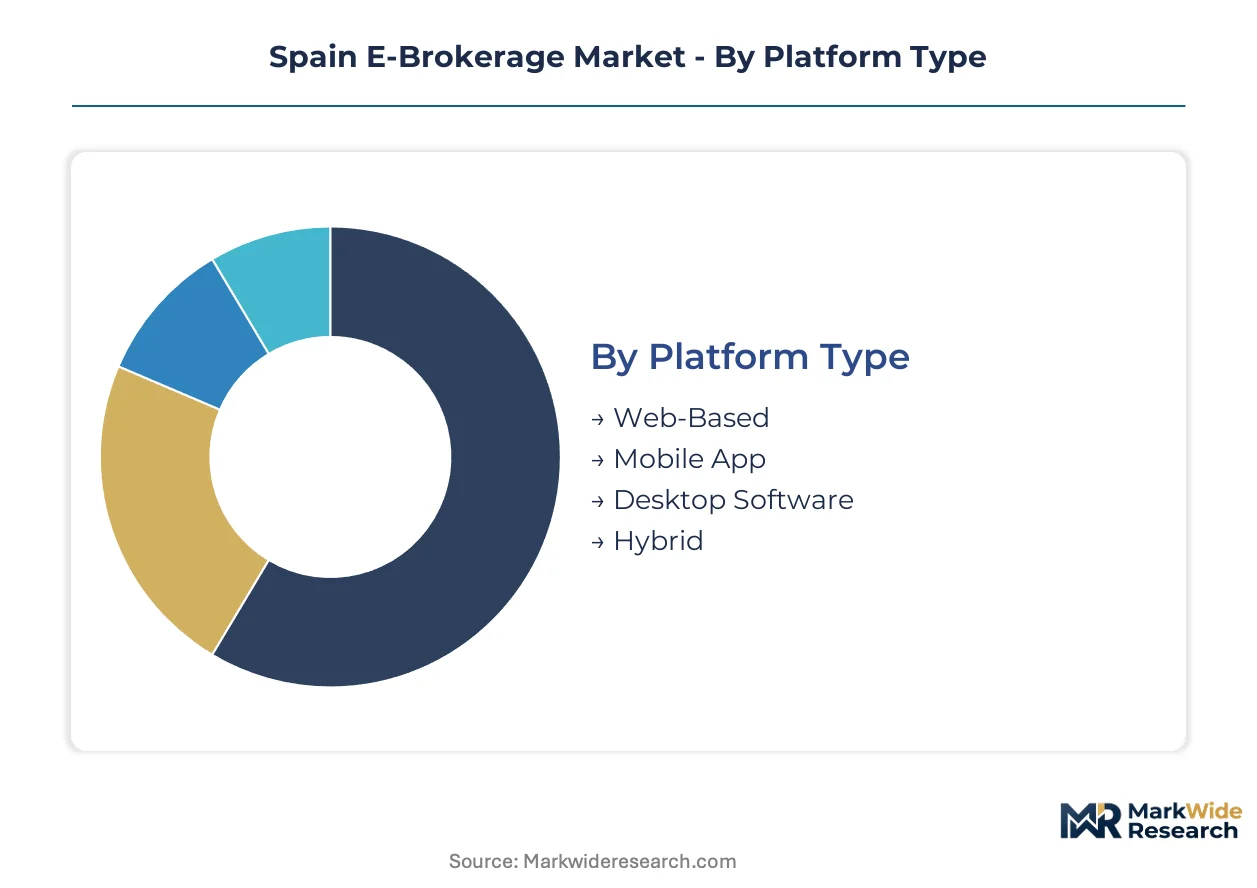
Platform architecture and service intensity define competitive boundaries in Spain's e-brokerage landscape. Segment-specific regulatory exposure and customer acquisition economics determine where neobrokers deploy capital versus where incumbents defend relationships.
Platform Type:
Domestic execution infrastructure concentrates in Madrid and Barcelona data centers, while cloud-native stacks source compute from EU-based hyperscale regions.
- Web-Based:Browser-agnostic interfaces serve occasional traders accessing portfolios from workplace networks. Demand clusters among older investors in northern Spain who prioritize screen real estate over mobility.
- Mobile App:Native iOS and Android applications dominate account origination flows, with biometric KYC reducing onboarding friction to under three minutes. Barcelona's millennial cohort drives the highest session frequency per user.
- Desktop Software:Installable platforms with advanced charting and API connectivity attract algorithmic retail traders in Madrid's financial district. Latency-sensitive order types require dedicated co-location.
- Hybrid:Unified account architectures synchronize positions across devices, enabling seamless workflow handoffs. Adoption spreads fastest among professionals splitting time between office and remote trading.
Mobile App commands the established base. The steepest expansion runs through Hybrid.
Service Model:
Margin structure separates advisory-heavy relationships from execution-only economics, with regulatory capital requirements filtering viable business models.
- Full-Service Brokerage:Human advisor overlays with portfolio construction and tax-optimization services. Concentrated among high-net-worth households in Madrid seeking estate planning integration.
- Discount Brokerage:Flat-fee or zero-commission execution without research distribution. Barcelona-based self-directed investors accelerate platform switches as MiFID II cost transparency exposes hidden spreads.
- Robo-Advisory:Algorithmic portfolio construction with automated rebalancing and EU Taxonomy alignment screening. Fee-conscious millennials in Valencia and Seville favor the hands-off wealth accumulation model.
- Managed Account:Discretionary mandate structures where platform operators execute pre-approved strategies. Institutional penetration remains thin due to Banco de España custody reserve requirements.
Discount Brokerage commands the established base. Robo-Advisory climbs the fastest.
Customer Segment:
Account profitability varies sharply by segment, with acquisition cost recovery periods ranging from months for retail traders to years for institutional relationships.
- Individual Investors:Mass-market accounts with sub-50,000 euro balances executing primarily equity and ETF orders. Andalusia and Valencia underpenetration offers greenfield economics.
- Institutional Traders:Corporate treasuries, family offices, and fund managers requiring block execution and multi-currency settlement. Madrid concentrates decision-making authority.
- High-Net-Worth Individuals:Households with investable assets exceeding 500,000 euros demanding bespoke reporting and alternative access. Relationship stickiness sustains premium pricing.
- Retail Traders:Active speculators with high turnover velocity and derivatives exposure. Social trading features from neobrokers capture this cohort's engagement dependency.
Retail Traders commands the established base. Individual Investors gain share fastest.
Investment Product:
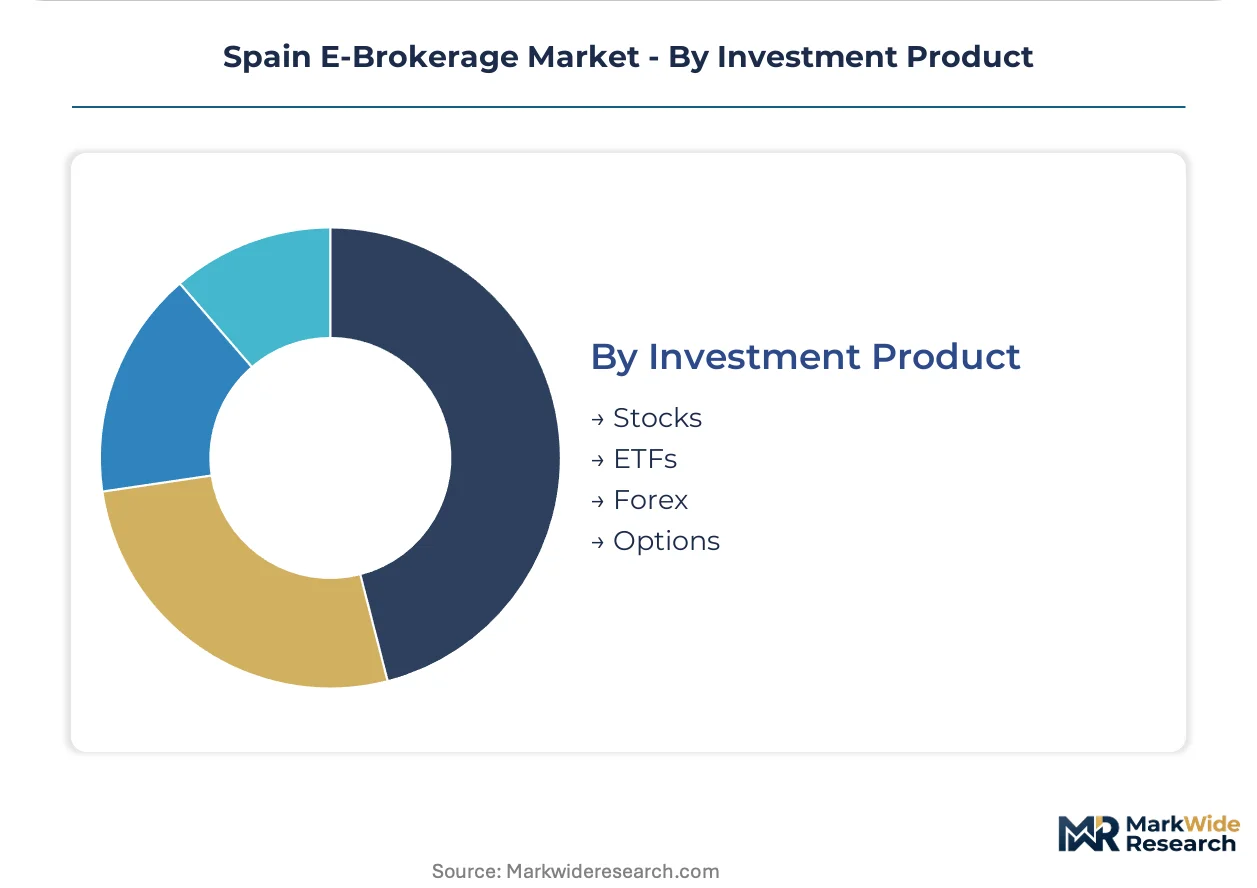
Product mix determines clearing complexity and regulatory reporting burden, with derivatives requiring enhanced risk infrastructure.
- Stocks:Direct equity ownership in Spanish and European listed companies. IBEX 35 constituents attract the highest order flow concentration from domestic accounts.
- ETFs:Exchange-traded fund access with fractional share capabilities enabling euro-denominated diversification. UCITS compliance screening adds platform overhead.
- Forex:Currency pair speculation with leverage restrictions under CNMV retail intervention measures. 24-hour market access competes with crypto exchange alternatives.
- Options:Derivative strategies requiring margin calculation engines and exercise handling. Sophisticated traders in Barcelona drive adoption of multi-leg structures.
Stocks commands the established base. ETFs climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's CNMV anchors regulatory oversight across the Iberian Peninsula, with Madrid and Barcelona data centers processing the majority of order flow. The national market fragments into distinct regional trading ecosystems shaped by local wealth concentration and digital infrastructure maturity.
Madrid
Institutional-grade execution infrastructure clusters in Madrid's financial district, serving corporate treasuries and family offices demanding sub-50 millisecond latency. Banco de España custody reserve requirements filter platform operators seeking to serve high-net-worth households. The capital's fintech engineering talent pools support cloud-native brokerage stack development.
Catalonia
Barcelona's millennial cohort drives the highest mobile trading session frequency per user nationwide. Self-directed investors here accelerate platform switches as MiFID II cost transparency exposes hidden execution spreads. The metropolitan area's 94 percent smartphone penetration enables biometric KYC integration reducing onboarding to under three minutes.
Basque Country
Industrial wealth from manufacturing exports sustains demand for full-service brokerage with human advisor overlays. Bilbao-based investors prioritize estate planning integration and tax-optimization services. Regional savings banks maintain legacy relationships through branch-based identity verification resistant to mobile-first displacement.
Andalusia
Self-directed investor penetration lags Madrid by 40 percentage points, offering greenfield acquisition economics for neobrokers. Seville and Málaga smartphone users favor robo-advisory algorithmic portfolio construction over active trading. SEPA Instant integration eliminates three-day fund settlement friction previously driving account abandonment.
Valencia
The eastern coastal region attracts fee-conscious millennials to hands-off wealth accumulation models. Valencia's underpenetration relative to Madrid creates opportunity for embedded finance distribution through neobank white-label brokerage APIs. Local fintech apps expand platform reach without direct customer acquisition spend.
Spain E-Brokerage Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with neobrokers and incumbent banks occupying distinct competitive spaces. The market structure reflects bifurcated engineering talent pools between legacy banking infrastructure and cloud-native stacks. Three archetypes dominate: social trading platforms leveraging engagement engines, flat-fee discount brokers competing on disclosed pricing, and full-service incumbents defending high-net-worth relationships. Consolidation accelerates among discount brokers unable to absorb MiFID II compliance costs, while strategic partnerships with neobanks expand distribution without proprietary acquisition spend.
Among international platform operators, eToro and Interactive Brokers occupy positions at opposite ends of the service spectrum. eToro exemplifies the social trading archetype sustaining millennial engagement through community-driven execution. Interactive Brokers anchors institutional-grade access for sophisticated traders requiring multi-currency settlement. DEGIRO represents the flat-fee discount model capturing self-directed investors through transparent European equity pricing.
| Leading Market Players |
|---|
| eToro |
| Interactive Brokers |
| DEGIRO |
| Banco Santander |
| BBVA |
| Renta 4 Banco |
| XTB |
| Bankinter |
| Trade Republic |
| Others |
Pricing and Supply Chain Analysis
MiFID II cost-transparency mandates gate both platform qualification and price differentiation simultaneously, forcing disclosure architectures that compress hidden-spread revenue while elevating flat-fee models. Banco de España custody reserve requirements filter viable operators, concentrating pricing power among cloud-native stacks that absorb compliance overhead more efficiently than legacy incumbents.
Pricing Analysis
Madrid-Barcelona spreads on execution fees run 15-30 basis points wider than southern Spanish markets where neobrokers compete aggressively for greenfield accounts. The dominant structure is a hybrid of flat-fee per-trade pricing with subscription tiers for premium data feeds and API access. Price differentiation hinges on execution latency guarantees and CNMV audit trail certification levels. Cost compression in discount tiers is intensifying because MiFID II best-execution rules expose hidden revenue pools. Retail traders in Catalonia exhibit the highest price sensitivity, while Madrid-based institutional accounts prioritize settlement reliability over marginal cost savings.
Supply Chain Analysis
Order management system inventory cycles and clearing integration lead times now stretch 6-9 months due to DORA penetration testing requirements. Core platform infrastructure draws from Ireland, Germany, and the Netherlands for EU-regulated cloud compute, while biometric KYC modules source from Estonia and Lithuania. The supply chain rests on single-source vulnerability at the Iberclear-Euroclear clearing nexus, where custody fee negotiations favor infrastructure incumbents. Distribution runs through white-label API partnerships with neobanks and embedded finance apps, bypassing proprietary customer acquisition channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of engineers fluent in both SEPA-integrated settlement protocols and sub-50 millisecond latency optimization constrains platform differentiation, compressing margins for operators unable to secure specialized talent.
For Market Incumbents: Compound defensive moats by accelerating cloud-native core banking migration ahead of DORA operational continuity deadlines, and deepen clearing relationships with Iberclear to secure custody fee leverage against neobroker price aggression. Legacy system integration friction from 1990s-era platforms represents the existential threat requiring immediate capital redeployment. For New Entrants and Emerging Players: CNMV sandbox fast-track programs for algorithmic execution tools open regulatory pathways without full licensing timelines. Target Andalusia and Valencia where self-directed investor penetration lags Madrid by 40 percentage points, and embed brokerage APIs through neobank distribution partnerships rather than building proprietary acquisition engines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across robo-advisory sub-segments as automated portfolio construction scales without proportional advisor headcount expansion. Over the medium-term horizon, acquisition targets should profile cloud-native discount brokers with established SEPA Instant integration and biometric KYC deployment. The signal to monitor is Banco de España guidance on minimum operational reserve recalibration, which would reshape viable business model economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Migration | Microservices architectures reduce order-routing latency below 50 milliseconds for algorithmic retail traders. |
| SEPA Instant Integration | Same-day euro settlement eliminates three-day friction that previously drove account abandonment in southern Spain. |
| Biometric KYC Deployment | Android and iOS-native identity verification compresses onboarding from days to under three minutes. |
| ESG Scoring Integration | EU Taxonomy alignment tools attract sustainability-focused portfolios seeking automated compliance screening. |
| Embedded Finance Distribution | Neobank white-label APIs expand platform reach without direct customer acquisition spend in underpenetrated regions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across platform engineering, regulatory compliance, and retail trading functions. Primary interviews captured perspectives from CTOs at neobroker platforms, CNMV supervisory staff, Banco de España payment system specialists, and self-directed investor community leads. Secondary validation drew from CNMV circulars, Banco de España financial stability reports, EU DORA technical standards, and SEPA implementation guidelines. Bottom-up account origination flows were triangulated against top-down payment rail transaction data.
The forecasting boundary spans the full analysis window with annual granularity across platform type, service model, customer segment, and investment product dimensions. CAGRs were derived from logistic adoption curves fitted to mobile penetration rates and SEPA Instant diffusion patterns. Model inputs incorporated CNMV enforcement intensity indices and cloud infrastructure capex disclosures from EU hyperscale regions.
Underlying assumptions cover MiFID II disclosure compliance stability and DORA timeline adherence, with deviation risk concentrated in Banco de España custody reserve recalibration and crypto-asset substitute encroachment among younger cohorts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
E-Brokerage Market
Financial Services
Global Business Management Consulting Service Market
Financial Services
Online Investment Platform Market
Financial Services
Global Power Bank Rental Service Market
Financial Services
Source to Pay Market
Financial Services
Foreign Exchange Services Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
CFD Trading Affiliate Programs Market
Financial Services
Mobile Notary Service Market
Financial Services
North America Management Consulting Services Market
Financial Services
China Trade Finance Market
Financial Services
Financial Services Application Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Cash Flow Market