
 Proximity Payment Market | 2026-2036
Proximity Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Proximity Payment Market Analysis
Merchant acquiring channels is narrowing as digital wallet providers consolidate point-of-sale integration paths. Visa Inc. leverages its tokenization infrastructure to secure contactless transaction rails across issuing banks. Mastercard Inc. competes through biometric card pilots that merge fingerprint sensors with EMV chip architecture. Apple Inc. anchors premium mobile wallet adoption via its closed-loop hardware-software payment stack.
Proximity payment denotes short-range data exchange between a consumer device and a merchant terminal, typically operating within 4 centimeters for NFC or via encrypted QR payload transmission, enabling authenticated fund transfer without physical card insertion. Near Field Communication dominates in-person volume due to sub-second latency and established EMV compliance, while QR Code penetration accelerates in cost-sensitive merchant segments where terminal hardware investment is prohibitive. Mobile Wallets capture recurring consumer preference through embedded loyalty and transit credential storage, whereas Contactless Cards retain dominance in markets with mature chip-and-PIN migration.
EMVCo governs global token specification for contactless transactions, while PCI Security Standards Council mandates encryption protocols for cardholder data environments; both frameworks elevate compliance costs for new entrants. The EU AI Act and GDPR impose algorithmic transparency and data minimization requirements on biometric verification workflows in European payment flows. Stakeholders must monitor regulatory divergence between tokenization mandates in Europe and QR-code authentication norms in Asia-Pacific when architecting cross-border acceptance infrastructure.
Market Dynamics
Tokenization infrastructure consolidation is compressing merchant acquiring pathways, as EMVCo and PCI Security Standards Council mandates force smaller payment processors to license proprietary rails rather than build independent authentication stacks.
Growth Catalysts
- Transit Credential Integration:Metropolitan agencies in São Paulo, London, and Tokyo are deploying unified tap-to-ride systems that store transit passes within mobile wallets, converting daily commuters into habitual proximity payment users.
- GDPR-Driven Trust Infrastructure:The EU's data minimization requirements have accelerated tokenized payment architectures that replace raw card data with single-use cryptographic tokens, reducing breach liability for merchants.
- QR Code Cost Arbitrage:Street vendors and micro-merchants across India and Indonesia are adopting static QR displays that eliminate terminal hardware costs entirely, expanding addressable merchant bases beyond NFC penetration limits.
Market Restraints
- Semiconductor Supply Concentration:NFC controller chip fabrication concentrates in Taiwan and South Korea, exposing terminal manufacturers to foundry allocation volatility and 18-24 month procurement lead times.
- Biometric Certification Friction:The EU AI Act's algorithmic transparency mandates for fingerprint and facial recognition payments are extending European biometric card deployment timelines by 12-18 months versus Asian markets.
- Legacy Terminal Stranding:Merchants with EMV chip-and-PIN installations from 2015-2018 face sunk-cost resistance to contactless hardware upgrades despite consumer preference shifts.
Strategic Opportunities
- Offline QR Resilience:India's UPI Lite and similar protocols enable transaction completion without persistent network connectivity, opening rural and underground transit environments previously excluded from real-time settlement.
- Embedded Finance Convergence:Automotive OEMs and appliance manufacturers are integrating payment credentials directly into vehicle head units and smart home devices, bypassing smartphone intermediation entirely.
- RBI's Tokenization Mandate:India's central bank requirement that merchants replace stored card numbers with tokens by September 2024 is forcing rapid infrastructure investment that benefits domestic payment aggregators.
Industry Challenges
- Cross-Border Protocol Fragmentation:European EMV tokenization standards remain incompatible with China's QR authentication norms, forcing acquirers to maintain parallel technical stacks for international travelers.
- Certification Backlog Compression:PCI DSS 4.0 compliance deadlines are overwhelming qualified security assessor capacity, delaying new entrant market entry by 6-9 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proximity Payment Market |
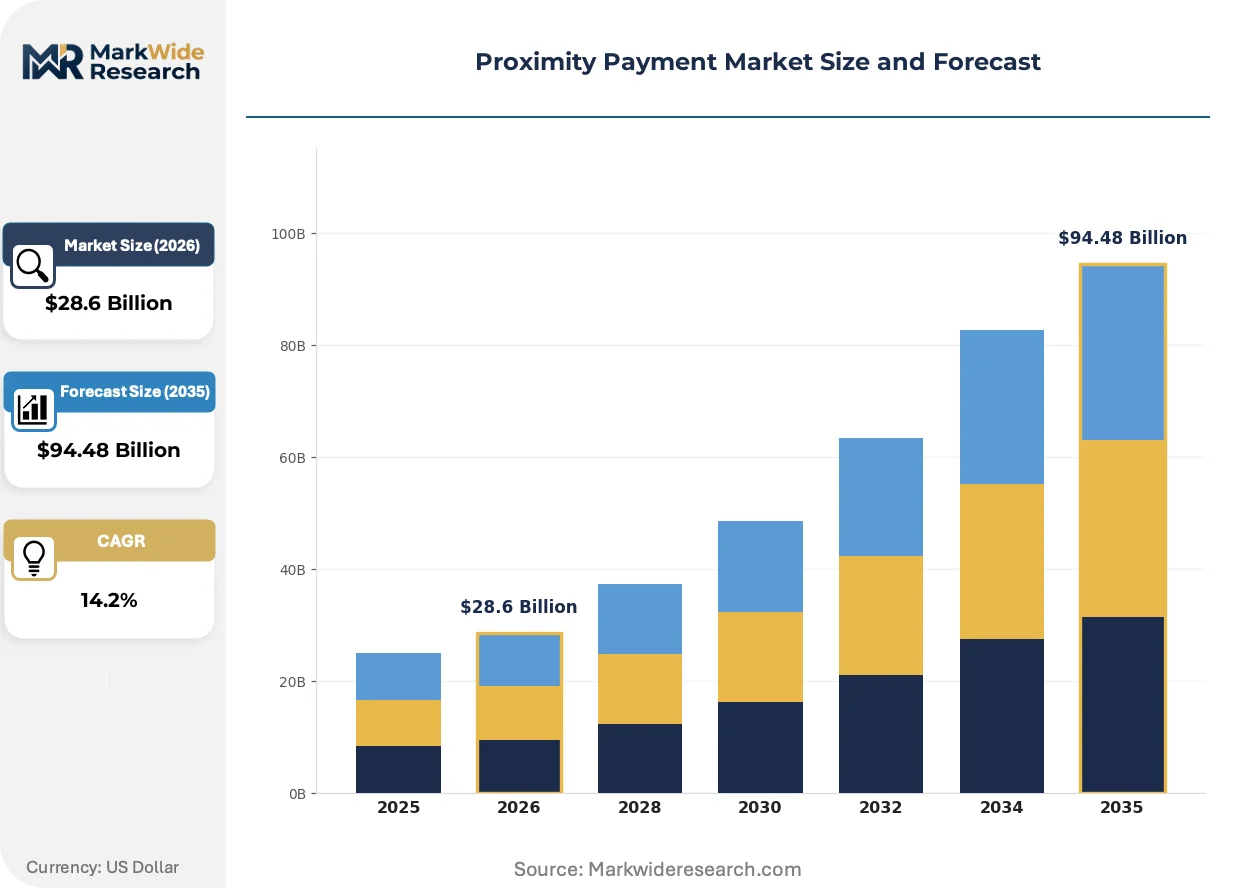
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Near Field Communication, Magnetic Secure Transmission, QR Code, Bluetooth Low Energy Payment Type: Contactless Cards, Mobile Wallets, Wearable Devices, Digital Vouchers End User: Retail Stores, Restaurants, Public Transport, E-commerce Security Method: Tokenization, Encryption, Multi-Factor Authentication, Biometric Verification |
| Companies Covered | Amazon.com Inc., Mastercard Inc., Apple Inc., Stripe Inc., PayPal Holdings Inc., Google LLC, Visa Inc., Adyen N.V., Samsung Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proximity Payment Market Emerging Trajectories
Authentication latency is becoming the primary competitive variable as sub-300 millisecond transaction speeds separate premium acceptance experiences from commodity payment rails.
Biometric card architecture is collapsing the distinction between possession and inherence factors in multi-factor authentication. Transit authorities in Paris and Singapore are piloting fingerprint-activated contactless cards for unbanked riders lacking smartphone access. This convergence is compressing fraud rates in cash-heavy demographic segments while eliminating PIN entry friction.
The EU AI Act's risk-based classification system is mandating algorithmic impact assessments for facial recognition payment flows. German retailers deploying biometric checkout must now document training data provenance and false-positive rates. High-stakes authentication vendors are responding by shifting development resources toward European certification pre-emption rather than feature expansion.
Merchant aggregation models are consolidating small-ticket payment acceptance under platform umbrellas. Street vendors in Mexico City and Bangkok now route transactions through super-app wallets rather than direct bank relationships. This channel compression is visible most acutely in food delivery and ride-hailing verticals where driver earnings settle through embedded wallet infrastructure rather than discrete payment events.
Proximity Payment Market Segmentation
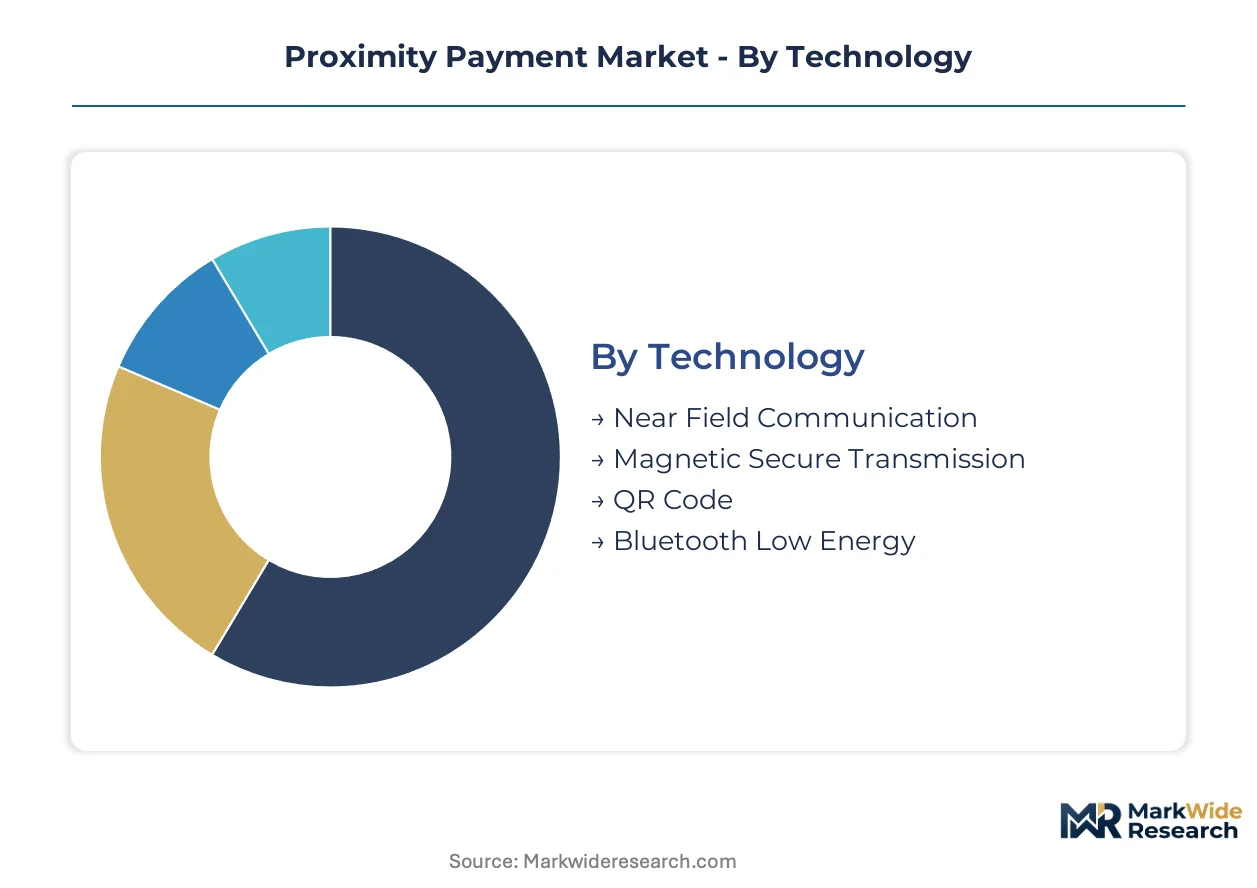
Technology choice determines hardware investment thresholds and merchant onboarding friction in proximity payment deployment. Payment type selection shapes consumer habit formation and credential portability across transit, retail, and online contexts. Security method differentiation separates regulated financial institutions from platform-native wallet providers in compliance architecture.
Technology:
Cost tier stratification separates premium NFC infrastructure from zero-hardware QR alternatives, with magnetic secure transmission occupying a narrowing middle ground.
- Near Field Communication:Sub-second transaction latency and established EMV compliance make NFC the default for transit turnstiles and high-throughput retail. Demand concentrates in São Paulo, London, and Tokyo where metropolitan agencies deploy unified tap-to-ride systems, though semiconductor fabrication concentration in Taiwan and South Korea creates procurement lead time volatility.
- QR Code:Static display codes eliminate terminal hardware costs entirely, enabling street-vendor scale acceptance. Penetration accelerates in India and Indonesia where micro-merchants route transactions through super-app wallets rather than direct bank relationships, constrained by persistent network connectivity requirements in rural environments.
- Magnetic Secure Transmission:Legacy compatibility with magstripe terminals preserves acceptance in markets with delayed EMV migration. Declining relevance as contactless card issuance accelerates.
- Bluetooth Low Energy:Extended range enables hands-free transit gate passage and automotive fueling without device retrieval. Emerging pilot deployments in vehicle head units and smart home appliances.
NFC commands the established base. The steepest expansion runs through QR Code penetration in cost-sensitive merchant segments.
Payment Type:
Application context dictates whether consumers prioritize credential portability, biometric security, or embedded device convenience.
- Mobile Wallets:Embedded loyalty storage and transit credential consolidation drive habitual daily use. Preference concentrates among commuters in metropolitan corridors where unified tap-to-ride systems convert transit passes into persistent payment habits.
- Contactless Cards:Mature chip-and-PIN migration in European markets sustains dominance where consumers resist smartphone intermediation. Sunk-cost resistance from 2015-2018 EMV terminal installations constrains merchant upgrade willingness despite consumer preference shifts.
- Wearable Devices:Fitness band and smartwatch form factors target health-conscious demographics seeking credential portability without phone retrieval. Limited by battery dependency and form factor constraints.
- Digital Vouchers:Prepaid closed-loop instruments serve unbanked populations and corporate disbursement programs. Regulatory divergence between European tokenization mandates and Asian QR authentication norms complicates cross-border redemption infrastructure.
Contactless Cards retain the installed base. Mobile Wallets gain share fastest through transit integration and loyalty embedding.
End User:
Volume concentration varies dramatically by transaction frequency and average ticket size, with public transport generating the highest daily touchpoint density.
- Public Transport:Metropolitan agencies in Paris and Singapore pilot biometric-activated cards for unbanked riders lacking smartphone access. Daily commuter habit formation converts transit credential holders into persistent proximity payment users across retail contexts.
- Retail Stores:Supermarket and convenience store checkout drives contactless volume in markets with mature NFC terminal penetration. Queue reduction pressure accelerates sub-300 millisecond authentication requirements.
- Restaurants:Table-side payment and tip adjustment workflows favor mobile wallet interfaces over card-present transactions. Food delivery verticals route driver earnings through embedded wallet infrastructure.
- E-commerce:Proximity handoff at click-and-collect points bridges online purchase with physical retrieval, though pure digital checkout falls outside core proximity payment definition.
Retail Stores anchor transaction volume. Public Transport shows the steepest expansion trajectory through unified credential systems.
Security Method:
Maturity differentiation separates established tokenization infrastructure from emerging biometric verification facing regulatory certification friction.
- Tokenization:EMVCo global specifications and PCI Security Standards Council mandates force smaller processors to license proprietary rails rather than build independent authentication stacks. RBI's mandate requiring merchants to replace stored card numbers with tokens accelerates infrastructure investment in India.
- Biometric Verification:Fingerprint sensors merged with EMV chip architecture collapse possession and inherence factors in multi-factor authentication. EU AI Act algorithmic transparency requirements extend European deployment timelines versus Asian markets.
- Encryption:PCI DSS 4.0 compliance deadlines overwhelm qualified security assessor capacity, delaying new entrant market entry. Mandatory for all cardholder data environments.
- Multi-Factor Authentication:Layered possession-knowledge-inherence combinations satisfy high-value transaction thresholds. Regulatory divergence between European and Asian authentication norms complicates cross-border acceptance architecture.
Tokenization commands the established base. Biometric Verification climbs the fastest despite certification friction in European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
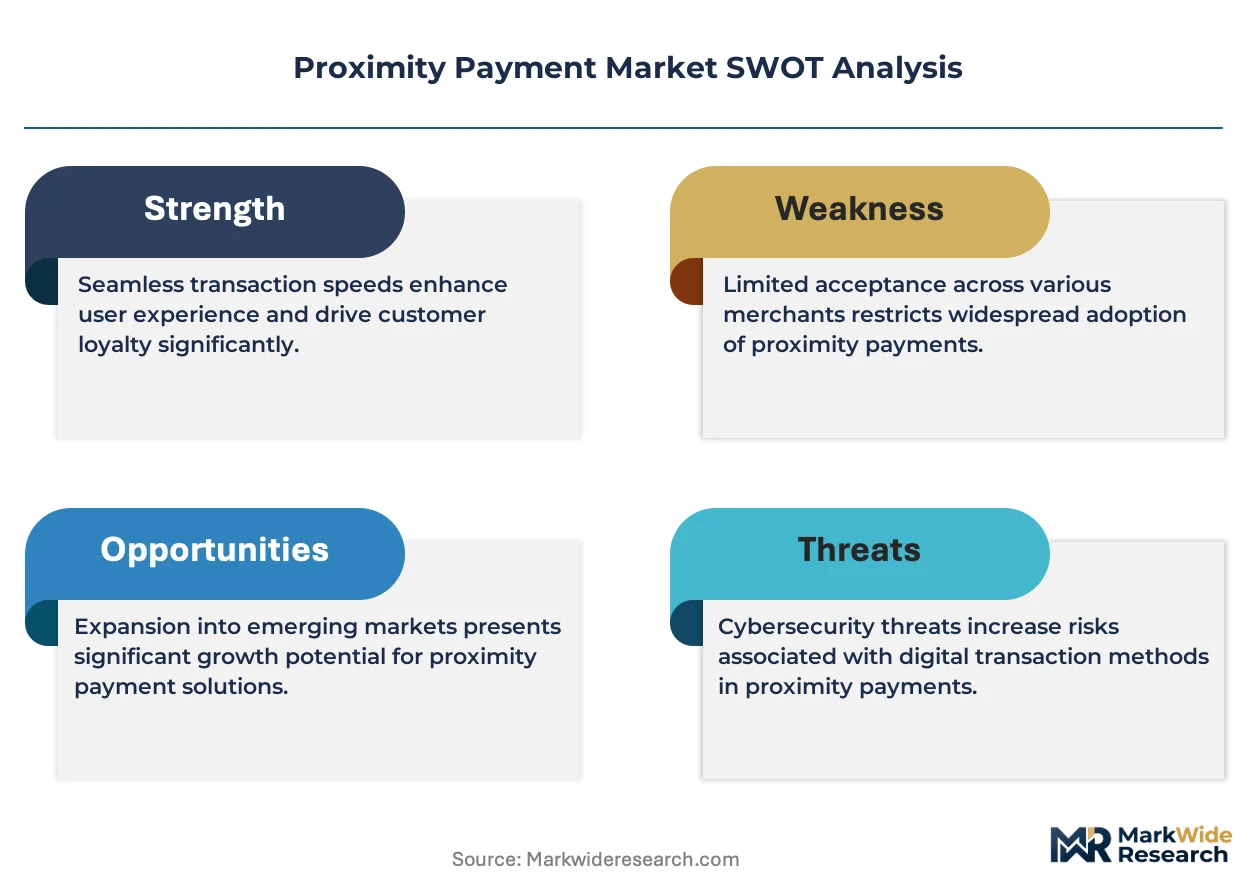
Pricing power concentrates asymmetrically between Chinese QR-code networks and European NFC infrastructure, with Alipay and WeChat Pay extracting minimal merchant fees while EMVCo-compliant terminals impose higher hardware costs on acquirers.
China
Street-vendor scale QR settlement dominates through Alipay and WeChat Pay, normalizing zero-hardware proximity acceptance. SAMR oversees payment platform antitrust compliance and data localization mandates. Shenzhen anchors hardware manufacturing clusters producing NFC controller chips for export markets.
United States
Transit credential integration accelerates in New York and Chicago metropolitan corridors, converting commuters into habitual mobile wallet users. The FTC monitors payment platform competition and merchant fee transparency. Silicon Valley hosts platform integrators consolidating point-of-sale software stacks.
India
UPI Lite protocols enable offline QR transactions in rural and underground transit environments previously excluded from real-time settlement. RBI mandates tokenization infrastructure investment by September 2024. Mumbai payment aggregators expand merchant acquiring pathways under regulatory pressure.
Germany
Contactless card retention persists among consumers resisting smartphone intermediation despite mobile wallet growth. The EU AI Act extends biometric payment certification timelines through algorithmic transparency requirements. Berlin transit authorities pilot fingerprint-activated cards for unbanked riders.
United Kingdom
Unified tap-to-ride systems in London convert daily commuters into persistent proximity payment users across retail contexts. GDPR data minimization requirements accelerate tokenized architectures replacing raw card storage. Manchester fintech clusters develop transit-integrated wallet infrastructure.
Proximity Payment Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying authentication hardware and tokenization engines. The vendor base stratifies between closed-loop ecosystem operators and open-network infrastructure providers. Three archetypes dominate: card network incumbents extending tokenization rails, technology platforms embedding payment into operating systems, and merchant acquirers consolidating small-ticket acceptance. Competitive moves center on transit credential partnerships and biometric certification pre-emption in European markets.
Within the card network tier, Visa Inc. and Mastercard Inc. occupy positions anchoring global token specification and contactless compliance architecture. Among technology platforms, Apple Inc. exemplifies closed-loop hardware-software integration that captures premium mobile wallet adoption through device-native credential storage. These three entities represent the dominant competitive anchors shaping infrastructure investment cycles and merchant acquiring economics across regional markets.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| Mastercard Inc. |
| Apple Inc. |
| Stripe Inc. |
| PayPal Holdings Inc. |
| Google LLC |
| Visa Inc. |
| Adyen N.V. |
| Samsung Group |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwan Semiconductor Manufacturing Company and Samsung Foundry for NFC controller fabrication determines both tiered hardware pricing spreads and supply chain vulnerability profiles across terminal manufacturer procurement strategies.
Pricing Analysis
The customization-premium spread separates EMVCo-certified terminal configurations from baseline QR-code acceptance infrastructure. Pricing stratifies across premium biometric-enabled terminals, standard NFC contactless readers, and economy-tier static QR display setups. Cost compression in economy tiers intensifies because Indian and Indonesian micro-merchants eliminate hardware entirely through super-app wallet routing. Transit agencies in São Paulo and Tokyo demonstrate lowest price sensitivity due to throughput optimization requirements, while street vendors in Mexico City exhibit highest sensitivity to upfront terminal investment.
Supply Chain Analysis
Upstream feedstock for NFC controller silicon draws from Taiwan and South Korea foundry capacity, with substrate materials and advanced packaging services anchoring in Japan and Malaysia. Raw material dependencies center on high-purity silicon wafers, rare-earth elements for magnetic components, and copper-laminate substrates for antenna integration. Single-source vulnerability concentrates in 7nm and below process nodes where TSMC dominates merchant foundry supply. Distribution runs through tier-one terminal OEMs in China and Germany, with downstream channel consolidation under payment platform integrators accelerating.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of qualified security assessor capacity for PCI DSS 4.0 certification creates bottlenecks that determine competitive viability across authentication infrastructure deployment timelines.
For Market Incumbents: Pre-empt biometric certification delays in European markets by front-loading algorithmic transparency documentation under EU AI Act mandates. Secure exclusive transit credential partnerships in metropolitan corridors before platform competitors consolidate habitual user bases. Vertical integration into tokenization engine development reduces licensing exposure to EMVCo specification changes. For New Entrants and Emerging Players: Rural India and underground transit environments in Southeast Asia offer white-space penetration through offline QR protocol deployment. Target unbanked rider segments in São Paulo and Bangkok where fingerprint-activated cards bypass smartphone dependency. Partner with domestic payment aggregators under RBI tokenization mandates to accelerate merchant onboarding velocity. For Investors and Strategic Acquirers: RBI's September 2024 tokenization deadline reshapes the acquisition landscape toward domestic Indian payment infrastructure specialists. Long-term viability hinges on regulatory compliance architecture rather than feature differentiation alone. Monitor qualified security assessor queue lengths as inflection indicator for new entrant market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Transit Credential Partnership | London Underground and Tokyo Metro deployments convert commuters into habitual proximity payment users across retail contexts. |
| Biometric Certification Pre-emption | Early EU AI Act algorithmic documentation accelerates European market entry versus competitors facing 12-18 month delays. |
| Offline QR Protocol Development | India's UPI Lite resilience opens rural and underground environments previously excluded from real-time settlement infrastructure. |
| Tokenization Infrastructure Investment | RBI mandates force rapid merchant migration from stored card data to cryptographic token architectures by domestic aggregators. |
| Embedded Finance Integration | Automotive OEMs and appliance manufacturers bypass smartphone intermediation through direct vehicle head-unit credential storage. |
Methodological Framework
Initial hypotheses were tested against primary input from payment platform executives, transit authority procurement directors, merchant acquiring specialists, and qualified security assessors and refined through secondary validation against EMVCo specification documents, PCI Security Standards Council compliance frameworks, RBI circulars on tokenization mandates, and customs data on NFC terminal hardware imports. Bottom-up terminal deployment estimates triangulated against top-down transaction volume projections.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning technology type, payment instrument, end-use context, and security method tier. CAGRs derived from logistic diffusion curves fitted to transit credential adoption rates and merchant terminal replacement cycles. Industry-specific forecast inputs incorporated foundry capacity allocation schedules and regulatory compliance deadline clustering.
Practitioners should monitor foundry allocation volatility, qualified security assessor capacity constraints, and transit agency procurement timeline acceleration for early signals of forecast revision triggers. Cross-checking against EMVCo published terminal deployment statistics and national payment system operator transaction reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
India Gift Card and Incentive Card Market
Payments
Europe Accounts Payable Automation Market
Payments
Freight Audit and Payment Service Market
Payments
Indonesia Payments Infrastructure Market
Payments
Mobile Payment Security Software Market
Payments
Slovenia Point of Sale (POS) Terminal Market
Payments
Malta POS Terminal Market
Payments
Egypt Mobile Payments Market
Payments
Mpos Terminals Market
Payments
United Kingdom Real Time Payments Market
Payments
Global Financial Cards and Payments Market
Payments
Digital Remittance Service Market
Payments
Cross-Border Payment Platform Market
Payments
South Korea POS Terminals Market
Payments
Dual Interface Payment Card Market
Payments
E-Wallet Market