
 LAMEA Financial Services Software Market | 2026-2036
LAMEA Financial Services Software Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Financial Services Software Market Analytics
The EU Green Deal is broadening sustainability disclosure requirements for financial institutions with cross-border operations in LAMEA, compelling banks to adopt ESG-aligned reporting modules within their software stacks. SAP SE leverages its embedded sustainability analytics to capture this mandate across European-LatAm trade corridors. Oracle Corporation anchors its competitive position through database-tier integration with risk engines serving Gulf banking conglomerates. Temenos AG specializes in cloud-native core banking architectures that reduce on-premises carbon footprints for African retail banks.
Financial services software comprises modular platforms that automate banking operations, securities processing, insurance administration, and regulatory compliance through API-orchestrated workflows, typically deployed with sub-50 millisecond transaction latency thresholds for real-time payment networks. The primary commercial purpose is to replace manual ledger systems with algorithmic transaction routing that reduces operational cost while satisfying audit traceability requirements. Payment Processing solutions dominate transaction volume across LAMEA corridors due to instant payment mandates in Brazil and Nigeria, while Cloud-based deployment captures the fastest expansion as Saudi and Emirati regulators certify domestic data residency frameworks. Core Banking retains the largest installed base but faces margin compression from SaaS challengers with faster implementation cycles.
Brazil's Central Bank open banking regulations, South Africa's POPIA data protection standards, and the UAE's DFSA technology risk requirements collectively shape product certification roadmaps and vendor qualification timelines across the region. SAMR-aligned cybersecurity protocols for Chinese bank subsidiaries in LAMEA further complicate cross-border software licensing structures. Stakeholders must monitor how divergent data localization statutes between Gulf financial centers and Sub-Saharan African markets affect single-tenant versus multi-tenant architecture decisions.
Market Dynamics
Open banking mandates from Brazil's Central Bank and Saudi Arabia's central bank are dismantling decades-old siloed infrastructure across retail banking, forcing incumbent institutions into core system replacement cycles that favor modular, API-native architectures over monolithic legacy stacks.
Growth Catalysts
- Instant payment networks:Brazil's PIX and Nigeria's NIBSS real-time rails are compelling banks to upgrade transaction processing engines to sub-50 millisecond latency thresholds.
- EU Green Deal extraterritoriality:Sustainability disclosure requirements for European banks with LAMEA operations are driving ESG-aligned reporting module procurement.
- Cloud certification frameworks:Domestic data residency approvals from Saudi and Emirati regulators are accelerating multi-tenant SaaS adoption.
Market Restraints
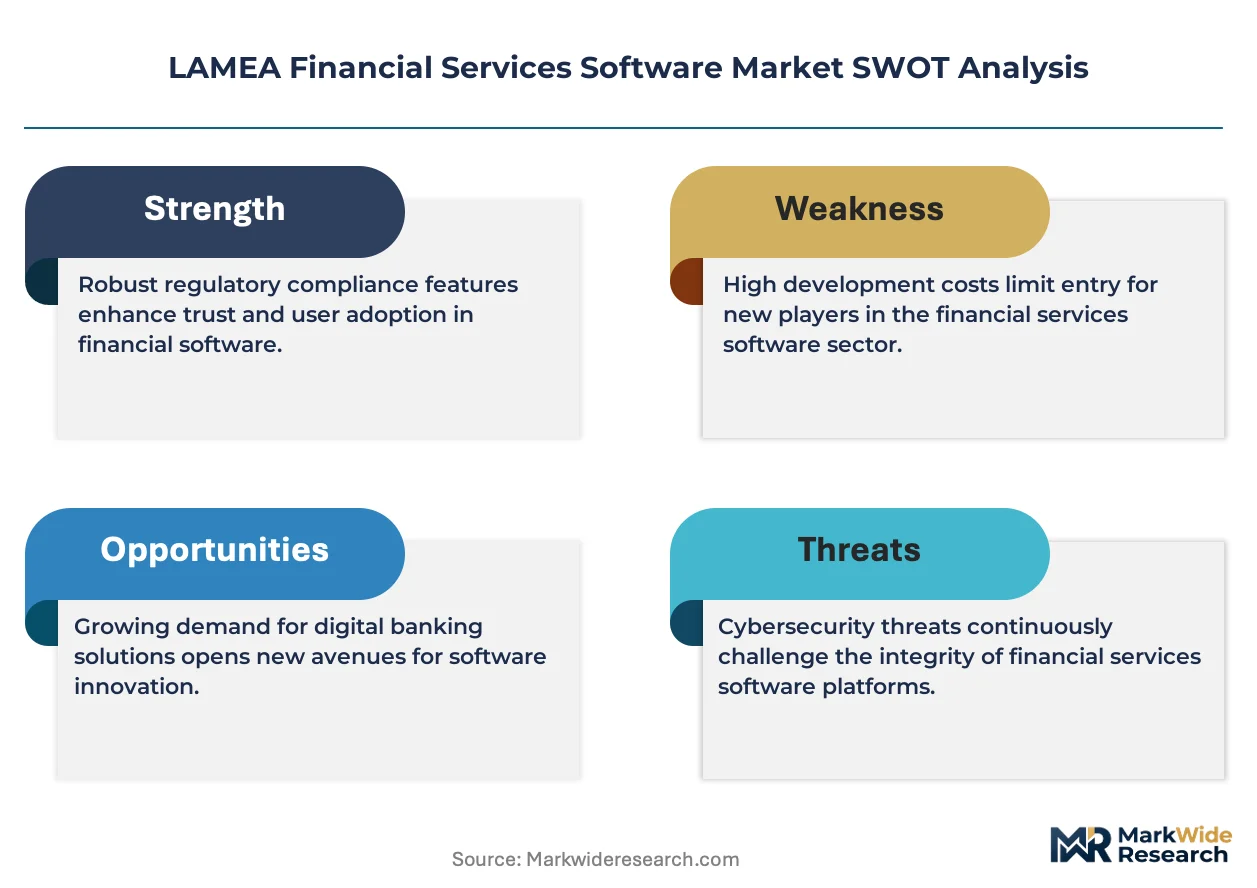
- Legacy core entrenchment:COBOL-based systems in South African retail banks create technical debt that inflates migration costs and extends implementation timelines.
- Input cost volatility:Specialized cloud infrastructure pricing fluctuations in Gulf financial centers compress margins for vendors operating domestic data centers.
- Regulatory fragmentation:Divergent data localization statutes between the UAE's DFSA and Sub-Saharan African markets force expensive single-tenant architecture compromises.
Strategic Opportunities
- Underpenetrated East African corridors:Kenyan and Ethiopian retail banks lack modern core banking infrastructure, creating first-mover advantages for cloud-native vendors.
- Regulatory tailwind from POPIA:South Africa's data protection enforcement is generating demand for privacy-by-design compliance modules.
- Convergence of AI and risk engines:Machine learning integration with real-time fraud detection is opening new product categories for Gulf banking conglomerates.
Industry Challenges
- Integration complexity with mainframe architectures:API orchestration layers must bridge real-time payment networks with batch-oriented legacy ledgers, extending project timelines.
- Certification timeline compression:SAMR-aligned cybersecurity protocols for Chinese bank subsidiaries in LAMEA add parallel approval tracks that delay go-live dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Financial Services Software Market |
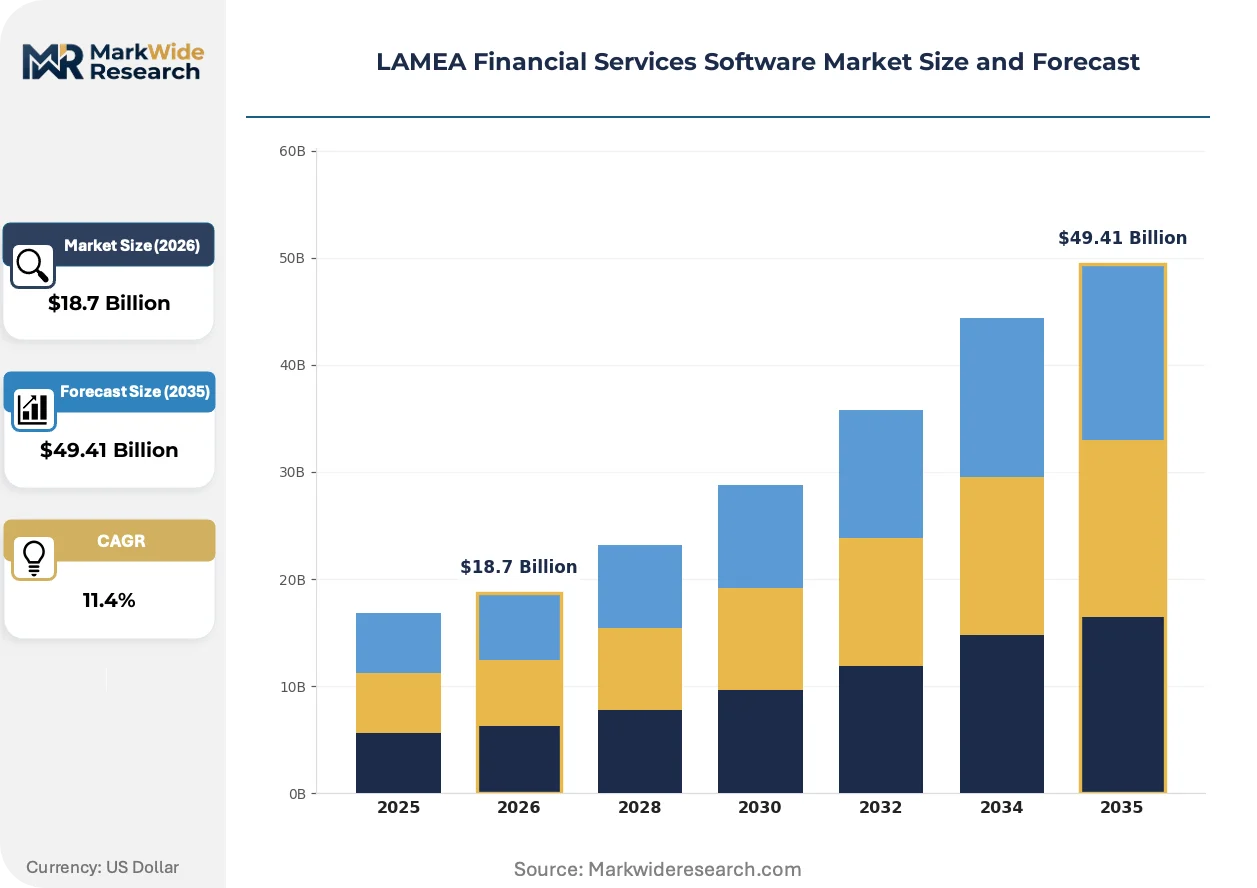
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Banking, Wealth Management, Payment Processing, Risk Management End User: Retail Banks, Investment Firms, Insurance Companies, Credit Unions Deployment: On-premises, Cloud-based, Hybrid, SaaS Solution: Fraud Detection, Customer Relationship Management, Transaction Monitoring, Compliance Management |
| Companies Covered | SAP SE, Fiserv, Inc., Oracle Corporation, Infosys Limited, Temenos AG, Fidelity National Information Services, Inc., The Sage Group PLC, Finastra Group Holdings Limited, Tata Consultancy Services Ltd., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Financial Services Software Market Evolving Landscape
API-orchestrated workflows are displacing point-to-point integrations across payment processing and core banking stacks, compressing vendor implementation cycles and enabling modular procurement that fragments traditional suite-based purchasing patterns.
Cloud-native core banking architectures are consolidating market share among African retail banks seeking to reduce on-premises carbon footprints and escape datacenter capital intensity. Tier-2 institutions in Nigeria and Kenya are adopting these platforms fastest, drawn by subscription pricing that converts fixed infrastructure costs to operational expenditure. The structural consequence is consolidating vendor relationships around fewer hyperscaler-aligned software providers.
Brazil's Central Bank open banking regulations and the UAE's DFSA technology risk requirements are mandating standardized API specifications that force incumbent vendors to rearchitect product roadmaps. These frameworks compel disclosure of transaction metadata that enables third-party fintech aggregation. Gulf banking conglomerates and Brazilian retail networks are responding by building internal API management layers that preserve customer relationship control.
Subscription-based licensing is displacing perpetual software ownership across LAMEA financial institutions, unbundling maintenance from upfront capital commitment. Regional banks in South Africa and Saudi Arabia are leading this transition, attracted by faster upgrade cycles and reduced internal IT overhead. The shift is most visible in payment processing, where instant payment mandates demand continuous platform updates that perpetual licenses struggle to accommodate.
LAMEA Financial Services Software Market Segmentation
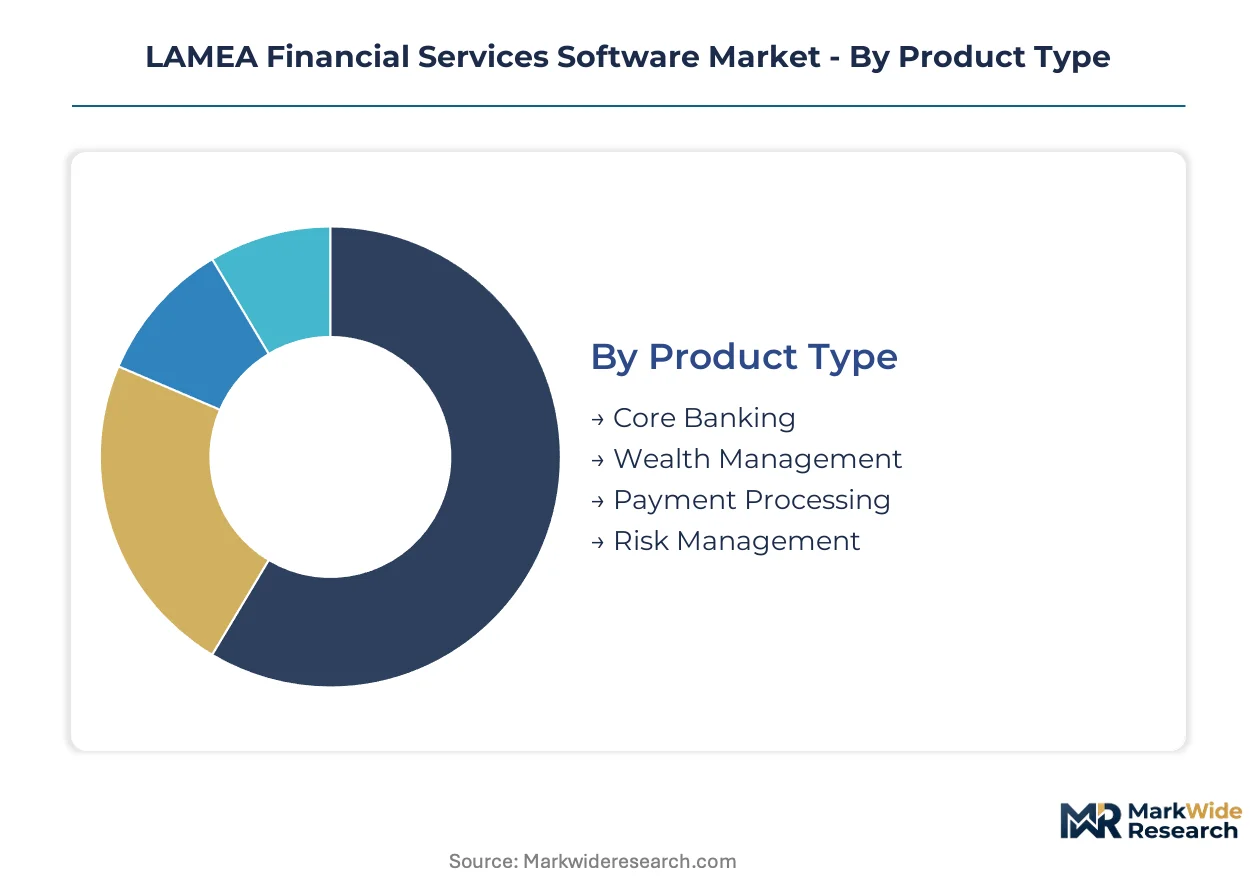
Financial services software procurement across Latin America, the Middle East, and Africa follows distinct capital allocation patterns. Technology investment priorities diver sharply between Gulf banking conglomerates with sovereign backing and African retail institutions constrained by currency volatility.
Product Type:
Capital intensity varies dramatically across product categories, with core system replacement demanding multi-year implementation budgets while peripheral modules deploy with lighter upfront commitment.
- Core Banking:Monolithic transaction ledgers and customer account management engines anchor institutional technology stacks. South African retail banks and Saudi banking conglomerates concentrate replacement demand here as open banking mandates force API-native rearchitecture of decades-old COBOL infrastructure.
- Payment Processing:Real-time transaction routing platforms achieving sub-50 millisecond latency thresholds for instant payment networks. Brazilian institutions drive regional demand following PIX mandate implementation, with Nigerian banks accelerating parallel upgrades to NIBSS infrastructure.
- Wealth Management:Portfolio analytics and advisory platforms serving high-net-worth segments across UAE private banking.
- Risk Management:Integrated credit and market risk engines for Gulf banking conglomerates facing DFSA technology risk requirements.
Core Banking absorbs the bulk of installed capacity; Payment Processing is expanding most quickly.
End User:
Customer sophistication determines solution complexity, with tier-1 institutions demanding customizable enterprise architectures while smaller entities prioritize rapid deployment.
- Retail Banks:Full-service deposit and lending institutions modernizing legacy infrastructure across Brazil, South Africa, and Saudi Arabia. These entities face the most acute pressure from open banking mandates and instant payment network compliance deadlines.
- Investment Firms:Brokerage and asset management operations requiring real-time portfolio analytics and trade execution platforms. UAE-based entities concentrate demand for wealth technology integration with regional capital markets infrastructure.
- Insurance Companies:Policy administration and claims processing automation for carriers across South Africa and Kenya.
- Credit Unions:Member-owned cooperative financial institutions in Latin America seeking cost-efficient cloud migration paths.
Retail Banks command the dominant share of vendor relationships; Investment Firms are climbing the fastest as regional wealth pools expand.
Deployment:
Infrastructure ownership models are shifting as regulatory certification enables alternatives to captive data centers.
- Cloud-based:Multi-tenant architectures hosted on hyperscaler infrastructure with domestic data residency compliance. Saudi and Emirati regulator certifications have unlocked rapid adoption among Gulf banking conglomerates seeking to escape datacenter capital intensity.
- SaaS:Subscription-licensed platforms with vendor-managed maintenance and continuous upgrade cycles. Nigerian and Kenyan tier-2 institutions favor this model for core banking replacement, converting fixed infrastructure costs to operational expenditure.
- On-premises:Self-managed infrastructure retaining dominance among South African retail banks with legacy COBOL entrenchment.
- Hybrid:Split architectures combining cloud scalability with on-premises control for sensitive transaction data.
On-premises retains the largest legacy footprint; Cloud-based deployment is gaining share fastest as regulatory frameworks mature.
Solution:
Functional modules are unbundling from integrated suites as institutions pursue targeted capability procurement.
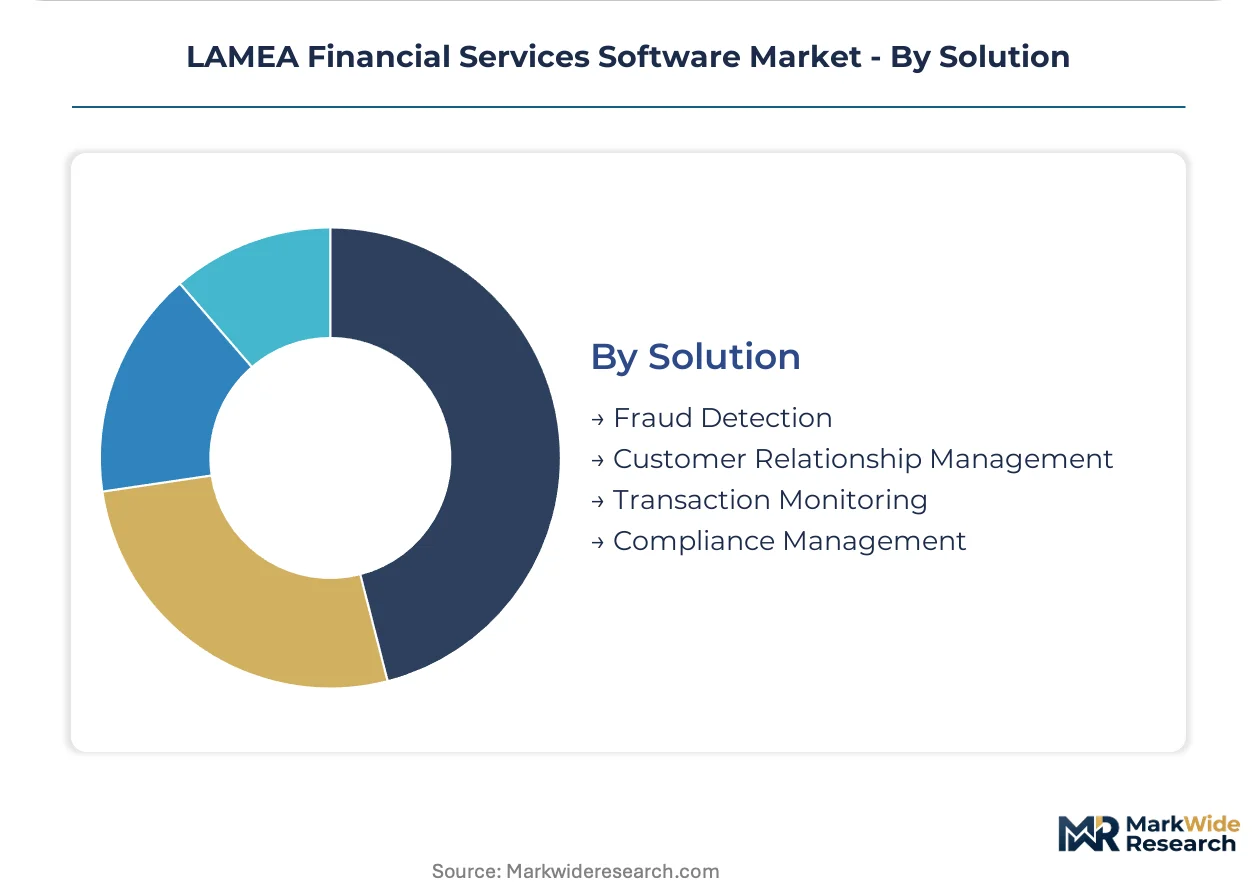
- Fraud Detection:Machine learning-powered transaction surveillance systems identifying anomalous patterns in real-time payment flows. Gulf banking conglomerates concentrate investment here as transaction velocity increases and regulatory scrutiny intensifies.
- Compliance Management:Automated regulatory reporting and audit trail generation for POPIA, SAMR-aligned cybersecurity, and EU Green Deal extraterritorial requirements. South African institutions drive regional procurement following enforcement acceleration.
- Customer Relationship Management:Unified client data platforms for personalized product recommendation across Brazilian open banking ecosystems.
- Transaction Monitoring:Real-time surveillance for anti-money laundering and sanctions screening in UAE financial centers.
Compliance Management captures the steepest expansion trajectory as regulatory fragmentation multiplies reporting obligations; Fraud Detection holds the deepest incumbent penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai International Financial Centre anchors the highest concentration of financial services software procurement across LAMEA, hosting regional headquarters for vendors serving Gulf banking conglomerates and African retail networks.
Brazil
PIX instant payment mandates from Brazil's Central Bank are forcing core system replacements at tier-1 retail banks. Open banking regulations require standardized API disclosure that fragments traditional vendor relationships. São Paulo's financial district concentrates implementation activity for payment processing engines.
Saudi Arabia
SAMA certifications for domestic cloud data residency are accelerating multi-tenant SaaS adoption among banking conglomerates. The central bank's open banking framework compels API-native rearchitecture of legacy infrastructure. Riyadh's King Abdullah Financial District hosts the primary vendor qualification and deployment coordination centers.
South Africa
POPIA enforcement is generating procurement demand for privacy-by-design compliance modules at retail banks with legacy COBOL entrenchment. The national data protection regulator's audit acceleration compresses vendor certification timelines. Johannesburg's financial hub concentrates risk engine and fraud detection platform deployments.
United Arab Emirates
DFSA technology risk requirements are shaping product roadmaps for wealth management and transaction monitoring systems serving private banking. Domestic data residency approvals unlock hyperscaler-aligned cloud migration paths. Abu Dhabi's Global Market and Dubai's financial free zones split vendor regional headquarters functions.
Nigeria
NIBSS real-time payment infrastructure upgrades are compelling transaction processing engine replacements at tier-2 institutions. Currency volatility constrains capital budgets, favoring subscription-licensed SaaS models over perpetual licenses. Lagos anchors West African corridor expansion for cloud-native core banking vendors.
LAMEA Financial Services Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the API-native versus legacy-integrated dimension, with the former capturing implementation speed premiums and the latter defending installed-base maintenance streams. The vendor base organizes around three strategic archetypes: hyperscaler-aligned cloud-native specialists, database-tier incumbents with risk engine integration, and embedded sustainability analytics providers. Consolidation pressure intensifies as open banking mandates fragment traditional suite-based purchasing patterns. Competitive moves center on API management layer acquisitions and domestic data center partnerships for regulatory certification.
Within the European-origin tier, SAP SE and Temenos AG exemplify divergent positioning archetypes, with the former representing embedded sustainability analytics integration and the latter cloud-native core banking specialization. Oracle Corporation anchors the database-tier incumbent position. Infosys Limited and Tata Consultancy Services Ltd. occupy the India-based systems integrator tier that bridges implementation gaps between Western software vendors and LAMEA financial institutions. Fiserv, Inc. and Fidelity National Information Services, Inc. sit within the payment processing specialist category where instant payment mandates drive the steepest expansion.
| Leading Market Players |
|---|
| SAP SE |
| Fiserv, Inc. |
| Oracle Corporation |
| Infosys Limited |
| Temenos AG |
| Fidelity National Information Services, Inc. |
| The Sage Group PLC |
| Finastra Group Holdings Limited |
| Tata Consultancy Services Ltd. |
| Others |
Value Network & Pricing Analysis
API-native versus legacy-integrated performance divergence creates a bifurcated pricing hierarchy across LAMEA financial services software, with subscription-licensed cloud architectures commanding implementation speed premiums while COBOL-maintenance contracts defend entrenched maintenance streams through switching-cost capture. This tier split feeds directly into supply chain configuration, as hyperscaler-aligned vendors concentrate development capacity in Saudi and Emirati certified data centers while legacy integrators anchor professional services networks around Johannesburg and São Paulo.
Pricing Analysis
Throughput-based pricing anchors vendor contracts across payment processing modules, with Brazilian PIX and Nigerian NIBSS compliance thresholds tying fees to transaction velocity guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies by API response latency and domestic data residency certification, with Gulf banking conglomerates absorbing premium tiers for sub-50 millisecond guarantees. Cost compression in standard-tier SaaS offerings is intensifying because Nigerian and Kenyan tier-2 institutions negotiate volume-scaled subscriptions. African retail banks exhibit highest price sensitivity due to currency volatility, while UAE private banking operations demonstrate lowest sensitivity given sovereign-backed capital allocation.
Supply Chain Analysis
Refurbishment flows for legacy COBOL codebases create reverse-logistics dependencies, with South African retail banks contracting specialized maintenance providers to extend mainframe asset life rather than migrate. Software development supply concentrates in India, Ireland, and Poland, with systems integrators drawing from these hubs to serve LAMEA implementation demand. Proprietary risk engine libraries and hyperscaler compute credits constitute critical input dependencies. Single-source vulnerability runs through certified domestic data center capacity in Saudi Arabia and the UAE, where regulator-approved facilities face capacity constraints. Distribution runs through Dubai International Financial Centre as the primary regional coordination node for vendor qualification and deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified domestic data center capacity scarcity across Gulf financial centers props pricing power for hyperscaler-aligned vendors, constraining rapid SaaS expansion despite regulatory tailwinds. This bottleneck concentrates procurement leverage among incumbent players with pre-certified infrastructure.
For Market Incumbents: Acquire API management layer specialists to defend against modular procurement fragmentation driven by Brazil's Central Bank open banking mandates. Consolidate channel control through exclusive partnerships with Saudi and Emirati certified data center operators, blocking challenger access to regulatory-compliant hosting capacity. COBOL-maintenance revenue streams require protection via long-term service contracts that embed switching-cost escalation clauses. For New Entrants and Emerging Players: Launch via Kenyan and Ethiopian tier-2 retail banking corridors, where core banking infrastructure underpenetration creates first-mover subscription conversion opportunities. Target Nigerian credit unions and cooperative institutions with lightweight SaaS core banking modules priced below legacy vendor maintenance fees. Go-to-market acceleration hinges on pre-certification against South Africa's POPIA data protection standards, enabling rapid multi-country deployment. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler-aligned cloud-native specialists with existing SAMR-aligned cybersecurity certification for Chinese bank subsidiary access. Long-term viability favors vendors with demonstrated regulatory certification velocity across multiple LAMEA jurisdictions rather than single-market depth. Acquisition target archetype: African-focused core banking SaaS providers with established tier-2 bank reference sites. Monitor Saudi SAMA and UAE DFSA certification queue lengths as early signals of vendor scalability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| API Management Layer Acquisition | Captures open banking mandate value by enabling third-party fintech orchestration for Brazilian retail networks. |
| Domestic Data Center Partnership | Unlocks SAMA-certified capacity for Saudi banking conglomerates seeking cloud migration compliance. |
| POPIA Compliance Module Development | Addresses South African enforcement acceleration with privacy-by-design architecture for retail banks. |
| Machine Learning Risk Engine Integration | Converges AI capabilities with real-time fraud detection for Gulf banking conglomerate procurement. |
| East African Geographic Expansion | Establishes first-mover position in Kenyan and Ethiopian core banking replacement cycles. |
Research Methodology
Multi-period observation of PIX transaction volume trajectories, NIBSS infrastructure upgrade timelines, and POPIA enforcement acceleration anchored the trend analysis, supplemented by interviews with CTOs at Brazilian tier-1 retail banks, IT procurement officers at Saudi banking conglomerates, platform engineers at UAE private banking operations, and integration specialists serving Nigerian tier-2 institutions. Secondary validation drew from Brazil Central Bank regulatory filings, SAMA certification disclosures, DFSA technology risk guidance documents, and SEC 10-K filings of listed financial services software vendors. Bottom-up deployment tracking across identified institutions combined with top-down market sizing through vendor revenue attribution.
Segment-weighting applied deployment model, organization tier, and integration complexity as primary dimensions across the modeling period, with vertical specialization and regional regulatory cluster as secondary stratifiers. CAGRs derived from slope analysis of observed adoption curves rather than extrapolated trend fitting. Industry-specific forecast inputs included open banking mandate implementation schedules and domestic data residency certification velocity.
Regulatory timeline delays, currency volatility spikes in Sub-Saharan African markets, and hyperscaler capacity constraints in Gulf financial centers are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding certification queue processing rates and tier-2 bank capital allocation stability. Practitioners should monitor SAMA and DFSA certification announcement frequencies and Nigerian naira exchange rate bands for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Contract for Difference Broker Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Latin America Factoring Services Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Benefits Consulting Service Market
Financial Services
North America B2C Legal Services Market
Financial Services
Africa Factoring Services Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Credit Rating Software Market
Financial Services
Banknote Counters Market
Financial Services
Trade Finance Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Global P2P Fundraising Tool Market
Financial Services
Global Financial Consulting Software Market
Financial Services
Digital Account Opening Market
Financial Services
Global Business Management Consulting Service Market