
 Southeast Asia E-Invoicing Market | 2026-2036
Southeast Asia E-Invoicing Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia E-Invoicing Market Analytics
Market Context
Retail and e-commerce platform adoption is hardening as the dominant end-use vertical across Southeast Asia. SAP SE leverages its ERP integration depth to anchor large enterprise deployments in Thailand and Vietnam. Basware Corporation specializes in accounts-payable automation, sustaining competitive positioning through PEPPOL network connectivity. Tradeshift competes on supplier onboarding velocity, extending its cloud-native architecture to mid-market distributors in Indonesia.
Technical Definition and Segment Structure
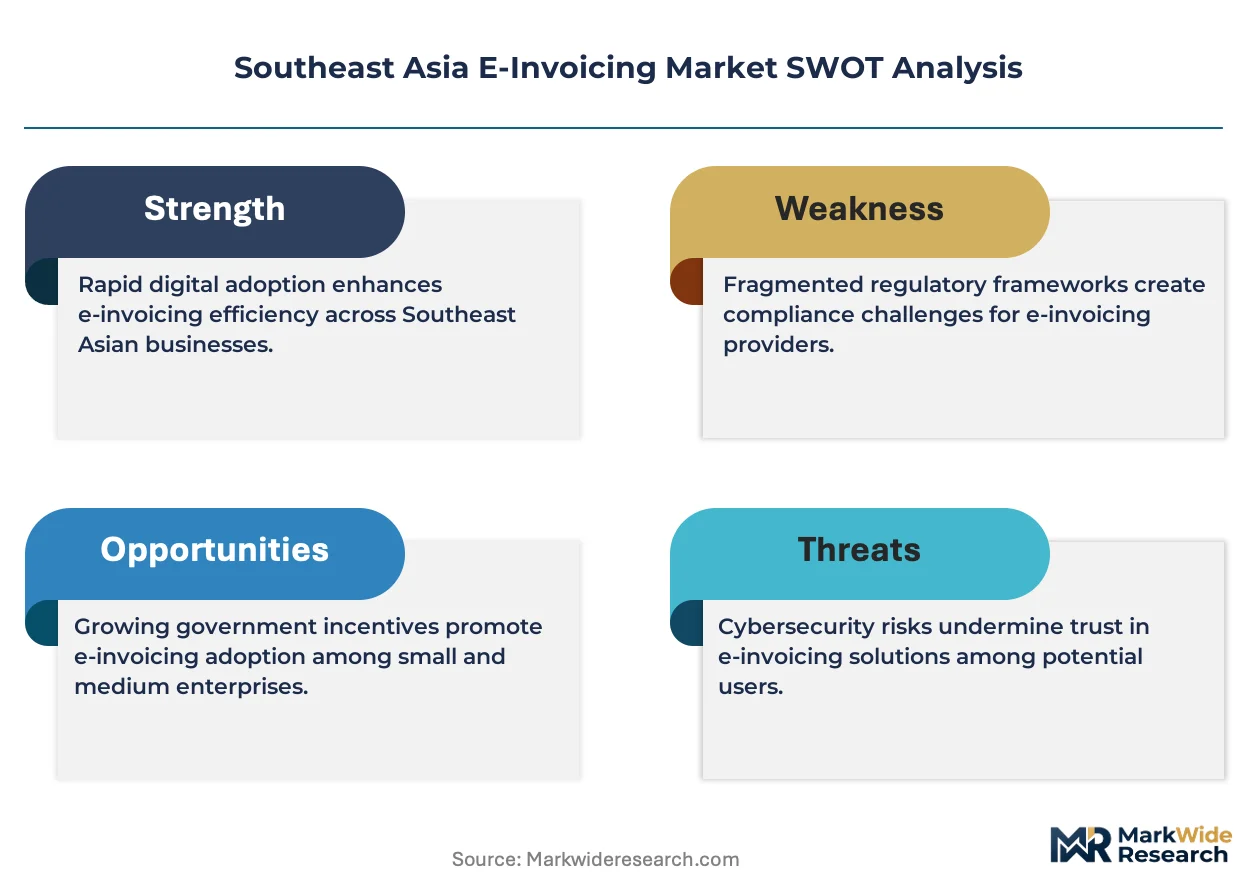
E-invoicing denotes the structured electronic exchange of invoice data between buyers and suppliers through standardized formats such as XML or UBL, enabling automated validation, tax reporting, and payment reconciliation without manual document re-entry. Cloud-based technology leads current deployment preference due to lower capital barriers and faster regulatory update cycles, while hybrid models capture financial institutions requiring on-premise data sovereignty with cloud scalability. The SME end-user segment represents the fastest-growing addressable pool as tax digitization mandates expand threshold coverage across ASEAN economies.
Regulatory Framework and Outlook
Indonesia's Directorate General of Taxes enforces real-time e-invoice clearance through its e-Faktur system, while Thailand's Revenue Department mandates structured data submission under its e-Tax framework. Vietnam's General Department of Taxation accelerates compliance deadlines, forcing legacy accounting software replacements. Stakeholders must monitor interoperability standard convergence between national PEPPOL variants and emerging ASEAN-wide protocols.
Market Dynamics
Indonesia's real-time tax clearance mandate through its e-Faktur system is compressing deployment timelines and forcing wholesale replacement of legacy accounting infrastructure across the archipelago.
Growth Catalysts
- PEPPOL Network Expansion:Thailand's Revenue Department e-Tax framework mandates structured data exchange, accelerating supplier onboarding to national interoperability gateways.
- Cloud-Native Architecture:Lower capital barriers enable mid-market distributors to bypass on-premise ERP upgrades entirely.
- SME Mandate Threshold Reduction:Vietnam's General Department of Taxation compliance deadline acceleration widens the addressable base beyond large enterprises.
Market Restraints
- Fragmented National Standards:Divergent PEPPOL variants across ASEAN create integration friction for cross-border invoice routing.
- Legacy System Sunk Costs:Decades-old on-premise ERP installations in Indonesian conglomerates resist cloud migration despite regulatory pressure.
- Data Sovereignty Requirements:Thai financial institutions demand hybrid deployments, inflating total cost of ownership versus pure-cloud alternatives.
Strategic Opportunities
- Philippines Digital Economy Framework:Pending tax digitization legislation creates first-mover positioning before mandate enforcement.
- API-First Integration:Open banking standards convergence with e-invoicing protocols enables embedded finance products for e-commerce platforms.
- Cross-Border ASEAN Protocol:Emerging regional interoperability standards promise unified invoice clearing across member states.
Industry Challenges
- XML/UBL Expertise Scarcity:Local system integrators lack depth in structured data format implementation, extending deployment timelines.
- Multi-Jurisdiction Compliance Burden:Pan-ASEAN enterprises must maintain parallel validation rules for Indonesia, Thailand, and Vietnam simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia E-Invoicing Market |
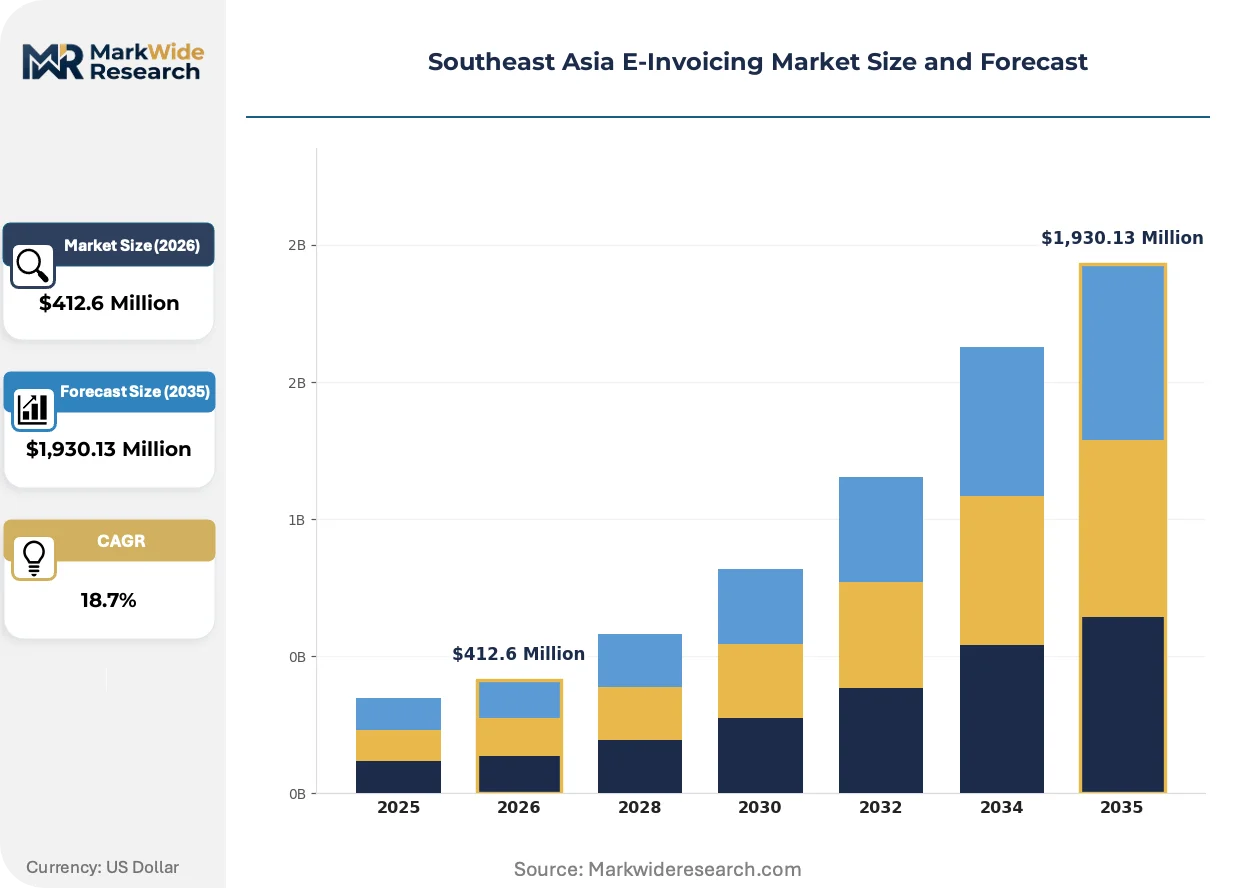
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,930.13 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-based, On-premise, Hybrid, SaaS End User: SMEs, Large Enterprises, Government, Financial Institutions Deployment Model: Public Cloud, Private Cloud, Community Cloud, Hybrid Cloud Service Type: Implementation, Consulting, Support, Maintenance |
| Companies Covered | Comarch SA, The Sage Group Plc, SAP SE, Basware Corporation, Tradeshift, IBM Corporation, Cegedim SA, Nipendo Ltd., Coupa Software Inc., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia E-Invoicing Market Evolving Landscape
Real-time tax reporting architectures are overtaking batch-based submission systems, compressing invoice validation from days to seconds and eliminating post-hoc audit trails.
Cloud-native SaaS platforms is overtaking installed ERP modules in mid-market penetration. Indonesian distributors bypass capital-intensive on-premise upgrades entirely. This shift compresses vendor selection cycles from quarters to weeks.
Thailand's Revenue Department e-Tax Invoice and Receipt framework tightens data field requirements quarterly. Enterprises must reconfigure validation engines repeatedly. Large retailers respond by embedding compliance logic directly into transaction systems rather than retrofitting accounting modules.
Buyer procurement teams now mandate PEPPOL-ready supplier onboarding as a contract prerequisite. Traditional email-and-PDF invoice acceptance is contracting to exception handling only. Vietnamese manufacturers face the steepest compliance pressure as export customers enforce interoperability standards.
Southeast Asia E-Invoicing Market Segmentation
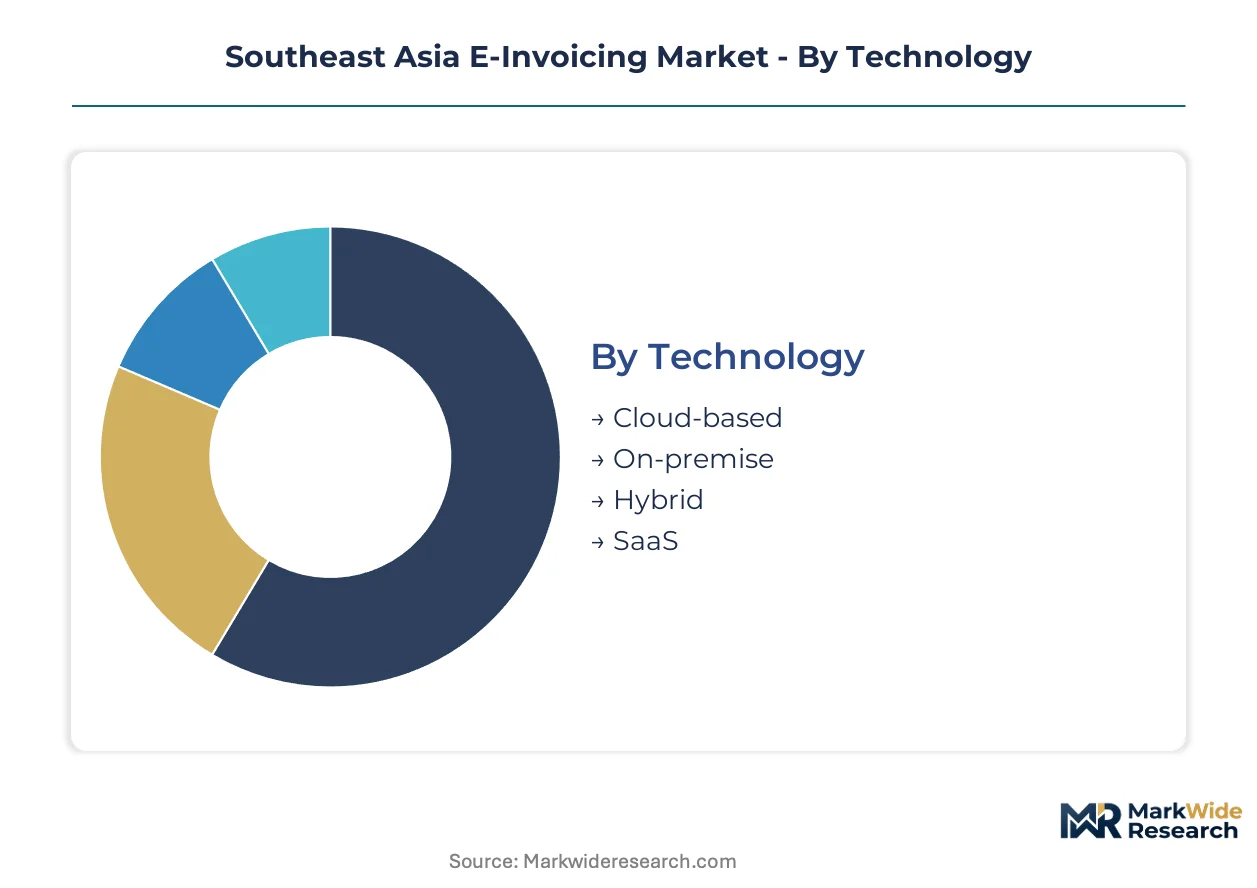
E-invoicing deployment patterns across Southeast Asia diverge sharply by infrastructure maturity and regulatory pressure. Technology choices determine integration complexity with national tax systems. End-user scale dictates compliance threshold exposure and vendor selection criteria.
Technology:
Architecture decisions hinge on data sovereignty requirements and capital availability across Indonesian, Thai, and Vietnamese deployments.
- Cloud-based:Multi-tenant SaaS platforms eliminate server procurement cycles. Indonesian distributors adopt these to bypass legacy ERP replacement costs entirely while meeting Directorate General of Taxes real-time clearance mandates.
- On-premise:Installed software behind corporate firewalls. Thai financial institutions retain these configurations to satisfy internal audit requirements despite higher maintenance overhead.
- Hybrid:Split architectures route sensitive data locally while pushing routine processing to cloud nodes. Vietnamese manufacturers deploy these to balance export customer PEPPOL connectivity with domestic compliance data retention.
- SaaS:Subscription-delivered application layers with automatic regulatory update propagation. Mid-market retailers across ASEAN favor these for quarterly e-Tax framework reconfiguration without IT staff expansion.
Mature deployment sits with on-premise installations in established conglomerates. Newer deployment is concentrated in cloud-based platforms among SMEs facing compressed compliance deadlines.
End User:
Organizational scale determines mandate coverage timing and solution complexity requirements.
- SMEs:Businesses below revenue thresholds now face phased e-invoicing obligations. Vietnamese General Department of Taxation threshold reductions are pulling hundreds of thousands of smaller enterprises into compliance scope.
- Large Enterprises:Conglomerates with multi-jurisdiction operations. These organizations maintain parallel validation engines for Indonesia's e-Faktur, Thailand's e-Tax, and Vietnam's emerging protocols simultaneously.
- Government:Public sector procurement bodies. State-owned enterprises in Indonesia and Thailand now mandate PEPPOL-ready supplier onboarding as a contract prerequisite.
- Financial Institutions:Banks and insurers with heightened data sovereignty constraints. Thai institutions particularly demand hybrid deployments that inflate total cost of ownership versus pure-cloud alternatives.
Procurement volume concentrates in large enterprises. SME segment expansion is climbing the fastest as mandate thresholds descend.
Deployment Model:
Infrastructure tenancy arrangements reflect risk tolerance and cross-border data flow patterns.
- Public Cloud:Shared infrastructure with provider-managed security. Indonesian e-commerce platforms leverage these for elastic capacity during promotional sales periods without capital commitment.
- Private Cloud:Dedicated single-tenant environments. Thai banks deploy these to maintain physical data location control while gaining cloud scalability benefits.
- Community Cloud:Sector-specific shared infrastructure. Healthcare and logistics consortia in Vietnam experiment with these for standardized invoice exchange within industry verticals.
- Hybrid Cloud:Workload-optimized distribution across public and private nodes. Pan-ASEAN manufacturers use these to keep domestic tax data local while routing international trade documentation through global cloud regions.
Conservative deployment favors private cloud among regulated sectors. Aggressive expansion concentrates in public cloud among digital-native retailers.
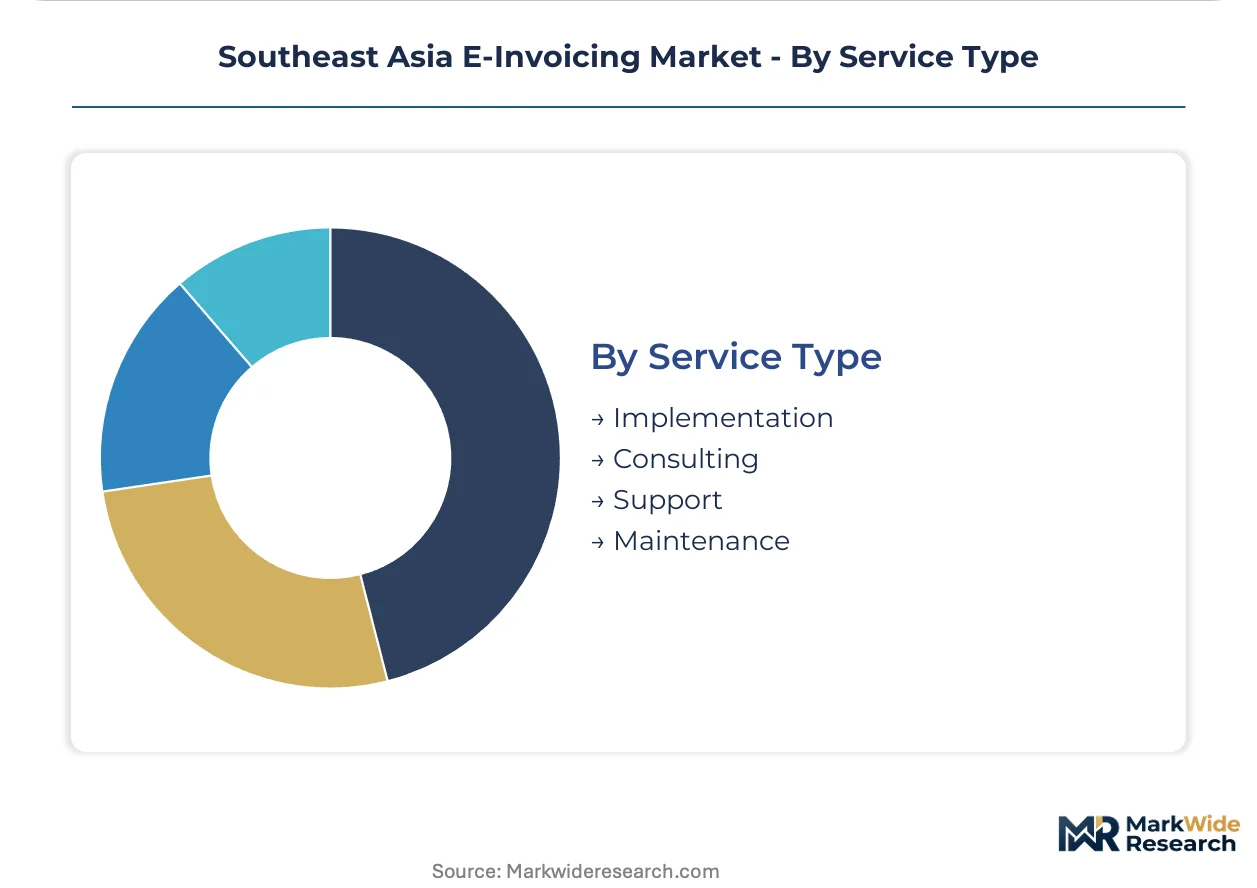
Service Type:
Professional service attachment rates vary by internal technical capability and regulatory change velocity.
- Implementation:System integration and data migration execution. Local Indonesian system integrators with XML/UBL expertise command premium pricing due to scarcity.
- Consulting:Compliance strategy and process redesign advisory. Thai enterprises engage these services repeatedly as Revenue Department e-Tax requirements tighten quarterly.
- Support:Ongoing technical assistance and troubleshooting. Vietnamese manufacturers rely heavily on these due to limited internal IT capacity.
- Maintenance:Update management and performance optimization. Subscription models now bundle these with SaaS platforms, reducing standalone procurement.
Revenue concentration sits with implementation services during mandate rollout phases. Recurring maintenance contracts are expanding most quickly as installed bases mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia generates the highest deployment volumes for e-invoicing infrastructure, while Vietnam and Thailand concentrate implementation service demand. Singapore functions as the regional interoperability standards hub, with Malaysia and the Philippines building compliance frameworks.
Indonesia
Jakarta's e-commerce platforms and Surabaya's manufacturing clusters drive cloud-native adoption to meet real-time clearance mandates. The Directorate General of Taxes enforces e-Faktur system compliance with quarterly threshold reductions. West Java's textile exporters face the steepest legacy ERP replacement pressure as buyer procurement teams mandate PEPPOL-ready documentation.
Thailand
Bangkok's financial institutions and Chiang Mai's electronics assemblers anchor hybrid deployment demand for data sovereignty compliance. The Revenue Department's e-Tax framework tightens structured data field requirements every quarter. Eastern Economic Corridor manufacturers embed validation logic directly into transaction systems to avoid repeated accounting module reconfiguration.
Vietnam
Ho Chi Minh City's distributors and Hanoi's state-owned enterprises lead SME segment expansion as mandate thresholds descend. The General Department of Taxation accelerates compliance deadlines for businesses below previous revenue exemptions. Northern industrial zones around Hai Phong experiment with community cloud infrastructure for standardized invoice exchange within automotive supply chains.
Singapore
The city-state's trade finance platforms and logistics technology providers anchor regional PEPPOL gateway development. Enterprise Singapore promotes cross-border invoice standardization through bilateral interoperability agreements. Jurong's chemical processing clusters and Tuas port operators pilot API-first integration between open banking protocols and e-invoicing networks.
Southeast Asia E-Invoicing Market Competitive Landscape
Top-tier vendors anchor enterprise ERP integration, while mid-market specialists compete on supplier onboarding velocity and cloud-native architecture. The vendor base stratifies across three functional tiers: legacy ERP extenders, accounts-payable automation specialists, and transaction network platforms. Consolidation pressure intensifies as national mandate deadlines compress procurement cycles from quarters to weeks. Dominant competitive moves include strategic partnerships with national tax authorities and geographic expansion through local system integrator alliances.
Within the ERP extender tier, SAP SE and The Sage Group Plc represent established archetypes leveraging installed base depth for large-enterprise retention. Basware Corporation and Tradeshift exemplify contrasting positioning—one anchoring accounts-payable automation through PEPPOL connectivity, the other competing on cloud-native supplier onboarding for Indonesian distributors. IBM Corporation occupies a hybrid position spanning infrastructure services and compliance consulting across multi-jurisdiction deployments.
| Leading Market Players |
|---|
| Comarch SA |
| The Sage Group Plc |
| SAP SE |
| Basware Corporation |
| Tradeshift |
| IBM Corporation |
| Cegedim SA |
| Nipendo Ltd. |
| Coupa Software Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up SaaS specialists in Indonesia and Thailand have consolidated fragmented local system integrators, tightening pricing discipline among implementation providers while compressing deployment timelines for mid-market distributors facing Directorate General of Taxes mandates.
Pricing Analysis
Margin tightening in cloud-native tiers reflects aggressive vendor land-grab strategies targeting Vietnamese SME mandate expansions. Three-tier pricing structure across premium ERP-integrated, standard PEPPOL-gateway, and economy self-service levels separates enterprise buyers from mid-market distributors from micro-enterprises. Cost-down pressure on hybrid deployments accelerates because Thai financial institutions demand data sovereignty compliance without cloud economics. Micro-enterprises exhibit highest price sensitivity, while conglomerates prioritize integration depth over unit cost.
Supply Chain Analysis
XML/UBL expertise supply rests on Indonesian and Vietnamese system integrators with scarce structured-data certification, supplemented by Singapore-based regional consultancies and Indian offshore development centers. Critical inputs include PEPPOL access point licenses, tax authority API credentials, and localized accounting software connectors. Single-source vulnerability concentrates in national tax gateway integrations where authority-approved vendor lists create bottleneck risk. Distribution runs through direct enterprise sales teams for large deployments, with channel partners and accounting firm alliances reaching SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's e-Faktur real-time clearance mandate transforms compliance infrastructure into a barrier-to-entry moat, favoring vendors with pre-certified tax authority integrations and punishing late entrants lacking validation engine deployment experience.
For Market Incumbents: Extend PEPPOL network connectivity into Philippine and Malaysian markets before pending tax digitization legislation hardens competitive positions. Acquire XML/UBL implementation specialists in Vietnam to capture scarce technical capacity. SAP SE and Basware Corporation anchor defensible positions through Directorate General of Taxes pre-certification that emerging cloud-native competitors cannot replicate without multi-quarter validation cycles.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in Indonesian mid-market distributor segments enables disruptive SaaS-only positioning without hybrid deployment overhead. Target Vietnamese SME threshold reductions pulling hundreds of thousands of enterprises into first-time compliance scope. Embed compliance logic directly into e-commerce platform transaction systems rather than competing for retrofitted accounting module replacements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native specialists with proven Indonesian tax authority integrations over legacy ERP extenders facing subscription revenue transition pressure. Monitor Thai Revenue Department quarterly e-Tax framework tightening as inflection indicator for implementation service demand acceleration. Long-term viability hinges on ASEAN-wide protocol convergence positioning rather than single-national mandate capture.
| Strategic Initiative | Industry Significance |
|---|---|
| PEPPOL Gateway Pre-Certification | Directorate General of Taxes validation creates 12-18 month competitive moat for compliant vendors. |
| API-First Platform Integration | Open banking protocol convergence enables embedded finance products for Indonesian e-commerce platforms. |
| Local System Integrator Alliance | Vietnamese XML/UBL expertise scarcity commands premium pricing and extends deployment timelines. |
| Hybrid Cloud Architecture Development | Thai financial institution data sovereignty requirements inflate total cost of ownership versus pure-cloud alternatives. |
| SME Self-Service Portal Launch | Vietnam General Department of Taxation threshold reductions widen addressable base beyond large enterprises. |
Research Methodology
Document review covered national tax authority regulatory filings, PEPPOL interoperability standards documentation, and ASEAN digital economy framework white papers, complemented by interviews with software vendor product managers, system integration firm technical leads, enterprise CFOs managing multi-jurisdiction compliance, and tax authority digital transformation officers. Secondary validation drew from customs data on enterprise software imports, cloud infrastructure capex disclosures, and accounting software vendor SEC filings. Bottom-up deployment volume estimates triangulated against top-down market sizing from regulatory mandate coverage expansion.
Cross-referencing historical compliance deadline acceleration patterns against expert panel inputs on technology adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organizational scale tier, service type attachment, and national regulatory framework cluster. CAGRs derived from elasticity-adjusted mandate threshold descent rates and cloud platform penetration trajectories. Industry-specific forecast inputs incorporated e-Faktur clearance volume growth and e-Tax framework quarterly tightening velocity.
Inputs from Indonesian Directorate General of Taxes and Thai Revenue Department were available through the study window; gaps in Philippine pending legislation timing and Malaysian framework development introduce uncertainty bands around early-stage market entries. Forecasts reflect documented assumptions on interoperability standard convergence and SME threshold reduction schedules. Regulatory deadline delays, PEPPOL variant fragmentation persistence, or legacy ERP replacement cost shocks could revise trajectory. A small set of triggers—ASEAN-wide protocol emergence, open banking standard finalization, and sovereign cloud mandate introduction—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Europe Financial Advisory Services Market
Financial Services
South Korea Financial Services Software Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Credit Rating Software Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Cash Flow Market
Financial Services
Middle East Islamic Finance Market
Financial Services
Investment Trading Software Market
Financial Services
White Glove Services Market
Financial Services
Belgium Gift Card and Incentive Card Market
Financial Services
Contract for Difference Broker Market
Financial Services
ATM Managed Services Market
Financial Services
E-KYC Market
Financial Services
Latin America Factoring Services Market
Financial Services
Australia Online Gambling Market
Financial Services
Global Temporary Labor Market