
 Commodity Services Market | 2026-2036
Commodity Services Market Size, Share, and Industry Trends Forecast 2026-2036
Commodity Services Market Analysis
Cloud-based trade-execution platforms is rewriting how commodity services are delivered, replacing phone-based brokerage with algorithmic routing and real-time position tracking. Glencore leverages its vertically integrated mining-logistics network to sustain margin capture across copper and cobalt chains. Cargill anchors its competitive position through proprietary grain-origination software that connects Brazilian farms to Asian millers directly. Koch Industries competes by controlling midstream energy infrastructure that feeds its commodity-management desk with physical-flow data.
Commodity services encompass the ancillary functions—consulting, logistics, management, and trading—that enable the physical and financial exchange of raw materials, typically executed through contracts denominated in standardized lots with delivery terms governed by exchange rules or bilateral master agreements. These services reduce counterparty risk, optimize working-capital cycles, and match producers with end-users across dislocated geographies. Logistics services dominate current revenue pools because bulk-shipping coordination and storage-terminal access command persistent premiums in tight freight markets. Trading services represent the fastest-expanding segment as algorithmic execution and exchange-traded fund hedging draw institutional capital into commodity beta. Agricultural commodity services remain mature, with thin margins concentrated among incumbents who own origination assets.
The US Commodity Futures Trading Commission and the UK Financial Conduct Authority enforce position-limit and reporting rules that shape how trading desks construct exposure. EPA tailpipe standards and the EU Green Deal's carbon-border adjustment mechanism redirect energy and metals flows toward lower-carbon supply routes, altering logistics demand. ISO 14001 environmental management certifications increasingly gate access to European and North American offtake contracts. Stakeholders must monitor which regulatory jurisdictions adopt mutual recognition frameworks versus unilateral standards, as this divergence determines where service providers must maintain duplicate compliance infrastructure.
Market Dynamics
Algorithmic trade-execution platforms are compressing brokerage margins while forcing incumbent service providers to rebuild their technology stacks around real-time position tracking and API-native infrastructure.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Commodity traders must restructure supply-chain compliance to maintain European market access, creating demand for integrated carbon-accounting and logistics-verification services.
- Brazilian agricultural belt concentration:Soybean and iron-ore flows require bundled port-to-port service packages, pulling third-party logistics providers into long-term origination contracts.
- Cloud-native execution infrastructure:Phone-based brokerage is yielding to algorithmic routing systems that institutional capital now demands for commodity beta exposure.
Market Restraints
- Freight-market volatility:Bulk-shipping coordination and storage-terminal access command persistent premiums that squeeze service-provider margins when charter rates spike.
- Latin American mining logistics concentration:Third-party providers face counterparty risk from single-source dependence on Chilean and Peruvian copper corridor infrastructure.
- ISO 14001 certification gating:European and North American offtake contracts increasingly require environmental management credentials that smaller service providers cannot obtain quickly.
Strategic Opportunities
- US Inflation Reduction Act mineral sourcing incentives:Battery-metals traders can capture new compliance-service revenue by certifying domestic-content thresholds for electric-vehicle supply chains.
- India's agricultural commodity digitization:Proprietary grain-origination software platforms have room to connect domestic farms directly to Asian millers, bypassing traditional brokerage layers.
- API-to-API data convergence:Physical-flow telemetry from midstream energy infrastructure is hybridizing with financial risk-management systems to create real-time hedging products.
Industry Challenges
- Quantitative trading talent scarcity:Commodity-services firms struggle to hire algorithmic execution engineers who understand both derivatives pricing and physical-delivery mechanics.
- Legacy system integration friction:Phone-based brokerage desks must rebuild order-routing infrastructure without disrupting active client positions during migration windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commodity Services Market |
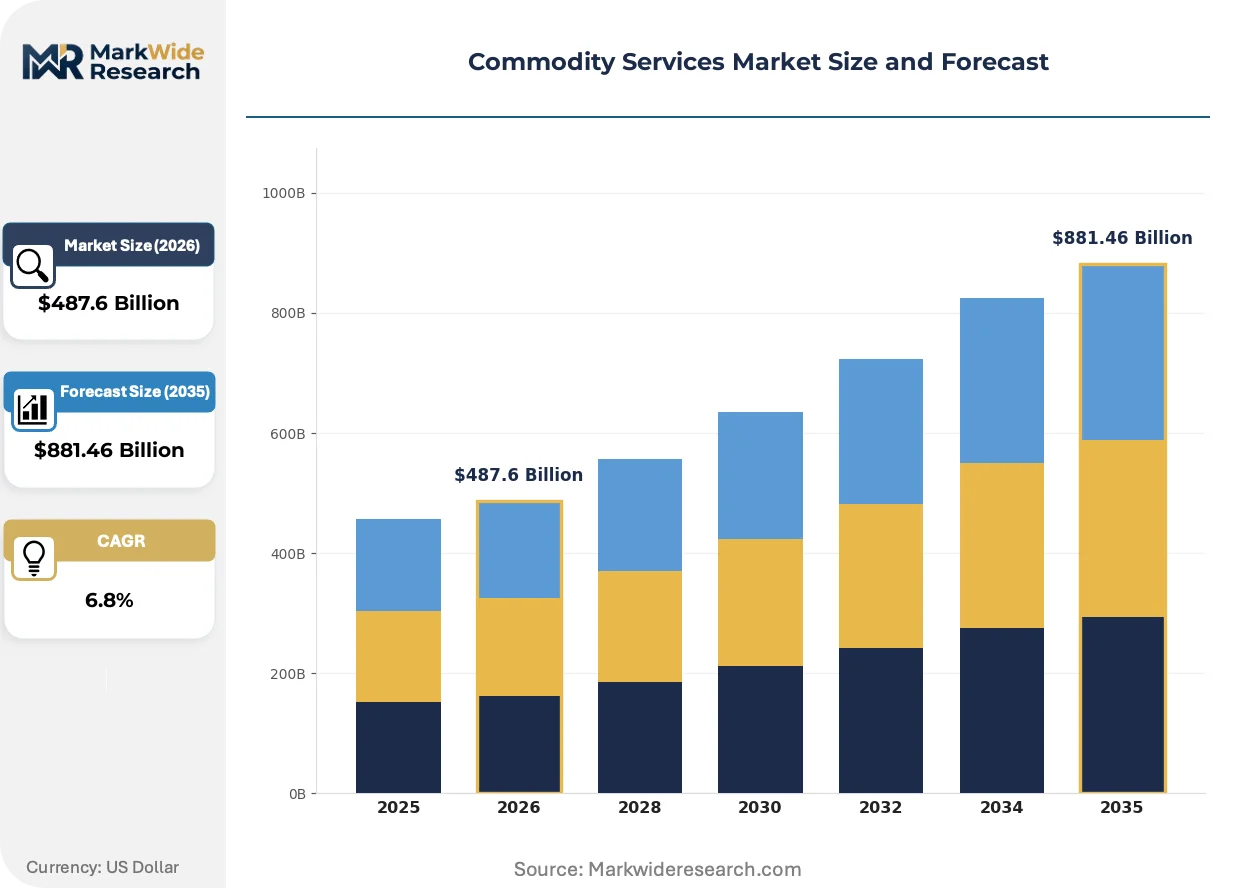
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $881.46 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Logistics, Management, Trading Commodity Type: Metals, Energy, Agriculture, Soft Commodities Delivery Model: Online, Offline, Hybrid, Regional Customer Segment: Producers, Investors, Traders, Retailers |
| Companies Covered | Vitol, Glencore, Cargill, Koch Industries, Noble Group, Louis Dreyfus, Bunge, Olam, BP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commodity Services Market Emerging Trajectories
Digital infrastructure is rewriting how commodity risk is priced and transferred, compressing the latency between physical-flow detection and financial-position adjustment while fragmenting traditional brokerage hierarchies.
Blockchain-enabled trade documentation is hybridizing paper-based letter-of-credit processes with smart-contract settlement, reducing documentary fraud exposure in bulk-cargo transactions. Agricultural exporters in Argentina and wheat traders in the Black Sea corridor are piloting these systems to accelerate working-capital cycles. The structural consequence is a compression of trade-finance margins as banks disintermediate from documentary verification.
REACH chemical-registration requirements and the EU Green Deal's carbon-border adjustment mechanism are redirecting metals and energy flows toward lower-carbon supply routes. Commodity traders now must maintain duplicate compliance infrastructure for mutual-recognition frameworks versus unilateral standards. Battery-metals shipments into Rotterdam and Antwerp face the most stringent documentation requirements, forcing logistics providers to build emissions-verification capabilities.
Buyers are unbundling after-sales risk-management advisory from execution services, contracting directly with technology platforms for position monitoring while retaining separate relationships for physical logistics. This pattern is most visible among Asian millers sourcing Brazilian soybeans, who now demand API access to origin-tracking data rather than broker-mediated updates. The shift compresses revenue per transaction for traditional full-service providers.
Commodity Services Market Segmentation
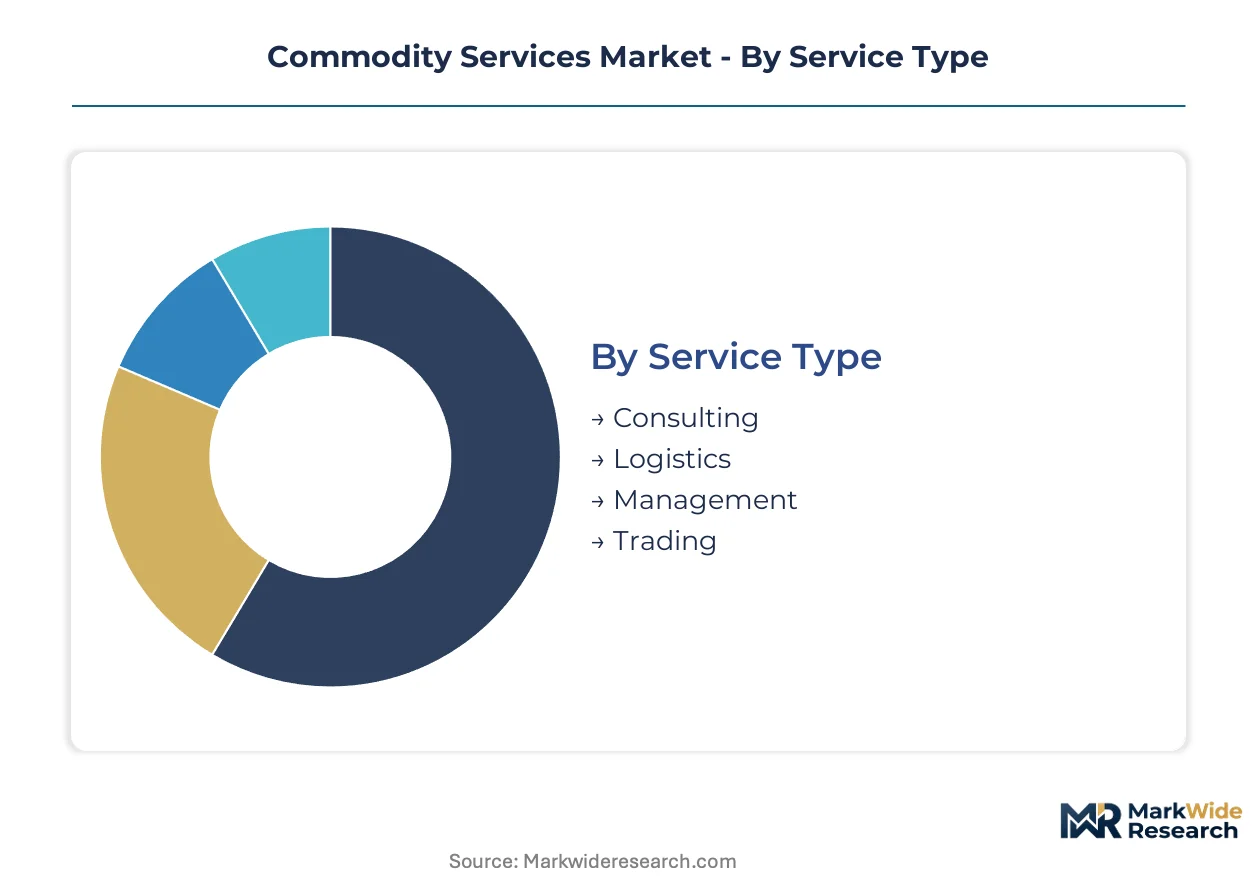
Commodity services fragment across service archetypes, physical asset classes, and customer risk profiles. Each segmentation axis reveals distinct margin structures and technology adoption curves that determine competitive positioning.
Service Type:
Mature brokerage functions coexist with emerging algorithmic infrastructure, creating divergent investment requirements across the service spectrum.
- Consulting:Advisory services span supply-chain optimization, carbon-accounting compliance, and counterparty risk assessment. European traders facing EU Green Deal carbon-border adjustments drive sustained demand for regulatory navigation expertise.
- Logistics:Coordination of bulk-shipping charters, storage-terminal access, and port-to-port routing commands persistent premiums in tight freight markets. Brazilian soybean and iron-ore flows require integrated service bundles that lock providers into long-term origination contracts.
- Management:Portfolio construction and position-monitoring services unbundle from execution as Asian millers demand direct API access to origin-tracking data rather than broker-mediated updates.
- Trading:Algorithmic routing systems displace phone-based brokerage as institutional capital demands real-time position tracking for commodity beta exposure.
Logistics handles the majority of throughput; trading is the fastest mover on share.
Commodity Type:
Margin concentration varies sharply by underlying asset volatility and regulatory scrutiny intensity.
- Metals:Copper and cobalt chains require vertically integrated mining-logistics networks to sustain margin capture. Battery-metals shipments into Rotterdam face stringent emissions-verification requirements under EU Green Deal frameworks.
- Energy:Midstream infrastructure control feeds commodity-management desks with physical-flow telemetry. EPA tailpipe standards redirect flows toward lower-carbon supply routes, altering logistics demand patterns.
- Agriculture:Grain-origination software connects Brazilian farms directly to Asian millers, compressing traditional brokerage margins. Argentine exporters pilot blockchain-enabled trade documentation to accelerate working-capital cycles.
- Soft Commodities:Coffee and cocoa trading retains higher-touch service requirements due to fragmented origin infrastructure and quality-verification complexity.
Metals commands the highest service fees per transaction; agriculture is expanding most quickly on volume.
Delivery Model:
Technology stack investments separate scalable platforms from relationship-dependent intermediaries.
- Online:Cloud-native execution platforms enable algorithmic routing with API-native infrastructure. Institutional investors now mandate digital position monitoring as a baseline requirement.
- Offline:Phone-based brokerage persists in illiquid commodity corridors where counterparty trust outweighs execution speed. Latin American mining logistics retain significant voice-trading volume.
- Hybrid:Combined digital-physical service bundles dominate Brazilian agricultural belt flows, requiring providers to maintain both software development and terminal operations capabilities.
- Regional:Localized compliance infrastructure addresses divergent mutual-recognition frameworks versus unilateral standards across jurisdictions.
Hybrid models capture the largest contract values; online platforms are gaining share fastest.
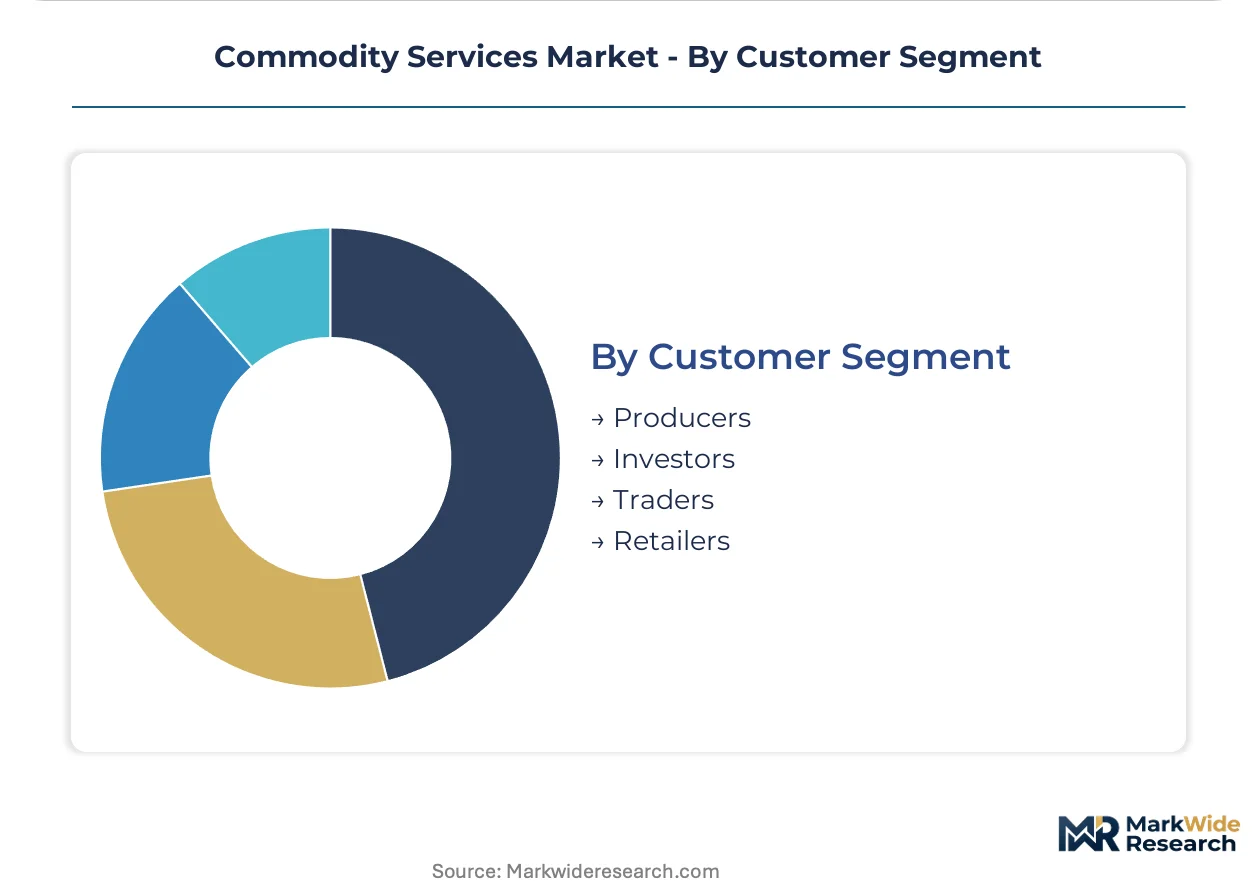
Customer Segment:
Procurement sophistication determines service bundling preferences and price elasticity.
- Producers:Mining and agricultural originators seek long-term logistics contracts that guarantee offtake capacity. ISO 14001 certification requirements increasingly gate access to European and North American contracts.
- Investors:Institutional capital demands exchange-traded fund hedging and algorithmic execution for commodity beta exposure. Position-limit rules enforced by the US Commodity Futures Trading Commission shape portfolio construction.
- Traders:Merchants require real-time physical-flow telemetry hybridized with financial risk-management systems to construct real-time hedging products.
- Retailers:End-user procurement desks unbundle risk-management advisory from execution, contracting directly with technology platforms for position monitoring.
Traders generate the highest transaction frequency; investors are climbing the fastest on fee contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redrawing service demand geography. Countries with concentrated commodity production increasingly import logistics and risk-management capabilities from specialized providers abroad.
United States
The US Inflation Reduction Act mineral sourcing incentives are drawing battery-metals traders into compliance-service revenue streams. EPA tailpipe standards redirect energy flows toward lower-carbon supply routes. Houston and the Gulf Coast corridor anchor midstream energy infrastructure that feeds commodity-management desks with physical-flow telemetry.
Brazil
Soybean and iron-ore flows through the agricultural belt require bundled port-to-port service packages that lock providers into long-term origination contracts. The national agricultural regulator enforces grain-origination documentation standards that favor digitized service platforms. São Paulo and the Santos port cluster concentrate third-party logistics expansion as mining companies outsource risk-management functions.
Germany
REACH chemical-registration requirements and EU Green Deal carbon-border adjustments redirect metals and energy flows toward lower-carbon supply routes. The ECHA enforcement framework shapes how traders construct exposure to European offtake markets. The Rhine-Ruhr industrial corridor and Hamburg port complex host emissions-verification capabilities for battery-metals shipments facing stringent documentation requirements.
China
Dual carbon goals and GB standards are forcing commodity traders to restructure supply-chain compliance for domestic market access. SAMR position-limit rules shape how trading desks construct exposure. The Yangtze River Delta and Pearl River Delta concentrate algorithmic execution infrastructure as institutional capital demands real-time position tracking.
India
Agricultural commodity digitization is creating openings for proprietary grain-origination software platforms to connect domestic farms directly to Asian millers. SEBI and RBI regulations govern commodity derivatives trading and cross-border payment flows. Maharashtra and Gujarat host pilot programs for blockchain-enabled trade documentation that accelerates working-capital cycles for wheat and rice exporters.
Commodity Services Market Vendor Landscape
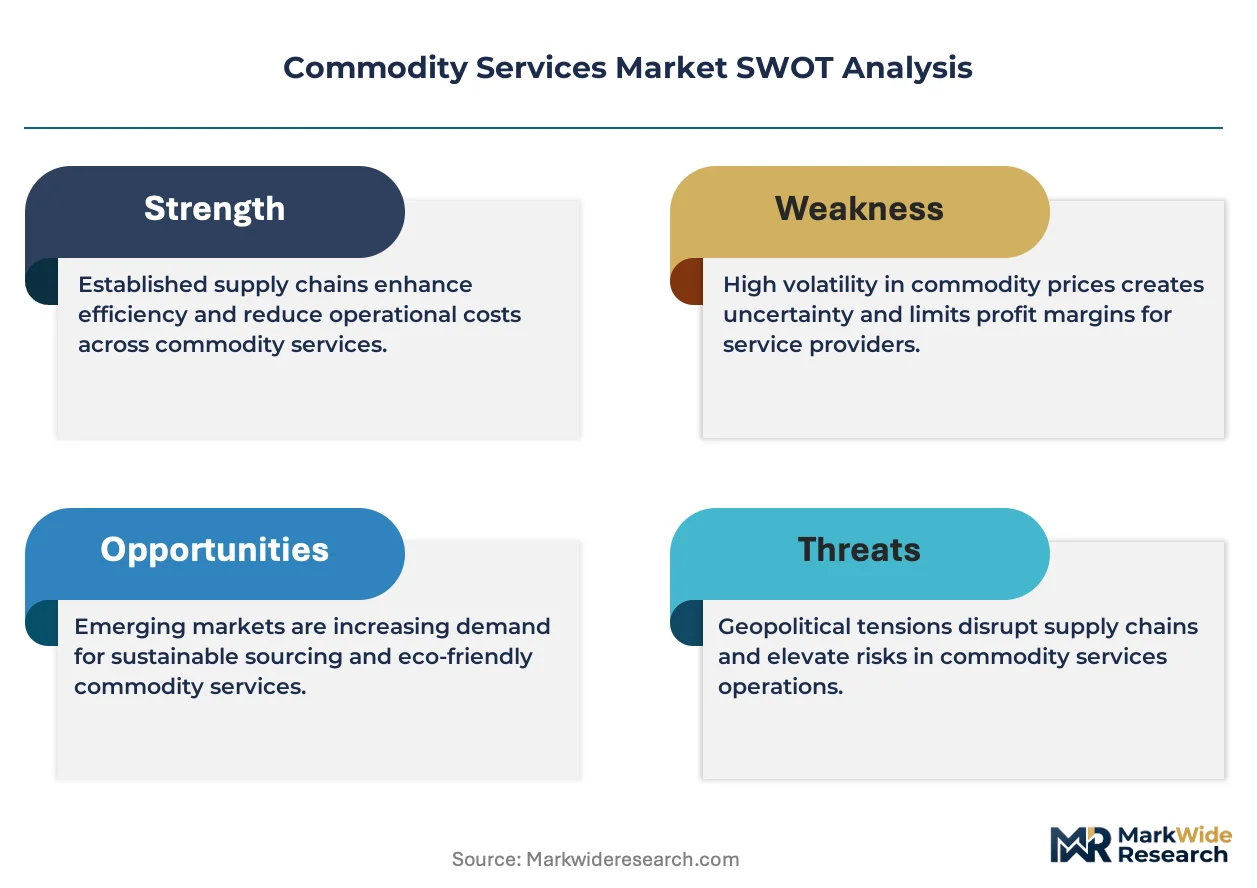
On the supply side, the industry is consolidating around vertically integrated trading houses with captive logistics networks. Tier-one players command origination assets and terminal access that smaller providers cannot replicate. Three strategic archetypes dominate: asset-heavy integrated traders, technology-enabled execution platforms, and regional specialists with local regulatory expertise. Competitive moves center on M&A to secure midstream infrastructure and strategic partnerships to build API-native execution stacks.
Within the integrated trading tier, Glencore, Cargill, and Vitol exemplify divergent approaches to margin capture. Glencore represents the mining-logistics integration model with vertically controlled copper and cobalt chains. Cargill anchors the agricultural origination archetype through proprietary software connecting Brazilian production to Asian demand. Vitol occupies the energy-specialist position, leveraging midstream infrastructure control to feed risk-management systems with real-time flow data.
| Leading Market Players |
|---|
| Vitol |
| Glencore |
| Cargill |
| Koch Industries |
| Noble Group |
| Louis Dreyfus |
| Bunge |
| Olam |
| BP |
| Others |
Supply Flow & Price Mechanics
Brazilian mining-logistics corridors concentrate upstream capacity for iron-ore and soybean flows, anchoring margin capture in port-to-port service bundles and long-term origination contracts. This geographic chokepoint shapes downstream pricing power for third-party providers who control terminal access and storage capacity.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing, with three-tier pricing structure across premium, standard, and economy levels differentiated by ISO 14001 certification status and volume scale. Price differentiation stems from carbon-accounting compliance depth and API-native execution capabilities. Cost compression in standard-tier logistics services is intensifying because freight-market volatility squeezes margins when charter rates spike. Retail procurement desks show highest price sensitivity, while institutional investors absorbing commodity beta exposure demonstrate lowest elasticity.
Supply Chain Analysis
Supply-chain finance facilities extended by integrated trading houses to Brazilian and Chilean mining operators reduce working-capital friction but concentrate counterparty exposure. Raw material flows draw from Australian iron-ore, Chilean copper concentrate, and Argentine soybean inputs. Single-source vulnerability runs through the Santos-Antwerp shipping lane for battery-metals shipments facing EU Green Deal emissions-verification requirements. Distribution runs through hybrid digital-physical service bundles that combine cloud-native execution platforms with captive terminal operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithmic trade-execution platforms are disrupting established brokerage hierarchies, with cloud-native infrastructure and real-time position tracking creating decisive competitive separation. EU Green Deal carbon-border adjustments accelerate this inflection by mandating integrated compliance services that legacy phone-based systems cannot deliver.
For Market Incumbents: Insulate origination assets through backward integration into Brazilian agricultural belt infrastructure and Chilean copper corridor terminal capacity. Secure ISO 14001 certification across all European-facing operations before regulatory gating tightens. Deepen API-native technology stacks to defend against execution-platform entrants targeting institutional commodity beta demand. For New Entrants and Emerging Players: Establish a beachhead in India's agricultural commodity digitization, where proprietary grain-origination software platforms can bypass traditional brokerage layers. Target blockchain-enabled trade documentation for Argentine wheat and Black Sea corridor exporters seeking accelerated working-capital cycles. Lead with supply-chain finance facilities to secure origination relationships before building execution capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive logistics networks in battery-metals corridors. Long-term viability across the analysis window hinges on emissions-verification capabilities and API-to-API data convergence. Watch for inflection when institutional capital mandates fully displace phone-based brokerage for commodity beta exposure.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Execution Platform Buildout | Algorithmic routing displaces phone-based brokerage as CFTC position-limit rules reshape portfolio construction. |
| Carbon-Accounting Compliance Service Launch | EU Green Deal documentation requirements create new revenue pools for verified emissions-tracking capabilities. |
| Backward Integration into Port Terminals | Santos and Rotterdam terminal control secures margin capture in tight bulk-shipping charter markets. |
| Blockchain Trade Documentation Pilot | Smart-contract settlement accelerates working-capital cycles for Argentine and Black Sea agricultural exporters. |
| Strategic Partnership with Cloud Infrastructure Provider | Real-time position tracking hybridizes physical-flow telemetry with financial risk-management systems. |
Methodological Framework
A spread of perspectives from commodity trading desk heads, logistics terminal operators, regulatory compliance officers, and institutional portfolio managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against customs trade data, SEC filings from integrated trading houses, ECHA enforcement frameworks, and FERC infrastructure disclosures. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates across the projection horizon.
Demand-supply balance modeling anchored the analytical framework, with segmentation across service type, commodity class, delivery model, and customer sophistication shaping volume trajectories. CAGRs were derived from growth-rate convergence analysis applied to logistics throughput, trading velocity, and compliance-service adoption curves. Freight-market volatility indices and carbon-border adjustment implementation timelines served as industry-specific forecast inputs throughout the modeling period.
Stress conditions across charter rate spikes, regulatory recognition framework divergence, and algorithmic execution talent scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about EU Green Deal enforcement intensity and cloud-platform migration timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Power Bank Sharing Services Market
Financial Services
North America Financial Advisory Services Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Global Trust and Corporate Service Market
Financial Services
Hyperinflation System Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
BFSI A2P SMS Market
Financial Services
Europe B2B Legal Services Market
Financial Services
ATM Managed Services Market
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Reconciliation Software Market
Financial Services
Currency Exchange Software Market
Financial Services
Check Cashing Services Market
Financial Services
US Online Trading Platform Market
Financial Services
Financial Services Application Market
Financial Services
Global Financial Consulting Software Market