
 Dual Interface Payment Card Market | 2026-2036
Dual Interface Payment Card Market Size, Share, and Industry Trends Forecast 2026-2036
Dual Interface Payment Card Market Intelligence
Southeast Asia is narrowing the gap between legacy magnetic stripe infrastructure and full contactless deployment. Giesecke+Devrient GmbH leverages its regional manufacturing footprint to serve central banks migrating to EMV standards. Infineon Technologies AG anchors supply for secure element chips that power dual-interface authentication. Thales Group competes on certification breadth, sustaining contracts with transit authorities requiring multi-application card platforms.
A dual interface payment card embeds both contact chip and contactless antenna circuitry within ISO/IEC 7816 and 14443 compliant substrates, enabling physical insertion or tap-to-pay authentication through a single device. The card's primary commercial purpose is to bridge legacy point-of-sale terminals and modern NFC readers while maintaining cryptographic security across both protocols. Contactless cards lead product type demand in urban retail corridors where transaction speed governs merchant preference, while secure elements technology captures margin concentration due to semiconductor scarcity and certification barriers. EMV compliance requirements continue to displace magnetic stripe cards in banking applications, though RFID variants retain niche utility in closed-loop transit and campus environments.
The European Central Bank's TARGET Instant Payment Settlement framework, the US Federal Reserve's FedNow service guidelines, and India's RBI tokenization mandates collectively pressure issuers toward interoperable dual-interface architectures. PCI DSS certification and country-specific central bank directives shape product roadmaps by dictating encryption standards and domestic data-residency requirements. Stakeholders must monitor which regulatory bodies move first on quantum-resistant cryptography standards, as this timing will force card replacement cycles and reshape foundry partnerships.
Market Dynamics
The migration from magnetic stripe to EMV contactless infrastructure is compressing replacement cycles and forcing foundry capacity reallocation toward secure element substrates. Banking issuers now face simultaneous mandates for tokenization compliance and NFC transit integration, creating procurement urgency that favors dual-interface architectures over single-protocol alternatives.
Growth Catalysts
- EMV Migration Mandates:India's RBI and Southeast Asian central banks have issued deadlines for chip-card compliance, forcing banking institutions to accelerate dual-interface issuance timelines.
- Transit Authority Convergence:Urban transit systems in Singapore, Bangkok, and Jakarta are adopting open-loop payment acceptance, requiring multi-application card platforms that bridge fare collection and retail banking.
- Semiconductor Security Upgrades:Foundry investments in 40nm and 28nm secure element processes are enabling higher cryptographic throughput for biometric-integrated card designs.
Market Restraints
- Substrate Cost Volatility:Polyvinyl chloride and polycarbonate resin prices fluctuate with petrochemical feedstock markets, compressing card manufacturer margins on high-volume contracts.
- Foundry Concentration Risk:Secure element wafer fabrication concentrates among three European and East Asian semiconductor houses, creating supply vulnerability during capacity crunches.
- Legacy Terminal Compatibility:Magnetic stripe acceptance persists in rural merchant networks, forcing issuers to maintain triple-interface support and delaying full contactless transition.
Strategic Opportunities
- Biometric Card Convergence:Fingerprint sensor integration with dual-interface antennas creates premium product tiers for high-net-worth banking segments in the UAE and Saudi Arabia.
- Tokenization Infrastructure:India's NPCI tokenization mandate and similar frameworks in Indonesia open white space for domestic secure element personalization facilities.
- Closed-Loop Campus Expansion:University and corporate campus card programs in Malaysia and the Philippines represent underpenetrated demand for multi-application dual-interface platforms.
Industry Challenges
- Certification Timeline Compression:EMVCo and PCI DSS validation queues extend 14-18 months, delaying product launches for issuers racing regulatory deadlines.
- Antenna Design Talent Scarcity:RF engineering expertise for 13.56 MHz inlay optimization concentrates among a narrow pool of specialists in Germany and Taiwan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dual Interface Payment Card Market |
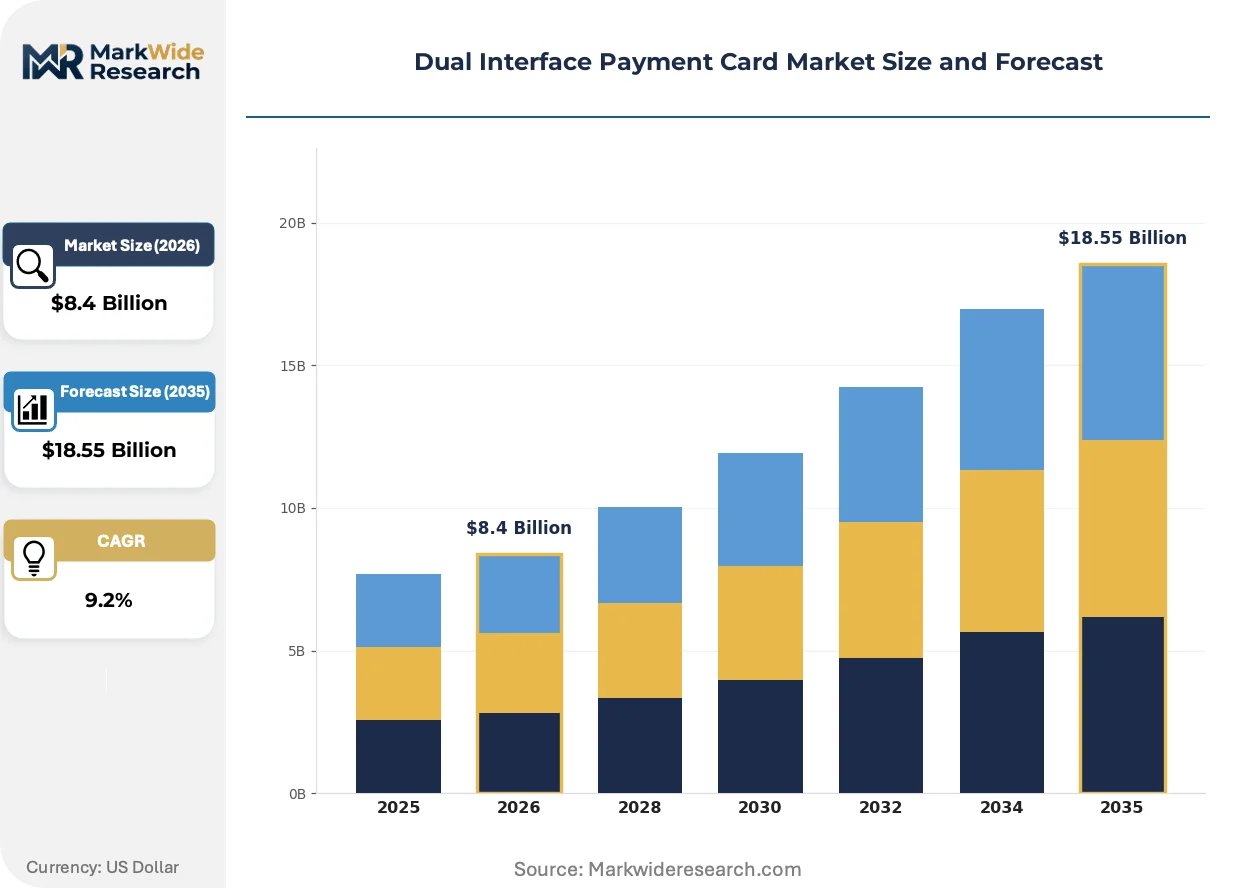
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contactless Cards, Chip Cards, Magnetic Stripe Cards, Smart Cards Technology: Near Field Communication, EMV, RFID, Secure Elements End User: Retail, Banking, Telecom, Transportation Application: Mobile Payments, Online Transactions, Ticketing, Loyalty Programs |
| Companies Covered | Giesecke+Devrient GmbH, Infineon Technologies AG, Thales Group, Goldpac, NXP Semiconductors, CPI Card Group Inc., IDEMIA, Paragon Group Limited, Eastcompeace Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dual Interface Payment Card Market Strategic Shifts & Innovations
Three intersecting forces are reconfiguring how dual-interface cards are engineered, certified, and deployed. Technology convergence between biometric authentication and contactless protocols is creating new product categories, while regulatory pressure on data residency is fragmenting supply chain geography.
Dynamic CVV display technology is digitizing card-not-present security by replacing static printed codes with battery-powered e-ink or LCD modules that refresh authentication tokens at intervals. Premium banking segments in Singapore and Hong Kong are piloting these cards for e-commerce fraud reduction. The technology is digitizing issuer value propositions by shifting competitive differentiation from plastic design to active security features.
India's RBI tokenization mandate and the EU's Digital Operational Resilience Act are forcing card manufacturers to regionalize data processing infrastructure. Domestic personalization facilities must now achieve certification for local token vault management rather than relying on centralized European or North American hubs. Banking issuers in India and Germany are responding by qualifying second-source personalization partners within national borders.
Merchant acquiring patterns are consolidating around integrated POS terminal providers that bundle hardware, software, and payment acceptance. Small and mid-size retailers in Indonesia and Vietnam now procure contactless-enabled terminals through banking partnerships rather than independent distributors. This channel compression is most visible in urban retail corridors where transaction speed governs merchant preference for tap-to-pay over chip-insert protocols.
Dual Interface Payment Card Market Segmentation
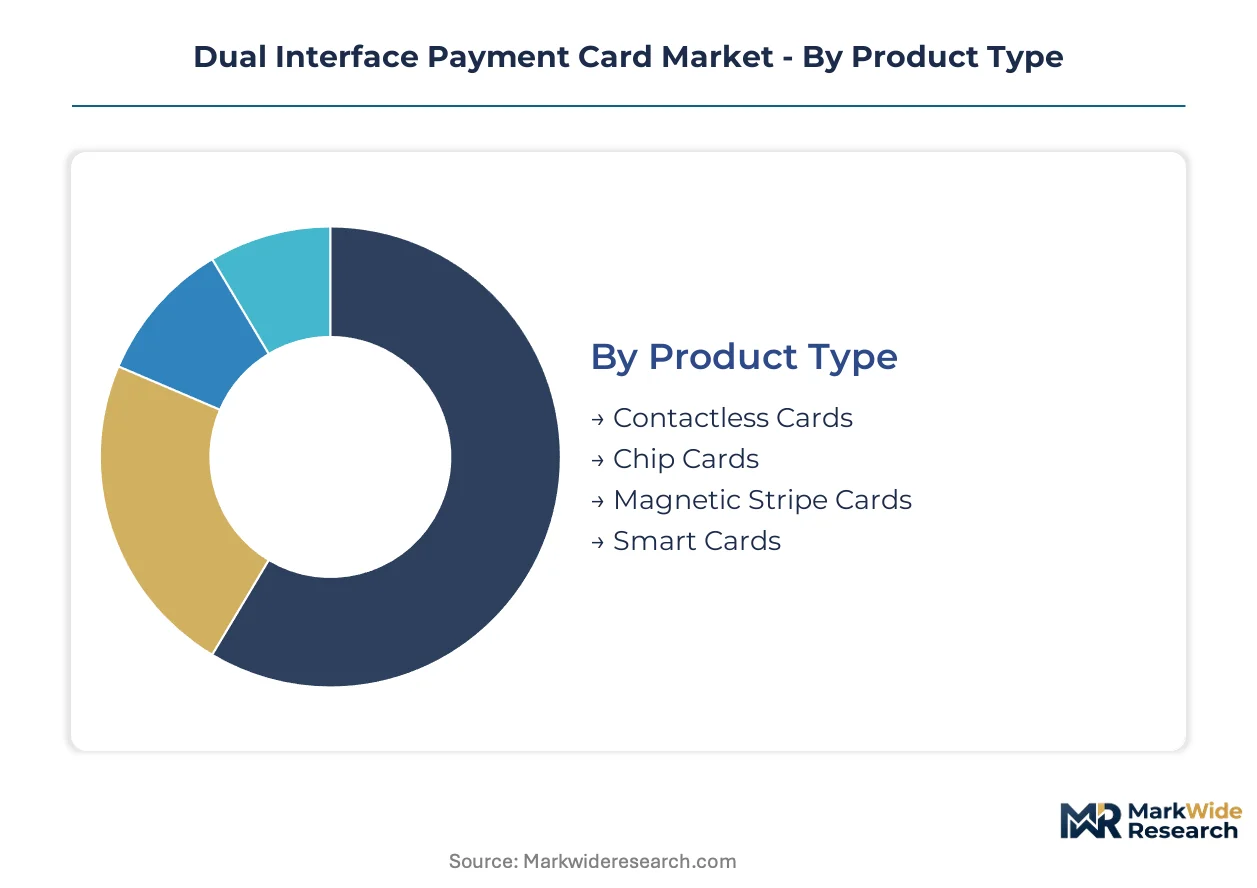
Dual-interface payment cards demand granular segmentation because procurement specifications diverge sharply across issuer types. Banking institutions prioritize EMV compliance and secure element certification, while transit authorities optimize for antenna durability and transaction speed under environmental stress.
Product Type:
After-sales service intensity varies dramatically across card substrates, with contactless-enabled products requiring antenna recalibration support and magnetic stripe legacy formats demanding minimal ongoing technical intervention.
- Contactless Cards:These substrates embed 13.56 MHz copper coil antennas between polycarbonate or PVC layers, enabling tap-to-pay authentication at point-of-sale terminals. Demand concentrates in Singapore and Bangkok urban retail corridors where merchant preference for transaction speed drives banking procurement. Antenna durability under flex stress creates warranty exposure that elevates service costs for high-volume issuers.
- Chip Cards:ISO/IEC 7816-compliant modules with physical contact pads dominate India's RBI-mandated EMV migration, where domestic personalization facilities now manage token vault infrastructure. The substrate requires insertion-style terminal compatibility, extending utility in rural merchant networks where contactless reader penetration remains incomplete.
- Magnetic Stripe Cards:Legacy iron oxide tape substrates persist in closed-loop campus environments and transitional markets.
- Smart Cards:Multi-application platforms with dual-interface capability serve transit-banking convergence projects in Jakarta and Kuala Lumpur.
Contactless cards hold the largest share; momentum sits with smart cards bridging retail and transit applications.
Technology:
Cost tier stratification separates premium secure element implementations from commodity RFID alternatives, with certification barriers creating margin concentration at the high end.
- Near Field Communication:13.56 MHz radio frequency protocols enable peer-to-peer data exchange and card emulation for mobile wallet integration. Transit authorities in Singapore specify NFC for open-loop fare collection, requiring EMVCo certification for payment network interoperability.
- EMV:Europay-Mastercard-Visa cryptographic standards govern chip authentication and dynamic data generation for counterfeit resistance. India's central bank mandates EMV compliance for all new card issuance, compressing procurement timelines for domestic banking institutions.
- RFID:Ultra-high frequency variants serve closed-loop asset tracking and campus access control where payment network interoperability is unnecessary.
- Secure Elements:Tamper-resistant semiconductor substrates host cryptographic keys and biometric templates, capturing premium pricing in UAE high-net-worth banking segments.
EMV technology holds the largest share; secure elements are expanding most quickly as biometric integration accelerates.
End User:
Volume concentration patterns reveal banking as the dominant procurement channel, though transportation authorities are emerging as technical specification leaders for multi-application platforms.
- Banking:Commercial and retail banking institutions issue dual-interface cards as primary customer touchpoints for deposit and credit products. India's NPCI-driven infrastructure buildout has created the world's largest chip-card deployment, with domestic foundry partnerships securing supply continuity.
- Retail:Merchant acquirers and retail chains deploy private-label card programs for loyalty integration and closed-loop payment acceptance.
- Telecom:Mobile network operators embed payment functionality in SIM-based secure elements for emerging market financial inclusion.
- Transportation:Urban transit authorities in Bangkok and Jakarta specify dual-interface architectures for open-loop fare collection bridging retail banking networks.
Banking holds the largest share; transportation is gaining share fastest as transit-banking convergence accelerates.
Application:
Customer type differentiation separates high-frequency low-value ticketing use cases from high-value authenticated online transactions, with loyalty programs occupying a hybrid position on data analytics value.
- Mobile Payments:Host card emulation and secure element-based tokenization enable smartphone-initiated transactions at NFC terminals. Singapore and Hong Kong banking segments pilot dynamic CVV display cards for e-commerce fraud reduction, integrating battery-powered e-ink modules with dual-interface substrates.
- Online Transactions:Card-not-present authentication relies on token vault infrastructure and 3D Secure protocols, with India's RBI mandate forcing domestic data residency for personalization facilities.
- Ticketing:Transit fare collection demands millisecond transaction speeds and environmental durability for daily commuter volume.
- Loyalty Programs:Multi-application cards integrate payment rails with points accumulation and redemption across merchant networks.
Mobile payments hold the largest share; ticketing shows the steepest expansion trajectory as urban transit systems modernize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mumbai Metro's open-loop payment integration anchors India's dominance in dual-interface card deployment. Singapore's Mass Rapid Transit network drives Southeast Asian transit-banking convergence. The Dubai Metro's NFC fare collection infrastructure supports premium biometric card pilots across the Gulf.
India
Domestic banking institutions issue dual-interface cards at scale following the National Payments Corporation of India's infrastructure mandates. The RBI's tokenization compliance deadlines compress procurement timelines for chip-card migration. Mumbai and Bangalore host personalization facilities managing local secure element vault infrastructure.
Singapore
Urban transit authorities specify multi-application card platforms bridging fare collection and retail banking networks. The Monetary Authority of Singapore's payment system oversight framework mandates interoperability standards for contactless acceptance. The Marina Bay financial district concentrates pilot programs for dynamic CVV display technology integration.
Germany
Central bank EMV migration timelines drive secure element demand from European banking consortiums. The Bundesbank's oversight of payment system stability influences cryptographic certification requirements. Frankfurt's financial technology cluster anchors foundry partnerships for quantum-resistant cryptography research.
United States
FedNow service guidelines pressure issuers toward interoperable dual-interface architectures for instant settlement compatibility. The Federal Reserve's payment system oversight shapes encryption standards for domestic card networks. New York and Chicago financial centers concentrate merchant acquiring consolidation around integrated POS terminal providers.
United Arab Emirates
High-net-worth banking segments pilot biometric-integrated dual-interface cards for premium customer authentication. The UAE Central Bank's digital payment regulations mandate secure element certification for domestic issuance. Dubai's financial free zones host personalization facilities serving Gulf Cooperation Council markets.
Dual Interface Payment Card Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in secure element and antenna supply. The vendor base stratifies across three tiers: multinational technology conglomerates with certification breadth, regional card manufacturers with domestic personalization scale, and semiconductor foundries with cryptographic process expertise. Strategic moves concentrate on foundry capacity reservation and transit authority partnership formation.
Among European-based technology conglomerates, Giesecke+Devrient GmbH and Infineon Technologies AG exemplify the integrated platform archetype. Thales Group occupies a position spanning secure element supply and system integration. These entities represent the certification-heavy tier where EMVCo validation queues create defensive moats.
| Leading Market Players |
|---|
| Giesecke+Devrient GmbH |
| Infineon Technologies AG |
| Thales Group |
| Goldpac |
| NXP Semiconductors |
| CPI Card Group Inc. |
| IDEMIA |
| Paragon Group Limited |
| Eastcompeace Technology Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Secure element wafer fabrication concentrates in Germany, Taiwan, and South Korea, anchoring margin pools at the semiconductor tier while card manufacturers absorb substrate cost volatility downstream. This upstream concentration forces banking issuers into long-term foundry contracts that lock in pricing tiers before polycarbonate resin fluctuations hit converter margins.
Pricing Analysis
EMVCo certification dictates the pricing tier structure across the dual-interface card market, separating premium secure element implementations from commodity RFID alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with biometric-integrated designs commanding the highest tier. Price differentiation stems from antenna design complexity and domestic personalization facility qualification. Cost compression in standard-tier EMV cards is intensifying because polycarbonate resin prices fluctuate with petrochemical feedstock markets. Small regional banking issuers exhibit the highest price sensitivity, while Gulf high-net-worth segments prioritize security features over unit cost.
Supply Chain Analysis
Foundry partnerships with Infineon Technologies AG, NXP Semiconductors, and East Asian semiconductor houses hold the majority of secure element capacity. Manufacturing concentrates in Germany, Taiwan, and South Korea for cryptographic chip fabrication, while card lamination and personalization spreads across India, Singapore, and the UAE. Raw material dependencies include polyvinyl chloride resin, polycarbonate substrates, and copper coil antenna stock. Single-source vulnerability concentrates in 40nm and 28nm secure element wafer production, where only three facilities qualify for EMVCo certification. Distribution runs through banking procurement channels and transit authority tender processes rather than independent retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone-based host card emulation and digital wallet proliferation threaten physical card substitution, forcing incumbents to defend issuance volume through security differentiation and transit integration lock-in.
For Market Incumbents: Insulate core banking relationships by reserving foundry capacity for secure element substrates and accelerating biometric card certification timelines. Deepen antenna design capabilities through targeted hiring in Germany and Taiwan to offset RF engineering talent scarcity. Prioritize transit authority partnerships in Jakarta and Bangkok that create multi-application platform switching costs against mobile wallet displacement. For New Entrants and Emerging Players: Domestic personalization facilities in Indonesia and the Philippines represent the most penetrable entry point for regional banking issuers seeking alternatives to European hub dependency. Closed-loop campus card programs in Malaysian universities offer technical specification entry with lower certification barriers than EMVCo-mandated banking products. Position through tokenization infrastructure partnerships that align with India's RBI data residency requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed card manufacturers that consolidated during the 2015-2020 EMV migration wave and now face renewal decision points. Long-term viability hinges on quantum-resistant cryptography certification timing and biometric integration capability buildout. Monitor India's NPCI infrastructure mandates and EU quantum cryptography standardization as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | Long-term secure element wafer contracts with Infineon and NXP lock in supply continuity for EMV migration deadlines. |
| Transit Authority Partnership Formation | Open-loop fare collection contracts in Singapore and Bangkok create multi-application platform revenue streams. |
| Biometric Card Certification Investment | Fingerprint sensor integration with dual-interface antennas opens premium banking segments in UAE and Saudi Arabia. |
| Domestic Personalization Facility Buildout | Local token vault infrastructure in India and Indonesia satisfies RBI and central bank data residency mandates. |
| Quantum-Resistant Cryptography R&D | Early alignment with Bundesbank and ECB standards positions for forced card replacement cycles. |
Research Approach
Initial hypotheses were tested against primary input from banking procurement executives, transit authority technical specification leads, secure element foundry account managers, and EMVCo certification auditors and refined through secondary validation. Primary fieldwork combined structured interviews with card manufacturer operations directors and antenna design specialists. Secondary sources included EMVCo certification databases, central bank payment system reports from RBI and the Monetary Authority of Singapore, and semiconductor foundry capacity disclosures. Bottom-up demand modeling from individual banking issuer procurement timelines triangulated against top-down market sizing from regional central bank card issuance statistics.
Demand-supply balance modeling across the projection horizon anchored volume forecasts to foundry capacity constraints and polycarbonate resin supply elasticity. Segmentation dimensions included product type, technology tier, end-user category, and application use case, with additional modeling of certification queue duration by regional regulatory cluster. CAGRs were derived from regression analysis of historical issuance velocity against EMV migration deadline proximity. Industry-specific inputs incorporated transit authority tender award patterns and domestic personalization facility qualification timelines.
Practitioners should monitor central bank quantum cryptography standardization announcements and secure element foundry capacity allocation shifts for early signals of forecast revision. Forecasts reflect assumptions about EMVCo certification queue stability and petrochemical feedstock price normalization. Quarterly review of RBI tokenization mandate enforcement intensity and Singapore transit open-loop adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Canada POS Terminal Market
Payments
Netherlands POS Terminal Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Argentina Mobile Wallet Market
Payments
Asia-Pacific Digital Remittance Market
Payments
Mexico POS Terminals Market
Payments
Retail Point of Sale (POS) Market
Payments
Mobile Payment Market
Payments
Epayment System Market
Payments
Electronic Payment Processing Software Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Europe Credit Cards Market
Payments
Japan Payment Gateway Market
Payments
Direct Carrier Billing Market
Payments
Digital Transfer Services Market
Payments
Middle East and Africa Payments Market