
 Europe Mobile Payment Market | 2026-2036
Europe Mobile Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Mobile Payment Market Intelligence
Embedded finance bundling is consolidating merchant acquirer relationships across Europe. Adyen N.V. leverages unified platform architecture to sustain cross-border transaction dominance. Worldline SA anchors European acquiring scale through banking partnerships. Klarna Bank AB differentiates via buy-now-pay-later integration at Nordic retail checkouts.
Europe mobile payment denotes proximity and remote transaction execution via smartphone-enabled instruments using NFC chips, tokenized credentials, or QR-encoded instructions, routing funds through licensed payment institutions to settle purchases without physical card presentation. Digital wallet penetration leads transaction volume as consumers shift credentials from plastic to device-native storage, while NFC technology captures in-store margin pools due to interchange efficiency and sub-500 millisecond latency requirements. P2P payments represent the fastest-growing transaction type as open banking APIs reduce settlement friction between individuals.
PSD2 strong customer authentication mandates from the European Banking Authority shape product roadmaps, requiring two-factor verification for transactions exceeding thresholds. GDPR and the EU AI Act constrain how payment providers deploy behavioral analytics for fraud scoring, forcing investment in privacy-preserving machine learning. Stakeholders must monitor how the European Commission's digital euro initiative alters wallet interoperability standards and merchant fee structures.
Market Dynamics
PSD2 strong customer authentication mandates from the European Banking Authority have triggered a platform consolidation wave, forcing merchants to abandon fragmented payment stacks in favor of unified acquiring architectures that can route transactions across multiple schemes while maintaining compliance.
Growth Catalysts
- NFC infrastructure densification:Transit authorities in Germany and the Netherlands are deploying contactless readers at metro gates and bus terminals, conditioning commuters to tap-to-pay behavior that transfers directly to retail environments.
- Open banking API standardization:The EU's revised Payment Services Directive mandates account-to-account payment rails, reducing interchange costs for merchants and accelerating P2P volume between consumers.
- GDPR-compliant fraud analytics:Privacy-preserving machine learning frameworks enable real-time transaction scoring without exposing personal data, satisfying both risk officers and data protection officers at issuing banks.
Market Restraints
- Issuer processing concentration:Four banking groups control over sixty percent of European card issuing infrastructure, creating single-point-of-failure risk during peak transaction windows like Black Friday.
- Token vault interoperability gaps:Proprietary credential tokenization systems from major wallet providers prevent seamless credential portability between competing platforms, fragmenting merchant integration roadmaps.
- Hardware security module costs:PCI-DSS compliance requires certified HSM deployments for key management, imposing six-figure capex floors that exclude smaller merchant acquirers from direct scheme connectivity.
Strategic Opportunities
- Polish and Romanian merchant digitization:Cash-heavy retail corridors in Central Europe present first-mover advantages for mobile-first acquiring platforms that bypass legacy terminal infrastructure entirely.
- Request-to-pay messaging convergence:The European Payments Council's SEPA Instant Credit Transfer scheme enables invoice-initiated payments, opening B2B receivables automation previously dominated by card networks.
- Biometric authentication at point-of-sale:Fingerprint and facial recognition systems certified under PSD2's inherence factor requirements are reducing checkout friction below three seconds in Nordic grocery chains.
Industry Challenges
- Legacy core banking integration:Tier-2 banks in France and Italy operate on COBOL-based ledger systems that require expensive middleware layers to expose real-time balance APIs for wallet funding.
- Cross-border scheme certification timelines:Obtaining Visa and Mastercard token service provider status demands eighteen-month audit cycles that delay product launches for fintech challengers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Mobile Payment Market |
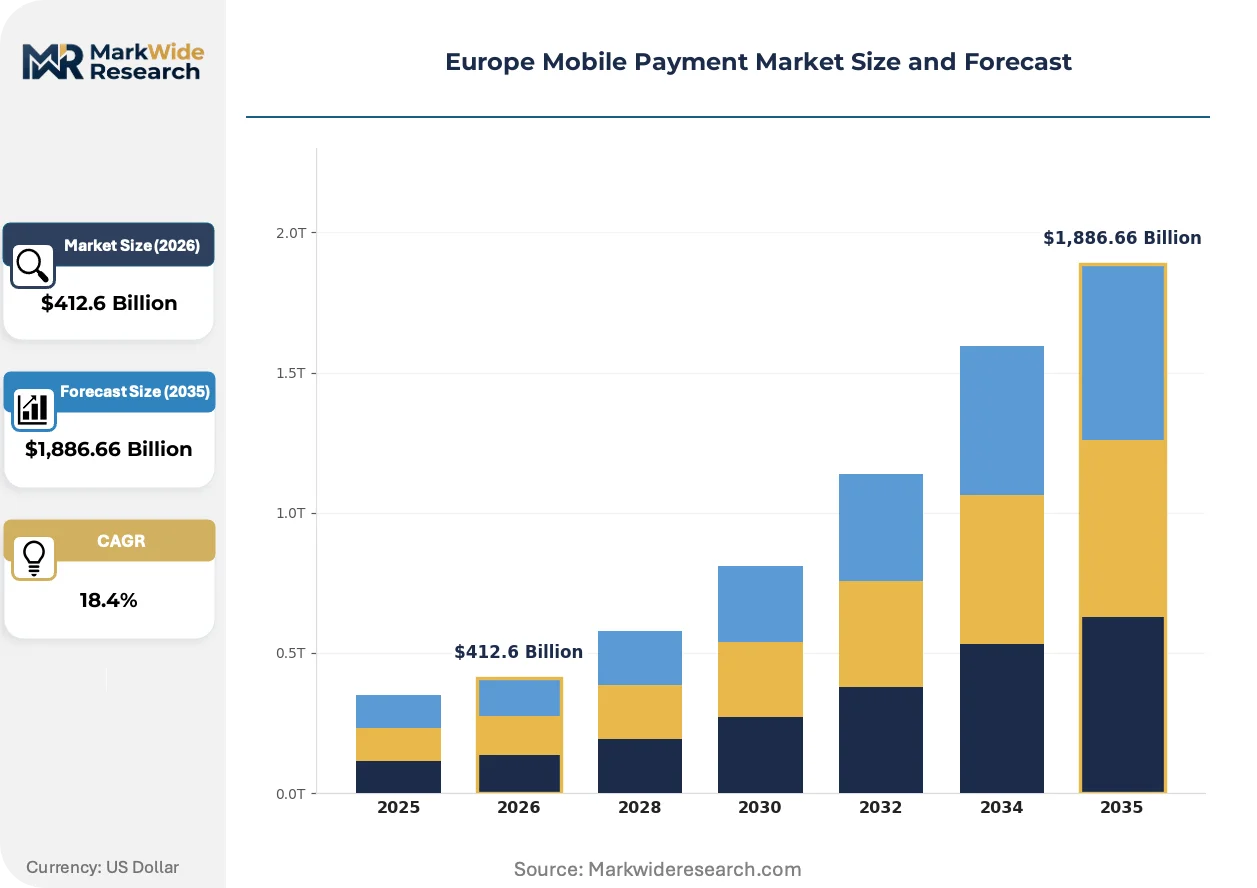
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $1,886.66 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Digital Wallet, Bank Transfer End User: Retail Consumers, Service Providers, Enterprises, Merchants Technology: NFC, QR Code, Mobile App, Bluetooth Transaction Type: In-Store Payments, Online Payments, P2P Payments, Subscription Services |
| Companies Covered | Adyen N.V., Samsung Electronics Co., Ltd., Apple Inc., Klarna Bank AB, Worldline SA, Google LLC, Stripe, Inc., Amazon.com, Inc., PayPal Holdings, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Mobile Payment Market Strategic Shifts & Innovations
Embedded finance architectures are collapsing the distinction between payment acceptance and merchant software, enabling SaaS platforms to capture interchange revenue previously reserved for licensed financial institutions.
Software point-of-sale systems are absorbing merchant checkout flows by converting generic tablets and smartphones into certified payment terminals through cryptographic attestation protocols. Mid-market retailers in Spain and Portugal are adopting these solutions at triple-digit annual rates, eliminating dedicated hardware procurement cycles. This absorption is compressing margins for traditional terminal manufacturers while expanding addressable market coverage to micro-merchants previously below hardware viability thresholds.
The EU AI Act's risk classification framework for biometric identification systems is forcing payment providers to rearchitect facial recognition checkout pilots across German supermarkets and Dutch convenience stores. High-risk system designations trigger conformity assessment obligations that extend deployment timelines by twelve to eighteen months. Nordic wallet operators are responding by pivoting toward behavioral biometrics—keystroke dynamics and gait analysis—that fall outside the Act's most stringent compliance tiers.
Merchant procurement of payment acceptance is fragmenting across vertical-specific software platforms rather than consolidating through generic acquiring relationships. Restaurant operators now expect native payment functionality within reservation and inventory systems, bypassing standalone terminal procurement entirely. This disintermediation is most visible in Italy's hospitality sector, where property management system vendors have captured seventy percent of new payment terminal deployments through bundled software contracts.
Europe Mobile Payment Market Segmentation
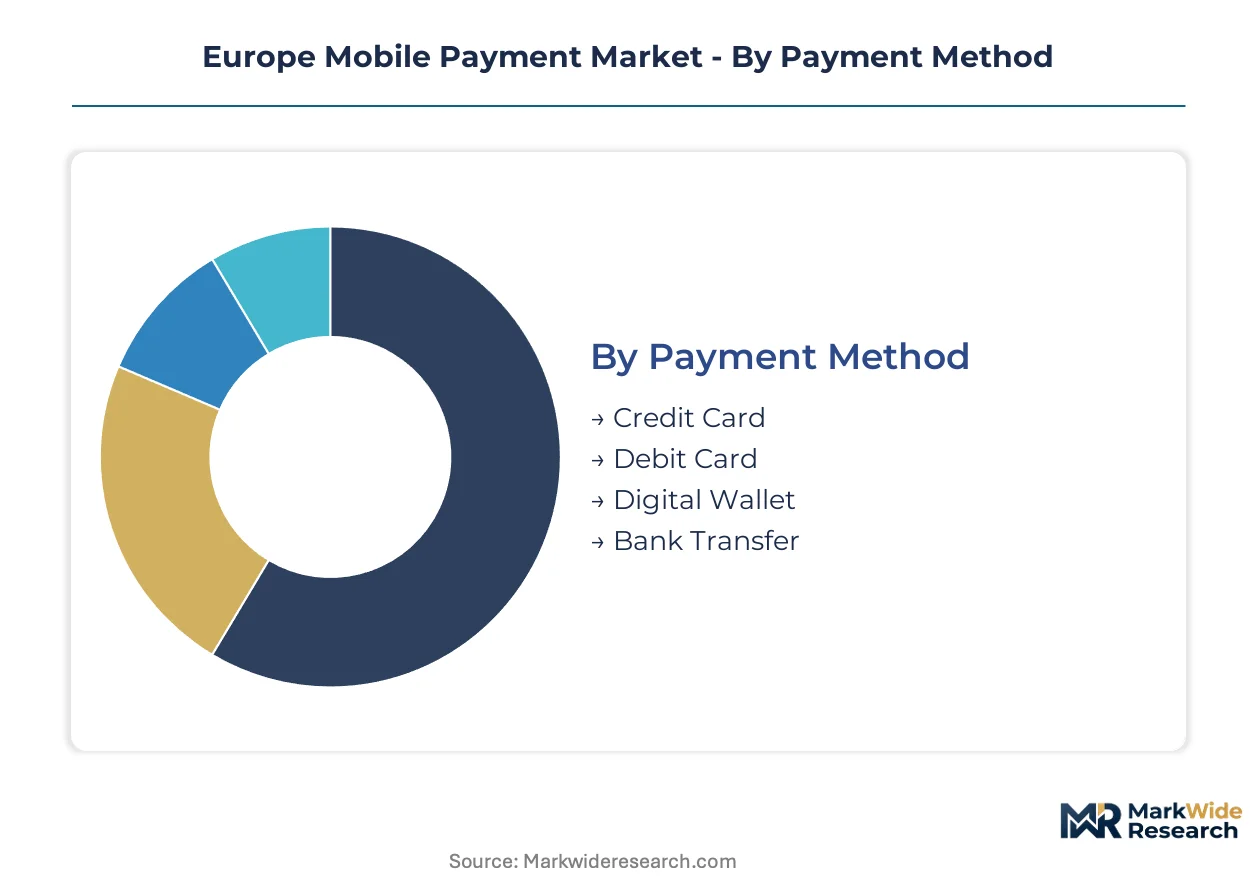
Mobile payment segmentation in Europe reflects divergent infrastructure maturity and regulatory pressure points. Volume concentration varies sharply across payment rails, while premium capture clusters around authentication-integrated solutions.
Payment Method:
Credit and debit card rails dominate transaction volume through established interchange networks, while digital wallets command premium positioning via embedded loyalty and biometric verification.
- Credit Card:Revolving credit lines tokenized into device-native wallets sustain high average transaction values across German automotive and French luxury retail. PSD2 strong customer authentication requirements have elevated 3D-Secure adoption rates, reducing fraud liability for issuing banks while adding friction to guest checkout flows.
- Digital Wallet:Device-native credential storage with embedded transit and identity credentials captures the steepest expansion trajectory in Nordic markets. Apple Pay and Google Pay interoperability with open banking APIs enables account-to-account funding that bypasses traditional card scheme economics entirely.
- Debit Card:Real-time balance verification through open banking rails supports instant authorization without credit risk exposure, concentrating demand among Dutch and German consumers with negative interest rate sensitivities.
- Bank Transfer:SEPA Instant Credit Transfer integration via mobile banking apps eliminates interchange fees for merchants, gaining traction in B2B invoice settlement and high-value consumer purchases.
Mature deployment sits with credit and debit card tokenization. Newer deployment is concentrated in bank transfer and wallet-native account funding.
End User:
Merchant scale determines payment acceptance complexity, with micro-enterprises demanding zero-hardware solutions and large retailers requiring multi-scheme routing intelligence.
- Retail Consumers:Individual users executing proximity and remote purchases through smartphone-enabled credentials. French and German consumers lead contactless tap limits, routinely exceeding single-transaction thresholds that trigger strong authentication.
- Merchants:Businesses accepting mobile payments span sole proprietors to pan-European retail chains. Italian hospitality operators increasingly bundle payment acceptance into property management systems, bypassing standalone terminal procurement.
- Service Providers:Platforms facilitating payment orchestration for sub-merchant networks, including gig economy marketplaces and software-integrated billing systems.
- Enterprises:Corporate treasury functions deploying mobile-enabled expense management and supplier payment automation through ERP-integrated wallets.
Volume concentration favors retail consumers. Margin expansion concentrates in merchant and enterprise segments with customized routing logic.
Technology:
Infrastructure deployment costs separate proximity technologies, with NFC requiring dedicated reader hardware and QR codes leveraging existing display infrastructure.
- NFC:Near-field communication chips enable sub-500 millisecond transaction completion at physical point-of-sale. German transit authorities and Dutch retail chains have densified reader deployment, conditioning consumer tap-to-pay behavior that transfers across merchant categories.
- QR Code:Optical scanning of encoded payment instructions eliminates hardware dependencies for micro-merchants. Polish and Romanian cash-heavy corridors show accelerating adoption as smartphone penetration outpaces terminal infrastructure investment.
- Mobile App:Merchant-branded applications with integrated checkout and loyalty functions capture repeat purchase economics in Spanish grocery and Portuguese fuel retail.
- Bluetooth:Low-energy beacon protocols enable proximity-triggered payment initiation without physical tap, piloting in Nordic convenience stores for sub-three-second checkout completion.
Hardware-intensive NFC deployment saturates Western European urban corridors. QR and Bluetooth solutions are expanding most quickly in hardware-constrained Central European markets.
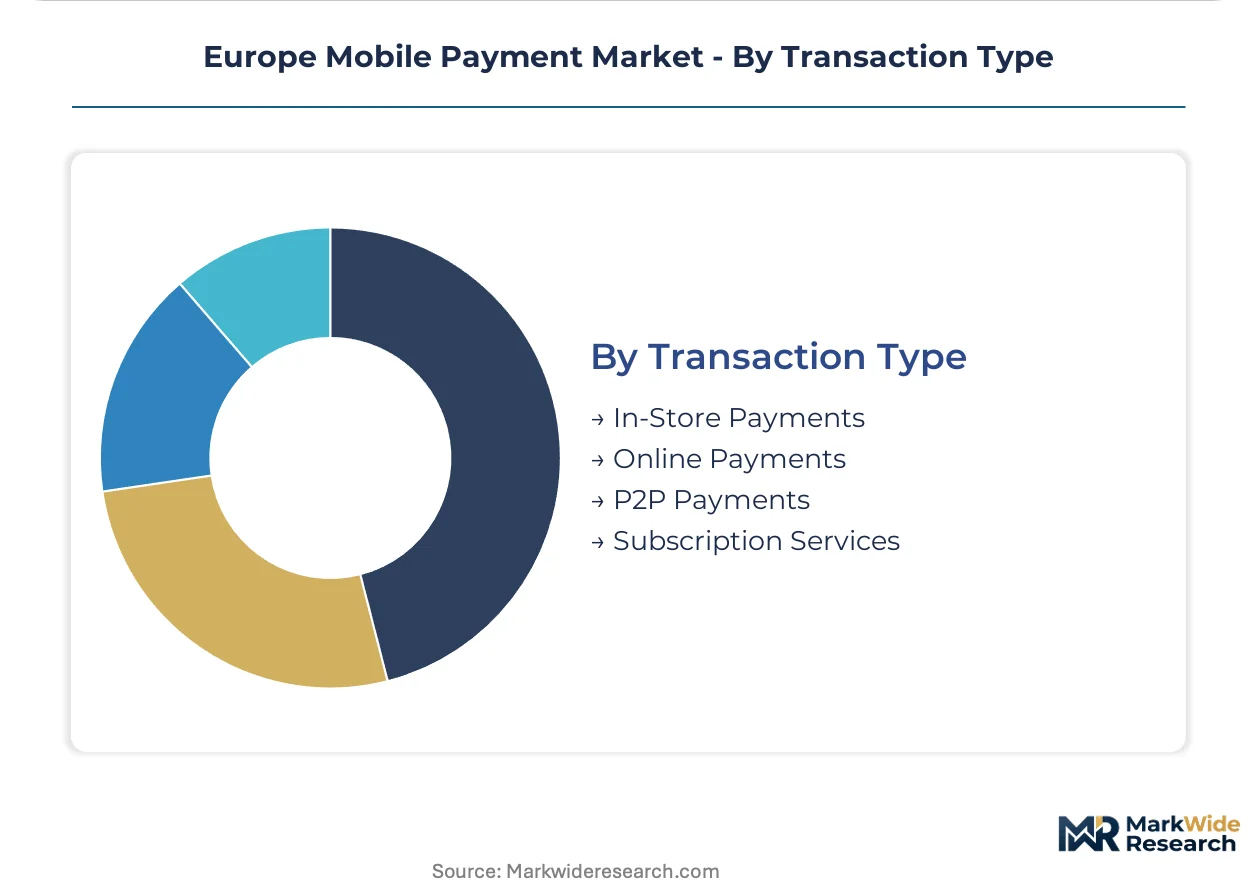
Transaction Type:
Settlement timing and authentication requirements fragment transaction economics, with instant P2P transfers disrupting traditional correspondent banking and subscription models capturing recurring revenue streams.
- P2P Payments:Person-to-person transfers via mobile number or email alias represent the fastest-climbing transaction category. Open banking APIs reduce settlement friction between individuals, with Dutch and British consumers leading adoption of account-to-account person-to-person rails.
- In-Store Payments:Proximity transactions at physical merchant locations leverage NFC density and tokenized credentials. Contactless limits vary by country, with some Nordic markets eliminating maximum thresholds for low-risk biometrically-verified purchases.
- Online Payments:Remote commerce via mobile browsers and in-app checkout flows. Strong customer authentication mandates have elevated biometric verification adoption, reducing cart abandonment in French fashion and German electronics verticals.
- Subscription Services:Recurring billing authorization through stored credentials with variable amount frameworks. GDPR-compliant consent management and instant cancellation rights shape merchant retention strategies.
Recurring subscription infrastructure is maturing in media and software verticals. P2P and in-store proximity solutions are gaining share fastest as open banking and transit conditioning converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payment processing capacity concentrates in Western European financial hubs while consumption growth accelerates across Central and Eastern European corridors. Germany and the Netherlands anchor acquiring infrastructure investment. Poland and Romania drive volume expansion as cash substitution accelerates.
Germany
Automotive retail and grocery chains are densifying NFC reader deployment at checkout lanes. The Federal Financial Supervisory Authority enforces PSD2 strong customer authentication timelines for issuing banks. Berlin and Hamburg host fintech clusters where software point-of-sale platforms are displacing traditional terminal vendors.
United Kingdom
Open banking API adoption for account-to-account transfers is reshaping P2P payment behavior among retail consumers. The Financial Conduct Authority mandates contingency safeguarding arrangements for e-money institutions. London's Square Mile concentration of merchant acquirers is expanding into subscription billing and B2B invoice automation.
France
Hospitality operators in Paris and Lyon are bundling payment acceptance into property management systems. The French Prudential Supervision and Resolution Authority coordinates with the European Banking Authority on authentication compliance. Île-de-France fintech incubators are piloting biometric checkout systems in supermarket chains.
Netherlands
Transit authorities in Amsterdam and Rotterdam have conditioned commuters to tap-to-pay behavior that transfers to retail environments. The Dutch Central Bank supervises instant payment settlement under SEPA Instant Credit Transfer frameworks. Eindhoven's technology corridor hosts tokenization service providers serving cross-border merchant networks.
Poland
Micro-merchants in Warsaw and Kraków are bypassing legacy terminal infrastructure through QR-code acceptance solutions. The Polish Financial Supervision Authority implements EU payment service directives with national transposition deadlines. Cash-heavy retail corridors present first-mover advantages for mobile-first acquiring platforms.
Europe Mobile Payment Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the European mobile payment ecosystem. Consolidation pressures favor unified platform architectures that can route transactions across multiple schemes while maintaining regulatory compliance. Three archetypes dominate: pan-European merchant acquirers with banking partnerships, device-native wallet operators with tokenized credential ecosystems, and embedded finance platforms integrating checkout into vertical software. Dominant competitive moves include strategic partnerships for open banking API access and geographic expansion into underpenetrated Central European corridors.
Within the merchant acquirer tier, Adyen N.V. and Worldline SA exemplify platform-scale operations that anchor European acquiring infrastructure. Klarna Bank AB occupies a differentiated position among buy-now-pay-later specialists with deep Nordic retail integration. These entities represent contrasting strategic postures: unified cross-border architecture versus regional banking partnership density versus vertical checkout integration.
| Leading Market Players |
|---|
| Adyen N.V. |
| Samsung Electronics Co., Ltd. |
| Apple Inc. |
| Klarna Bank AB |
| Worldline SA |
| Google LLC |
| Stripe, Inc. |
| Amazon.com, Inc. |
| PayPal Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
GDPR-compliant data processing certification gates qualified supply access for payment service providers seeking premium-tier merchant contracts across German and French retail corridors. The European Banking Authority's strong customer authentication mandates simultaneously constrain infrastructure deployment options and justify premium pricing for compliant platform architectures.
Pricing Analysis
Margin tightening in merchant acquiring reflects interchange compression from open banking account-to-account rails displacing traditional card scheme economics. Three-tier pricing structure across enterprise, mid-market, and micro-merchant levels separates customized routing logic from standardized API access from self-serve onboarding. Pricing pressure intensifies in the micro-merchant tier as software point-of-sale platforms eliminate hardware procurement barriers entirely. Enterprise buyers demonstrate lowest price sensitivity due to multi-scheme routing requirements and regulatory compliance complexity.
Supply Chain Analysis
Hardware security module production rests on certified semiconductor foundries in Germany, Taiwan, and the Netherlands. Payment terminal manufacturing draws from Taiwanese chip fabrication, Malaysian electronics assembly, and German precision engineering components. Single-source vulnerability concentrates in certified HSM cryptographic processor supply where qualified vendor lists remain restricted. Distribution runs through pan-European merchant acquirer networks with direct scheme connectivity bypassing regional banking intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payment infrastructure consolidation has triggered a vertical-integration race where platform control over tokenization vaults and open banking API access determines long-term margin capture.
For Market Incumbents: Lock in merchant relationships through embedded finance partnerships that bundle payment acceptance into vertical software platforms. Deepen control over token service provider certification to defend against fintech challengers facing eighteen-month audit timelines. Prioritize banking partnership density in Poland and Romania where cash substitution accelerates. For New Entrants and Emerging Players: Begin with QR-code acceptance solutions targeting Polish and Romanian micro-merchants bypassing legacy terminal infrastructure entirely. Exploit regulatory arbitrage in SEPA Instant Credit Transfer integration where incumbent core banking modernization lags. Deploy mobile-first acquiring platforms with zero-hardware onboarding to capture first-mover advantages in Central European cash-heavy corridors. For Investors and Strategic Acquirers: Open banking API adoption velocity among tier-2 banks is the leading indicator that middleware modernization demand will sustain independent software vendor valuations. Frame long-term viability around platform architectures capable of routing across multiple payment schemes while maintaining PSD2 compliance. Target acquisition profiles emphasizing tokenization service provider status and biometric authentication certification. Watch Nordic behavioral biometrics pilots as the signal for regulatory-compliant friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Partnership | Captures interchange revenue previously reserved for licensed financial institutions through vertical software integration. |
| Token Service Provider Certification | Accelerates product launch timelines by satisfying Visa and Mastercard eighteen-month audit requirements. |
| Biometric Authentication Deployment | Reduces checkout friction below three seconds while satisfying PSD2 inherence factor mandates. |
| Open Banking API Integration | Enables account-to-account funding that bypasses traditional card scheme economics entirely. |
| Software Point-of-Sale Expansion | Converts generic tablets into certified payment terminals, eliminating dedicated hardware procurement cycles. |
Research Approach
Multi-period observation of NFC infrastructure deployment rates, open banking API adoption curves, and merchant acquiring contract structures anchored the trend analysis, supplemented by interviews with payment platform executives, regulatory compliance officers at issuing banks, merchant acquirer product managers, and transit authority procurement leads. Secondary validation drew from European Banking Authority guidance documents, European Payments Council SEPA scheme rulebooks, national financial supervisory authority transposition notices, and PCI-DSS certification databases. Bottom-up merchant adoption modeling and top-down payment volume projections were triangulated against scheme-reported transaction statistics.
Input-output matrices structured demand drivers across payment method, end user scale, technology deployment, and transaction type dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate differentials weighted by baseline volume concentration. Industry-specific forecast inputs included PSD2 strong customer authentication implementation timelines and digital euro initiative pilot program scope.
Regulatory enforcement variance, biometric authentication certification delays, and core banking modernization timeline slippage are the dominant revision risks to modeled projections. A concentrated set of regulatory and technology triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Sweden Mobile Payments Market
Payments
China POS Terminals Market
Payments
Australia Buy Now Pay Later Services Market
Payments
Uganda Mobile Money Market
Payments
E-Commerce Payments Market
Payments
Smart POS System Market
Payments
Hong Kong Credit Cards Market
Payments
Global Accounts Payable Automation Market
Payments
Czech Republic POS Terminals Market
Payments
United States POS Terminals Market
Payments
Egypt Mobile Payments Market
Payments
Canada Mobile Payments Market
Payments
Mobile Wallet Market
Payments
Global Telecom Billing and Revenue Management Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Global Virtual Payment (POS) Terminals Market