
 Dissolvable Sutures Market | 2026-2036
Dissolvable Sutures Market Size, Share, and Industry Trends Forecast 2026-2036
Dissolvable Sutures Market Outlook
USP Class VI compliance is rotating from a niche specification to a baseline procurement filter across North American and European hospital systems. Johnson & Johnson Services, Inc. leverages its Ethicon heritage to dominate synthetic polymer R&D pipelines. B. Braun Melsungen AG anchors European supply through vertically integrated filament extrusion facilities in Germany. Medtronic competes by extending its surgical portfolio into specialized cardiovascular closure applications.
Dissolvable sutures are absorbable surgical threads engineered from synthetic polymers such as polyglactin 910 or polyglycolic acid, designed to degrade through hydrolysis within 60 to 90 days and eliminate the need for post-operative removal. Their primary commercial purpose centers on reducing infection risk, shortening hospital stays, and eliminating follow-up extraction procedures in soft-tissue approximation. Polyglactin formulations lead material-type revenue due to their balanced tensile strength and absorption predictability, while polylactic acid variants represent the fastest-growing segment as orthopedic surgeons adopt longer-lasting absorbable constructs for ligament and tendon repair. Monofilament product forms command premium positioning in minimally invasive procedures where tissue drag minimization determines clinical selection.
FDA 510(k) clearance pathways and EU MDR Class IIa conformity requirements shape product development timelines, with both agencies intensifying scrutiny of absorption-rate consistency claims and particulate contamination thresholds. ISO 10993 biocompatibility testing series governs cytotoxicity and sensitization protocols, creating compliance cost barriers that favor manufacturers with established regulatory affairs infrastructure. Stakeholders must monitor evolving FDA guidance on absorbable synthetic sutures as the agency weighs whether to reclassify certain polymer compositions based on emerging adverse event profiles tied to inflammatory foreign-body responses.
Market Dynamics
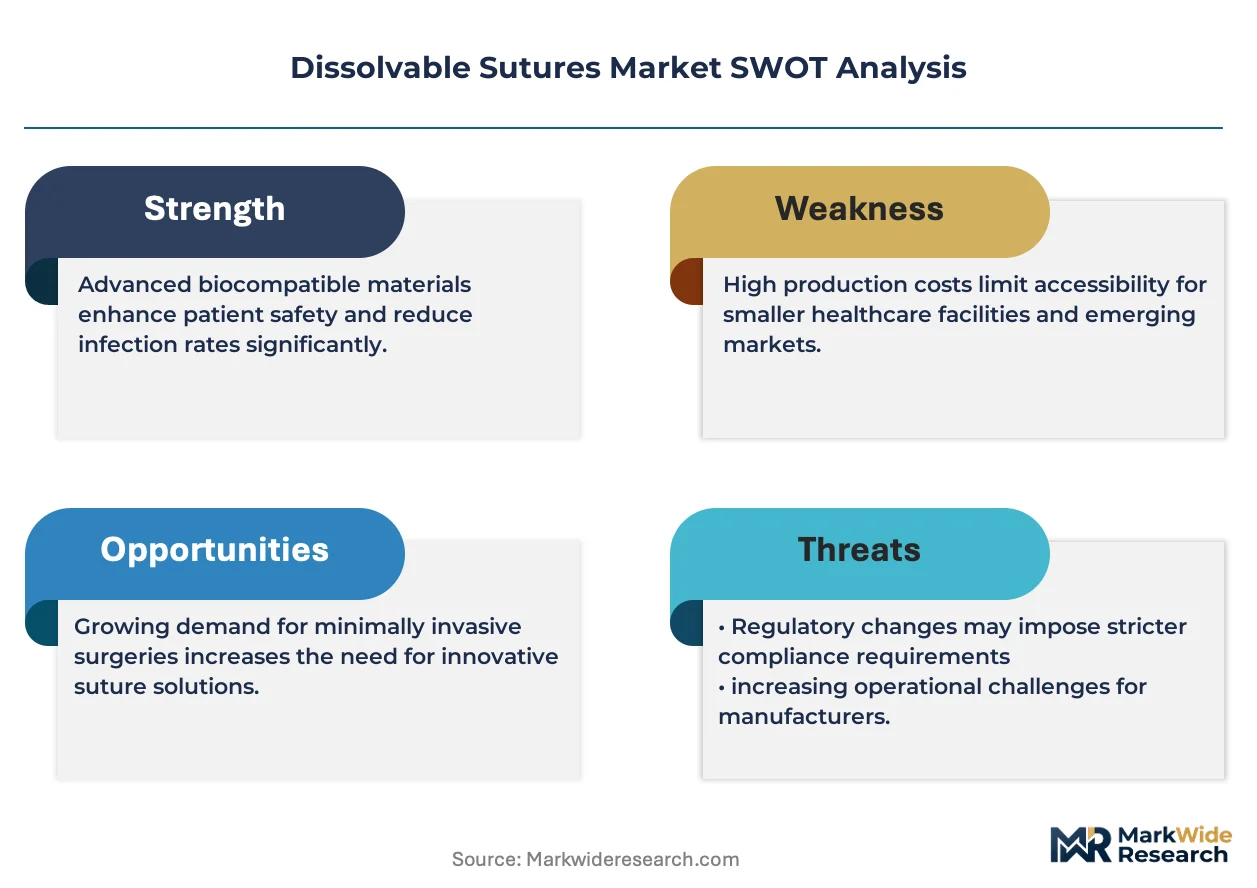
Hospital procurement networks are consolidating vendor lists around USP Class VI-certified synthetic polymer sutures, compressing supplier margins while elevating compliance documentation to a competitive differentiator.
Growth Catalysts
- Ambulatory surgical center expansion:General surgery departments at outpatient facilities are standardizing absorbable wound closure protocols to reduce follow-up visit burdens and infection liability.
- FDA Class II guidance updates:The tightened biocompatibility documentation requirements are filtering out smaller competitors and concentrating procurement among established manufacturers with regulatory infrastructure.
- Polyglactin 910 formulation advances:Predictable hydrolysis profiles with balanced tensile strength are displacing traditional silk and catgut alternatives in soft-tissue approximation procedures.
Market Restraints
- Raw material concentration:Polyglycolic acid and polylactic acid precursor supply chains cluster in East Asian chemical manufacturing zones, exposing suture producers to input volatility and logistics disruption.
- EU MDR conformity costs:The intensified scrutiny of absorption-rate consistency claims and particulate contamination thresholds is extending product development timelines by 12-18 months for Class IIa submissions.
- Monofilament technical limitations:Single-filament synthetic constructs exhibit reduced knot security compared to braided alternatives, restricting adoption in high-tension orthopedic applications.
Strategic Opportunities
- Orthopedic ligament repair segment:Polylactic acid variants with extended absorption windows are penetrating sports medicine practices for tendon-to-bone fixation where longer-lasting absorbable constructs reduce revision surgery rates.
- Indian hospital procurement modernization:CDSCO alignment with ISO 10993 standards is opening institutional tender opportunities for USP Class VI-compliant synthetic polymer suppliers.
- Minimally invasive surgery instrumentation:Low-friction monofilament sutures paired with robotic laparoscopic delivery systems are creating premium positioning in cardiac and gynecologic procedures.
Industry Challenges
- Regulatory affairs talent scarcity:Manufacturers face acute shortages of professionals fluent in FDA 510(k) pathway navigation and EU MDR technical documentation requirements.
- Absorption-rate validation capex:In vivo degradation testing facilities and accelerated aging chambers require seven-figure capital commitments to generate ISO-compliant consistency data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dissolvable Sutures Market |
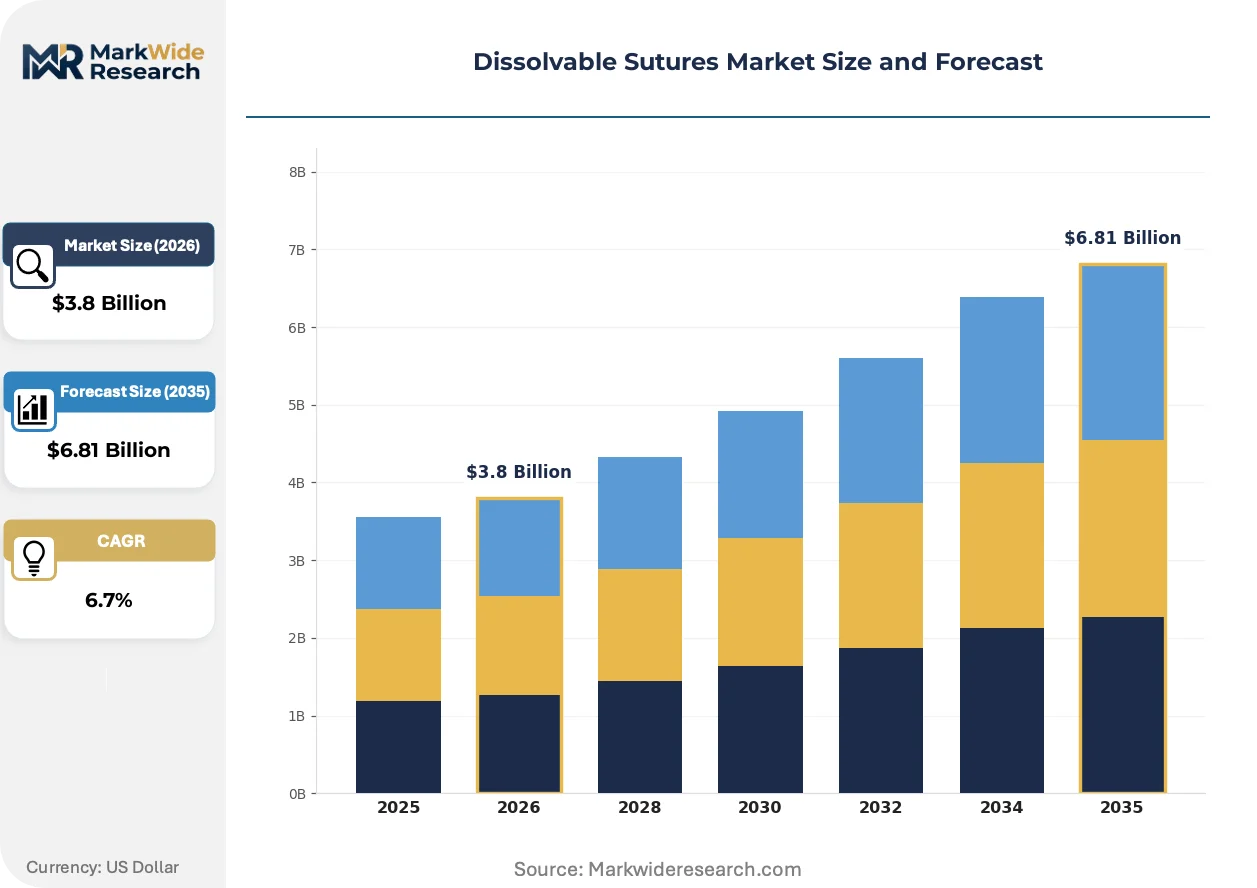
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyglactin, Polyglycolic Acid, Catgut, Polylactic Acid Application: General Surgery, Orthopedic Surgery, Dental Procedures, Gynecological Surgery End User: Hospitals, Clinics, Ambulatory Surgical Centers, Veterinary Clinics Product Form: Monofilament, Multifilament, Coated, Non-coated |
| Companies Covered | B. Braun Melsungen AG, Johnson & Johnson Services, Inc., Medtronic, Boston Scientific Corporation, DemeTECH Corporation, Smith & Nephew, Teleflex Incorporated, Surgical Specialties Corporation, CONMED Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dissolvable Sutures Market Strategic Shifts
Material science breakthroughs and regulatory harmonization pressures are converging to redefine performance benchmarks for absorbable surgical closure, with hydrolysis predictability now commanding premium positioning over tensile strength alone.
Antibacterial-coated polyglactin formulations are supplanting uncoated synthetic alternatives in contaminated wound settings. Surgical teams at trauma centers and emergency departments are accelerating adoption of triclosan-impregnated monofilament constructs. This coating technology is compressing infection-related revision rates and shortening post-operative antibiotic protocols.
EU MDR technical documentation requirements are forcing manufacturers to revalidate absorption-rate claims with longitudinal clinical data. The regulation mandates traceable particulate contamination thresholds across filament extrusion batches. Cardiovascular closure applications face the steepest compliance burden due to inflammatory foreign-body response sensitivity.
Hospital procurement committees are consolidating suture SKUs around standardized synthetic polymer platforms with predictable degradation curves. Group purchasing organizations are displacing physician preference item autonomy with formulary restrictions tied to total cost-of-care metrics. This concentration is most visible in United States health systems where value-based reimbursement contracts penalize preventable readmissions.
Dissolvable Sutures Market Segmentation
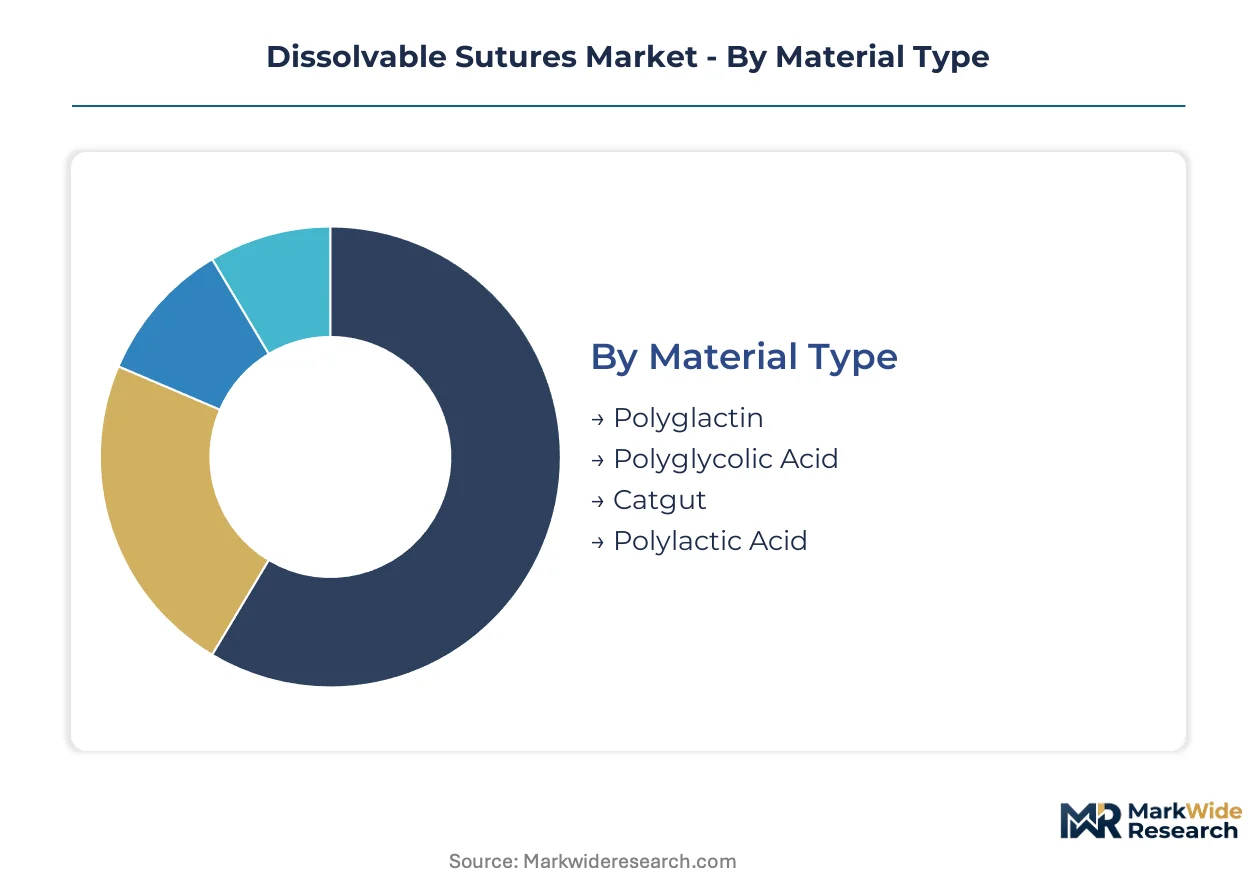
Dissolvable sutures fragment across material chemistry, clinical application, and institutional procurement channels. Each segmentation axis carries distinct regulatory burdens and margin structures that reshape competitive positioning.
Material Type:
Polyglactin formulations anchor domestic production in Germany and the United States, while polylactic acid precursor supply concentrates in East Asian chemical manufacturing zones.
- Polyglactin:A copolymer of glycolide and lactide engineered for predictable hydrolysis within 60-90 days. Demand concentrates in United States hospital procurement networks where USP Class VI certification filters vendor selection. The balanced tensile strength profile displaces silk and catgut in soft-tissue approximation.
- Polylactic Acid:A longer-lasting absorbable polymer with degradation windows extending 12-18 months. Orthopedic surgeons in sports medicine practices adopt these constructs for tendon-to-bone fixation, reducing revision surgery liability. The steepest expansion trajectory runs through ligament repair applications.
- Polyglycolic Acid:The foundational synthetic absorbable with rapid hydrolysis kinetics. Braided multifilament forms dominate cardiovascular closure where rapid strength loss is clinically acceptable.
- Catgut:Collagen-based natural absorbable derived from bovine or ovine intestinal submucosa. Declining share in regulated markets due to prion transmission concerns and inconsistent absorption rates.
Polyglactin commands the established base. The steepest expansion runs through polylactic acid variants.
Application:
Procedure volume and reimbursement intensity determine segment attractiveness, with orthopedic and cardiac applications commanding premium positioning over commoditized general surgery.
- General Surgery:High-volume soft-tissue closure in abdominal and thoracic procedures. Ambulatory surgical centers standardize absorbable protocols here to eliminate follow-up extraction visits.
- Orthopedic Surgery:Ligament and tendon repair applications requiring extended absorption windows. Sports medicine practices in the United States drive adoption of polylactic acid constructs with 12-month degradation profiles.
- Dental Procedures:Oral surgery and periodontal applications favor rapid-absorption monofilament forms. Infection risk in contaminated oral environments accelerates antibacterial-coated product penetration.
- Gynecological Surgery:Laparoscopic hysterectomy and pelvic floor repair procedures. Robotic surgical systems demand low-friction monofilament delivery compatibility.
General surgery captures volume concentration. Orthopedic surgery delivers margin expansion.
End User:
Procurement authority and formulary control differentiate customer segments, with hospital networks consolidating vendor lists while ambulatory centers prioritize total cost-of-care metrics.
- Hospitals:Integrated delivery networks with centralized procurement committees. Group purchasing organizations displace physician preference item autonomy with standardized synthetic polymer formularies.
- Clinics:Office-based surgical facilities with limited sterilization infrastructure. Pre-packaged sterile suture kits reduce compliance burden for minor procedure volumes.
- Ambulatory Surgical Centers:Outpatient facilities expanding general surgery capacity. Value-based reimbursement contracts penalize preventable readmissions, accelerating absorbable adoption.
- Veterinary Clinics:Companion animal and livestock surgical applications. Lower regulatory barriers permit faster product iteration compared to human medical channels.
Hospital networks concentrate purchasing power. Ambulatory surgical centers are gaining share fastest.
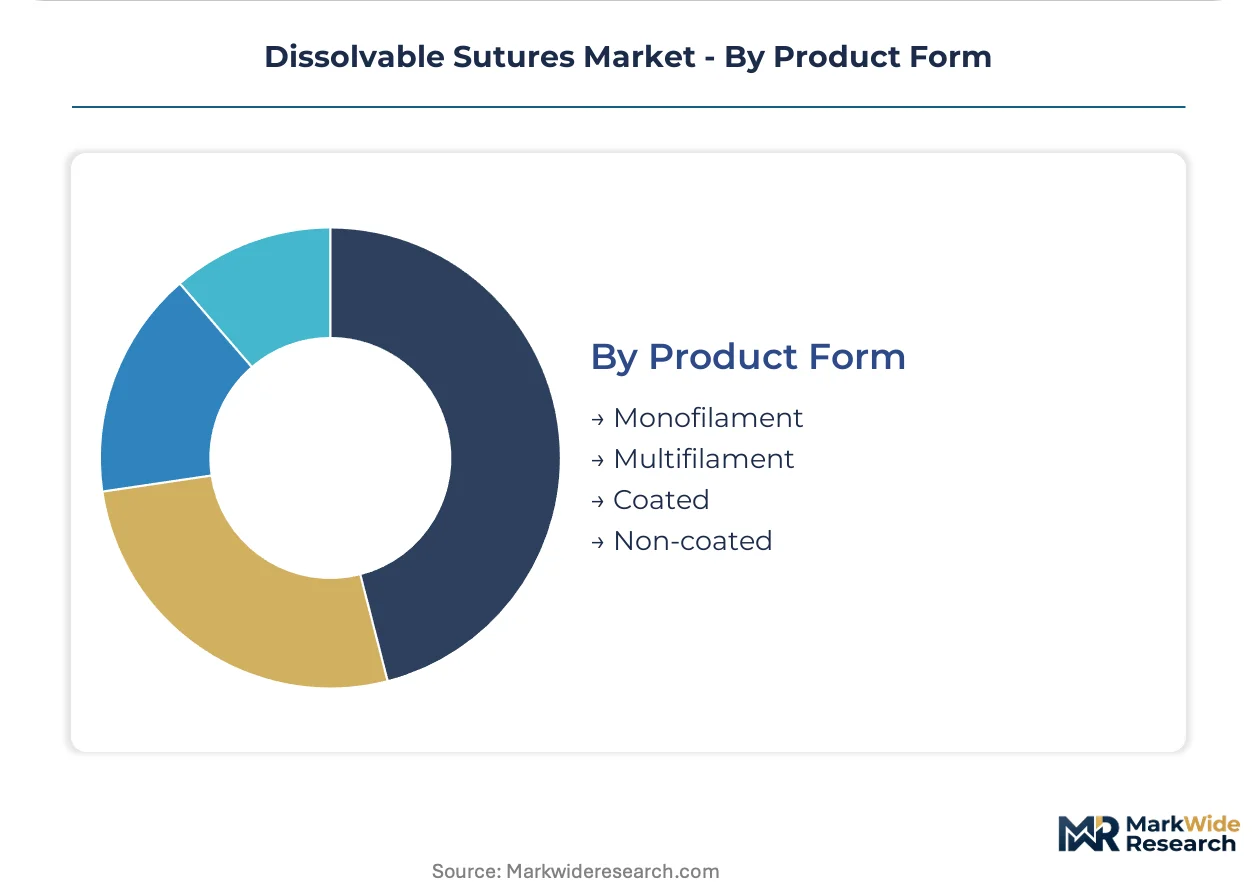
Product Form:
Manufacturing complexity and clinical performance trade-offs segment the market, with monofilament construction commanding premium pricing despite knot security limitations.
- Monofilament:Single-filament synthetic construction minimizing tissue drag. Minimally invasive cardiac and gynecologic procedures demand low-friction profiles for robotic laparoscopic delivery systems.
- Multifilament:Braided fiber construction delivering superior knot security. High-tension orthopedic applications retain preference for braided alternatives despite higher infection risk profiles.
- Coated:Surface-treated filaments with triclosan or similar antibacterial agents. Trauma centers adopt these for contaminated wound settings to compress infection-related revision rates.
- Non-coated:Base polymer construction without surface modification. Cost-sensitive procurement in veterinary and emerging market channels sustains residual demand.
Multifilament retains the volume base. Monofilament claims the steepest premium trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in dissolvable sutures tilt toward net import dependence in emerging economies while established manufacturing hubs in Germany and the United States supply synthetic polymer feedstock to hospital networks worldwide. Currency volatility and logistics disruption are redirecting procurement strategies toward regional buffer inventories.
United States
Hospital procurement networks concentrate purchasing power through group purchasing organizations that filter vendor selection around USP Class VI certification. FDA 510(k) clearance pathways for Class II medical devices shape product development timelines with intensified scrutiny of absorption-rate consistency claims. The Minneapolis-St. Paul corridor anchors domestic filament extrusion capacity serving ambulatory surgical center expansion.
Germany
B. Braun Melsungen AG maintains vertically integrated production from polymer precursor to finished suture through captive filament extrusion facilities. EU MDR Class IIa conformity requirements mandate revalidation of absorption-rate claims with longitudinal clinical data extending product development timelines. The Tuttlingen surgical instruments cluster integrates suture supply with laparoscopic and robotic delivery system manufacturers.
China
Domestic hospital procurement modernization under volume-based purchasing compresses margins for imported synthetic polymer sutures while elevating local CDSCO-aligned manufacturers. NMPA medical device registration requirements for absorbable sutures intensify biocompatibility documentation thresholds. The Yangtze River Delta chemical manufacturing zone concentrates polyglycolic acid and polylactic acid precursor supply exposing producers to input volatility.
India
CDSCO alignment with ISO 10993 standards opens institutional tender opportunities for USP Class VI-compliant synthetic polymer suppliers in tertiary care hospital networks. The Medical Device Rules 2017 classification of surgical sutures as Class C devices imposes quality management system audits on domestic manufacturers. The Ahmedabad-Vadodara pharmaceutical corridor hosts emerging suture fabricators targeting export markets in Southeast Asia and Africa.
Japan
PMDA marketing authorization requirements for absorbable surgical sutures mandate Japan-specific clinical bridging studies extending regulatory timelines for foreign manufacturers. Aging demographics and surgical procedure volume growth drive hospital procurement of predictable hydrolysis profile polymers. The Kansai region maintains specialized coating technology capabilities for antibacterial-impregnated monofilament constructs.
Dissolvable Sutures Market Competitive Environment
Concentration sits with diversified medical device conglomerates that leverage surgical portfolio breadth to secure hospital formulary placement. Three to five manufacturers control synthetic polymer R&D pipelines and regulatory affairs infrastructure while mid-tier specialists compete on price in veterinary and emerging market channels. Strategic archetypes include vertically integrated polymer-to-suture producers, surgical instrumentation bundlers, and regional private-label fabricators. Competitive moves center on M&A to acquire absorption-rate validation capabilities and strategic partnerships with robotic surgical system manufacturers.
Among diversified medical device conglomerates, Johnson & Johnson Services, Inc. and Medtronic exemplify the surgical portfolio breadth archetype that secures integrated delivery network contracts. B. Braun Melsungen AG represents the vertically integrated polymer-to-suture producer model with captive filament extrusion infrastructure. These three occupy positions where regulatory affairs scale and biocompatibility documentation depth filter smaller competitors from hospital procurement shortlists.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Johnson & Johnson Services, Inc. |
| Medtronic |
| Boston Scientific Corporation |
| DemeTECH Corporation |
| Smith & Nephew |
| Teleflex Incorporated |
| Surgical Specialties Corporation |
| CONMED Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between hospital procurement networks and synthetic polymer suppliers lock in multi-year supply access while anchoring price visibility against glycolide and lactide feedstock volatility. These contracts compress spot-market exposure for tier-one manufacturers while elevating documentation compliance to a cost-of-entry threshold that filters smaller competitors from formulary shortlists.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium USP Class VI-certified monofilament, standard polyglactin multifilament, and economy-grade veterinary channels. Price differentiation hinges on FDA 510(k) clearance tier and absorption-rate validation depth, with cardiovascular applications commanding the steepest premiums. Cost compression in the standard tier intensifies as group purchasing organizations consolidate vendor lists around predictable hydrolysis profiles. Ambulatory surgical centers exhibit the highest price sensitivity due to value-based reimbursement penalties, while integrated delivery networks prioritize total cost-of-care metrics over unit pricing.
Supply Chain Analysis
China and South Korea anchor polyglycolic acid and polylactic acid precursor production through the Yangtze River Delta and Ulsan chemical manufacturing corridors. Suture fabricators in Germany and the United States draw from these feedstock sources for captive filament extrusion, exposing finished-goods producers to tariff exposure on polymer imports. Distribution runs through hospital group purchasing organizations and specialized surgical distributors serving ambulatory surgical center expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dissolvable sutures market sits in a post-regulatory-harmonization recovery phase, with EU MDR implementation delays and FDA guidance updates now stabilizing procurement timelines.
For Market Incumbents: Secure absorption-rate validation infrastructure through in-house degradation testing facilities or specialist laboratory acquisitions to defend against emerging polylactic acid specialists. Deepen backward integration into polymer precursor supply through strategic offtake partnerships with Chinese chemical manufacturers, reducing exposure to glycolide price volatility that compresses margins in standard-tier segments. For New Entrants and Emerging Players: CDSCO fast-track certification for USP Class VI-compliant synthetic polymers opens institutional tender access in Indian tertiary care networks where procurement modernization displaces legacy catgut suppliers. Target veterinary clinics in Southeast Asia with pre-sterilized suture kits requiring minimal regulatory documentation, leveraging lower biocompatibility barriers to establish manufacturing scale before human-market entry. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors regulatory affairs scale over pure R&D intensity, with absorption-rate validation capabilities commanding acquisition premiums. Target mid-tier manufacturers with established ISO 10993 testing infrastructure and dormant FDA 510(k) submission pipelines. Watch for inflection signals in orthopedic polylactic acid adoption rates as sports medicine practices shift tendon-to-bone fixation protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Absorption-Rate Validation Facility Investment | In-house ISO 10993 testing infrastructure accelerates EU MDR Class IIa submissions and filters competitors from hospital procurement shortlists. |
| Antibacterial Coating Technology Licensing | Triclosan-impregnated monofilament constructs capture trauma center demand for contaminated wound protocols and compress infection-related revision liability. |
| Robotic Surgical System Partnership | Low-friction monofilament compatibility with laparoscopic delivery systems secures premium positioning in cardiac and gynecologic procedure growth segments. |
| Polylactic Acid Orthopedic Portfolio Expansion | Extended degradation window constructs penetrate sports medicine practices for ligament repair applications with 12-month absorption profiles. |
| Indian CDSCO Registration Fast-Track | Institutional tender access in tertiary care networks accelerates volume capture as procurement modernization displaces unregulated suppliers. |
Study Parameters
Operator-level perspectives from hospital procurement directors, biomedical engineers, regulatory affairs specialists, and ambulatory surgical center administrators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) clearance databases, EU MDR technical documentation repositories, and hospital group purchasing organization contract disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators to establish demand sizing across material chemistry, application, and end-user channels.
Sensitivity analysis tested forecast robustness across alternative regulatory implementation timelines and raw material price scenarios over the projection horizon. The analytical framework modeled dissolvable sutures across material type, clinical application, institutional procurement channel, and product form dimensions. CAGRs derived from procedure volume growth trajectories, reimbursement intensity shifts, and synthetic polymer adoption curves in soft-tissue approximation protocols.
The analysis sits within stated boundaries; outcomes outside stable FDA-EU regulatory convergence or sustained glycolide feedstock availability would require recalibration. Forecasts reflect documented assumptions regarding ambulatory surgical center expansion rates and orthopedic polylactic acid penetration trajectories. Recalibration cycles align with material shifts in EU MDR enforcement intensity and hospital procurement network consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Global Surgical Lasers Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Hand-Held Surgical Instruments Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
United States General Surgical Devices Market
Surgical Instruments
Cryosurgical Equipment Market
Surgical Instruments
Surgical Clips Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Skin Graft Blades Market
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
Ophthalmology Surgical Devices Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Special Purpose Needles Market