
 Brazil General Surgical Devices Market | 2026-2036
Brazil General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil General Surgical Devices Market Outlook
Minimally invasive technique integration is narrowing the performance gap between imported and domestically sourced surgical instruments across Brazilian operating rooms. Stryker leverages its robotics platform to anchor high-value spine and joint reconstruction procedures in tier-one hospitals. Medtronic sustains deep catheter and energy device penetration through direct sales teams covering Brazil's southeast corridor. B. Braun Melsungen AG differentiates its sutures and infection control portfolio through localized sterilization service bundling.
General surgical devices encompass sterile instruments, energy systems, wound closure materials, and operative consumables manufactured from medical-grade stainless steel, polymer composites, and braided absorbable filaments, designed to enable tissue manipulation, hemostasis, and anatomical access during operative procedures. Electrosurgical devices command premium placement in cardiovascular and orthopedic surgery applications where precision energy delivery reduces perioperative blood loss. Handheld surgical instruments retain volume dominance across public sector tenders despite slower replacement cycles, while robotic surgery systems capture margin concentration at academic medical centers in Rio de Janeiro and São Paulo.
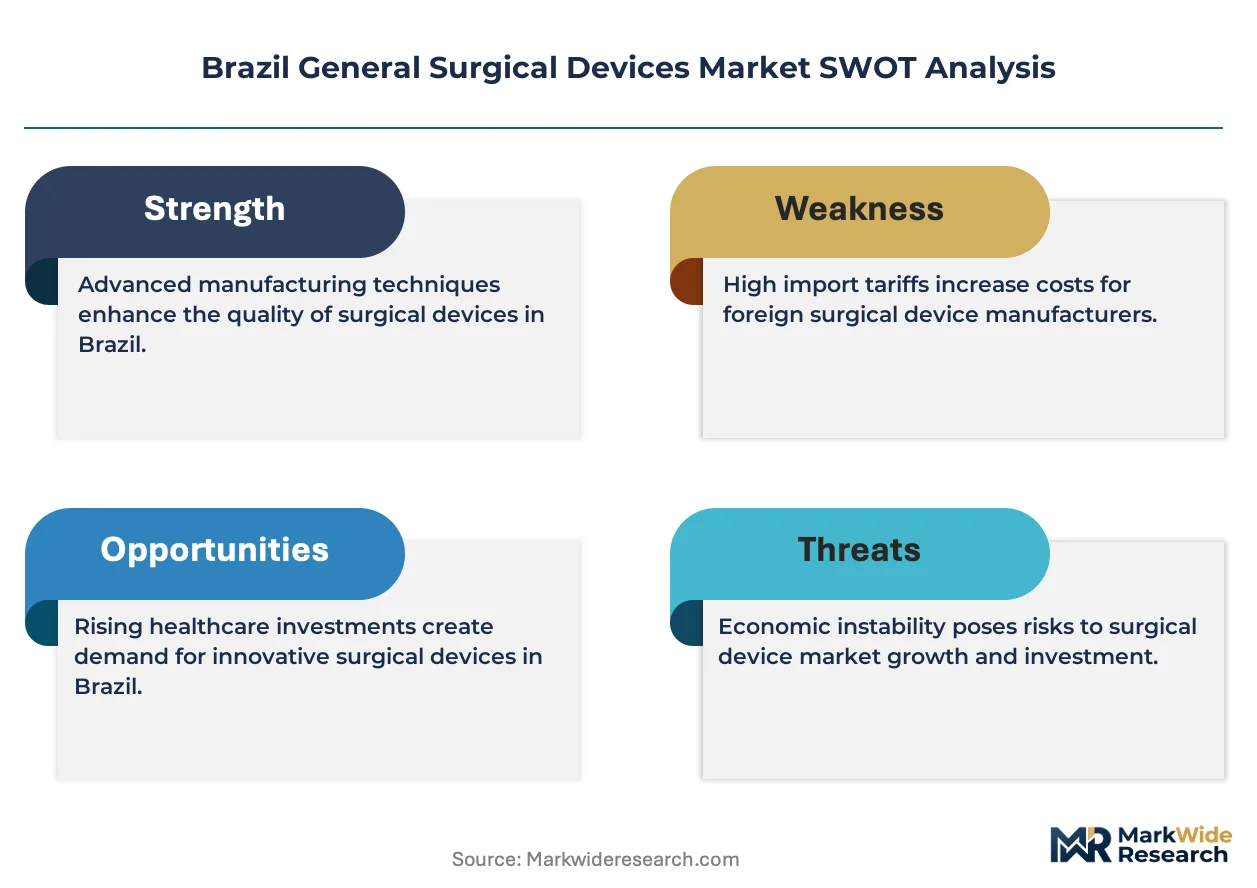
ANVISA governs medical device registration, post-market surveillance, and Good Manufacturing Practice compliance, with recent resolution updates extending conformity assessment timelines for imported class III and IV products. Brazil's national health surveillance agency coordinates with INMETRO for mandatory certification of active surgical equipment, creating dual-track regulatory entry that advantages established suppliers with dedicated local regulatory affairs capacity. Stakeholders must monitor ANVISA's alignment with Mercosur harmonization protocols and the pace of digital submission system modernization to anticipate competitive access shifts.
Market Dynamics
ANVISA's extended conformity assessment timelines for imported class III and IV devices are compressing competitive access windows, forcing suppliers to build dedicated local regulatory affairs capacity or cede share to domestic sterilization service bundlers.
Growth Catalysts
- Unified health system expansion:Brazil's SUS is accelerating public hospital procurement of electrosurgical devices to broaden surgical access across underserved municipalities.
- Minimally invasive technique diffusion:Narrowing performance gaps between imported and domestically sourced instruments are enabling broader adoption across tier-two and tier-three hospital networks.
- São Paulo private hospital corridor concentration:Premium capital budgets at academic medical centers in Rio de Janeiro and São Paulo are absorbing robotic surgery systems at margin-accretive placement rates.
Market Restraints
- Dual-track regulatory entry:ANVISA coordination with INMETRO for mandatory certification of active surgical equipment creates timeline friction that advantages only established suppliers with captive local compliance infrastructure.
- Import dependency for polymer composites:Medical-grade polymer feedstock concentration in external supply chains exposes device manufacturers to input cost volatility and currency fluctuation risk.
- Handheld instrument replacement cycle elongation:Public sector tender structures prioritize lowest acquisition cost over total cost of ownership, stretching stainless steel instrument refresh intervals beyond optimal clinical performance thresholds.
Strategic Opportunities
- Mercosur harmonization alignment:ANVISA's protocol convergence with regional standards creates pathway for Brazil-registered devices to access Argentine and Uruguayan hospital procurement channels without redundant certification.
- Localized sterilization service bundling:Infection control portfolio providers can capture recurring revenue streams by integrating device supply with captive reprocessing infrastructure at multi-hospital systems.
- Energy device and suture convergence:Electrosurgical platform manufacturers can displace standalone wound closure suppliers by integrating advanced hemostasis with absorbable filament delivery systems.
Industry Challenges
- Robotics integration complexity:Academic medical centers face steep learning curves in assimilating spine and joint reconstruction platforms into existing orthopedic service lines, requiring extended proctoring and credentialing cycles.
- Digital submission system modernization lag:ANVISA's incomplete transition to electronic regulatory filing creates documentation bottlenecks that delay market entry for novel device categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil General Surgical Devices Market |
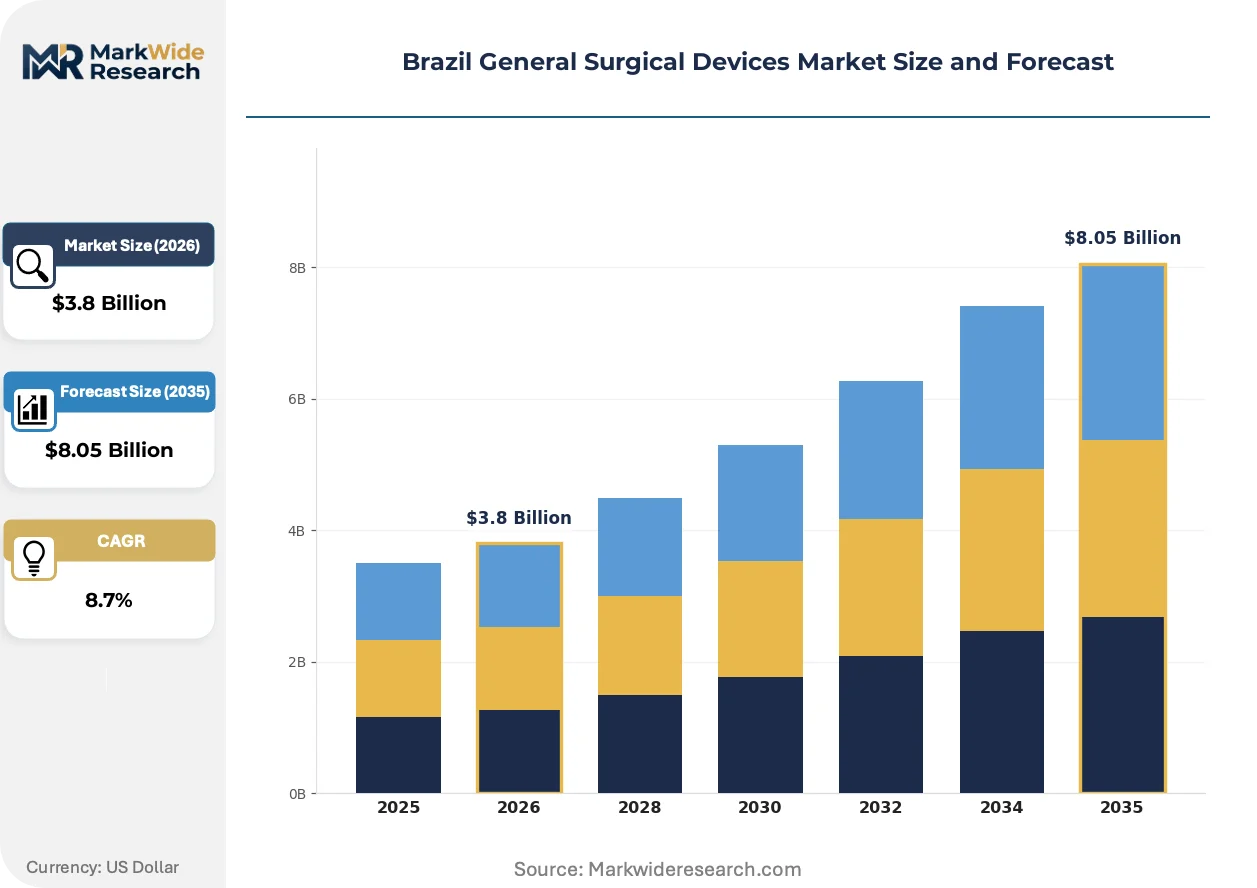
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Sutures, Handheld Surgical Instruments, Electrosurgical Devices, Surgical Drapes End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Technology: Minimally Invasive Techniques, Robotic Surgery, Traditional Surgery, Laparoscopic Procedures Application: Cardiovascular Procedures, Orthopedic Surgery, Neurological Interventions, General Surgery |
| Companies Covered | Stryker, Olympus Corporation, Medtronic, Ovesco Endoscopy AG, Getinge AB, Johnson & Johnson, Boston Scientific Corporation, Biocardio Comércio e Representações Ltda, B. Braun Melsungen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil General Surgical Devices Market Strategic Shifts
Energy delivery systems and operative consumables are undergoing functional convergence, with precision hemostasis technologies reshaping surgical workflow economics across Brazil's stratified hospital tiers.
Electrosurgical generators with integrated vessel sealing is hybridizing radiofrequency and ultrasonic energy modalities into single-platform systems. Tier-one hospitals in São Paulo state are adopting these hybrid platforms to consolidate capital equipment footprints and reduce sterile processing complexity. This convergence is hybridizing procurement categories that previously operated as separate budget lines, compressing vendor count in cardiovascular and orthopedic surgery suites.
ANVISA's updated medical device resolution is extending post-market surveillance requirements for active surgical equipment. Manufacturers must now maintain local adverse event reporting infrastructure and periodic safety update submissions. Class III implantable device suppliers face the steepest compliance cost escalation, driving consolidation among smaller import-dependent distributors unable to sustain dedicated regulatory affairs teams.
Public hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases. State health secretariats in Brazil's northeast and central-west regions are demanding separate pricing for installation, training, and maintenance to improve tender transparency. This unbundling is most visible in Minas Gerais and Bahia, where consolidated purchasing cooperatives are extracting service-level guarantees that were previously embedded in premium device pricing.
Brazil General Surgical Devices Market Segmentation
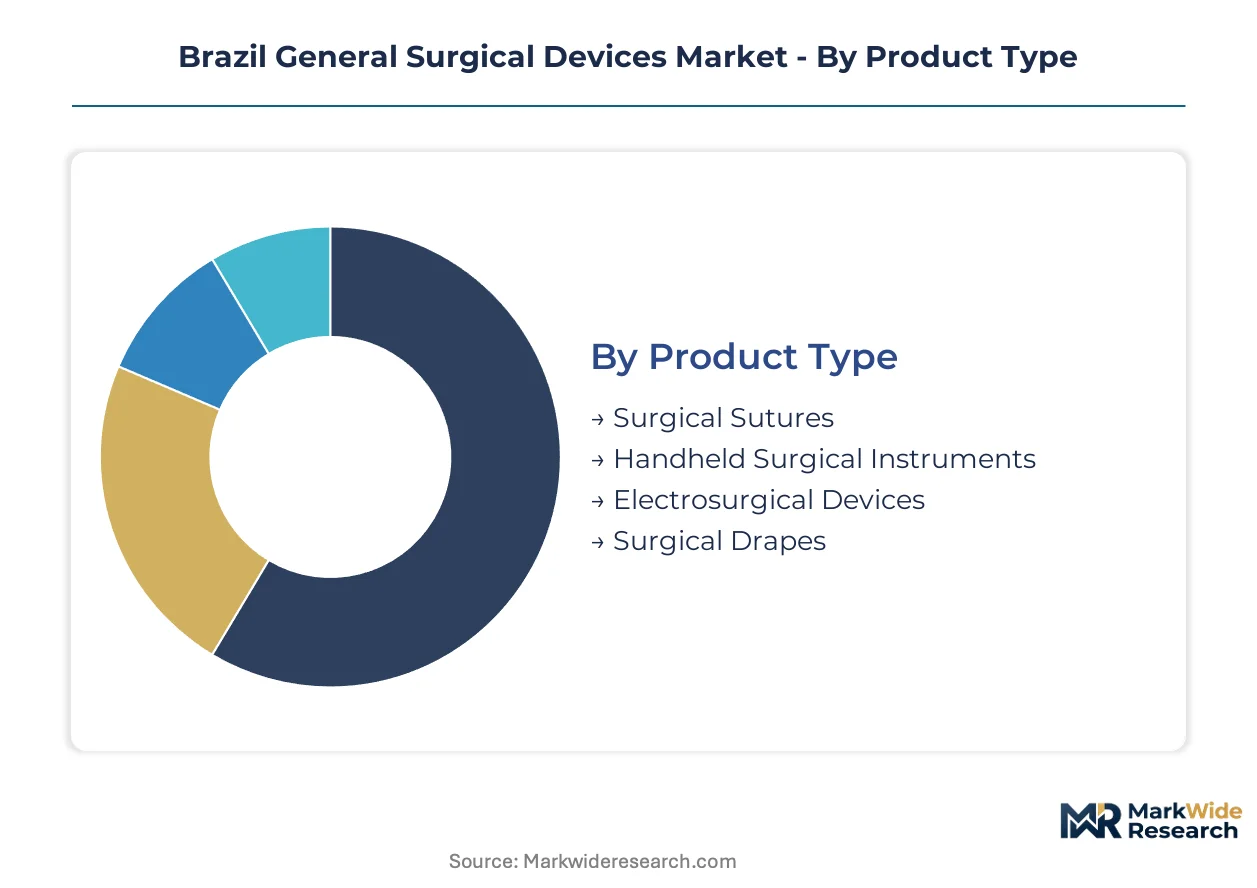
Segmentation in Brazil's general surgical devices market exposes divergent procurement logics across public and private healthcare tiers. Each dimension reveals distinct competitive access pathways shaped by ANVISA regulatory tiers, SUS reimbursement structures, and São Paulo state's concentration of premium capital budgets.
Product Type:
Maturity spreads unevenly across this category, with legacy stainless steel instruments coexisting alongside emerging energy delivery platforms that command disproportionate margin capture.
- Surgical Sutures:Braided absorbable filaments and monofilament non-absorbable threads manufactured from medical-grade polymers and natural materials. Demand concentrates in São Paulo state's private hospital corridor where cardiac and orthopedic service lines absorb premium antimicrobial-coated products despite higher unit economics.
- Handheld Surgical Instruments:Forceps, retractors, scissors, and needle holders forged from medical-grade stainless steel with tungsten carbide inserts. Public sector tenders across Brazil's northeast and central-west regions dominate volume procurement, though extended replacement cycles compress supplier margins below sustainable service bundling thresholds.
- Electrosurgical Devices:Radiofrequency generators and vessel sealing systems enabling precision hemostasis in soft tissue dissection.
- Surgical Drapes:Sterile barrier fabrics and adhesive incise films manufactured from spunbond-meltblown-spunbond polypropylene composites.
Handheld surgical instruments retain volume leadership; electrosurgical devices hold the steepest expansion curve.
End User:
Customer type stratification mirrors Brazil's bifurcated healthcare financing structure, with SUS-funded institutions operating under fundamentally different procurement timelines than privately capitalized facilities.
- Hospitals:Tertiary care institutions spanning public SUS networks, private hospital groups, and academic medical centers in Rio de Janeiro and São Paulo. Public hospital procurement committees in Minas Gerais and Bahia are unbundling after-sales service contracts from capital equipment purchases to improve tender transparency.
- Ambulatory Surgical Centers:Freestanding same-day surgery facilities concentrating cataract, hernia, and arthroscopic procedures. Regulatory alignment with ANVISA's updated resolution is extending conformity assessment timelines for active equipment, favoring established suppliers with captive local compliance infrastructure.
- Specialty Clinics:Single-specialty outpatient facilities performing dermatologic, ophthalmologic, and gastroenterologic interventions.
- Research Laboratories:Academic and industry R&D facilities engaged in preclinical device validation and surgical technique development.
Hospitals retain volume leadership; ambulatory surgical centers hold the steepest expansion curve.
Technology:
Volume concentration tilts toward established open surgery platforms while margin accretion concentrates in capital-intensive robotic installations requiring extended proctoring cycles.
- Minimally Invasive Techniques:Percutaneous and endoscopic approaches reducing tissue trauma through smaller access ports. Tier-two and tier-three hospital networks across Brazil's southeast corridor are adopting these platforms as performance gaps narrow between imported and domestically sourced instrumentation.
- Robotic Surgery:Computer-assisted telemanipulation systems enabling precision in spine and joint reconstruction procedures. Academic medical centers in São Paulo state absorb these systems at margin-accretive placement rates despite steep learning curves in orthopedic service line integration.
- Traditional Surgery:Open operative approaches utilizing direct anatomical visualization and manual tissue manipulation.
- Laparoscopic Procedures:Video-assisted abdominal and pelvic surgery through trocar-based instrument access.
Traditional surgery retains volume leadership; robotic surgery holds the steepest expansion curve.
Application:
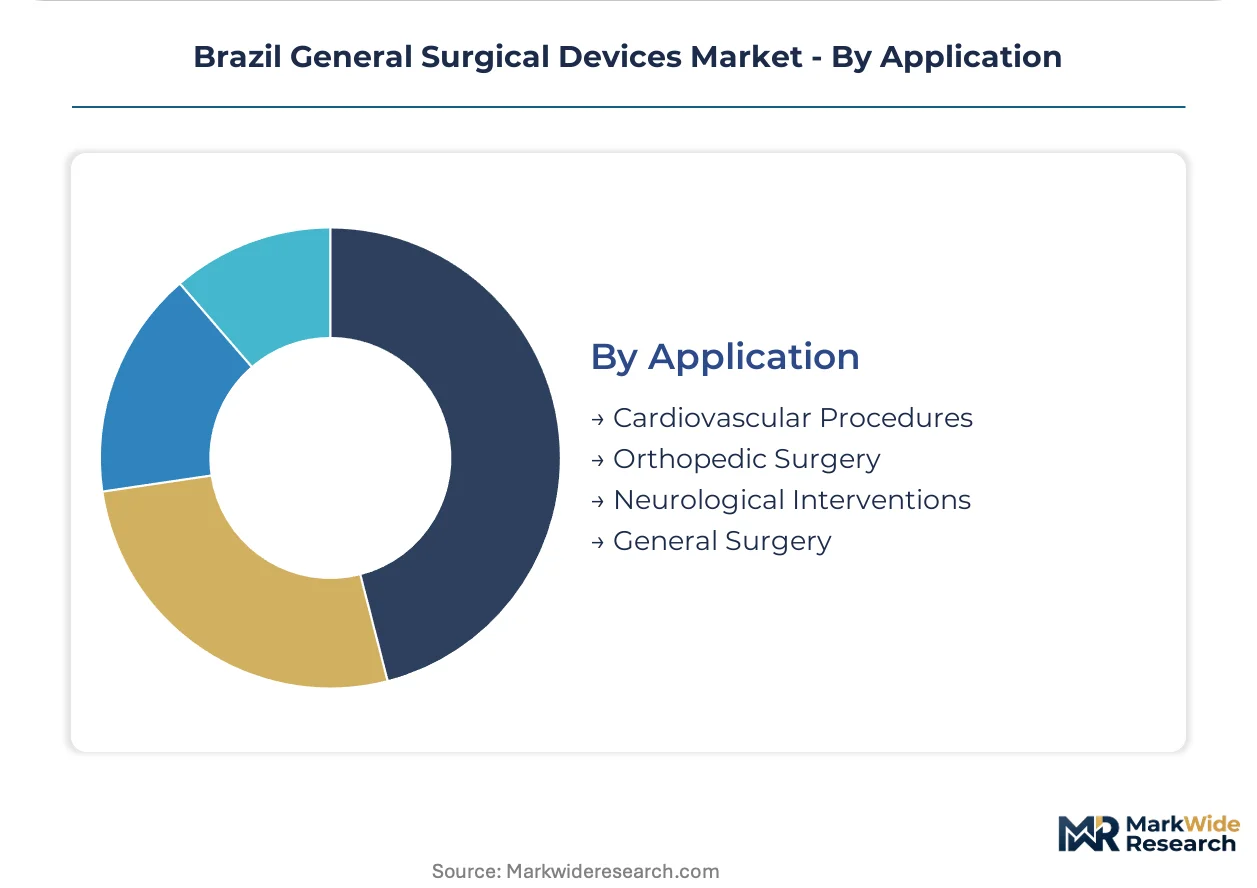
Procedure type segmentation reflects cardiovascular and orthopedic service line expansion as Brazil's aging population and SUS access broadening reshape surgical demand profiles.
- Cardiovascular Procedures:Coronary artery bypass grafting, valve repair, and electrophysiological interventions requiring precision energy delivery. Electrosurgical device placement in these applications commands premium positioning where reduced perioperative blood loss justifies higher capital expenditure.
- Orthopedic Surgery:Joint reconstruction, spine fusion, and trauma fixation procedures. Hybrid energy platforms consolidating radiofrequency and ultrasonic modalities are penetrating São Paulo tier-one hospitals seeking to reduce sterile processing complexity.
- Neurological Interventions:Cranial and spinal procedures addressing tumor, vascular, and degenerative conditions.
- General Surgery:Abdominal, thoracic, and soft tissue procedures spanning hernia repair, cholecystectomy, and appendectomy.
General surgery retains volume leadership; cardiovascular procedures hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German electrosurgical device manufacturers export precision energy systems to São Paulo's private hospital corridor, while domestic sterilization service providers in Minas Gerais capture recurring revenue through localized infrastructure bundling.
São Paulo
Academic medical centers in São Paulo state absorb robotic surgery systems at margin-accretive placement rates. ANVISA's extended conformity assessment timelines for imported class III devices compress competitive access windows for capital equipment suppliers. The São Paulo private hospital corridor concentrates premium minimally invasive equipment purchases as cardiac and orthopedic service lines expand surgical capacity.
Minas Gerais
Consolidated purchasing cooperatives in Minas Gerais extract service-level guarantees previously embedded in premium device pricing. State health secretariats unbundle after-sales service contracts from capital equipment purchases to improve tender transparency. Belo Horizonte's multi-hospital systems drive demand for localized sterilization service bundling that integrates device supply with captive reprocessing infrastructure.
Bahia
Public hospital procurement committees in Bahia prioritize lowest acquisition cost over total cost of ownership in handheld instrument tenders. Brazil's unified health system expansion accelerates electrosurgical device procurement across underserved municipalities in the state's interior. Salvador's tertiary care institutions anchor northeast regional demand for precision hemostasis technologies in cardiovascular procedures.
Rio de Janeiro
Academic medical centers in Rio de Janeiro face steep learning curves assimilating spine and joint reconstruction platforms into existing orthopedic service lines. ANVISA coordination with INMETRO for mandatory certification of active surgical equipment creates timeline friction that advantages established suppliers. The metropolitan corridor's tier-one hospitals adopt hybrid energy platforms consolidating radiofrequency and ultrasonic modalities to reduce sterile processing complexity.
Rio Grande do Sul
Porto Alegre's hospital networks exhibit extended replacement cycles for stainless steel instruments as public sector tender structures stretch refresh intervals. The state's southern location exposes device distributors to import dependency risks for medical-grade polymer feedstocks. Regional purchasing cooperatives negotiate separate pricing for installation, training, and maintenance to improve capital equipment tender transparency.
Brazil General Surgical Devices Market Competitive Environment
Channel-controlling players compete with product-specialist players across Brazil's stratified procurement tiers. The market structure concentrates around established multinational suppliers with dedicated local regulatory affairs capacity and domestic sterilization service bundlers capturing recurring revenue streams. Three archetypes dominate: robotics-anchored platform providers, energy device direct sales operators, and localized infection control portfolio bundlers. Competitive moves center on strategic partnerships with multi-hospital systems and portfolio diversification into convergent hemostasis-suture delivery systems.
Among US-based multinationals, Stryker and Medtronic occupy positions as robotics-anchored and energy device archetypes respectively, while Germany's B. Braun Melsungen AG exemplifies the localized sterilization service bundler model. These three companies represent distinct competitive vectors: Stryker anchors high-value spine and joint reconstruction procedures through platform dominance, Medtronic sustains deep catheter and energy device penetration via direct sales team coverage of Brazil's southeast corridor, and B. Braun differentiates through integrated reprocessing infrastructure at multi-hospital systems. Their collective positioning illustrates how regulatory compliance scale and service bundling depth determine access to Brazil's bifurcated public-private procurement channels.
| Leading Market Players |
|---|
| Stryker |
| Olympus Corporation |
| Medtronic |
| Ovesco Endoscopy AG |
| Getinge AB |
| Johnson & Johnson |
| Boston Scientific Corporation |
| Biocardio Comércio e Representações Ltda |
| B. Braun Melsungen AG |
| Others |
Value Chain & Pricing Dynamics
The Santos-Guarulhos freight corridor's escalating container handling costs are compressing margins for imported electrosurgical generators while amplifying price differentiation between ANVISA-certified premium devices and unbundled economy alternatives across Brazil's hospital procurement tiers.
Pricing Analysis
Cost-plus contracts with Brazilian real-US dollar indexation dominate capital equipment procurement, insulating multinational suppliers from currency volatility while exposing domestic distributors to margin erosion. Price differentiation rests on ANVISA registration tier and after-sales service bundling depth, with São Paulo private hospitals absorbing premium positioning for robotic platforms. Cost compression in handheld instrument tenders is intensifying as Minas Gerais purchasing cooperatives unbundle installation and maintenance pricing. Public sector SUS-funded institutions exhibit highest price sensitivity; academic medical centers in Rio de Janeiro demonstrate lowest sensitivity due to research grant offsets.
Supply Chain Analysis
Contract manufacturing for polymer suture filaments concentrates in Germany, the United States, and Costa Rica, with limited Brazilian domestic capacity for medical-grade polymer extrusion. Raw material dependencies span medical-grade stainless steel from Italian forges, braided absorbable polymers from German chemical specialists, and electrosurgical generator components from Malaysian electronics assembly hubs. Single-source vulnerability runs through German electrosurgical device suppliers serving São Paulo's tier-one hospitals. Distribution runs through hospital purchasing cooperatives in Minas Gerais and Bahia, with direct sales teams covering Rio de Janeiro and São Paulo academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's general surgical devices market demands substitution defense against convergent hemostasis-suture delivery systems that threaten standalone wound closure suppliers. Incumbents must navigate regulatory compliance scale as the primary barrier to entrenchment.
For Market Incumbents: Build regulatory affairs capacity moats by embedding dedicated ANVISA liaison teams within São Paulo and Rio de Janeiro operations. Consolidate sterilization service infrastructure across multi-hospital systems in Minas Gerais to capture recurring revenue streams. Vertical integration into polymer suture filament sourcing hedges import dependency exposure from German supply concentration. Channel control through GPO contract exclusivity at Bahia public purchasing cooperatives defends volume position against emerging domestic sterilization bundlers. For New Entrants and Emerging Players: Brazil's central-west region exhibits underpenetration for minimally invasive technique platforms as tier-two hospitals in Goiás and Mato Grosso delay capital refresh cycles. Target ambulatory surgical centers in Brasília's private corridor with leasing-structured electrosurgical generator placements to bypass upfront capital barriers. Service bundling integration—combining device supply with localized sterilization infrastructure—offers the most penetrable go-to-market angle against established multinational direct sales coverage. For Investors and Strategic Acquirers: Domestic sterilization service providers with captive ANVISA regulatory affairs infrastructure represent the priority acquisition archetype for portfolio exposure to Brazil's SUS expansion. Long-term viability hinges on Mercosur harmonization completion enabling Argentine and Uruguayan market access without redundant certification investment. Watch ANVISA's digital submission system modernization pace as the inflection signal—accelerated electronic filing would compress competitive access windows for import-dependent distributors and favor regulatory-scale incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Registration Acceleration | Compressed timelines for class III device entry favor established suppliers with captive regulatory infrastructure in São Paulo. |
| Hospital System Partnership | Multi-hospital alliances in Minas Gerais enable sterilization service bundling that locks in recurring device revenue streams. |
| Backward Integration into Polymer Supply | In-house medical-grade filament production mitigates currency exposure from German and Costa Rican import dependency. |
| Software Companion Development | Integrated energy delivery platforms with procedure-specific algorithms differentiate hybrid electrosurgical systems in cardiovascular applications. |
| Reimbursement Strategy Alignment | SUS procedure code expansion for minimally invasive techniques accelerates adoption across Brazil's northeast and central-west corridors. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ANVISA registration databases, hospital procurement records, and INMETRO certification filings to establish baseline market sizing and competitive positioning. Primary interviews engaged biomedical engineers at São Paulo academic medical centers, purchasing committee directors at Minas Gerais multi-hospital systems, regulatory affairs leads at multinational device manufacturers, and GPO contracts managers across Bahia and Rio Grande do Sul. Secondary validation drew from ANVISA resolution updates, SUS reimbursement bulletins, and customs import records for electrosurgical device categories. Bottom-up hospital procurement analysis triangulates against top-down manufacturer shipment data to constrain estimate variance.
Forecast inputs span procedure volume trajectories across cardiovascular, orthopedic, and general surgery service lines, technology adoption curves for robotic and minimally invasive platforms, and ANVISA regulatory timeline scenarios. Segmentation modeling incorporates product type tiering, end-user facility classification, technology deployment mode, and application-specific procedure growth. CAGRs derive from logarithmic trend fitting across historical procurement patterns and projected SUS access expansion. Industry-specific inputs include ANVISA-Mercosur harmonization implementation pace and electrosurgical device replacement cycle compression at tier-one hospitals.
The forecast holds incumbent behavior within observed patterns; aggressive moves by domestic sterilization service bundlers or accelerated ANVISA digital modernization would shift outcomes beyond modeled ranges. Currency volatility in Brazilian real-US dollar exchange rates and polymer feedstock cost inflation represent primary revision risks for import-dependent device categories. Quarterly review of ANVISA registration approval timelines and SUS procedure reimbursement updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Surgical Hemostats Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
Global Gastroenterology Ambulatory Surgery Center Market
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Global Surgical Retractor Market
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
Surgical Retainers Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Iraq Healthcare (Surgical Procedures) Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Europe General Surgical Devices Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Middle East and Africa Lancet and Pen Needles Market
Surgical Instruments
Global Surgical Catheters Market
Surgical Instruments
Cleft Lip and Palate Repair Surgical Instrument Package Market