
 Europe General Surgical Devices Market | 2026-2036
Europe General Surgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe General Surgical Devices Market Foresight
A capital-intensity divergence between high-volume manufacturers and precision instrument specialists is reorganizing competitive dynamics across Europe. Medtronic plc leverages its integrated supply chain to sustain cost advantages in electrosurgical device production at scale. B. Braun SE anchors its position through deep specialization in suture and infusion technologies across German and Swiss manufacturing bases. Karl Storz SE & Co. KG competes on optical precision, dominating rigid endoscope supply for minimally invasive procedures.
General surgical devices encompass handheld instruments, powered equipment, and consumables manufactured from medical-grade stainless steel, titanium alloys, and polymer composites, sterilized for single or repeated use in operative interventions. Electrosurgical devices and minimally invasive surgery platforms command expanding margin pools as hospitals prioritize energy-based tissue management and reduced postoperative recovery times. Surgical instruments and sutures retain volume leadership but face pricing pressure from consolidated procurement frameworks, while robotic-assisted surgery delivery modes attract capital investment despite longer payback periods.
The EU Medical Device Regulation and CE marking framework enforced by national competent authorities reshape product registration timelines and clinical evidence requirements across member states. EMA coordination with notified bodies elevates quality system standards, filtering smaller manufacturers from premium hospital supply chains. Stakeholders must monitor reimbursement divergence between national health systems as robotic and laparoscopic modalities spread beyond academic institutions into community hospital settings.
Market Dynamics
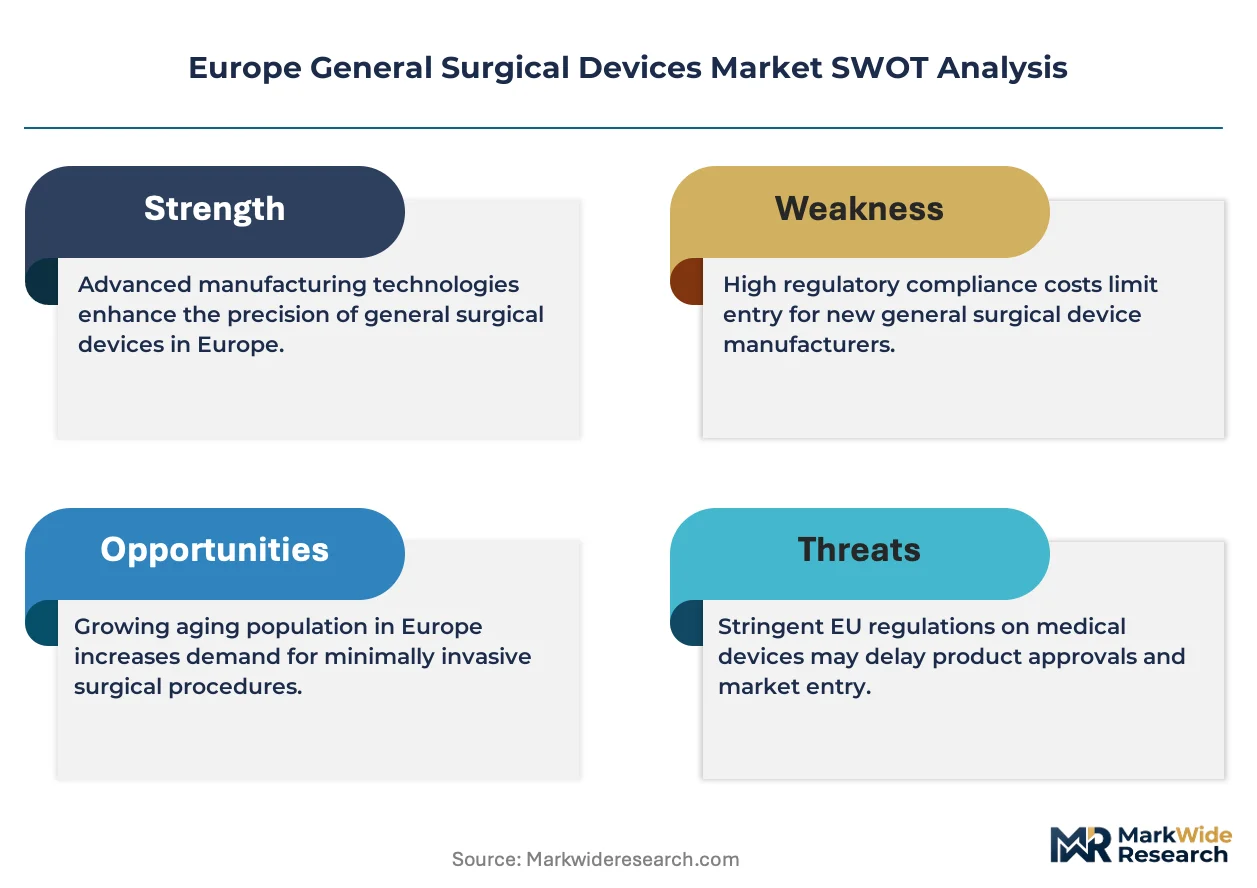
The EU Medical Device Regulation (MDR) is compressing product registration timelines and elevating clinical evidence requirements, forcing manufacturers to restructure quality systems and consolidate notified body relationships across member states.
Growth Catalysts
- Outpatient Surgery Center Expansion:France and Italy are maturing networks of ambulatory surgical centers that prioritize minimally invasive platforms and same-day discharge protocols.
- EMA-Notified Body Coordination:Enhanced quality system standards under the MDR framework are filtering subscale manufacturers from premium hospital supply chains, creating procurement consolidation benefits for compliant suppliers.
- Electrosurgical Energy Adoption:German hospitals are expanding capital procurement of energy-based tissue management systems amid compliance-driven equipment refresh cycles.
Market Restraints
- Medical-Grade Stainless Steel Input Volatility:Surgical instrument manufacturers face margin pressure from fluctuating alloy feedstock costs and energy-intensive sterilization logistics.
- Notified Body Capacity Bottleneck:Concentration of EU-authorized conformity assessment bodies in Germany and the Netherlands creates certification queue delays for new market entrants.
- Reusable Instrument Durability Limits:Polymer composite and titanium alloy alternatives face adoption barriers from established sterilization workflows and capital depreciation schedules.
Strategic Opportunities
- Polish and Romanian Hospital Modernization:Central and Eastern European member states are channeling EU cohesion funds into surgical infrastructure upgrades with preference for CE-marked electrosurgical platforms.
- Robotic-Assisted Surgery Diffusion:Community hospital settings beyond academic medical centers present untapped demand for capital-efficient laparoscopic and robotic delivery modes.
- CSRD Supply Chain Disclosure:The EU Corporate Sustainability Reporting Directive creates competitive differentiation for manufacturers with documented carbon footprint reduction across German and Swiss production bases.
Industry Challenges
- Clinical Evidence Generation Timeline:MDR-mandated post-market surveillance and PMCF study requirements extend product launch cycles by 18-24 months for novel surgical devices.
- Cross-Border Regulatory Divergence:National competent authorities in France, Germany, and Italy apply inconsistent reimbursement coding for robotic-assisted procedures, complicating commercialization strategy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe General Surgical Devices Market |
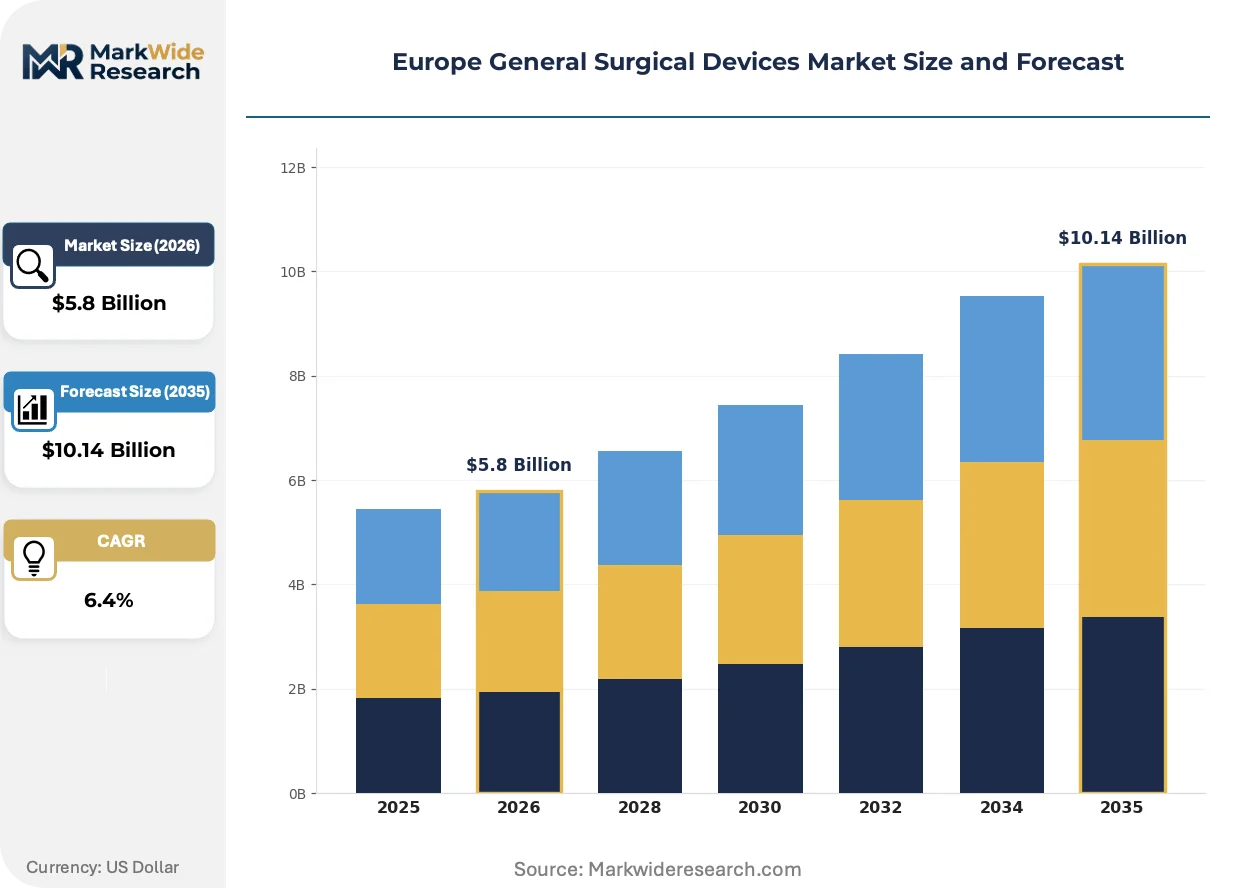
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Electrosurgical Devices, Sutures, Surgical Implants Application: Cardiovascular Surgery, Orthopedic Surgery, Neurosurgery, General Surgery End User: Hospitals, Outpatient Surgery Centers, Specialty Clinics, Academic Institutions Delivery Mode: Open Surgery, Minimally Invasive Surgery, Robotic-Assisted Surgery, Laparoscopic Surgery |
| Companies Covered | Medtronic plc, Johnson & Johnson, Stryker Corporation, Boston Scientific Corporation, B. Braun SE, Olympus Corporation, Smith & Nephew PLC, Conmed Corporation, Karl Storz SE & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe General Surgical Devices Market Shifts & Advancements
Energy-based tissue management and optical precision systems are displacing conventional mechanical instruments across European operative settings, while regulatory disclosure mandates reshape supplier qualification criteria.
Single-use electrosurgical pencils and dispersive electrodes are miniaturizing component geometries to enable compatibility with robotic instrument arms and narrow-access laparoscopic ports. German outpatient surgery centers are adopting these platforms at accelerated replacement cycles compared to reusable alternatives. This miniaturization is compressing aftermarket service revenue pools while expanding consumable attach rates per procedure.
The EU MDR's Unique Device Identification (UDI) mandate and Eudamed database integration requirements are forcing manufacturers to restructure labeling, traceability, and post-market surveillance systems. Industrial consequence includes elevated documentation burdens and third-party audit frequency for Class IIa and IIb surgical devices. Electrosurgical generator and active electrode segments are responding by consolidating product portfolios to reduce SKU complexity and compliance overhead.
Hospital procurement consortia in France and Italy are unbundling after-sales service contracts from capital equipment purchases, shifting toward performance-based maintenance agreements with penalty clauses for device downtime. Distributors and manufacturer direct-sales teams face margin compression as buyers centralize vendor management through regional purchasing organizations. This behavioral shift is most visible in Lombardy and Ile-de-France health system tenders, where total cost-of-ownership scoring dominates award criteria over upfront capital outlay.
Europe General Surgical Devices Market Segmentation
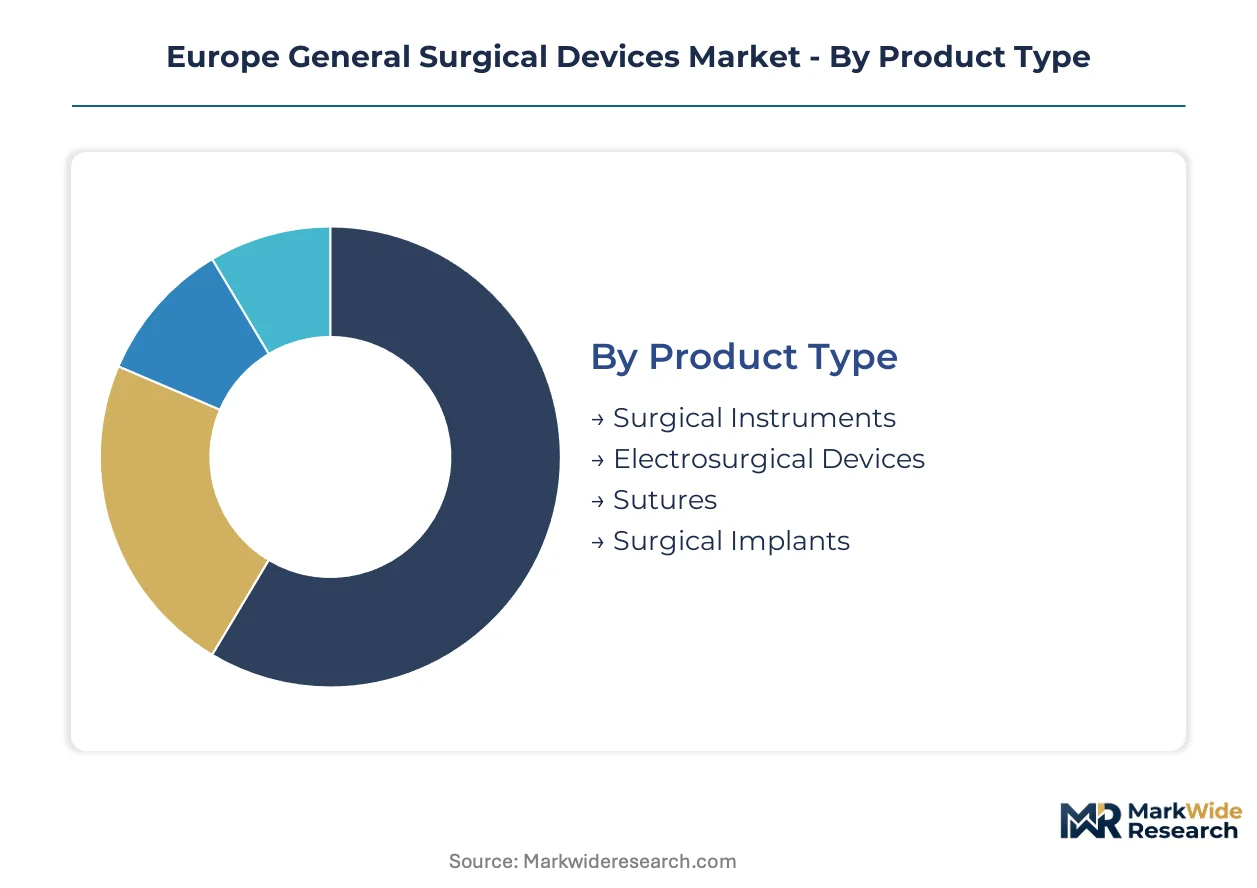
Segmentation in the Europe General Surgical Devices Market reveals how regulatory tiering under the EU MDR reshapes competitive access across product categories. CE marking classification and post-market surveillance obligations create divergent margin structures that manufacturers must navigate through portfolio prioritization.
Product Type:
EU MDR risk classification stratifies clinical evidence burdens and notified body engagement intensity across instrument categories.
- Surgical Instruments:Medical-grade stainless steel and titanium alloy constructs dominate forceps, retractors, and scalpels. German university hospitals drive premium instrument procurement amid MDR-mandated quality system upgrades that filter non-compliant suppliers from tender shortlists.
- Electrosurgical Devices:Energy-based tissue management systems integrate generator units with active electrodes and return pads. French outpatient surgery centers in Ile-de-France accelerate capital refresh cycles for these platforms to support same-day discharge protocols and reduced thermal injury rates.
- Sutures:Absorbable and non-absorbable polymer and natural fiber wound closure products. B. Braun SE's German and Swiss manufacturing bases anchor European supply.
- Surgical Implants:Permanent and resorbable devices for structural support and tissue replacement. Extended PMCF study timelines under MDR Article 74 delay market entry for novel biocompatible materials.
Established volume favors surgical instruments; emerging adoption favors electrosurgical devices.
Application:
Procedure complexity and reimbursement coding differentiation concentrate capital allocation across surgical specialties.
- Cardiovascular Surgery:Sternotomy instruments, cardiopulmonary bypass equipment, and vascular closure systems. Italian Lombardy health system tenders prioritize total cost-of-ownership scoring for these high-acuity procedures.
- Orthopedic Surgery:Joint replacement instruments, trauma fixation devices, and arthroscopy platforms. Polish hospital modernization programs channel EU cohesion funds into orthopedic infrastructure upgrades.
- Neurosurgery:Precision cranial access instruments and neural monitoring equipment. Steep learning curves and capital intensity constrain diffusion beyond academic medical centers in Germany and Switzerland.
- General Surgery:Broad-spectrum instruments for abdominal, thoracic, and soft tissue procedures. Community hospital procurement consortia in France unbundle service contracts from equipment purchases in this high-volume segment.
Orthopedic surgery commands capital intensity; general surgery drives procedure volume scale.
End User:
Facility type determines capital availability, sterilization workflow configuration, and preference for reusable versus single-use platforms.
- Hospitals:Integrated surgical departments with centralized sterilization services and multi-specialty instrument inventories. German hospital procurement frameworks under the Hospital Structures Act consolidate vendor relationships toward MDR-compliant suppliers with documented quality systems.
- Outpatient Surgery Centers:Ambulatory facilities optimized for same-day discharge and rapid instrument turnover. French and Italian networks mature these settings toward minimally invasive platform adoption with accelerated replacement cycles for consumables.
- Specialty Clinics:Focused surgical practices in ophthalmology, dermatology, or dental specialties. Narrow procedure scope enables standardized instrument portfolios with reduced SKU complexity.
- Academic Institutions:Teaching hospitals with research mandates and robotic surgery training programs. Cross-border regulatory divergence in robotic procedure reimbursement coding complicates commercialization strategy across France, Germany, and Italy.
Hospitals anchor reusable instrument demand; outpatient surgery centers expand single-use attach rates.
Delivery Mode:
Access technique selection reshapes instrument geometry requirements and capital equipment depreciation schedules.
- Open Surgery:Conventional incision-based procedures with direct tissue visualization. Established sterilization workflows and instrument durability standards sustain volume in emergency and complex reconstructive settings.
- Minimally Invasive Surgery:Reduced-access techniques through natural orifices or small incisions. Karl Storz SE's optical precision systems dominate rigid endoscope supply for these procedures across European operative settings.
- Robotic-Assisted Surgery:Computer-enhanced instrument control with tremor filtration and motion scaling. Community hospital settings beyond academic centers present untapped demand despite longer capital payback periods.
- Laparoscopic Surgery:Abdominal and pelvic procedures via trocar access with camera guidance. Single-use electrosurgical pencil miniaturization enables compatibility with narrow-access ports in German outpatient centers.
Open surgery retains emergency volume; robotic-assisted surgery climbs the fastest in capital investment priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss manufacturing clusters while Italian and French procurement consortia extract vendor concessions through centralized tendering. This asymmetry reshapes competitive access across the continent.
Germany
Hospital procurement frameworks under the Hospital Structures Act consolidate vendor relationships toward MDR-compliant suppliers with documented quality systems. The KBA and BfArM coordinate with notified bodies to elevate sterilization and traceability standards. Bavarian and Baden-Württemberg manufacturing bases anchor electrosurgical generator production for European export.
France
Ile-de-France health system tenders prioritize total cost-of-ownership scoring over upfront capital outlay, compressing margins for instrument suppliers. ANSM enforces post-market surveillance alignment with EMA-coordinated quality protocols. Auvergne-Rhône-Alpes clusters concentrate minimally invasive platform adoption in outpatient surgery networks.
Italy
Lombardy procurement consortia unbundle after-sales service contracts from equipment purchases, shifting toward performance-based maintenance agreements. The Ministry of Health applies national reimbursement coding that diverges from German and French frameworks. Emilia-Romagna and Veneto manufacturing districts sustain precision instrument subcontracting for premium surgical device brands.
United Kingdom
NHS Supply Chain consolidation filters non-compliant suppliers from tender shortlists as MHRA aligns with retained EU MDR provisions post-Brexit. The UK Health Security Agency coordinates infection control standards that elevate single-use platform preference. Greater London and Midlands hospital trusts drive capital refresh cycles for energy-based tissue management systems.
Switzerland
Swissmedic maintains autonomous device authorization while recognizing CE marking for EU market access, creating dual compliance pathways for manufacturers. Cantonal hospital procurement in Zurich and Geneva favors precision optical systems for minimally invasive procedures. Basel and Bern industrial clusters specialize in suture and infusion technologies with carbon footprint documentation under emerging CSRD-aligned disclosure.
Europe General Surgical Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European surgical device sector. Integrated multinationals with captive manufacturing dominate electrosurgical and powered equipment segments, while precision instrument specialists retain defensible positions in optical and hand-held categories. Three archetypes structure competition: scale-driven systems integrators, deep-specialization mid-caps, and regional fabrication clusters serving private-label channels. Consolidation pressure operates through M&A targeting notified body relationships and geographic expansion into Central and Eastern European procurement frameworks.
Among diversified healthcare conglomerates, Medtronic plc and Johnson & Johnson occupy positions spanning electrosurgical systems and broad surgical portfolios. B. Braun SE anchors the specialization tier through German and Swiss manufacturing concentration in suture and infusion technologies. Karl Storz SE & Co. KG exemplifies the precision-optical archetype, with its corporate structure reflecting family-owned continuity in rigid endoscope supply. These three entities represent distinct competitive vectors: scale integration, manufacturing depth, and optical engineering heritage.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson |
| Stryker Corporation |
| Boston Scientific Corporation |
| B. Braun SE |
| Olympus Corporation |
| Smith & Nephew PLC |
| Conmed Corporation |
| Karl Storz SE & Co. KG |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with German and Swiss electrosurgical component manufacturers lock in supply access for premium-tier hospitals while freezing price visibility across MDR compliance cycles. These contracts tether procurement consortia to fixed-volume commitments that insulate against medical-grade stainless steel volatility.
Pricing Analysis
Configured-to-order pricing for robotic instrument arms and customized electrosurgical generators commands a 40-60% premium over standard catalog configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking classification and PMCF documentation depth. Cost compression in standard-tier forceps and retractors is intensifying because consolidated procurement frameworks in Lombardy and Ile-de-France extract volume discounts. Community hospital procurement committees demonstrate highest price sensitivity; academic medical centers with research budgets exhibit lowest.
Supply Chain Analysis
Germany and Switzerland anchor electrosurgical generator and precision optical system production for European hospital supply. Medical-grade stainless steel feedstock draws from Swedish and Finnish alloy mills; polymer composites for single-use electrodes hinge on Dutch and Belgian petrochemical clusters. Single-source vulnerability concentrates in notified body relationships, with German and Dutch conformity assessment bodies controlling certification queues. Distribution runs through regional purchasing organizations that consolidate vendor management across hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based maintenance agreements with penalty clauses for device downtime represent a service-attach layer expanding faster than capital equipment hardware across French and Italian procurement frameworks.
For Market Incumbents: Fortify notified body relationships and CE marking portfolio breadth to defend against MDR-driven supplier filtering. Consolidate quality system documentation across German and Swiss manufacturing bases to reduce audit frequency burdens. Deepen backward integration into medical-grade stainless steel processing to offset alloy feedstock volatility. For New Entrants and Emerging Players: Differentiate on carbon footprint documentation aligned with CSRD supply chain disclosure mandates. Target Polish and Romanian hospital modernization programs channeling EU cohesion funds into surgical infrastructure. Pursue private-label partnerships with Emilia-Romagna precision instrument subcontractors as a capital-efficient go-to-market angle. For Investors and Strategic Acquirers: Precision-optical mid-caps with rigid endoscope specialization and family-owned governance structures offer acquisition exposure to minimally invasive surgery platform adoption. Long-term viability hinges on robotic-assisted surgery diffusion beyond academic centers into community hospital settings. Watch for inflection in reimbursement coding harmonization across French, German, and Italian national health systems.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR Article 74 compliance accelerates market access for Class IIb surgical devices in German hospital tenders. |
| Hospital System Partnership | Regional purchasing organization alignment in Lombardy secures multi-year electrosurgical platform supply contracts. |
| Software Companion Development | Electrosurgical generator connectivity modules enable remote monitoring compliance with Eudamed traceability mandates. |
| Reimbursement Strategy | Robotic procedure coding harmonization across ANSM, BfArM, and AIFA unlocks community hospital capital allocation. |
| Backward Integration | In-house polymer composite extrusion for single-use electrodes reduces sterilization logistics dependency and margin pressure. |
Research Methodology
Operator-level perspectives from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and notified body audit specialists anchored the qualitative base. Primary interview insights combined with secondary validation from Eudamed device registration data, hospital procurement tender databases, GPO contract disclosure filings, and CE marking certification records. Bottom-up procedure volume modeling and top-down manufacturing capacity assessment enabled triangulation across market sizing approaches.
Sensitivity analysis tested forecast outputs against variable assumptions for MDR implementation pace, outpatient surgery center expansion rates, and robotic-assisted surgery reimbursement adoption. Segmentation dimensions modeled include product risk classification under EU MDR, delivery mode technique, end-user facility type, and application specialty across the projection horizon. CAGRs derived from weighted procedure volume growth and capital equipment replacement cycle analysis, with electrosurgical energy adoption curves and single-use platform penetration serving as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU MDR enforcement and CE marking recognition across Swissmedic and MHRA alignment; material policy shifts would require re-modeling. Assumptions reflect current notified body capacity constraints and EU cohesion fund allocation patterns for Central and Eastern European hospital infrastructure. Recalibration cycles align with material shifts in MDR post-market surveillance requirements and national reimbursement coding updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Absorbable Sutures Market
Surgical Instruments
Ultrasound Needle Guides Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Europe Minimally Invasive Surgery Market
Surgical Instruments
Surgical Headband Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Colorectal Procedure Market
Surgical Instruments
Endoluminal Suturing Devices Market
Surgical Instruments
Global Surgical Instruments Market
Surgical Instruments
GCC Minimally Invasive Surgery Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Surgical Blades Market
Surgical Instruments
Disposable Ophthalmic Surgical Products Market
Surgical Instruments
Global Laparoscopic Instruments Market
Surgical Instruments
Global Plastic Surgery Instruments Market
Surgical Instruments
Ultrasonic Scissors Market