
 Gum Rosin Market | 2026-2036
Gum Rosin Market Size, Share, and Industry Trends Forecast 2026-2036
Gum Rosin Market Intelligence
The demand profile for gum rosin is hardening around high-performance adhesives and bio-based coatings, shifting away from legacy printing ink applications. Arakawa Chemical Industries, Ltd. leverages its strong R&D in synthetic resin modification to capture this value migration. Harima Chemicals Group, Inc. specializes in pine-chemical derivatives for electronics and adhesives. Meanwhile, Wuzhou Sun Shine Forestry and Chemicals Co., Ltd dominates raw colophony extraction, anchoring a significant portion of the primary supply chain.
Gum rosin is a solid, translucent resin obtained by distilling the oleoresin harvested from living pine trees. Its primary functional characteristic is determined by its acid number, which dictates its suitability as a tackifier in adhesives or an emulsifier in other formulations. Rosin esters represent a higher-value product category, offering improved thermal stability for demanding applications. The adhesives segment, particularly for packaging and construction, constitutes the largest and most significant application area for these materials.
Regulatory frameworks significantly influence market access and product chemistry. The European Union's REACH regulation imposes stringent registration and evaluation requirements for all chemical substances. In China, national GB standards dictate quality and safety for industrial materials, while in the United States, the EPA monitors volatile organic compounds in end-products like coatings. Stakeholders must now navigate the diverging requirements for bio-based content verification across key consumer markets.
Market Dynamics
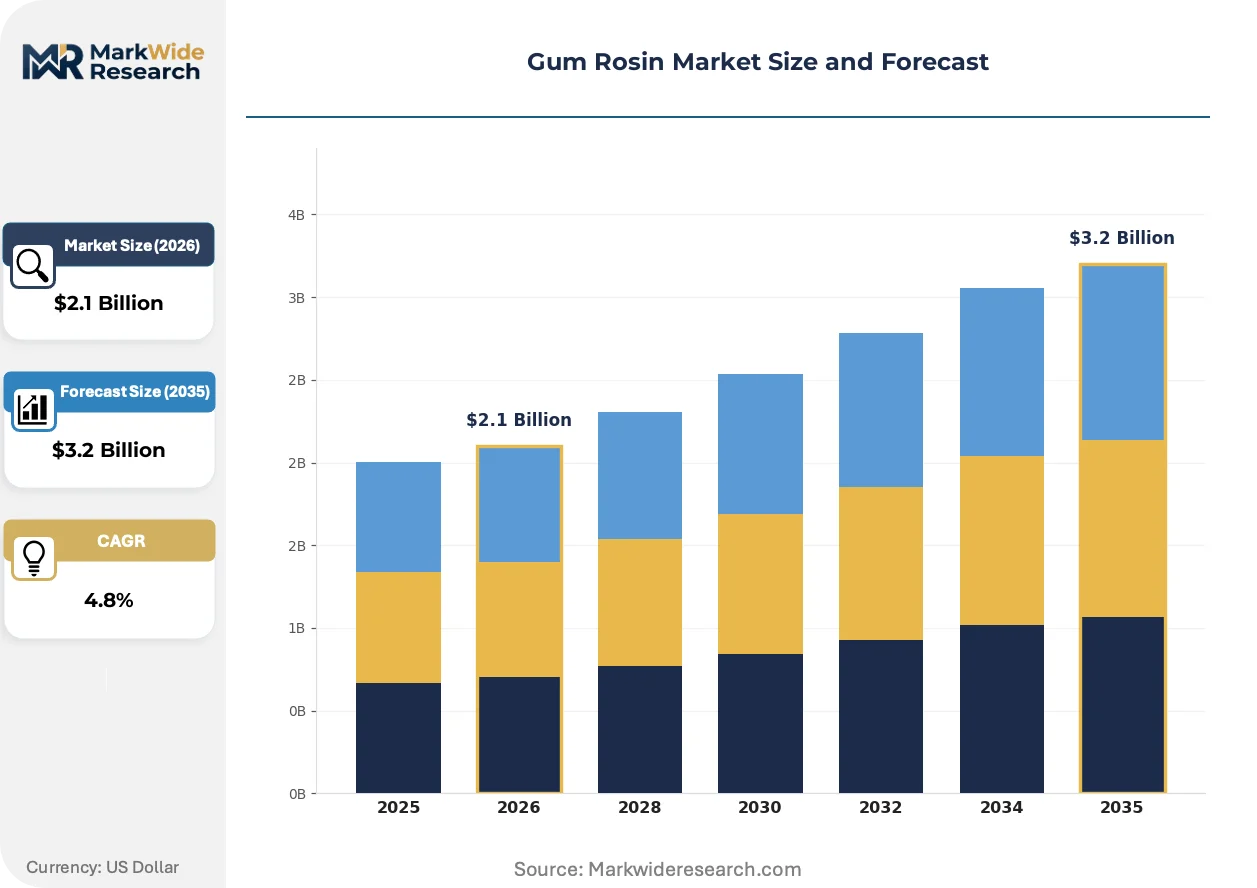
The market's central dynamic is the supply-side concentration of raw colophony production within China, which exerts significant influence over global pricing, availability, and the strategic calculus of downstream formulators. This structural reality forces companies to either build resilient supply chains or innovate on material chemistry to reduce dependency.
Growth Catalysts
- Bio-Based Formulations:Heightened consumer and regulatory pressure for sustainable products, particularly within the European Union, drives demand for gum rosin as a renewable raw material in adhesives, coatings, and polymers.
- Adhesives Sector Expansion:Growth in the packaging, construction, and automotive assembly industries creates consistent demand for gum rosin and its derivatives as essential tackifiers in hot-melt and pressure-sensitive adhesive systems.
- Rosin Ester Development:The chemical modification of gum rosin into higher-value rosin esters expands its utility into more demanding applications requiring superior thermal stability and oxidative resistance, opening new revenue streams.
Market Restraints
- Supply Chain Concentration:Heavy reliance on China for raw oleoresin and primary gum rosin creates significant price volatility and supply disruption risks for processors and end-users in other regions.
- Feedstock Volatility:The harvesting of pine oleoresin is labor-intensive and susceptible to climate conditions, leading to unpredictable fluctuations in raw material availability and cost, which impacts production planning.
- Synthetic Substitution:In cost-sensitive applications, petroleum-derived hydrocarbon resins can serve as a substitute for gum rosin as a tackifier, placing a ceiling on pricing power for lower-grade rosin products.
Strategic Opportunities
- Bio-Polymer Adhesives:Combining gum rosin derivatives with emerging bio-polymers like PLA and PHA presents an opportunity to develop fully biodegradable adhesive formulations for single-use packaging and agricultural films.
- Geographic Expansion:Rapid industrialization and infrastructure development in Latin American and Southeast Asian countries offer new growth markets for gum rosin in construction adhesives, road marking paints, and other industrial applications.
- Food-Grade Applications:Developing highly purified rosin esters that comply with stringent food-contact regulations, such as those from the FDA in the US, opens opportunities in chewing gum bases and citrus beverage stabilizers.
Industry Challenges
- Divergent Certifications:Navigating the complex and inconsistent requirements for bio-based content verification and sustainable forestry certification across the EU, US, and Asian markets creates significant compliance burdens.
- Quality Standardization:A lack of globally harmonized quality standards for raw colophony results in performance variability, forcing formulators to invest in extensive incoming material testing and supplier qualification processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gum Rosin Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colophony, Rosin Esters, Wood Rosin, Pine Rosin Application: Adhesives, Coatings, Inks, Rigid Polymers End User: Construction, Packaging, Automotive, Footwear Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | Arakawa Chemical Industries, Ltd., Guangxi Dinghong Resin Co., Ltd, Wuzhou Sun Shine Forestry and Chemicals Co., Ltd, CV. Indonesia Pinus, Forestar Chemical Co., Ltd., Harima Chemicals Group, Inc., Eastman Chemical Company, Ingevity Corporation, Foreverest Resources Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gum Rosin Market Strategic Shifts & Innovations
The gum rosin market is pivoting toward value-added derivatives and sustainable credentials. This evolution is a direct response to tightening environmental regulations and a demand-side pull for high-performance, bio-based materials in sophisticated industrial applications, moving the competitive focus from volume to specialized chemical function.
Rosin esters are a class of modified materials providing superior thermal stability and adhesion properties. Manufacturers of high-performance hot-melt adhesives for the automotive and electronics sectors are rapidly adopting these advanced derivatives. Consequently, rosin ester technology is overtaking the use of unmodified gum rosin in applications where heat resistance and long-term durability are critical performance metrics.
The European Union's REACH regulation mandates comprehensive registration and evaluation for all chemical substances, including gum rosin. This framework imposes significant data generation and reporting costs on producers, effectively acting as a non-tariff barrier to the EU market. The adhesives and coatings segments are most affected, now prioritizing suppliers who provide full REACH-compliant documentation for their formulations.
A distinct shift in buyer behavior is the growing preference for materials with verified sustainable sourcing, such as Forest Stewardship Council (FSC) certification. This trend disrupts traditional procurement models based solely on technical specifications, particularly in consumer-facing end-uses like food packaging. This demand for certified supply chains is most pronounced in North American and European markets, where corporations actively publish sustainability metrics.
Gum Rosin Market Segmentation
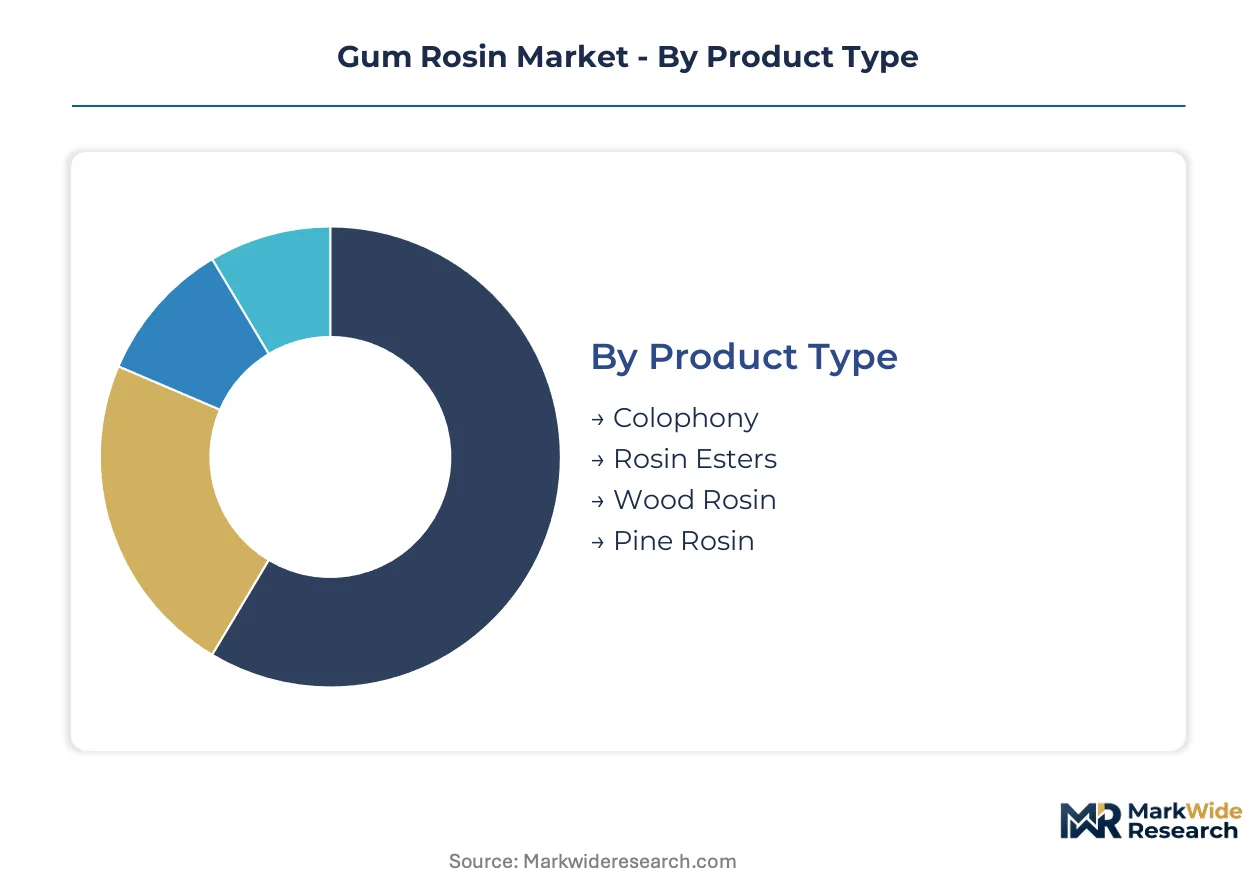
The gum rosin market's segmentation reflects the diverse applications and product refinements driving its evolution. Understanding these distinct segments provides insights into demand patterns and value chain dynamics across various industrial end-uses.
Product Type:
The market for gum rosin is undergoing a significant upgrade cycle, moving from basic raw materials to higher-value derivatives for specialized performance needs.
- Rosin Esters:These materials are chemically modified gum rosins, providing superior thermal stability and oxidative resistance for demanding applications. Automotive and electronics sectors drive demand for these high-performance hot-melt adhesives due to critical application requirements.
- Colophony:Colophony refers to the raw, solid, translucent resin obtained directly from pine oleoresin, with its acid number determining functional properties. China anchors the primary supply chain for colophony, which serves as a basic tackifier in general adhesive formulations.
- Wood Rosin:This product is extracted from aged pine stumps, often processed for lower-grade industrial applications where cost efficiency is paramount.
- Pine Rosin:This is a general term for rosin derived from living pine trees, utilized in various industrial products requiring tackifying or emulsifying properties.
Volume placements concentrate in Colophony; the faster expansion belongs to Rosin Esters.
Application:
Application-specific performance requirements dictate the suitability and formulation of gum rosin derivatives across various industrial sectors.
- Adhesives:Gum rosin functions primarily as a tackifier in both hot-melt and pressure-sensitive adhesive systems, enhancing bond strength. The packaging, construction, and automotive assembly industries create consistent demand for these essential materials.
- Coatings:Gum rosin improves adhesion, enhances gloss, and increases hardness in various paint and varnish formulations. The European Union market prioritizes bio-based formulations, driving gum rosin demand in sustainable coatings.
- Inks:Gum rosin historically provided gloss and adhesion properties in printing inks, though its use is declining in this segment due to substitution.
- Rigid Polymers:This application involves using gum rosin to modify polymer properties, enhancing stiffness, impact resistance, and processability.
The market dynamics for gum rosin applications are primarily shaped by the shift toward high-performance and sustainable formulations.
End User:
Customer type and their specific product needs heavily influence the demand for different gum rosin formulations and derivatives.
- Packaging:This sector requires strong, reliable adhesive bonds for diverse materials, from cardboard to flexible films. E-commerce growth and the food and beverage industries generate high-volume demand for gum rosin in packaging applications.
- Construction:Gum rosin finds utility in construction adhesives, sealants, and specialized road marking paints. Rapid industrialization in Latin American and Southeast Asian countries fuels growth in construction-related gum rosin consumption.
- Automotive:The automotive industry employs gum rosin derivatives in interior adhesives, sealants, and underbody coatings for durability and performance.
- Footwear:Gum rosin derivatives are used in sole adhesives for footwear, providing flexibility, strength, and water resistance.
The end-user segment reflects varying degrees of material specification and regulatory compliance across its constituent parts.
Distribution Channel:
Supply chain efficiency and market reach are critical factors determining how gum rosin products move from producers to end-users.
- Wholesalers:Wholesalers aggregate bulk purchases from primary producers and distribute them to a wide array of smaller formulators. This channel is critical for broad market penetration and efficient logistics in regions like China and Europe.
- Direct Sales:Producers engage in direct sales with large industrial customers, particularly for specialized, high-volume products. Major chemical companies in North America often prefer direct sales for strategic partnerships and technical support.
- Distributors:Distributors offer localized inventory, technical support, and value-added services to diverse industrial clients, facilitating market access.
- Online Retail:This emerging channel caters to smaller volume purchases and niche applications, providing convenience and broader product accessibility.
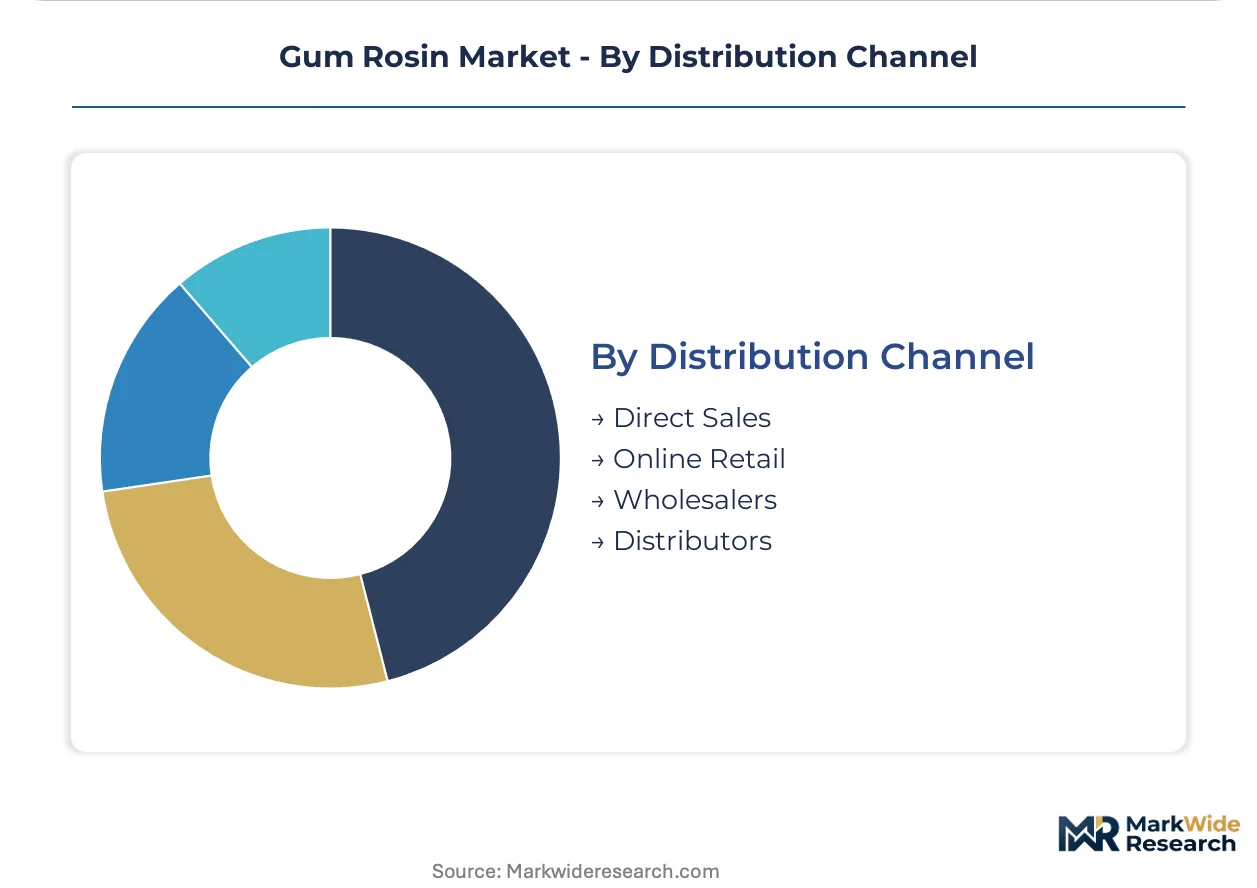
Market access for gum rosin depends heavily on the chosen distribution channel strategy and its alignment with customer scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Within China's Guangxi Zhuang Autonomous Region, a key forestry and chemical hub, gum rosin production and processing activities are heavily concentrated. This concentration significantly influences global supply dynamics and pricing for raw colophony. The region's strategic importance shapes raw material availability for downstream industries globally.
China
China's robust domestic demand for gum rosin stems from its expansive packaging and construction sectors. The national GB standards mandate specific quality and safety benchmarks for industrial materials. Wuzhou, in Guangxi, remains a critical hub, anchoring a significant portion of the primary colophony supply chain.
United States
United States demand for gum rosin derivatives is driven by advanced adhesive formulations and emerging food-grade applications. The EPA closely monitors volatile organic compounds in coatings and adhesives, influencing product chemistry. Chemical manufacturers along the Gulf Coast increasingly integrate rosin esters into high-performance industrial products.
Germany
Germany's market for gum rosin focuses on bio-based coatings and high-performance automotive adhesives. The European Union's REACH regulation significantly influences raw material sourcing and product composition. Companies in the Rhine-Ruhr industrial region are prioritizing REACH-compliant and sustainably sourced gum rosin formulations.
India
India's rapid industrialization fuels demand for gum rosin in packaging and construction adhesives. The Bureau of Indian Standards (BIS) establishes quality and safety standards for chemical products. Manufacturers within the Maharashtra industrial belt are expanding capacity for gum rosin-based adhesive and coating production.
Brazil
Brazil's growing construction sector and expanding domestic chemical industry drive demand for gum rosin. The country's ANVISA agency regulates chemical substances, impacting product formulations. Industrial hubs in São Paulo state are significant consumers, integrating gum rosin into adhesives, paints, and other industrial materials.
Gum Rosin Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments in the gum rosin market, reflecting varied strategic approaches. The industry structure is tiered, featuring primary raw material extractors at one end and refined derivatives producers at the other. Strategic archetypes include large integrated chemical companies, specialized pine chemical manufacturers, and regional processors. Companies are pursuing strategic partnerships, portfolio diversification, and selective capacity expansion to enhance their market reach and product offerings.
Specialists in pine-chemical derivatives, such as Japan-based Arakawa Chemical Industries, Ltd. and Harima Chemicals Group, Inc., exemplify the market's shift towards higher-value rosin esters. These companies occupy a position focused on R&D-intensive modifications for demanding applications like automotive and electronics adhesives. Meanwhile, Wuzhou Sun Shine Forestry and Chemicals Co., Ltd., a Chinese entity, anchors the primary supply chain, representing the raw colophony extraction segment. This structural differentiation highlights the varied business models and value capture strategies across the gum rosin industry.
| Leading Market Players |
|---|
| Arakawa Chemical Industries, Ltd. |
| Guangxi Dinghong Resin Co., Ltd |
| Wuzhou Sun Shine Forestry and Chemicals Co., Ltd |
| CV. Indonesia Pinus |
| Forestar Chemical Co., Ltd. |
| Harima Chemicals Group, Inc. |
| Eastman Chemical Company |
| Ingevity Corporation |
| Foreverest Resources Ltd. |
| Others |
Cost & Logistics Intelligence
Adhesive formulators' concentrated purchasing power influences the dominant contract-based long-term offtake pricing model in the gum rosin market. This structural reality often leads to tiered pricing, where larger buyers secure more favorable terms compared to smaller, transactional purchasers.
Pricing Analysis
Short-lead-time orders command a premium in the gum rosin market, reflecting immediate availability and expedited logistics. Commodity spot pricing often applies to lower-grade colophony, while contract-based long-term offtake agreements secure stable supply for high-volume users. Price differentiation stems from quality grade, particularly for rosin esters, and the geographic delivery cost to end-user markets. Pricing softness for basic colophony reflects the intense competition from petroleum-derived hydrocarbon resins. The packaging sector demonstrates high price sensitivity, while specialized electronics applications prioritize performance over cost.
Supply Chain Analysis
Reverse-logistics flows for gum rosin are minimal, as the product is consumed in manufacturing rather than returned. The supply chain concentrates heavily in China, which sources raw oleoresin, and also includes significant production from India and Brazil. Raw pine oleoresin remains the critical dependency, susceptible to climate conditions and labor availability. Commodity price volatility poses a significant structural risk for downstream processors. Distribution runs through a hybrid model combining wholesalers for broad market penetration and direct sales for large industrial customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gum rosin market presents a consolidation play, driven by tightening environmental regulations forcing smaller, less compliant producers out of the market.
For Market Incumbents: Anchor market position by investing in advanced rosin ester production capabilities, particularly for automotive and electronics applications. Diversify raw material sourcing beyond China to mitigate supply chain concentration risks. Pursue backward integration into oleoresin harvesting or processing to control feedstock quality and cost. Invest in REACH-compliant documentation and sustainable forestry certifications to counteract regulatory threats from the EU and North America.
For New Entrants and Emerging Players: Begin with niche applications requiring highly purified or specialized gum rosin derivatives, such as food-grade stabilizers. Target Latin American and Southeast Asian construction sectors due to rapid industrialization and less stringent regulatory barriers. Develop bio-polymer adhesive formulations combining gum rosin with PLA or PHA to address the growing demand for fully biodegradable solutions. A direct sales model, emphasizing technical support and customized formulations, can effectively penetrate these specialized segments.
For Investors and Strategic Acquirers: The window for entry favors integrated specialty chemical manufacturers with strong R&D capabilities. Long-term viability hinges on companies capable of transforming raw colophony into high-value rosin esters and bio-based formulations. Target acquisition archetypes include specialized pine chemical producers with proprietary modification technologies or strong regional distribution networks. Monitor the adoption rate of bio-based content verification standards as a key inflection indicator for market growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Rosin Esters | Increases supply of high-performance derivatives for demanding industrial applications. |
| Sustainable Forestry Certification Programs | Secures verified bio-based raw material sourcing for European and North American markets. |
| Geographic Diversification of Oleoresin Sourcing | Reduces dependence on single-country supply and mitigates price volatility. |
| R&D in Bio-Polymer Adhesives | Creates fully biodegradable adhesive solutions for the packaging and agricultural sectors. |
| Compliance with Food-Contact Regulations | Opens new revenue streams in chewing gum bases and beverage stabilizers. |
Research Approach
Multi-period observation of pricing trends, regulatory shifts, and application-specific demand anchored the trend analysis, supplemented by interviews with chemical plant managers, procurement leads at adhesive formulators, and technical R&D directors. This primary research was triangulated with secondary data from customs and trade statistics, chemical industry association reports (e.g., ACC/Cefic), and national GB standards from China. A bottom-up approach, aggregating data from specific end-use sectors, complemented a top-down validation against overall market size estimates.
The input-output matrix framework modeled market dynamics across the analysis window, considering product type (rosin esters, colophony), application (adhesives, coatings), end-user (packaging, construction), and regional production hubs. Segment-specific CAGRs were derived by analyzing historical growth drivers and projected shifts in technology adoption and regulatory compliance. Industry-specific forecast inputs included anticipated growth rates in packaging volumes and construction project pipelines across key geographies.
Underlying measurement precision varies by segment; rosin esters and adhesives carry tighter precision than general colophony or inks due to more defined value chains. Forecasts reflect assumptions regarding feedstock availability and the pace of regulatory enforcement. Practitioners should monitor global trade policies and climate-related disruptions to pine oleoresin harvesting for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Coatings Market
Rubber
Rubber Masterbatch Market
Rubber
Acrylic Based Elastomers Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Tire Recycling Downstream Products Market
Rubber
Rubber Bulb Seals Market
Rubber
Isobutylene Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Global Rubber Process Oil Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Global Latex Allergy Market
Rubber
Rubber Plated Hose Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
Europe Neoprene Market
Rubber
Silica for S-SBR Market
Rubber
Chloroprene Rubber Tape Market