
 Tire Recycling Downstream Products Market | 2026-2036
Tire Recycling Downstream Products Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Recycling Downstream Products Market Intelligence
Recovered carbon black is shifting price benchmarks away from virgin carbon black in tire manufacturing formulations. Scandinavian Enviro Systems leverages its proprietary pyrolysis platform to sustain premium product yields from end-of-life tires. Liberty Tire Recycling anchors North American collection density through its integrated processing network. Genan Holding A/S dominates European crumb rubber supply for industrial compounding applications.
Tire recycling downstream products encompass material outputs derived from mechanical shredding, cryogenic grinding, pyrolysis, and devulcanization of end-of-life tires, yielding particulate rubber, steel wire, synthetic gas, and recovered carbon black with particle sizes ranging from 0.1 mm crumb to 4 mm chips for distinct industrial specifications. Crumb rubber commands the largest volume share across pavement and molded product applications, while devulcanized rubber captures expanding margin pools in automotive seal manufacturing where compounders seek virgin rubber substitutes. Wire recovery generates stable revenue through direct steel mill offtake agreements, though tire-derived fuel faces regulatory pressure as cement kilns evaluate emissions profiles under tightening standards.
The EPA administers scrap tire management guidelines under the Resource Conservation and Recovery Act, while state-level regulators in California and Texas enforce landfill diversion quotas that directly shape collection infrastructure investment. The EU Green Deal and REACH chemical registration protocols constrain tire-derived fuel combustion thresholds, redirecting material flows toward higher-value recycling pathways. Stakeholders must monitor devulcanization technology cost curves and recovered carbon black qualification timelines with major tire OEMs to anticipate which processing routes secure durable offtake contracts.
Market Dynamics
The EU Green Deal's landfill diversion mandates are compressing traditional tire disposal routes and forcing material flows toward pyrolysis and devulcanization platforms that can extract recovered carbon black and synthetic gas at commercial scale.
Growth Catalysts
- Rubberized asphalt specifications:Federal highway contracts in Germany now mandate crumb rubber content in pavement binders, pulling volume from industrial molding into infrastructure applications.
- REACH chemical registration:The EU's tightened combustion thresholds for tire-derived fuel redirect pyrolysis output toward recovered carbon black qualification with tire OEMs.
- Cryogenic grinding advances:Ultra-fine crumb production below 0.5 mm particle size opens medical and consumer goods compounding previously served by virgin synthetic rubber.
Market Restraints
- Natural gas price volatility:Pyrolysis operations face margin compression when feedstock energy costs spike, particularly affecting continuous reactor economics.
- Collection infrastructure gaps:Rural and secondary city tire arisings concentrate in fragmented hauler networks that limit feedstock security for large-scale processors.
- Virgin carbon black substitution ceiling:Major tire manufacturers cap recovered carbon black at 10-15% of tread formulations pending durability certification timelines.
Strategic Opportunities
- India's PLI scheme for rubber goods:Domestic crumb rubber integration into conveyor belt and mat manufacturing offers tariff-advantaged supply to South Asian industrial buyers.
- Devulcanization-automation convergence:Microwave and ultrasonic devulcanization platforms paired with robotic sorting cut labor intensity for automotive seal compounders.
- Cement kiln emission standards:EU BAT (Best Available Techniques) regulations accelerate tire-derived fuel displacement toward higher-value material recovery routes.
Industry Challenges
- Pyrolysis reactor fabrication lead times:Specialized alloy vessel procurement stretches 18-24 months, delaying capacity expansion for recovered carbon black qualification.
- Cross-batch consistency certification:Tire OEMs require multi-year tread wear datasets that small-scale pyrolysis operators struggle to generate without consortium testing programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Recycling Downstream Products Market |
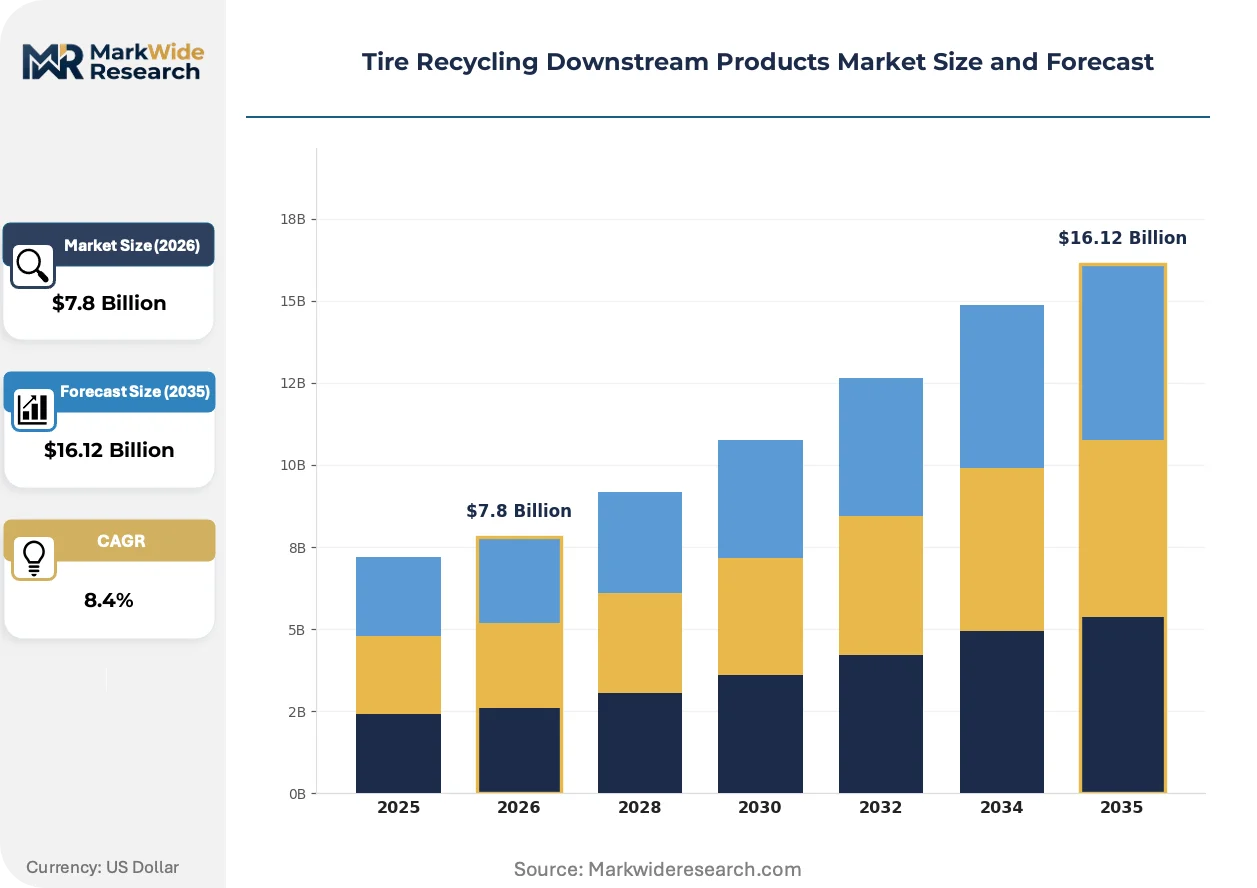
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crumb Rubber, Wire, Tire-derived Fuel, Devulcanized Rubber End User: Construction, Automotive, Sports, Agriculture Application: Pavement, Molded Products, Flooring, Adhesives Distribution Channel: Direct Sales, Retail, Wholesalers, E-commerce |
| Companies Covered | Scandinavian Enviro Systems, ResourceCo, Liberty Tire Recycling, Lakin Tires West, ETR Group, Genan Holding A/S, Ragn-Sells Group, Renelux Cyprus, Lehigh Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Recycling Downstream Products Market Strategic Shifts & Innovations
Processing platforms are fragmenting into specialized unit operations rather than integrated mega-facilities, with cryogenic grinding, pyrolysis, and devulcanization each attracting distinct capital pools and technical talent bases.
Continuous pyrolysis reactor design is modularizing around standardized 10,000-tonne annual input modules that permit incremental capacity addition without full-scale engineering redesign. Regional processors in Poland and the Czech Republic deploy these units to serve nearby tire manufacturing clusters with just-in-time recovered carbon black delivery. This architecture compresses project finance timelines and reduces offtake risk concentration.
The EPA's scrap tire management guidelines under RCRA are tightening state-level reporting granularity, forcing California and Texas operators to document mass balance through processing stages rather than collection tonnage alone. Cement kiln buyers face heightened emissions scrutiny that redirects tire-derived fuel volumes toward pyrolysis alternatives. Processors respond by segregating passenger tire feedstocks to optimize recovered carbon black yield profiles.
Automotive seal compounders now specify devulcanized rubber content thresholds in annual supply agreements, replacing spot-market crumb purchases with multi-year compound formulations. Tier-2 gasket manufacturers in Michigan and Ohio consolidate vendor bases to processors offering certified batch consistency. This specification-driven consolidation concentrates volume with operators maintaining in-house laboratory compounding capabilities.
Tire Recycling Downstream Products Market Segmentation
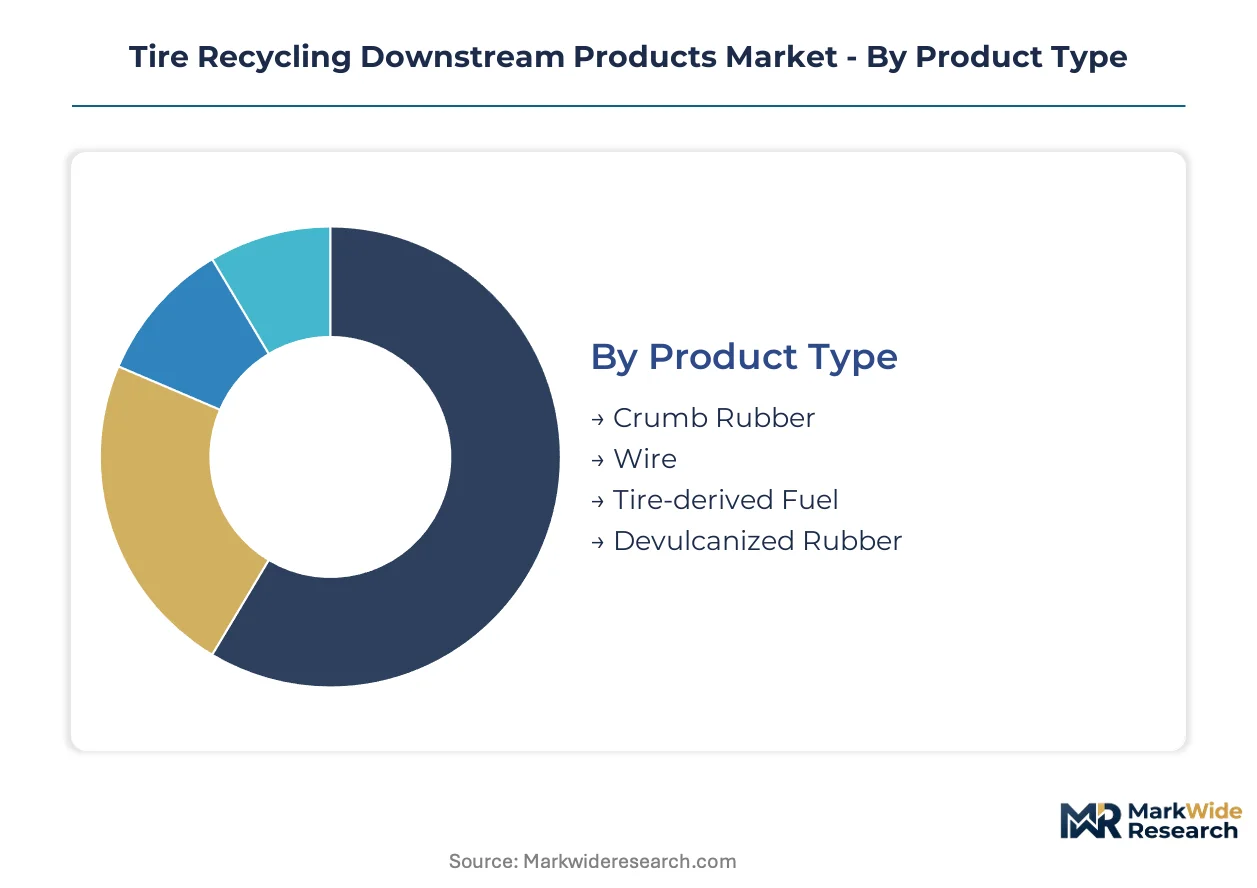
End-of-life tire processors configure output streams around distinct particle specifications and chemical recovery yields. Each product category commands discrete pricing benchmarks and qualification protocols with downstream compounders.
Product Type:
Replacement cycles for industrial rubber goods accelerate specification shifts across recycled material grades.
- Crumb Rubber:Ground tire rubber processed to 0.5-4 mm particle sizes serves asphalt modification and molded product feedstocks. German federal highway contracts now mandate crumb rubber content in pavement binders, redirecting volume from industrial molding into infrastructure applications.
- Wire:Steel recovery from tire shredding yields bead and belt wire for direct steel mill offtake. Stable revenue flows through long-term supply agreements with electric arc furnace operators in Poland and the Czech Republic.
- Tire-derived Fuel:Shredded tire chips burned in cement kilns face tightening EU BAT emission standards that compress combustion thresholds and redirect material toward pyrolysis alternatives.
- Devulcanized Rubber:Reclaimed polymer through microwave or ultrasonic processing restores elastomeric properties for automotive seal compounding where virgin rubber substitution premiums apply.
Volume placements concentrate in crumb rubber; the faster expansion belongs to devulcanized rubber.
End User:
Cost tier differentiation separates commodity construction procurement from specification-driven automotive contracts.
- Construction:Rubberized asphalt and drainage layer applications consume coarse crumb grades with lower processing intensity requirements.
- Automotive:Tier-2 gasket manufacturers in Michigan and Ohio now specify devulcanized rubber content thresholds in multi-year supply agreements, replacing spot-market purchases.
- Sports:Synthetic turf infill and running track surfaces drive consistent demand for 1-3 mm crumb with specific heavy metal compliance certification.
- Agriculture:Livestock matting and silage bunker lining applications absorb irregular crumb sizes that fail stricter industrial specifications.
Construction absorbs the largest tonnage; automotive contracts capture the steepest margin premiums.
Application:
Geographic clustering of tire arisings shapes regional application specialization.
- Pavement:Hot mix asphalt and spray-applied binders incorporate 10-20% crumb rubber content in Germany, Texas, and California where state specifications mandate recycled content.
- Molded Products:Traffic cones, wheel chocks, and industrial matting utilize coarse crumb with lower purity requirements than automotive grades.
- Flooring:Gymnasium surfaces and anti-fatigue mats demand 0.5-1.5 mm crumb with consistent particle distribution for compression set performance.
- Adhesives:Sealant and coating formulations utilize ultra-fine crumb below 0.5 mm produced through cryogenic grinding platforms.
Pavement commands the dominant share; adhesive applications are climbing the fastest on medical and consumer goods qualification.
Distribution Channel:
Customer type fragmentation between bulk industrial buyers and fragmented retail outlets determines channel economics.
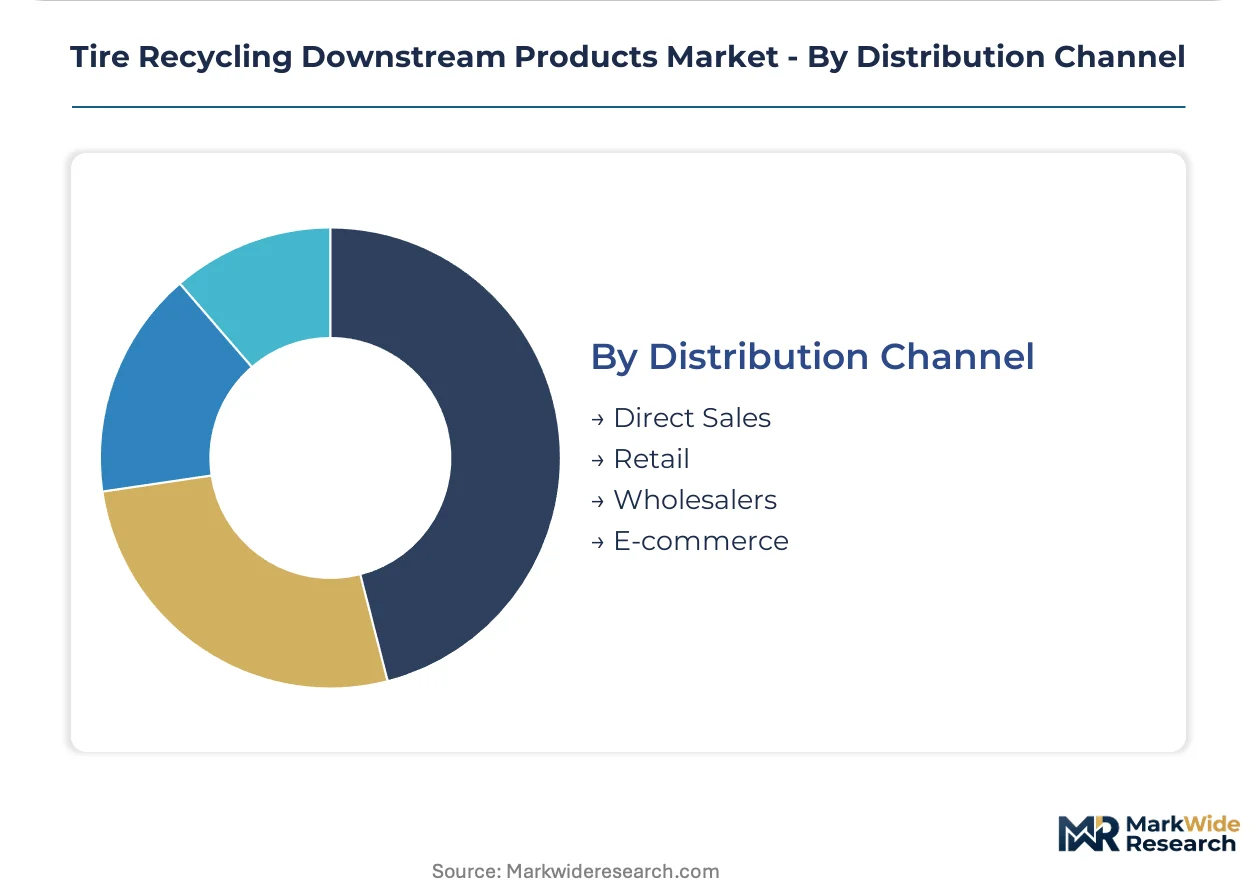
- Direct Sales:Large-volume compounders and asphalt contractors negotiate annual offtake agreements with processors maintaining in-house laboratory certification capabilities.
- Retail:Landscaping and home improvement channels distribute bagged crumb for residential applications with higher per-unit margins but logistics complexity.
- Wholesalers:Regional distributors aggregate small-lot demand from secondary manufacturers lacking direct processor relationships.
- E-commerce:Specialty grades and certified organic crumb products reach niche buyers through platform marketplaces with limited volume penetration.
Direct sales anchor volume throughput; e-commerce channels are gaining share fastest in specialty grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates infrastructure demand through federal highway contracts mandating crumb rubber content, while collection networks in Texas and California anchor North American feedstock security for pyrolysis scale-up.
Germany
Federal highway procurement mandates crumb rubber in pavement binders, pulling volume from industrial molding. The EU Green Deal tightens landfill diversion quotas under circular economy protocols. Processing clusters in North Rhine-Westphalia serve the Ruhr industrial corridor with just-in-time recovered carbon black delivery to tire manufacturing plants.
United States
State-level landfill diversion quotas in California and Texas shape collection infrastructure investment. The EPA administers scrap tire guidelines under RCRA with tightening reporting granularity. Liberty Tire Recycling anchors collection density through integrated processing networks serving asphalt contractors across the Midwest and Southeast.
India
The PLI scheme for rubber goods accelerates domestic crumb rubber integration into conveyor belt manufacturing. BIS standards govern industrial compound specifications for automotive seal applications. Processing capacity concentrates in Gujarat and Maharashtra to serve South Asian industrial buyers with tariff-advantaged supply.
Poland
Cement kiln operators face EU BAT emission standards that compress tire-derived fuel combustion thresholds. REACH chemical registration redirects pyrolysis output toward recovered carbon black qualification. Regional processors deploy modular 10,000-tonne pyrolysis units to serve nearby tire manufacturing clusters.
Sweden
Scandinavian Enviro Systems leverages proprietary pyrolysis platforms to sustain premium recovered carbon black yields. National circular economy targets exceed EU baseline landfill diversion rates. Technology development concentrates in Gothenburg engineering corridors with focus on continuous reactor commercialization.
Tire Recycling Downstream Products Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated collection-to-processing operators commanding feedstock security advantages over standalone technology licensors. The vendor base organizes around three archetypes: pyrolysis platform specialists, mechanical shredding networks, and devulcanization compounders. Consolidation pressure concentrates in North American collection assets and European recovered carbon black qualification programs. Competitive moves center on backward integration into tire collection networks and technology licensing partnerships for modular reactor deployment.
Among Nordic technology specialists, Scandinavian Enviro Systems exemplifies the pyrolysis platform archetype through its proprietary continuous reactor approach. Liberty Tire Recycling anchors North American market structure as an integrated collection and processing operator. Genan Holding A/S occupies a position within European crumb rubber supply, representing the mechanical shredding and devulcanization tier serving industrial compounding applications.
| Leading Market Players |
|---|
| Scandinavian Enviro Systems |
| ResourceCo |
| Liberty Tire Recycling |
| Lakin Tires West |
| ETR Group |
| Genan Holding A/S |
| Ragn-Sells Group |
| Renelux Cyprus |
| Lehigh Technologies |
| Others |
Cost & Logistics Intelligence
Pyrolysis reactor engineers concentrated in Gothenburg engineering corridors command wage premiums that compress margin spreads between standard-grade crumb rubber and premium recovered carbon black tiers. Labor-cost differentials between Nordic technology specialists and Polish modular reactor operators translate directly into pricing-tier spreads that buyers navigate when qualifying suppliers for tire OEM contracts.
Pricing Analysis
Volume placements in crumb rubber for pavement applications capture thin margins, while devulcanized rubber and recovered carbon black command substantial premiums in automotive seal compounding. Three-tier pricing structure across premium, standard, and economy levels separates certified batch-consistent recovered carbon black from industrial-grade crumb and unprocessed tire chips. Cost compression in standard crumb tiers is intensifying because German federal highway contracts consolidate procurement volumes with fewer qualified processors. Asphalt contractors exhibit the highest price sensitivity, whereas Tier-2 automotive gasket manufacturers prioritize batch consistency over unit cost.
Supply Chain Analysis
Workforce availability for cryogenic grinding technicians in Germany, pyrolysis operators in Poland, and devulcanization specialists in India shapes regional processing cost structures and capacity expansion timelines. Supply concentrates in Germany for crumb rubber qualification, Poland for modular pyrolysis deployment, and India for tariff-advantaged conveyor belt compounding. Feedstock draws from fragmented rural hauler networks, steel wire offtake agreements with electric arc furnace operators, and synthetic gas capture systems. Single-source vulnerability in specialized alloy reactor vessel fabrication stretches procurement lead times. Distribution runs through direct annual offtake agreements with large-volume compounders and asphalt contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
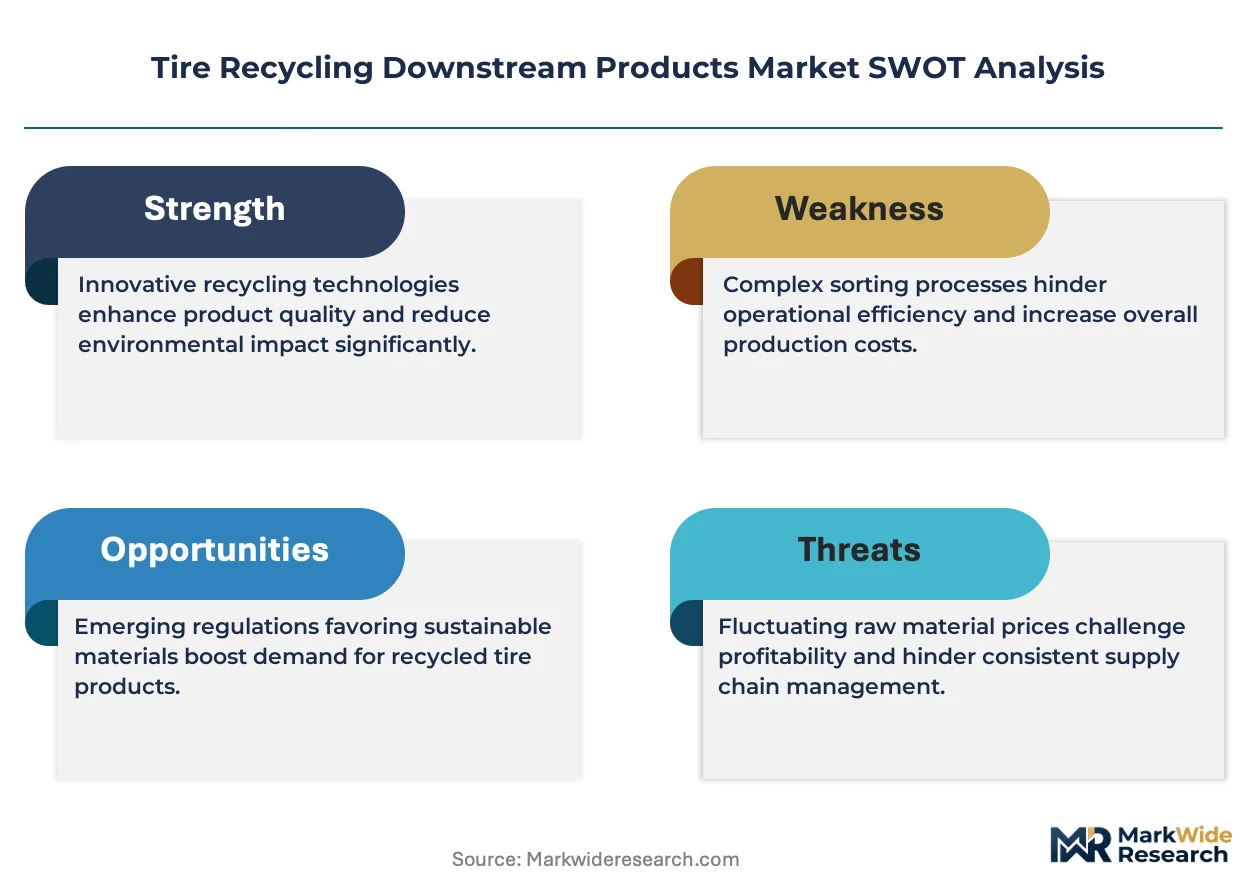
The tire recycling downstream products market functions as a cost-of-compliance arena where EU Green Deal landfill diversion mandates and REACH chemical registration protocols erect barrier-to-entry moats for processors with certified recovery pathways.
For Market Incumbents: Cement feedstock security through backward integration into collection networks across Texas and California where state landfill diversion quotas concentrate tire arisings. Expand in-house laboratory compounding capabilities to capture Tier-2 automotive gasket contracts specifying devulcanized rubber content thresholds. Defend against modular pyrolysis entrants by accelerating recovered carbon black qualification timelines with major tire OEMs. For New Entrants and Emerging Players: Launch via regional crumb rubber aggregation for India's PLI scheme-backed conveyor belt manufacturers seeking tariff-advantaged domestic supply. Target Poland's cement kiln displacement opportunity as EU BAT emission standards redirect tire-derived fuel volumes toward pyrolysis alternatives. Penetrate through cryogenic grinding specialization for medical-grade ultra-fine crumb below 0.5 mm particle size. For Investors and Strategic Acquirers: Re-rating potential sits with integrated collection-to-processing operators given tightening EPA RCRA reporting granularity and state-level mass balance documentation requirements. Long-term viability favors processors with captive tire supply agreements and qualified recovered carbon black output streams. Watch devulcanization-automation convergence as the inflection signal for margin expansion in automotive seal applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collection Networks | Liberty Tire Recycling's integrated density anchors feedstock security against fragmented rural hauler concentration. |
| Modular Pyrolysis Capacity Expansion | Polish regional processors deploy standardized 10,000-tonne units to serve Ruhr corridor tire manufacturing clusters. |
| Recovered Carbon Black Qualification | Scandinavian Enviro Systems sustains premium yields through proprietary continuous reactor commercialization. |
| Devulcanization Automation Investment | Microwave and ultrasonic platforms paired with robotic sorting cut labor intensity for Michigan gasket manufacturers. |
| Geographic Expansion to India | Gujarat and Maharashtra processing capacity serves South Asian industrial buyers under PLI scheme rubber goods incentives. |
Research Approach
Trade databases, EU regulatory filings, and tire industry association reports formed the secondary backbone for market sizing and competitive mapping. Primary interviews with pyrolysis plant managers, crumb rubber procurement leads at asphalt contractors, devulcanization technology directors, and automotive seal compounders validated processing cost structures and offtake contract terms. Bottom-up and top-down triangulation cross-checked volume estimates across mechanical shredding, cryogenic grinding, and pyrolysis platform outputs.
Bottom-up modeling built product-level forecasts from individual processor capacity announcements and qualified offtake agreements, while top-down analysis cross-referenced against EU Green Deal diversion targets and state-level landfill quotas. Segmentation dimensions included product type, end user industry, application specification, and distribution channel. CAGRs were derived from fitted growth curves calibrated to regulatory mandate implementation schedules and tire OEM qualification timelines. Key inputs encompassed natural gas price volatility effects on pyrolysis economics and cross-batch consistency certification requirements.
The model assumes a particular technology adoption path; alternative pathways for microwave devulcanization versus ultrasonic platforms would alter the outlook for automotive seal compounding penetration. Forecasts reflect assumptions regarding REACH chemical registration timelines and EPA RCRA reporting granularity enforcement. Material deviation in tire OEM recovered carbon black qualification thresholds or EU BAT emission standard implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Cast Elastomers Market
Rubber
Acrylic Rubber Market
Rubber
Nitrile Elastomers Market
Rubber
Nitrile Butadiene Rubber Market
Rubber
Rubber Gloves Market
Rubber
Rubber Choppers Market
Rubber
Silicone Rubber Market
Rubber
Rubber Wear Liners Market
Rubber
Global Rubber Market
Rubber
Isobutylene Market
Rubber
Ethylene Propylene Rubber Cable Market
Rubber
Styrene Butadiene (SB) Latex Market
Rubber
Rubber Sand Market
Rubber
Abrasion-Resistant Rubber Pipe Market
Rubber
Tire Chemicals Market
Rubber
Rubber Accelerators Market