
 Rubber Coatings Market | 2026-2036
Rubber Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Coatings Market Analytics
REACH solvent-content thresholds are decoupling European formulation economics from legacy cost structures. BASF SE leverages its integrated polymer intermediate chain to sustain margin capture across water-based transitions. PPG Industries anchors North American automotive supply through captive resin production and OEM qualification depth. AkzoNobel N.V. differentiates via marine certification density and regional distribution control across Baltic and Mediterranean ports.
Rubber coatings are elastomeric protective films, typically formulated from chloroprene, nitrile, or polyurethane dispersions with thickness ranges of 0.1–3.0 mm, applied by spray, dip, or electrodeposition to confer abrasion resistance, chemical shielding, and vibration damping. Liquid coatings dominate current volume owing to retrofit accessibility and field repair compatibility, while powder coatings represent the fastest-expanding technology segment as automotive manufacturers pursue zero-VOC bake cycles and reclaimable overspray economics. Water-based formulations are capturing margin pools in regulated European and North American jurisdictions, whereas solvent-based systems retain cost advantage in price-sensitive industrial maintenance sectors.
FDA food-contact rulings, EPA VOC emissions ceilings, and REACH Annex XVII substance restrictions collectively elevate compliance expenditure for cross-border suppliers. ECHA substance-of-very-high-concern listings are forcing reformulation timelines that favor pre-registered alternative chemistries. Stakeholders must monitor regulatory divergence between EU hazard-based classification and US risk-assessment frameworks when allocating R&D budgets across formulation platforms.
Market Dynamics
Water-based formulation migration is compressing solvent-dependent supply chains while REACH Annex XVII substance restrictions force multi-year reformulation cycles across European coating portfolios.
Growth Catalysts
- REACH solvent-content thresholds:European formulators accelerate water-based platform investments to retain market access across automotive OEM specifications.
- Automotive NVH reduction mandates:Underbody rubber coating specifications expand as OEMs target cabin noise suppression in electric vehicle architectures.
- Shanghai industrial corridor concentration:China's automotive and marine manufacturing clusters drive localized coating demand for abrasion-resistant protection systems.
Market Restraints
- Petrochemical feedstock volatility:Chloroprene and nitrile intermediate costs fluctuate with crude-linked naphtha pricing, compressing formulation margins unpredictably.
- Solvent-based legacy asset stranding:European coating facilities face accelerated depreciation as water-based capex requirements collide with restricted solvent throughput permits.
- Cured film thickness limitations:Dip-coating processes struggle to achieve sub-0.3 mm uniformity for precision electronics applications, ceding share to vapor deposition alternatives.
Strategic Opportunities
- India automotive manufacturing expansion:PLI scheme incentives for electric vehicle production create coating specification opportunities at emerging Tamil Nadu and Gujarat assembly hubs.
- Powder coating zero-VOC bake cycles:Reclaimable overspray economics align with automotive OEM sustainability targets for enclosed spray booth operations.
- Marine certification density gaps:Baltic and Mediterranean port authorities escalate anti-corrosion standards, opening formulation upgrade cycles for existing fleet maintenance.
Industry Challenges
- Formulation chemist scarcity:Water-based dispersion expertise remains concentrated among legacy solvent specialists undergoing forced skill retooling.
- OEM qualification timeline compression:Automotive coating approvals stretch 18-24 months, locking out reformulated products mid-certification cycle.
- Cross-border substance registration divergence:ECHA SVHC listings and EPA TSCA Section 5 notifications create conflicting compliance pathways for unified product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Coatings Market |
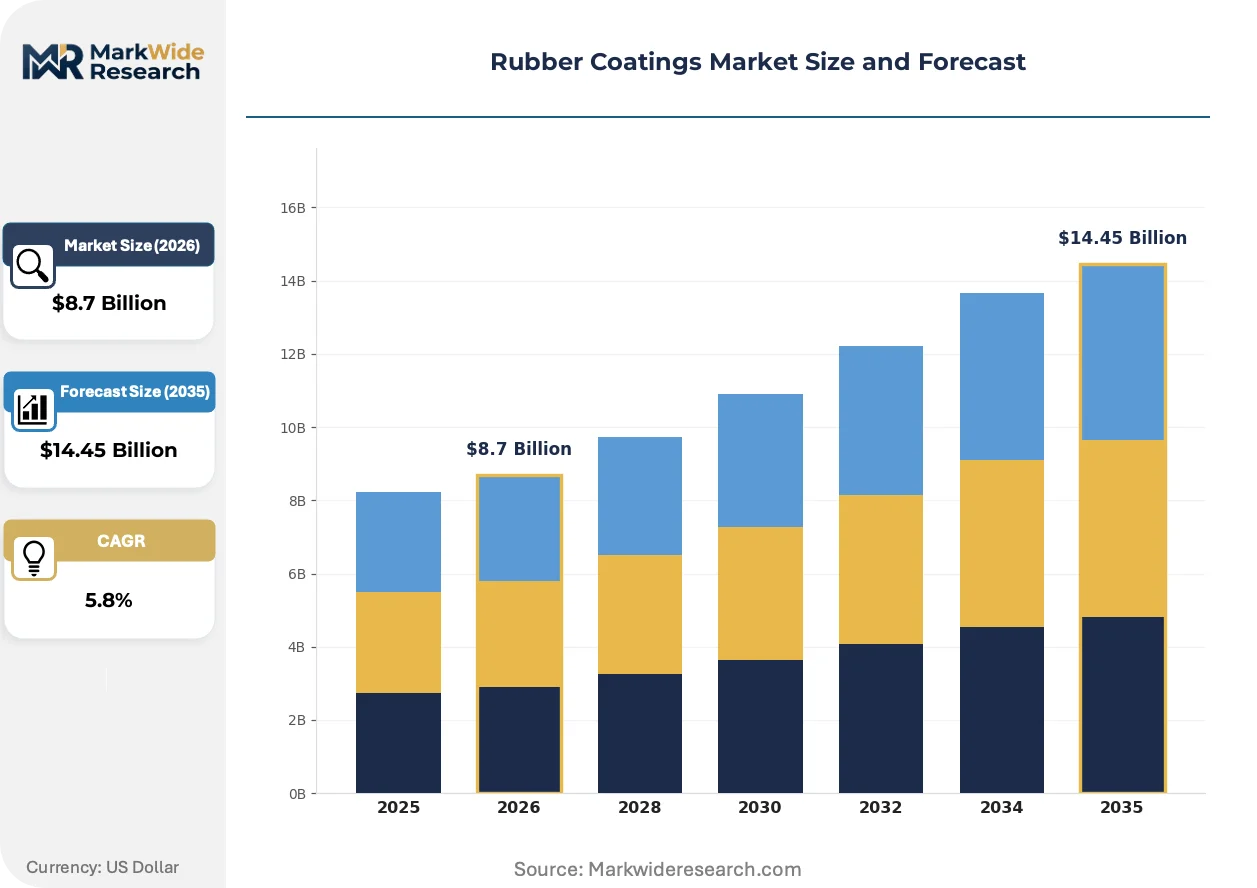
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Coatings, Powder Coatings, Specialty Coatings, Elastic Coatings Application: Automotive, Construction, Electronics, Marine End User: Manufacturers, Distributors, Retailers, Contractors Technology: Solvent-Based, Water-Based, UV-Cured, High-Performance |
| Companies Covered | BASF SE, PPG Industries, Inc., AkzoNobel N.V., 3M Company, Huntsman Corporation, Axalta Coating Systems, The Dow Chemical Company, Wacker Chemie AG, The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Coatings Market Evolving Landscape
Electrodeposition coating integration with rubber film deposition is collapsing traditional process steps. Formulators now compete on bake-cycle energy efficiency and film uniformity rather than standalone chemical performance.
Polyurethane dispersion electrodeposition is electrifying automotive underbody protection workflows. Tier-1 suppliers in Germany and Japan adopt integrated ED-rubber lines to eliminate primer-sandwich layers. The technology is compressing capital intensity per unit of protected surface area while tightening film thickness tolerances to 0.05 mm.
REACH Annex XVII phthalate restrictions are forcing plasticizer substitution in flexible coating formulations. European compounders pivot to bio-based adipate esters and polymerics, triggering raw material qualification backlogs. Marine and industrial maintenance segments absorb the highest compliance costs due to batch-size fragmentation and certificate renewal frequency.
Automotive OEMs now bundle coating specifications into platform-level procurement contracts. Tier-1 suppliers lose pricing autonomy as Volkswagen, Stellantis, and BYD centralize material approvals across multiple assembly plants. Germany's automotive belt exhibits the most pronounced buyer concentration, with three OEMs controlling over sixty percent of regional coating volume nominations.
Rubber Coatings Market Segmentation
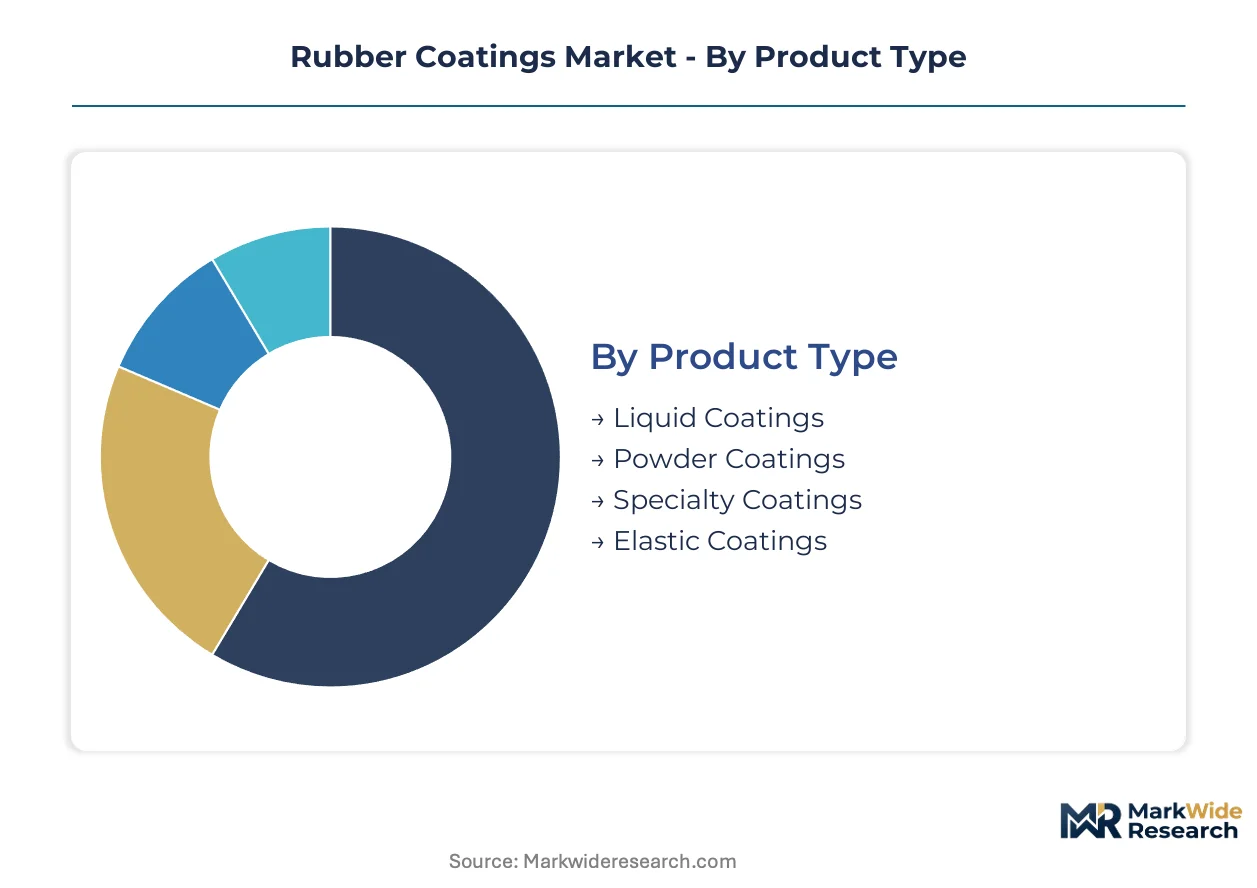
Rubber coatings segment along four intersecting dimensions that determine formulation economics, regulatory exposure, and customer access requirements. Product type and technology choices lock in capital intensity and VOC compliance profiles, while application and end-user splits dictate service models and qualification timelines.
Product Type:
Liquid coatings dominate current volume owing to retrofit accessibility, yet powder coatings command premium positioning through zero-VOC bake cycles and reclaimable overspray.
- Liquid Coatings:Chloroprene, nitrile, and polyurethane dispersions applied by spray, dip, or brush with thickness ranges of 0.1–3.0 mm. Demand concentrates in industrial maintenance across Germany's automotive belt, where field repair compatibility and substrate versatility outweigh bake-cycle constraints. REACH solvent-content thresholds are accelerating water-based liquid formulation investments among European suppliers.
- Powder Coatings:Thermoset elastomer powders applied via electrostatic spray with 100% solids content and near-zero overspray waste. Automotive OEMs in Stuttgart and Wolfsburg specify powder systems for enclosed underbody protection lines, driven by sustainability targets and energy-efficient cure cycles. This segment is gaining share fastest among new automotive platform nominations.
- Specialty Coatings:Functional formulations incorporating conductive fillers, thermal barriers, or antimicrobial agents for medical and aerospace substrates.
- Elastic Coatings:High-elongation films exceeding 300% strain capacity for bridge deck and roofing membrane applications.
Today's leader: Liquid Coatings. Tomorrow's challenger: Powder Coatings.
Application:
Automotive specifications drive the highest coating value per square meter, while marine applications impose the most demanding certification density.
- Automotive:Underbody protection, NVH damping layers, and cavity sealing across OEM assembly lines. Specifications from Volkswagen, Stellantis, and BYD centralize material approvals across multiple plants, compressing Tier-1 supplier pricing autonomy. Germany's automotive belt exhibits the most pronounced buyer concentration, with three OEMs controlling the majority of regional volume nominations.
- Marine:Anti-corrosion systems for hulls, decks, and ballast tanks subject to IMO PSPC and port authority standards. Baltic and Mediterranean port authorities escalate anti-corrosion requirements, opening formulation upgrade cycles for existing fleet maintenance. Certificate renewal frequency and batch-size fragmentation elevate compliance costs disproportionately.
- Construction:Waterproofing membranes, expansion joint covers, and structural steel protection for infrastructure projects.
- Electronics:Conformal coatings and vibration-damping films for precision components, where dip-coating thickness uniformity limitations cede share to vapor deposition alternatives.
Automotive commands margin; marine commands compliance expenditure.
End User:
Manufacturers capture volume through captive application lines, while contractors and retailers fragment procurement across project-based demand.
- Manufacturers:Tier-1 automotive suppliers and industrial OEMs with in-house coating operations. These buyers consolidate purchasing through platform-level procurement contracts, eliminating supplier pricing autonomy. Qualification timelines stretch 18-24 months, locking out reformulated products mid-certification cycle.
- Distributors:Regional stocking intermediaries serving maintenance contractors and smaller OEMs with fragmented batch requirements.
- Retailers:Consumer-facing channels for DIY repair and small-scale maintenance applications.
- Contractors:Field application specialists demanding fast-cure formulations and substrate-tolerant systems for retrofit projects.
Manufacturer consolidation is squeezing distributor margins while elevating contractor service premiums.
Technology:
Water-based platforms capture regulatory-driven substitution, while high-performance formulations defend niche applications against cheaper alternatives.
- Solvent-Based:Legacy formulations with established performance credentials but declining permit availability in regulated jurisdictions. European facilities face accelerated depreciation as water-based capex requirements collide with restricted solvent throughput permits.
- Water-Based:Polyurethane and acrylic dispersions with VOC content below regulatory thresholds. ECHA substance-of-very-high-concern listings favor pre-registered alternative chemistries, forcing multi-year reformulation timelines. BASF SE leverages integrated polymer intermediate chains to sustain margin capture across these transitions.
- UV-Cured:Rapid-cure systems for electronics and precision manufacturing with minimal thermal substrate exposure.
- High-Performance:Fluoropolymer-modified and ceramic-filled formulations for extreme chemical, thermal, or abrasion resistance.
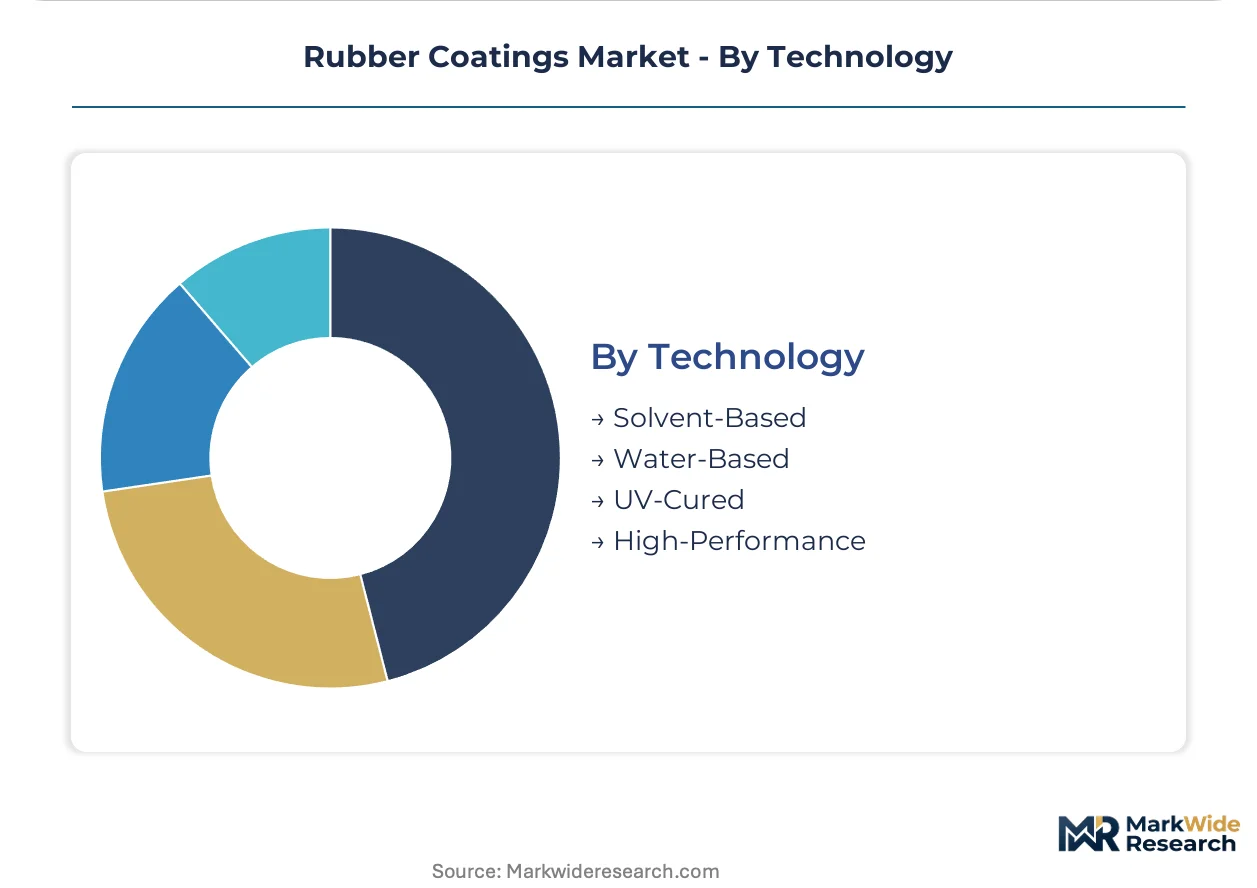
Water-based is climbing the fastest; solvent-based retains cost advantage only where regulation permits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rubber coatings technology first achieved industrial scale in Germany's automotive corridor during the 1960s, establishing the regulatory and technical templates that now govern global formulation standards. Production lineage traces through Stuttgart's Tier-1 supplier networks into contemporary water-based platform migrations.
Germany
Automotive OEM consolidation around Volkswagen, BMW, and Mercedes-Benz drives specification centralization across Wolfsburg, Munich, and Stuttgart assembly belts. REACH Annex XVII substance restrictions force multi-year reformulation cycles among coating compounders serving these platforms. BASF SE anchors supply through Ludwigshafen polymer intermediate integration.
China
Shanghai's industrial corridor concentrates demand from BYD, SAIC, and Tesla Gigafactory underbody protection programs. MIIT dual carbon goals accelerate powder coating adoption for zero-VOC bake cycles. Ningbo and Suzhou coating facilities serve marine and automotive clusters with localized formulation production.
United States
EPA VOC emissions ceilings compress solvent-based throughput permits across Michigan and Ohio automotive supplier parks. PPG Industries maintains captive resin production in Pittsburgh to defend OEM qualification depth. Detroit's Tier-1 suppliers face 18-24 month approval timelines that lock out mid-cycle reformulations.
Japan
Chubu region automotive manufacturers specify integrated electrodeposition-rubber coating lines for NVH reduction in electric vehicle architectures. METI industrial standards favor bake-cycle energy efficiency metrics over standalone chemical performance. Nagoya-based suppliers compress film thickness tolerances below 0.05 mm.
India
Tamil Nadu and Gujarat assembly hubs emerge under PLI scheme electric vehicle incentives, creating coating specification opportunities at emerging manufacturing sites. BIS standards alignment with automotive OEM requirements triggers raw material qualification backlogs. Mumbai distributors fragment procurement across maintenance contractor networks.
Rubber Coatings Market Competitive Landscape
The competitive structure tilts toward integrated chemical conglomerates with captive polymer intermediate chains. Formulation specialists and regional distributors occupy fragmented tiers beneath this apex. Three archetypes dominate: diversified chemical majors with backward integration into resin production, automotive-qualified coating specialists with deep OEM relationships, and regional compounders serving marine and industrial maintenance segments. Capacity expansion and water-based platform licensing constitute the dominant competitive moves.
Among German chemical conglomerates, BASF SE and Wacker Chemie AG exemplify integrated archetypes with polymer intermediate control. PPG Industries occupies a position among North American automotive-qualified specialists with deep OEM nomination depth. AkzoNobel N.V. represents the marine certification density archetype across Baltic and Mediterranean port networks.
| Leading Market Players |
|---|
| BASF SE |
| PPG Industries, Inc. |
| AkzoNobel N.V. |
| 3M Company |
| Huntsman Corporation |
| Axalta Coating Systems |
| The Dow Chemical Company |
| Wacker Chemie AG |
| The Sherwin-Williams Company |
| Others |
Value Network & Pricing Analysis
Naphtha-linked chloroprene monomer pricing cascades through European formulation economics, compressing margin pools at solvent-dependent compounders while rewarding integrated producers with captive polymer intermediate chains. Water-based platform investments absorb capex premiums that tier-1 automotive buyers refuse to shoulder, fragmenting pricing power across qualification-locked supply tiers.
Pricing Analysis
Contract-based long-term offtake agreements dominate automotive OEM nominations, with pricing stratifying across premium, standard, and economy tiers based on certification density and volume scale. REACH compliance grade and captive resin production anchor price differentiation between integrated majors and regional compounders. Cost compression in solvent-based tiers intensifies because feedstock volatility outruns reformulation timelines. Maintenance contractors exhibit highest price sensitivity; marine fleet operators with certificate renewal obligations show lowest.
Supply Chain Analysis
Single-source vulnerability sits with German automotive belt chloroprene feedstock, where Ludwigshafen polymer intermediate concentration creates dependency concentration. Supply draws from Germany, China, and the United States for resin production, with naphtha-derived monomers, polyurethane prepolymers, and specialty plasticizers as critical inputs. Tariff exposure on Chinese-sourced dispersions threatens cost structures for European water-based formulators. Distribution runs through captive OEM supply lines for automotive volume, fragmented distributor networks for maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rubber coatings function as a stable compounder market, with automotive NVH mandates and regulatory substitution cycles providing durable demand anchors across economic cycles.
For Market Incumbents: Anchor platform-level procurement relationships through 18-24 month qualification pipelines ahead of competitor reformulation cycles. Deepen backward integration into polyurethane dispersion production to defend margin capture as REACH Annex XVII restrictions accelerate. Prioritize electrodeposition-rubber integration patents to lock out mid-cycle technology entrants. For New Entrants and Emerging Players: Emerging marine fleet maintenance operators in Baltic and Mediterranean ports present the most penetrable buyer archetype, with certificate renewal fragmentation and batch-size flexibility creating service-model entry points. Target powder coating zero-VOC specifications for Chinese automotive expansion under MIIT dual carbon goals. Pursue toll-manufacturing partnerships with stranded solvent-based assets to bypass capex barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with water-based dispersion specialists possessing pre-registered alternative chemistries ahead of ECHA SVHC listing expansions. Five-to-ten year viability hinges on regulatory substitution durability rather than cyclical volume swings. Watch electrodeposition-rubber line adoption rates at Chubu region automotive manufacturers as inflection signal for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Intermediates | BASF SE and Wacker Chemie AG sustain margin capture across REACH-driven water-based transitions. |
| Electrodeposition-Rubber Line Integration | Tier-1 suppliers in Germany and Japan compress film thickness tolerances below 0.05 mm for electric vehicle NVH targets. |
| Marine Certification Density Investment | AkzoNobel N.V. defends Baltic and Mediterranean port network control through accelerated certificate renewal cycles. |
| Powder Coating Capacity Expansion | Automotive OEMs in Stuttgart and Wolfsburg specify zero-VOC bake cycles for enclosed underbody protection lines. |
| Regional Formulation Licensing | PPG Industries leverages captive Pittsburgh resin production to anchor North American OEM qualification depth. |
Research Methodology
Multiple input streams — technical interviews with coating formulators and plant managers, procurement discussions with Tier-1 automotive suppliers, and regulatory tracking across ECHA and EPA filings — were reconciled against customs data, ACC sector reports, and SEC 10-K disclosures. Bottom-up volume builds across liquid, powder, specialty, and elastic product categories were triangulated with top-down demand estimates from automotive production databases and marine fleet registries.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling technology splits by solvent-based, water-based, UV-cured, and high-performance tiers alongside application dimensions spanning automotive, marine, construction, and electronics. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic drivers, incorporating chloroprene monomer price elasticity and REACH compliance cost pass-through assumptions.
Underlying measurement precision varies by segment; automotive OEM nominations carry tighter precision than fragmented maintenance contractor demand. Forecasts reflect documented assumptions about regulatory substitution timelines and feedstock price normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Abrasion-Resistant Rubber Pipe Market
Rubber
Rubber Compound Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Global Rubber Process Oil Market
Rubber
Rubber Flooring Market
Rubber
Tire Recycling Downstream Products Market
Rubber
Fast Curing Nitrile Butadiene Rubber (NBR) Market
Rubber
Rubber Bulb Seals Market
Rubber
Europe Silicone Rubber Market
Rubber
Rubber Ropes Market
Rubber
Global Rubber Vulcanization Market
Rubber
Liquid Silicone Rubber Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Global Rubber Additives Market
Rubber
Tire Softener Market