
 Europe Neoprene Market | 2026-2036
Europe Neoprene Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Neoprene Market Intelligence
European chloroprene rubber producers is pivoting toward specialized grades for electric vehicle thermal management systems. ARLANXEO leverages its integrated polymerization assets in Germany to sustain supply continuity for automotive OEMs. Denka Company Limited anchors its position through advanced chloroprene process technology developed at its Japanese parent facilities. Tosoh Corporation competes on high-purity neoprene variants suited to medical and industrial glove applications.
Neoprene denotes a family of synthetic rubbers produced by polymerizing chloroprene, typically exhibiting oil resistance across temperature ranges from minus 35 to 100 degrees Celsius and tensile strength between 7 and 21 megapascals depending on filler loading. Manufacturers compound it with carbon black or silica to achieve specific hardness ratings for gasket, hose, and protective equipment production. Solid neoprene commands the dominant share of product type value owing to its established specification sheets and converter familiarity across European industrial channels. Neoprene foam is gaining fastest in sports equipment and consumer padding applications where weight reduction and moisture resistance differentiate performance.
REACH registration requirements enforced by ECHA mandate full substance dossiers for chloroprene monomer and polymer imports, raising compliance costs for non-EU suppliers. The EU F-Gas Regulation and broader Green Deal industrial transition frameworks are redirecting formulation R&D toward lower-emission curing systems and bio-based feedstock exploration. Stakeholders must monitor evolving substance restriction proposals under REACH and assess whether captive chloroprene production or strategic toll-compounding partnerships offer more resilient margin protection.
Market Dynamics
EU REACH substance restrictions and the F-Gas Regulation are compressing formulation options while redirecting R&D investment toward compliant curing systems and bio-based feedstock pathways across European chloroprene rubber supply chains.
Growth Catalysts
- Electric vehicle thermal management demand:Solid neoprene grades are penetrating battery pack sealing and cooling loop gasket applications as German and French automotive OEMs scale EV platform production.
- REACH compliance services:ECHA registration mandates for chloroprene monomer and polymer imports are creating recurring revenue streams for European toll compounders with established dossier capabilities.
- Sports equipment specification upgrades:Moisture-resistant neoprene foam is displacing conventional padding in cycling and watersports gear where weight reduction commands premium positioning.
Market Restraints
- Chloroprene monomer supply concentration:European producers depend on a limited set of integrated polymerization assets, with ARLANXEO's German facilities representing critical supply continuity risk.
- EPDM substitution in automotive cooling:Ethylene-propylene rubber compounds are capturing share in lower-temperature gasket applications where oil resistance specifications relax.
- REACH registration cost escalation:Full substance dossier requirements for imports raise fixed compliance burdens that disproportionately burden smaller compounders without captive chloroprene production.
Strategic Opportunities
- Medical glove specification migration:High-purity neoprene variants suited to surgical and industrial hand protection remain underpenetrated in Eastern European healthcare procurement channels.
- EU Green Deal formulation incentives:Bio-based feedstock exploration and lower-emission curing system development align with industrial transition framework funding mechanisms.
- EV battery recycling infrastructure:Closed-loop material recovery programs for end-of-life gaskets and seals create circular economy service revenue potential for compounders with reverse logistics capabilities.
Industry Challenges
- Specialized polymerization engineering scarcity:Chloroprene process technology expertise concentrates at legacy facilities, constraining workforce expansion for capacity scaling projects.
- Multi-jurisdiction certification timelines:Medical device grade approvals require parallel EMA and notified body pathways that extend commercialization cycles for new compound formulations.
- Legacy compounding equipment retrofit costs:Lower-emission curing system adoption demands capital-intensive reactor modifications that compress margins for mid-scale European processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Neoprene Market |
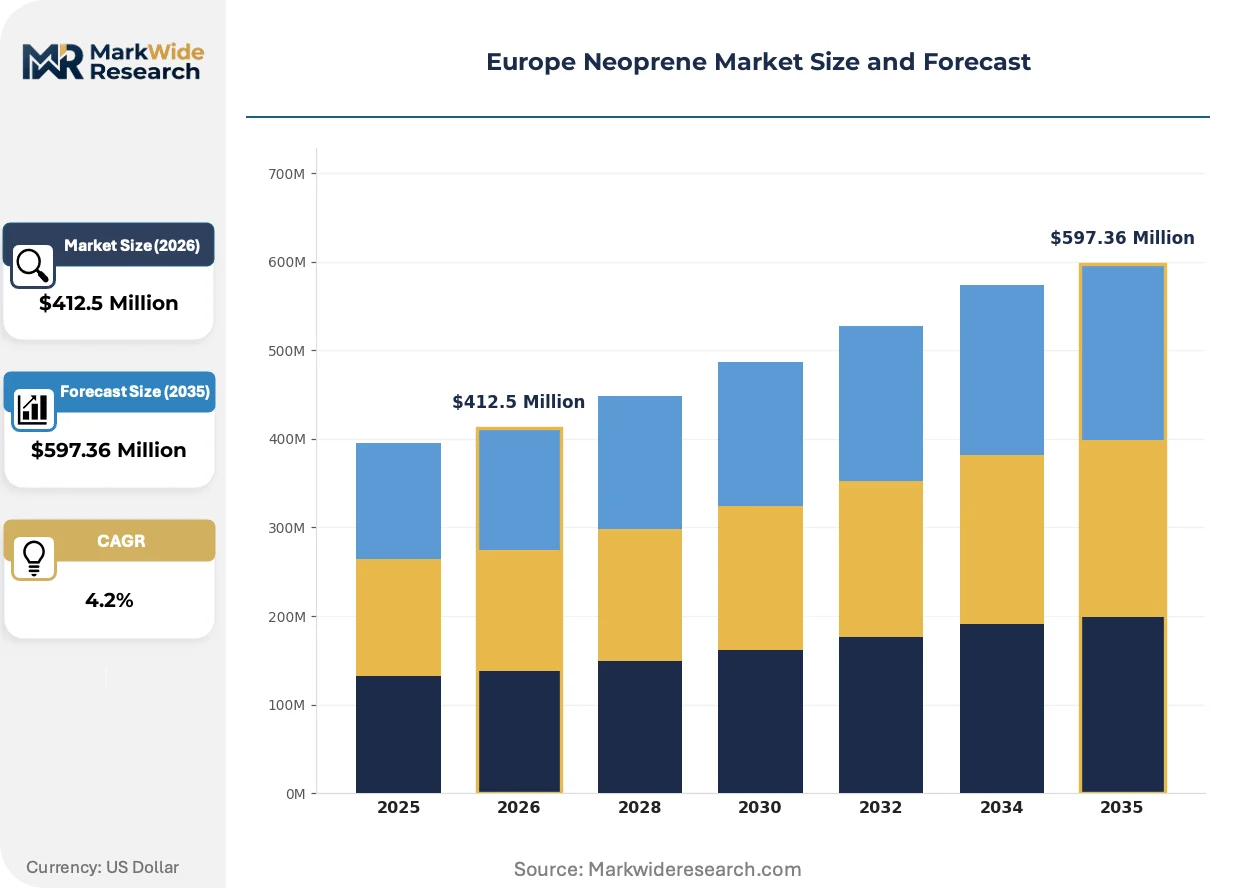
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $597.36 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neoprene Foam, Neoprene Rubber, Solid Neoprene, Neoprene Sheets Application: Automotive, Sports Equipment, Industrial Products, Consumer Goods End User: Manufacturers, Retailers, Wholesalers, Exporters Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Outlets |
| Companies Covered | Sundow Polymers, Mueller Sports Medicine, Denka Company Limited, Macro Products, ARIAPRENE, ARLANXEO, Ansell, Neoprene Craft Hub, Tosoh Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Neoprene Market Strategic Shifts & Innovations
Formulation chemistry and procurement specifications are diverging simultaneously. Material engineers are developing novel compound architectures while buyers restructure supplier relationships around compliance documentation and carbon accounting transparency.
Advanced chloroprene polymerization with precise molecular weight distribution control is electrifying specification possibilities for automotive OEMs demanding tighter compression set performance in EV battery sealing. German and French thermal management system suppliers are accelerating qualification timelines for these grades. The technology is compressing the performance gap between standard neoprene and higher-cost fluoroelastomer alternatives in moderate temperature applications.
EU F-Gas Regulation phase-down schedules are forcing reformulation of blowing agent systems in neoprene foam production. Manufacturers are pivoting toward hydro-olefin and other low-global-warming-potential alternatives for sports equipment and consumer padding applications. French and Italian molding houses are absorbing the steepest compliance costs as they retool continuous production lines.
Automotive procurement teams are consolidating supplier panels around integrated compounders capable of delivering REACH-compliant material certification bundled with Scope 3 carbon reporting. Tier-1 gasket manufacturers are displacing fragmented toll-compounding relationships in favor of strategic partnerships with polymerization-integrated processors. This concentration is most visible in German industrial corridors where Volkswagen and BMW procurement specifications now mandate single-source accountability for full material chain-of-custody documentation.
Europe Neoprene Market Segmentation
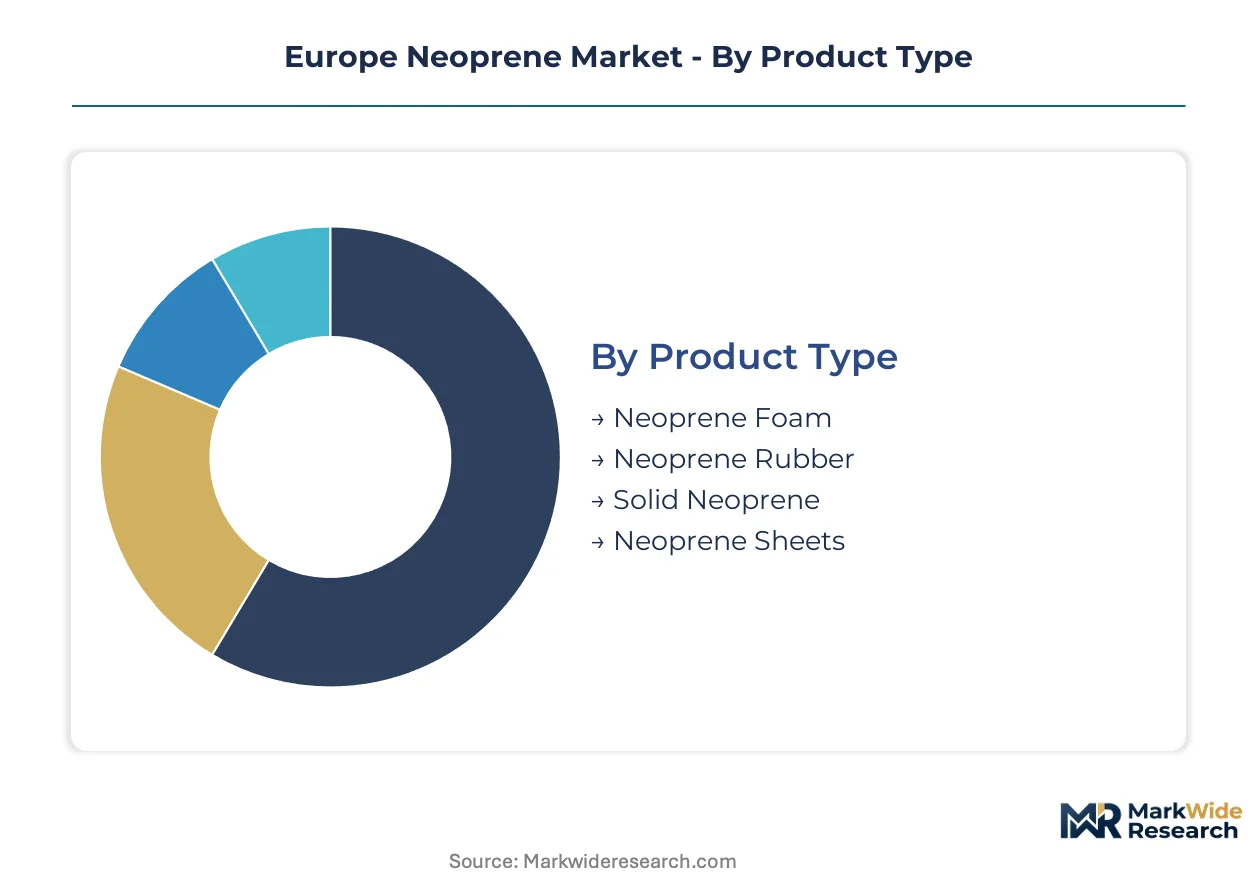
Neoprene specification diversity across European industrial channels demands precise segment targeting. Procurement teams in German automotive corridors and French supplier clusters prioritize distinct material grades, while REACH compliance requirements reshape channel economics for each product category.
Product Type:
Upgrade cycles in thermal management sealing and protective equipment specifications are redefining procurement priorities across European compounders.
- Solid Neoprene:Dense vulcanized rubber with tensile strength between 7 and 21 megapascals serves gasket and hose specifications. German automotive OEMs specify this grade for EV battery pack sealing as compression set performance tightens.
- Neoprene Foam:Cellular chloroprene rubber with hydro-olefin blowing agents displaces conventional padding. French and Italian sports equipment manufacturers absorb reformulation costs to meet EU F-Gas Regulation phase-down schedules.
- Neoprene Rubber:General-purpose polymerized chloroprene compounds serve industrial maintenance applications. Toll compounders in Eastern Europe process bulk volumes for machinery belting and conveyor specifications.
- Neoprene Sheets:Calendered or extruded flat stock enables converter fabrication of custom gaskets and protective barriers. Wholesale distributors stock standard thicknesses for maintenance procurement channels.
Solid Neoprene sits at the top of the volume ranking, with Neoprene Foam climbing the fastest.
Application:
Cost tier differentiation separates specification-grade procurement from commodity replacement cycles across European demand channels.
- Automotive:Thermal management system suppliers specify advanced chloroprene grades for battery sealing and cooling loop gaskets. ARLANXEO's integrated German polymerization assets anchor supply continuity for Volkswagen and BMW procurement panels.
- Sports Equipment:Moisture-resistant foam padding penetrates cycling and watersports gear where weight reduction commands premium positioning. French molding houses retool continuous production lines for low-global-warming-potential blowing agent compliance.
- Industrial Products:Hose, belting, and machinery sealing applications consume standard compounded grades. REACH registration dossiers for chloroprene monomer imports raise fixed compliance burdens for smaller processors.
- Consumer Goods:Protective cases, laptop sleeves, and lifestyle accessories drive sheet and foam demand. Online direct-to-consumer channels bypass traditional distributor markups for these applications.
Automotive commands the largest application share, though Sports Equipment exhibits the steepest specification upgrade trajectory.
End User:
Customer type concentration shapes margin structures and contract terms across European supply chains.
- Manufacturers:Tier-1 gasket producers and OEM direct suppliers negotiate REACH-compliant material certification bundled with Scope 3 carbon reporting. Single-source accountability requirements consolidate procurement panels around polymerization-integrated processors.
- Retailers:Sports equipment and consumer goods channels stock standard sheet and foam thicknesses for maintenance and hobbyist demand. Inventory turns accelerate for moisture-resistant foam grades in cycling seasonality.
- Wholesalers:Industrial distribution networks aggregate fragmented compounder output for machinery maintenance procurement. Eastern European channels show underpenetration for high-purity medical-grade specifications.
- Exporters:Non-EU destination markets drive toll-compounding volume for customers without captive chloroprene production. ECHA registration mandates raise barriers for smaller export-focused processors.
Manufacturers dominate procurement value, with Retailers gaining share in sports equipment specification upgrades.
Distribution Channel:
Supply concentration in polymerization-integrated processors redirects channel economics toward direct relationships.
- Direct Sales:Automotive OEMs and Tier-1 suppliers mandate full material chain-of-custody documentation. German industrial corridors show the most pronounced shift away from fragmented toll-compounding relationships.
- Distributors:Industrial maintenance channels aggregate standard grades from multiple compounders. REACH compliance services create recurring revenue streams for distributors with established ECHA dossier capabilities.
- Online Sales:Consumer goods and sports equipment segments bypass traditional markups through direct-to-consumer platforms. Sheet stock and foam padding specifications dominate this channel.
- Retail Outlets:Hobbyist and small-scale maintenance procurement accesses pre-cut sheet and standard hose sizes. Geographic coverage concentrates in French and Italian molding house proximity zones.
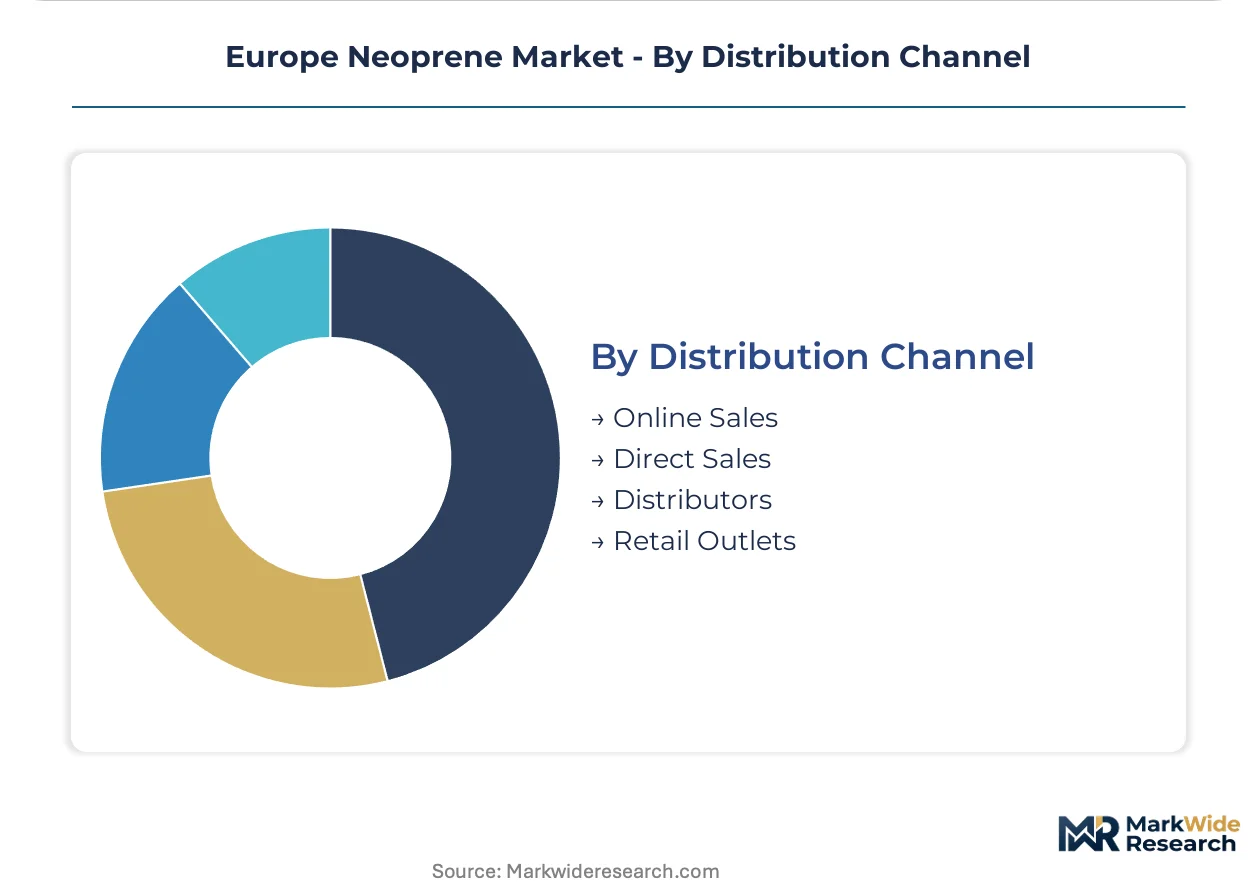
Direct Sales captures the highest value concentration, while Online Sales expands most quickly in consumer-facing segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates polymerization assets while France specializes in molding applications. The regulatory divergence between REACH implementation and national industrial policies creates distinct competitive conditions across European industrial corridors.
Germany
Automotive OEM procurement panels at Volkswagen and BMW mandate REACH-compliant material certification with Scope 3 carbon reporting. The EU F-Gas Regulation drives reformulation of blowing agent systems in foam production. The North Rhine-Westphalia and Bavaria industrial corridors host integrated polymerization facilities serving battery sealing and thermal management specifications.
France
Sports equipment manufacturers specify moisture-resistant neoprene foam for cycling and watersports gear where weight reduction commands premium positioning. ANSM medical device regulations extend approval timelines for surgical glove formulations. The Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur molding house clusters absorb capital-intensive retooling costs for low-global-warming-potential compliance.
Italy
Industrial distribution networks aggregate compounded grades for machinery belting and conveyor specifications. CE marking requirements for protective equipment create certification barriers for non-EU import competition. The Lombardy and Emilia-Romagna manufacturing belts concentrate toll-compounding capacity for maintenance procurement channels.
United Kingdom
Post-Brexit REACH divergence creates parallel substance registration obligations for chloroprene monomer and polymer imports. The Health and Safety Executive enforces workplace exposure limits distinct from ECHA guidelines. The Midlands and North England industrial zones maintain converter fabrication capacity for custom gasket and protective barrier applications.
Poland
Eastern European machinery maintenance procurement channels show underpenetration for high-purity medical-grade specifications. Polish national chemical regulator assessments align with ECHA dossier standards while maintaining independent enforcement timelines. The Silesian and Greater Poland industrial regions process bulk compounded volumes for conveyor belting and hose applications.
Europe Neoprene Market Key Industry Players
German producers anchor one tier; Japanese specialists hold differentiated positions in high-purity variants. The vendor base concentrates around integrated polymerization assets and toll-compounding relationships, with procurement consolidation favoring processors capable of full chain-of-custody documentation. Three archetypes dominate: polymerization-integrated compounders, specialized medical-grade formulators, and regional toll processors serving maintenance channels. Capacity expansion and strategic partnerships represent the dominant competitive moves as automotive OEMs consolidate supplier panels.
Within the integrated polymerization tier, ARLANXEO exemplifies supply continuity positioning for automotive OEM procurement panels. Among Japanese-based formulators, Denka Company Limited and Tosoh Corporation occupy positions distinguished by advanced chloroprene process technology and high-purity variant capabilities respectively. These three entities represent the structural concentration around which European compounder relationships reorganize.
| Leading Market Players |
|---|
| Sundow Polymers |
| Mueller Sports Medicine |
| Denka Company Limited |
| Macro Products |
| ARIAPRENE |
| ARLANXEO |
| Ansell |
| Neoprene Craft Hub |
| Tosoh Corporation |
| Others |
Cost & Logistics Intelligence
Advanced chloroprene polymerization with precise molecular weight distribution control is compressing cost economics for automotive-grade neoprene while simultaneously concentrating supply among integrated German producers with captive polymerization assets. This technology shift tightens specification possibilities for EV battery sealing applications and raises capital barriers for smaller compounders without backward integration into chloroprene monomer production.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for solid neoprene grades as ARLANXEO's integrated polymerization assets anchor supply continuity for automotive OEM procurement panels. Pricing stratifies across REACH-certified premium grades, standard industrial specifications, and economy-tier bulk compounds for maintenance channels. Price differentiation hinges on compression set performance ratings and ECHA dossier completeness. Cost compression in economy-tier rubber is intensifying because EPDM substitution captures share in lower-temperature gasket applications. Tier-1 automotive suppliers show least price sensitivity due to single-source accountability mandates, while Eastern European toll compounders face greatest pressure from registration cost escalation.
Supply Chain Analysis
Dual-sourcing qualification requirements from Volkswagen and BMW procurement panels are fragmenting supplier relationships across polymerization-integrated processors and specialized toll compounders. Supply concentrates in Germany, France, and Italy, with German facilities anchoring chloroprene monomer production and French molding houses dominating foam fabrication. Raw material dependencies rest on chloroprene monomer, carbon black fillers, and hydro-olefin blowing agents. Single-source vulnerability concentrates around ARLANXEO's German polymerization assets. Distribution runs through direct sales channels for automotive OEMs and industrial distributors for maintenance procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe neoprene functions as a stable compounder market where electric vehicle thermal management specifications drive steady specification-grade demand. REACH compliance requirements and F-Gas Regulation phase-down schedules create durable barriers protecting integrated producers with established dossier capabilities.
For Market Incumbents: Anchor supply continuity positioning through polymerization asset maintenance and ECHA registration dossier expansion. Defend against EPDM substitution in automotive cooling by tightening compression set performance specifications for EV battery sealing. Prioritize backward integration into chloroprene monomer production or captive toll-compounding partnerships to protect margin structures from registration cost escalation. For New Entrants and Emerging Players: Begin with high-purity medical-grade neoprene specifications in Eastern European healthcare procurement channels where ANSM and national regulator approvals remain underpenetrated. Target sports equipment foam applications where moisture-resistant grades command premium positioning and French molding house retooling creates temporary supply gaps. Pursue toll-compounding relationships with established ECHA dossier capabilities rather than greenfield polymerization investments. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale toll compounders without captive chloroprene production facing REACH registration cost burdens. Long-term viability centers on processors with reverse logistics capabilities for EV battery recycling infrastructure and circular economy service revenue. Watch for inflection in EU Green Deal formulation incentives redirecting R&D funding toward bio-based feedstock exploration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chloroprene Monomer | Captive polymerization supply protects margins from ECHA registration cost escalation for imports. |
| REACH Dossier Service Expansion | Recurring compliance revenue streams compound around ECHA registration mandates for non-EU suppliers. |
| Hydro-Olefin Blowing Agent Transition | F-Gas Regulation compliance preserves access to French and Italian sports equipment molding contracts. |
| Medical-Grade Certification Investment | ANSM and EMA parallel pathways unlock Eastern European surgical glove procurement channels. |
| Reverse Logistics Partnership | Closed-loop material recovery for end-of-life EV gaskets creates circular economy service differentiation. |
Research Approach
Multiple input streams — technical discussions with chloroprene plant managers and R&D directors, procurement interviews at German automotive Tier-1 suppliers, and distributor channel assessments — were reconciled against trade flow data, ECHA registration databases, and SEC filings from polymerization-integrated producers. Primary engagement spanned compounder technical directors, REACH compliance consultants, and sports equipment molding house operators. Secondary validation drew from customs records, EU F-Gas Regulation implementation reports, and Cefic chemical industry statistics. Bottom-up volume builds and top-down market sizing were triangulated for convergence.
Data-stream reconciliation across product type, application, and end-user dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated grade tier differentiation, regional production hub concentration, and compliance certification status. CAGRs were derived from trend extrapolation of specification-grade penetration rates and substitution elasticity estimates. Forecast inputs included EV platform production schedules and REACH substance restriction proposal timelines.
Several conditions sit outside the modeled scope, including abrupt chloroprene monomer supply disruptions, accelerated EPDM formulation advances, and unilateral national REACH divergences beyond current ECHA frameworks. Forecasts reflect documented assumptions about regulatory implementation pacing and automotive OEM procurement consolidation trajectories. Deviation in EU Green Deal funding allocation or F-Gas Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Rubber Vulcanization Market
Rubber
Rubber Splicing Tape Market
Rubber
Rubber Conveyor Belt Market
Rubber
Co-Extruded Rubber Profiles Market
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Rubber Chemicals Market
Rubber
Rubber Bulb Seals Market
Rubber
Global Crumb Rubber Market
Rubber
Medical Rubber and Balloon Products Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
Global Thermoplastic Vulcanizate (TPV) Market
Rubber
Global Chloroprene Rubber Market