
 Global Rubber Process Oil Market | 2026-2036
Global Rubber Process Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rubber Process Oil Market Foresight
Vegetable oil is broadening its addressable share in rubber compounding as refiners adapt hydro-treatment pathways to match paraffinic performance benchmarks. Exxon Mobil Corporation leverages integrated refining and lubricant base stock operations to sustain cost-advantaged supply of high-viscosity aromatic grades across Asian tire hubs. Shell plc anchors its position through specialty fluids R&D, while Nynas AB competes on naphthenic purity tailored to EPDM and butyl rubber specifications.
Rubber process oil denotes a petroleum-derived or bio-based hydrocarbon fluid blended with natural or synthetic rubber to reduce viscosity, improve filler dispersion, and control cure kinetics during milling and extrusion; typical products span aromatic extracts with 20-35% polycyclic aromatic content, naphthenic distillates with ring structures exceeding 30%, paraffinic oils with viscosity indices above 95, and vegetable-derived esters with pour points below minus twenty degrees Celsius. Aromatic oil still occupies the largest volume share in tire tread formulations where high glass-transition compatibility governs wet grip performance, yet paraffinic oil represents the fastest-expanding category as EPDM roofing and hose producers prioritize ozone resistance and color stability. Vegetable oil concentrates margin pools among adhesive suppliers and footwear producers seeking biobased content claims and reduced regulatory exposure.
The EPA enforces benzene and PAH emission thresholds at US refineries, while REACH and the EU Green Deal constrain aromatic oil import volumes into European compounding facilities. China's MEE implements GB standards on volatile organic compound discharge from rubber processing plants, tightening local formulation requirements. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional blending capacity or certified low-PAH imports offer the more durable supply pathway.
Market Dynamics
REACH restrictions on polycyclic aromatic hydrocarbons are compressing aromatic oil volumes in European compounding while accelerating hydro-treated naphthenic and vegetable oil substitution across tire and industrial rubber formulations.
Growth Catalysts
- Automotive production scaling in India and Thailand:Tire manufacturers in these countries are expanding procurement of naphthenic and paraffinic grades to feed domestic vehicle assembly plants and export-oriented rubber goods production.
- EPDM roofing and hose demand:Construction and infrastructure sectors are specifying paraffinic oils for ozone resistance and color stability in synthetic rubber applications, displacing aromatic alternatives in weather-exposed products.
- MEE GB standards enforcement:China's Ministry of Ecology and Environment is tightening volatile organic compound discharge limits from rubber processing plants, driving formulation upgrades toward low-emission process oils.
Market Restraints
- Crude oil feedstock volatility:Petroleum-derived rubber process oils remain exposed to naphtha and vacuum gas oil price swings that compress blender margins and destabilize contract pricing.
- Refinery capacity concentration:High-viscosity aromatic and naphthenic base stock production clusters in select coastal refining hubs, creating geographic supply risk for inland compounders.
- REACH authorization timelines:European compounders face extended transition periods for PAH-compliant oil substitution, delaying full formulation conversion and locking in dual inventory costs.
Strategic Opportunities
- Bio-based content mandates in EU Green Deal frameworks:Vegetable oil esters qualify for renewable content credits in automotive and footwear supply chains, opening premium pricing tiers for certified bio-based formulations.
- Underpenetrated footwear adhesive segment:Solvent-free adhesive manufacturers in Vietnam and Indonesia are sourcing vegetable-derived process oils to meet brand sustainability specifications and reduce regulatory exposure.
- Hydro-treatment technology convergence:Refiners combining catalytic dewaxing with severe hydro-cracking are producing paraffinic oils that match aromatic performance in tire tread compatibility tests.
Industry Challenges
- Formulation revalidation timelines:Compounders must complete cure kinetics and filler dispersion testing for each oil substitution, extending product qualification cycles by six to twelve months.
- Cross-border certification complexity:Low-PAH certificates accepted by ECHA may not satisfy India's BIS import requirements or China's GB testing protocols, forcing redundant laboratory analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rubber Process Oil Market |
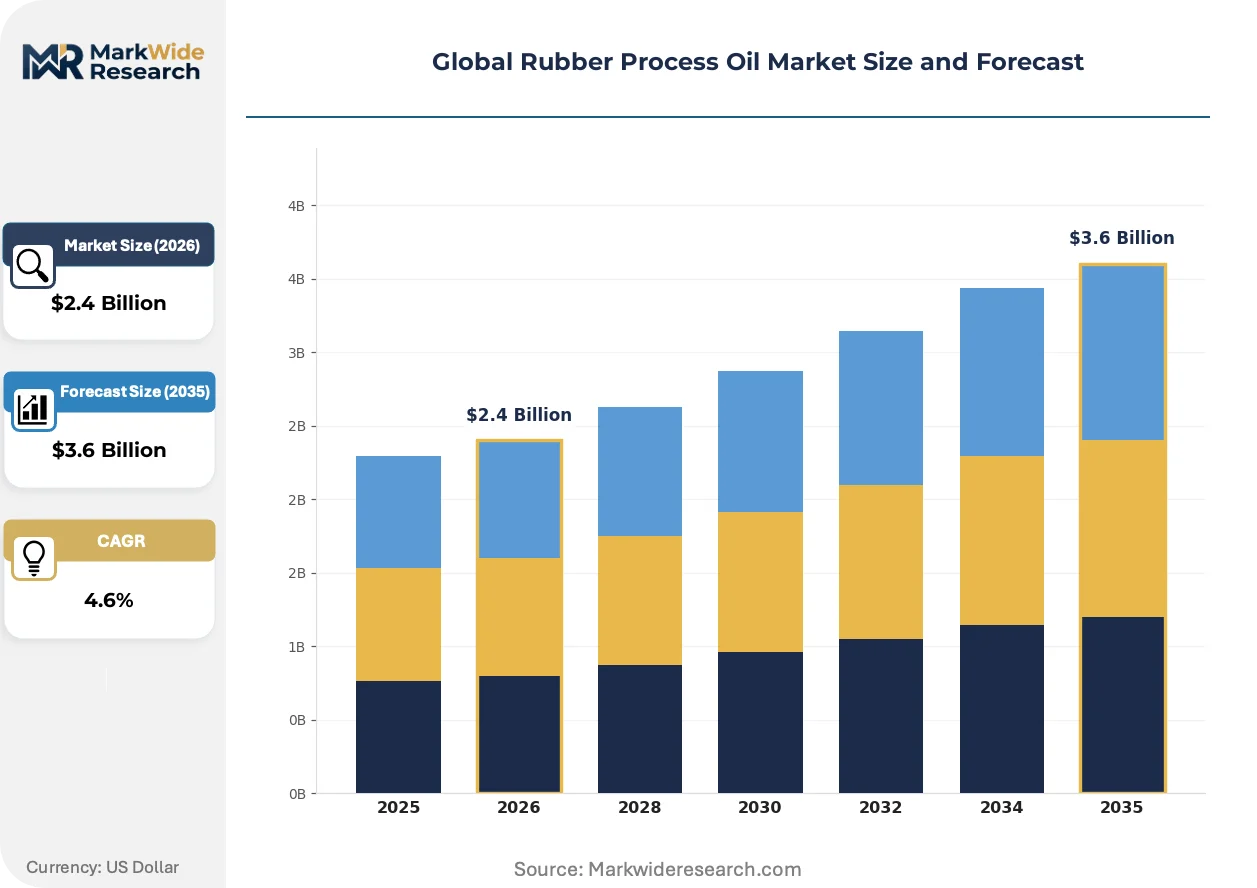
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.6 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aromatic Oil, Naphthenic Oil, Paraffinic Oil, Vegetable Oil Application: Tire, Footwear, Adhesives, Industrial Rubber Products End User Industry: Automotive Component Manufacturers, Footwear Producers, Adhesive Suppliers, Manufacturing Plants Packaging Type: Drums, Bulk Containers, Totes, Intermediate Bulk Containers |
| Companies Covered | Sinopec, Exxon Mobil Corporation, PetroChina Company Limited, Shell plc, Chevron Corporation, TotalEnergies, Idemitsu Kosan, H&R Group, Nynas AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rubber Process Oil Market Shifts & Advancements
Hydro-treated vegetable oil formulations are unifying performance benchmarks across previously segmented product categories, while regulatory stringency in multiple jurisdictions forces simultaneous compliance with divergent chemical safety standards.
Advanced hydro-treatment is unifying the performance gap between vegetable-derived esters and petroleum-based paraffinic oils. Tire manufacturers in Germany and Japan are qualifying these bio-based alternatives for tread compounds previously reserved for aromatic extracts. This unification is compressing the traditional premium commanded by naphthenic distillates in high-performance applications.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are forcing compounders to abandon conventional aromatic extracts for tire production. The industrial consequence is accelerated investment in severe hydro-cracking capacity at European refineries. Tire tread formulators serving the replacement market are most affected, responding with dual-sourcing strategies that blend certified low-PAH imports with regional hydro-treated production.
Specification-driven procurement is consolidating buyer power among tier-one tire manufacturers and automotive OEMs. Distributors and independent compounders face margin compression as direct refiner relationships displace intermediate blending operations. This consolidation is most visible in Thailand and China, where domestic tire producers have established captive supply agreements with regional base stock refiners.
Global Rubber Process Oil Market Segmentation
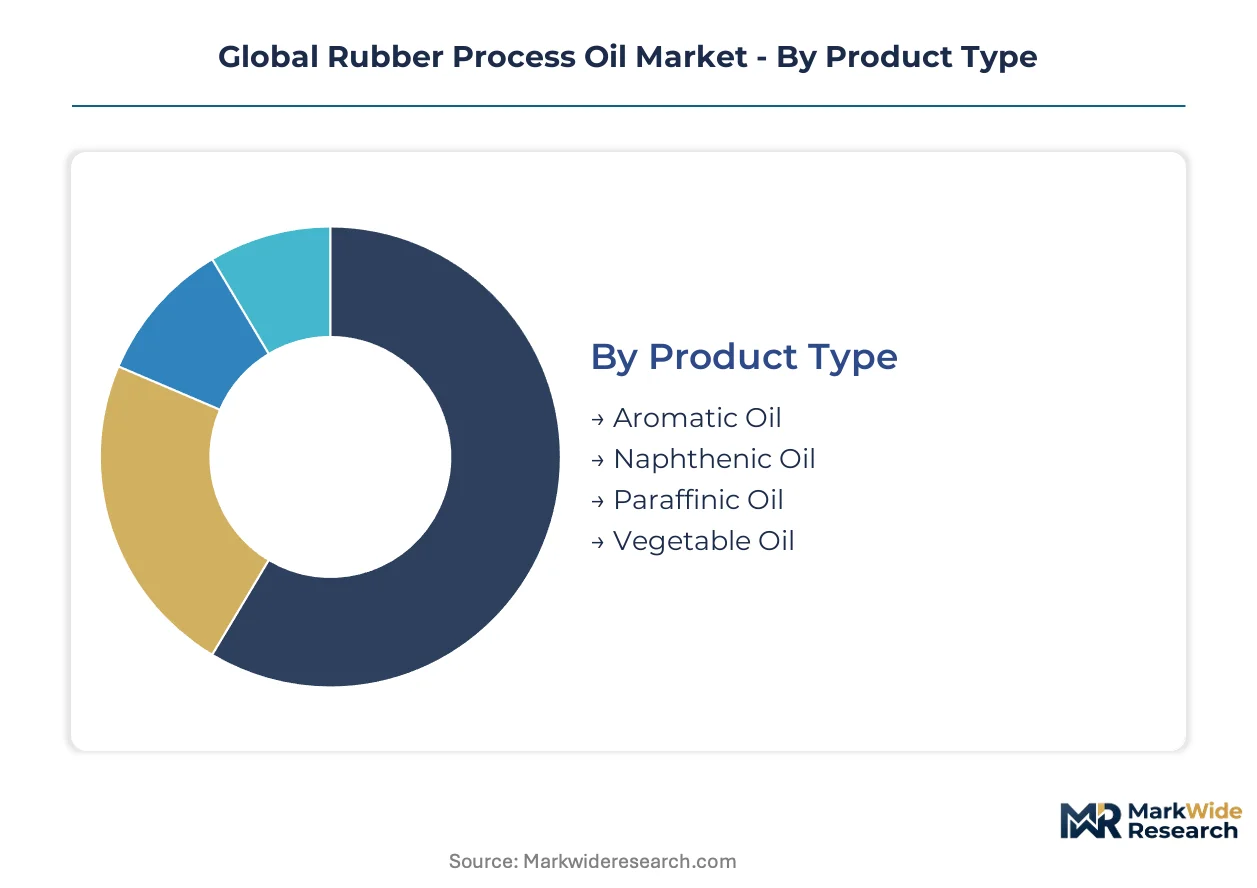
Rubber process oil segmentation reveals how technical specifications, logistics economics, and regulatory compliance intersect to determine procurement patterns. Each dimension carries distinct margin implications and supply chain requirements that compounders must navigate.
Product Type:
Product classification hinges on hydrocarbon structure, aromatic content, and viscosity index, which govern compatibility with specific elastomer formulations and end-use performance requirements.
- Aromatic Oil:Petroleum-derived extract containing 20-35% polycyclic aromatic hydrocarbons delivers superior glass-transition compatibility for tire tread wet grip. REACH restrictions in Europe and MEE GB standards in China are compressing volumes as compounders reformulate toward compliant alternatives.
- Paraffinic Oil:Severely hydro-treated distillates with viscosity indices exceeding 95 provide ozone resistance and color stability essential for EPDM roofing membranes and automotive hoses. Demand is climbing fastest in Thailand and India where construction and vehicle assembly are scaling simultaneously.
- Naphthenic Oil:Ring-structured distillates with 30%+ cycloparaffin content optimize filler dispersion in butyl rubber inner liners and EPDM weatherstripping.
- Vegetable Oil:Hydro-treated esters with pour points below minus twenty degrees Celsius qualify for EU Green Deal renewable content credits in footwear and adhesive applications.
Mature deployment sits with aromatic oil in legacy tire tread formulations. Newer deployment is concentrated in vegetable oil for sustainability-certified supply chains.
Application:
Application segmentation tracks how performance specifications, exposure conditions, and regulatory scrutiny vary across end-use categories.
- Tire:Tread compounds demand high-aromatic compatibility for wet traction, while sidewalls and inner liners specify naphthenic or paraffinic grades for flex resistance and air retention. Indian and Thai tire manufacturers are expanding procurement of low-PAH alternatives to serve export markets.
- Industrial Rubber Products:EPDM roofing, hose, and sealing applications specify paraffinic oils for UV stability and ozone resistance. Construction booms in Southeast Asia are accelerating volume growth in this segment.
- Footwear:Solvent-free adhesive bonding and sole compounding favor vegetable-derived oils to meet brand sustainability specifications and reduce regulatory exposure.
- Adhesives:Pressure-sensitive and hot-melt formulations require low-volatility process oils with precise viscosity control for coating uniformity.
Volume concentration remains with tire manufacturing. Margin expansion is shifting toward industrial rubber products as construction specification tightens.
End User Industry:
Customer type segmentation reflects divergent procurement power, technical sophistication, and compliance burden across the value chain.
- Automotive Component Manufacturers:Tier-one suppliers and OEM captive plants specify certified low-PAH oils with full chain-of-custody documentation. Direct refiner relationships are displacing distributor intermediaries in Thailand and China.
- Manufacturing Plants:General industrial rubber goods producers balance cost and performance across aromatic, naphthenic, and paraffinic grades depending on export destination requirements.
- Footwear Producers:Vietnam and Indonesia-based manufacturers source vegetable oil esters to satisfy EU and US brand sustainability audits.
- Adhesive Suppliers:Solvent-free formulation specialists prioritize low-emission process oils with consistent viscosity profiles for automated coating lines.
Procurement consolidation is most advanced among automotive component manufacturers. Fragmentation persists in manufacturing plants serving regional industrial markets.
Packaging Type:
Packaging economics hinge on volume scale, handling infrastructure, and contamination risk across diverse customer facilities.
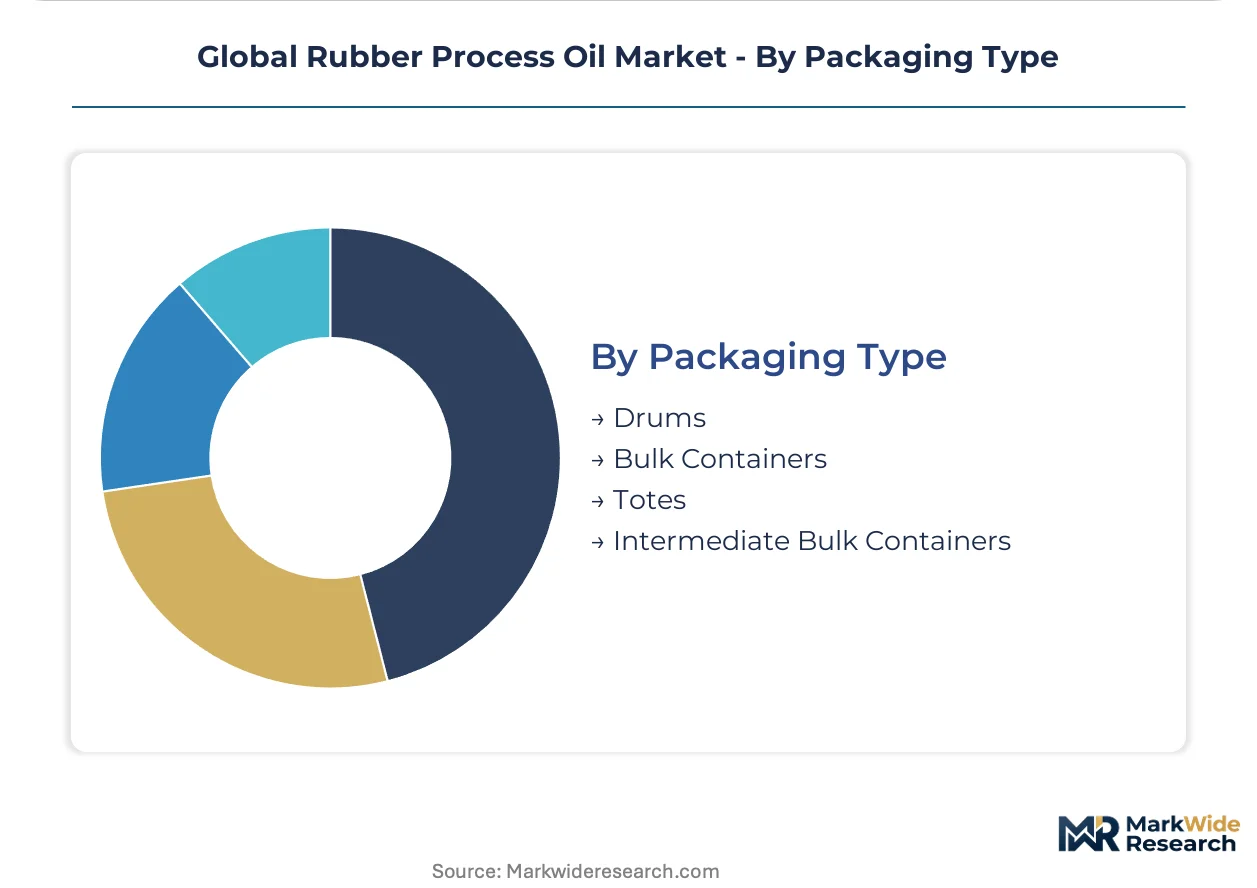
- Bulk Containers:Rail and vessel-delivered volumes serve high-throughput tire plants and refinery-adjacent compounders with dedicated storage and handling systems. Coastal refining hubs in China and Thailand anchor this format.
- Intermediate Bulk Containers:Flexible and rigid IBCs balance logistics efficiency with reduced contamination risk for mid-scale compounders lacking bulk infrastructure.
- Drums:Steel and polymer drums serve small-batch compounders, specialty formulators, and adhesive manufacturers requiring frequent grade changes and precise inventory control.
- Totes:Intermediate volume solutions support footwear and adhesive producers with moderate consumption rates and limited storage capacity.
Format concentration aligns with customer scale. Bulk infrastructure investment is tracking tire manufacturing expansion in India and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, India, and Thailand concentrate rubber process oil procurement as tire manufacturing clusters expand and domestic vehicle assembly scales. Regulatory divergence across jurisdictions is fragmenting supply pathways, with compounders in each market navigating distinct emission thresholds and import certification requirements.
China
MEE GB standards on volatile organic compound discharge are tightening formulation requirements at rubber processing plants in Shandong and Jiangsu provinces. The Yangtze River Delta hosts the densest concentration of domestic base stock refineries serving captive tire producer agreements. Domestic compounders are upgrading hydro-treatment capacity to meet both local emission limits and export market low-PAH specifications.
India
Automotive production scaling in Chennai and Pune is driving naphthenic and paraffinic grade procurement from domestic tire manufacturers. BIS import requirements for rubber process oils are creating certification complexity for European and Middle Eastern suppliers seeking market access. Gujarat's petroleum refining corridor is expanding hydro-cracking infrastructure to reduce dependence on aromatic oil imports.
Thailand
EPDM roofing and hose demand from Bangkok's construction sector is accelerating paraffinic oil consumption for ozone-resistant formulations. The country's Board of Investment incentives for petrochemical downstream expansion are attracting regional base stock investment. Eastern Economic Corridor industrial zones are consolidating tire manufacturing and rubber goods production within integrated supply chains.
Germany
REACH Annex XVII PAH restrictions are compressing aromatic oil volumes and accelerating severe hydro-cracking investment at northwestern refineries. KBA automotive standards are propagating low-PAH requirements through tier-one supplier specifications. The Ruhr industrial region's compounders are dual-sourcing certified imports and regional hydro-treated production to manage transition timelines.
United States
EPA benzene and PAH emission thresholds at Gulf Coast refineries are constraining high-aromatic base stock output for domestic tire tread formulators. Texas and Louisiana petrochemical hubs maintain the largest hydro-treatment capacity for paraffinic grade production. Midwest automotive belt compounders are negotiating direct supply agreements with integrated refiners to bypass distributor intermediaries.
Global Rubber Process Oil Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petroleum majors dominating high-volume aromatic and naphthenic supply while independent blenders capture niche bio-based formulations. The vendor base organizes into three archetypes: integrated refiners with captive base stock positions, specialty fluid producers focusing on low-PAH and hydro-treated grades, and regional compounders with backward integration into blending operations. Consolidation is most visible among tire-facing suppliers, where direct refiner relationships are displacing distributor channels. Competitive moves center on hydro-treatment capacity expansion and sustainability certification acquisition.
Among integrated petroleum majors, Exxon Mobil Corporation and Shell plc anchor the high-volume supply tier through integrated refining and lubricant base stock operations. Sinopec exemplifies the national champion archetype with domestic market concentration and downstream tire industry captive relationships. Nynas AB occupies a position within the specialty fluid segment, competing on naphthenic purity for EPDM and butyl rubber specifications. These three company types represent the structural segmentation of supply capacity across aromatic, paraffinic, and bio-based grade categories.
| Leading Market Players |
|---|
| Sinopec |
| Exxon Mobil Corporation |
| PetroChina Company Limited |
| Shell plc |
| Chevron Corporation |
| TotalEnergies |
| Idemitsu Kosan |
| H&R Group |
| Nynas AB |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between low-PAH hydro-treated formulations and conventional aromatic extracts manifests in dual pricing architectures and divergent procurement pathways. Premium tiers command sustained margins through REACH-compliant documentation and automotive OEM qualification, while commodity aromatic grades face compression from regulatory displacement and feedstock volatility.
Pricing Analysis
Volume-vs-margin split separates high-throughput tire manufacturers negotiating long-term offtake contracts from specialty compounders purchasing certified low-PAH grades in smaller lots. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, with EU Green Deal renewable content credits adding further differentiation for vegetable-derived esters. Pricing pressure stems from crude naphtha volatility transmitting through vacuum gas oil feedstock costs. Tier-one automotive suppliers exhibit lowest price sensitivity given qualification lock-in, while regional industrial compounders in Southeast Asia remain most responsive to spot market movements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns serving inland compounding facilities without bulk liquid handling infrastructure. Geographic supply concentration centers on China, Thailand, and India, where coastal refining clusters feed domestic tire manufacturing expansion. Raw material dependencies rest on vacuum gas oil from fluid catalytic cracking units, hydrocracker bottoms, and vegetable oil feedstocks from palm and soybean processing. Single-source vulnerability runs through naphthenic base stock concentration at select European refineries facing REACH-driven capacity conversion. Distribution runs through direct refiner relationships displacing distributor intermediaries among high-volume tire producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global rubber process oil market sits in a technology-transition phase as hydro-treated vegetable oil formulations displace legacy aromatic extracts in tire tread applications. This substitution is compressing traditional grade premiums and rewiring competitive positioning around sustainability certification rather than petroleum refining scale.
For Market Incumbents: Deepen hydro-treatment capacity investment in coastal refining hubs serving Asian tire manufacturing clusters to defend against bio-based substitution. Secure backward integration into vegetable oil hydro-processing technology through R&D partnerships or pilot facility deployment. Prioritize REACH and EU Green Deal certification maintenance as regulatory compliance becomes the primary margin defense against commodity competitors.
For New Entrants and Emerging Players: Begin with solvent-free adhesive and footwear sole compounding segments in Vietnam and Indonesia, where sustainability audits from EU and US brand owners create immediate demand for certified bio-based formulations. Target mid-scale compounders lacking direct refiner relationships and willing to pay modest premiums for technical support and flexible packaging. Establish go-to-market positioning around chain-of-custody documentation and rapid formulation revalidation services.
For Investors and Strategic Acquirers: Re-rating potential sits with specialty fluid producers possessing severe hydro-cracking assets and established automotive OEM qualification given accelerating low-PAH mandate propagation through tier-one supply chains. Long-term viability favors operators with dual petroleum and bio-based production capability across the analysis window. Monitor KBA and EPA regulatory tightening timelines as inflection indicators for aromatic grade demand displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Severe Hydro-Cracking Capacity Expansion | European refineries invest to meet REACH Annex XVII PAH limits and retain tire manufacturer supply contracts. |
| Backward Integration into Vegetable Oil Supply | Specialty blenders secure palm and soybean ester feedstocks to qualify for EU Green Deal renewable content credits. |
| Long-Term Supply Agreement with Tier-One Tire Producers | Direct refiner relationships in Thailand and China displace distributor channels and lock in volume commitments. |
| Joint Venture for Regional Hydro-Treatment Infrastructure | Indian refiners partner with technology licensors to reduce aromatic oil import dependence under BIS requirements. |
| Green Manufacturing Transition Certification | Footwear adhesive suppliers obtain sustainability audits to meet brand owner specifications in Vietnam and Indonesia. |
Research Methodology
Document review covered customs and trade flow databases, refinery capacity disclosures, and regulatory filings from ECHA and EPA, complemented by interviews with plant managers at rubber compounding facilities, procurement leads at tire manufacturers, technical R&D directors at base stock refiners, and distribution channel partners serving Southeast Asian industrial zones. Secondary validation drew from SEC 10-K filings of integrated petroleum majors, ACC and Cefic chemical industry reports, and MEE GB standards documentation. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity assumptions.
Segment-level value and volume trajectories across the projection horizon reflect modeled interactions between automotive production scaling, regulatory compliance cost pass-through, and feedstock price elasticity. Segmentation dimensions incorporated product type, application, end-use industry, packaging format, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules. Industry-specific inputs included tire manufacturing capacity utilization rates and EPDM roofing membrane specification trends.
Underlying measurement precision varies by segment; aromatic oil volumes carry tighter precision given established trade flows, while vegetable oil penetration rates in footwear applications exhibit wider confidence intervals due to nascent supply chain formation. Forecasts reflect documented assumptions regarding regulatory timeline adherence and automotive OEM qualification pacing. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that MEE enforcement intensity or REACH authorization delays could materially revise substitution trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Industrial Rubber Products Market
Rubber
Rubber Bulbs Market
Rubber
Rubber Ropes Market
Rubber
Performance Elastomers Market
Rubber
Global Tire Material Market
Rubber
Tire Chemicals Market
Rubber
Isoprene Rubber Market
Rubber
Rubber Extruder Market
Rubber
Styrene Butadiene Rubber (E-SBR and S-SBR) Market
Rubber
EMEA and Asia Pacific Electrical Insulating Rubber Gloves Market
Rubber
Fluorosilicone (FVMQ) Rubber Market
Rubber
Rubber Sand Market
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Snap on Rubber Stopper Market
Rubber
Rubber Valve Stem Market