
 Global Oxidative Stress Assay Market | 2026-2036
Global Oxidative Stress Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oxidative Stress Assay Market Foresight
China is rewriting capacity dynamics in life sciences consumables as domestic manufacturers scale GMP-compliant reagent production. Thermo Fisher Scientific leverages its global distribution network to sustain kit availability across multiple continents. Merck KGaA anchors European supply through its Darmstadt-based analytical chemistry division. QIAGEN differentiates with sample-to-insight automation that integrates oxidative stress panels into broader molecular workflows.
Oxidative stress assays quantify reactive oxygen species, antioxidant capacity, and cellular damage markers through enzymatic, immunological, or electrochemical detection methods, with sensitivity thresholds typically reaching picomolar concentrations for superoxide anion and hydrogen peroxide. These measurements enable pharmacological screening, disease mechanism elucidation, and therapeutic efficacy monitoring in preclinical and clinical settings. Immunoassays command the largest revenue share due to established ELISA infrastructure and antibody specificity for 4-HNE and 8-OHdG biomarkers, while microfluidic platforms represent the fastest-expanding delivery mode as point-of-care applications migrate from centralized labs to decentralized clinical settings. High-throughput technologies concentrate margin pools among pharmaceutical companies running parallel compound screens.
The FDA biomarker qualification program and EMA's qualification advice pathway shape demand by establishing evidentiary standards for oxidative stress endpoints in drug development submissions. ISO 13485 and IVDR compliance requirements in Europe are raising barriers for non-certified kit manufacturers seeking market access. REACH chemical registration obligations affect reagent formulation choices for vendors distributing chromogenic substrates across EU member states. Stakeholders must monitor evolving regulator positions on oxidative stress as surrogate endpoints in cardiovascular and neurodegenerative trials.
Market Dynamics
Microfluidic platform miniaturization is compressing assay workflows from multi-hour protocols to sub-30-minute readouts, redistributing testing capacity from centralized reference laboratories toward point-of-care settings and decentralized clinical networks.
Growth Catalysts
- NIH translational research mandates:US federal funding programs require oxidative stress biomarker integration into neurodegeneration and cardiovascular studies, institutionalizing assay demand across academic medical centers.
- Point-of-care diagnostic migration:Microfluidic cartridge systems enable bedside superoxide quantification in emergency departments and oncology infusion centers, expanding addressable testing occasions beyond traditional lab confines.
- EMA biomarker qualification pathway:European regulatory acceptance of 8-OHdG and 4-HNE as surrogate endpoints in drug development submissions validates assay outputs for pharmaceutical toxicology screening.
Market Restraints
- Antibody raw material concentration:High-affinity monoclonal antibody production concentrates among specialized bioreactor facilities, exposing kit manufacturers to batch-to-batch variability in 4-HNE detection specificity.
- IVDR compliance cost escalation:European In Vitro Diagnostic Regulation technical documentation requirements and notified body bottlenecks extend product registration timelines for non-multinational reagent suppliers.
- Electrochemical sensor substitution:Direct amperometric detection of hydrogen peroxide in wearable form factors threatens ELISA-based antioxidant capacity assays in continuous monitoring applications.
Strategic Opportunities
- India clinical laboratory expansion:Private diagnostic chains in Mumbai and Bangalore are installing automated oxidative stress panels to differentiate premium health screening packages from commodity biochemistry testing.
- ISO 13485 certification arbitrage:Quality management system accreditation opens procurement channels to hospital group purchasing organizations that exclude non-certified kit vendors from tender participation.
- CRISPR-oxidative stress convergence:Gene editing workflows require real-time reactive oxygen species monitoring during cell line engineering, creating integrated assay-automation demand from contract research organizations.
Industry Challenges
- Multiplex assay development expertise:Simultaneous quantification of superoxide, hydrogen peroxide, and lipid peroxidation markers demands rare cross-disciplinary proficiency in electrochemistry, immunochemistry, and microfluidic engineering.
- Legacy LIMS integration friction:Pre-analytical sample tracking and post-analytical result transmission require custom middleware development to connect novel microfluidic platforms with entrenched laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oxidative Stress Assay Market |
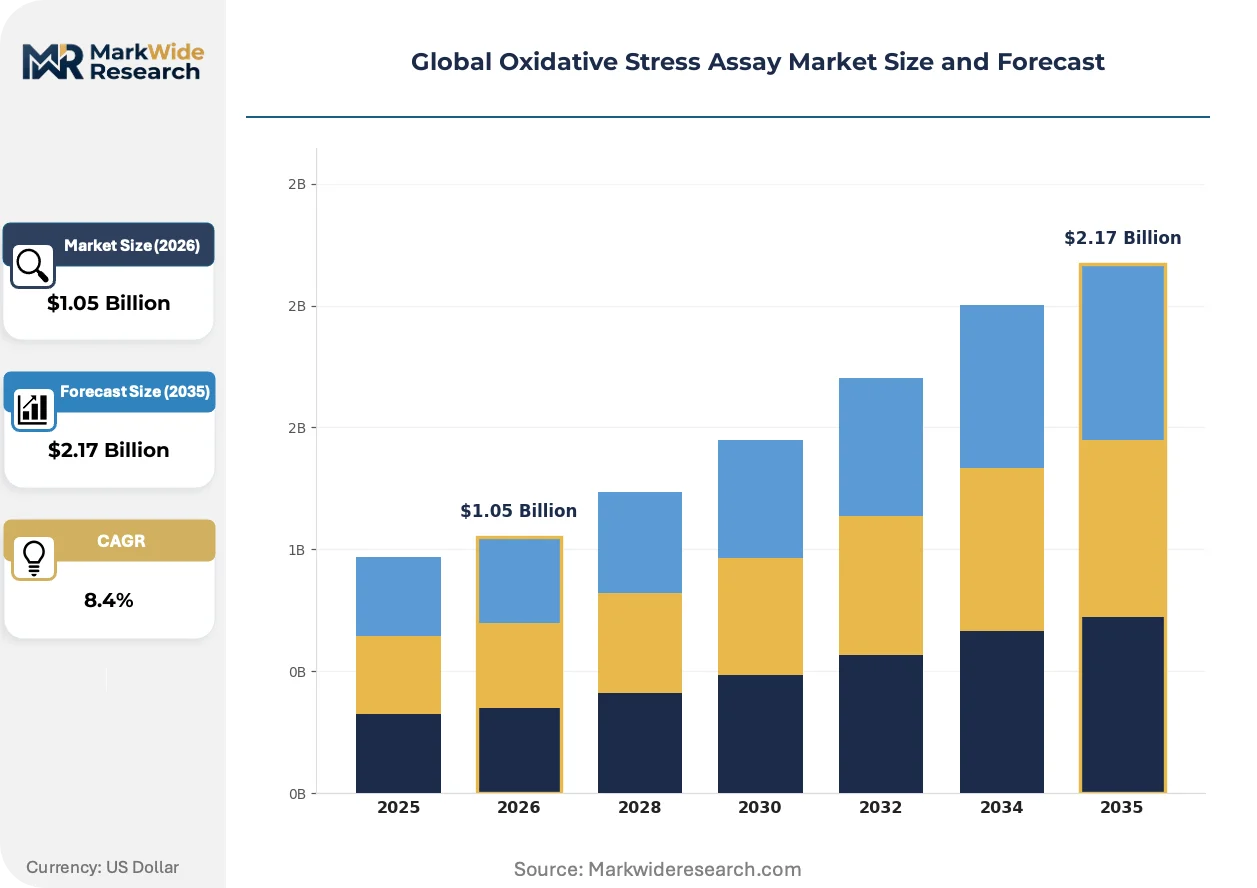
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzyme Assays, Immunoassays, Chromatographic Assays, Electrochemical Assays, Fluorometric Assays Therapy Area: Neurological Disorders, Cardiovascular Conditions, Metabolic Diseases, Inflammatory Disorders, Respiratory Diseases End User: Diagnostic Laboratories, Pharmaceutical Companies, Academic Research Institutes, Biotechnology Firms, Contract Research Organizations Delivery Mode: Manual Kits, Automated Systems, Point-of-Care Devices, Microfluidic Platforms, High-Throughput Technologies |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, QIAGEN, Abcam, Promega Corporation, Enzo Life Sciences, Cell Biolabs, AMSBIO, BioVision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oxidative Stress Assay Market Shifts & Advancements
Digital integration and miniaturization are collapsing the traditional separation between sample preparation, detection, and data interpretation, compressing analytical timelines while expanding the settings where oxidative stress quantification occurs.
Lab-on-a-chip microfluidic cartridges incorporating electrochemical sensor arrays are digitizing oxidative stress measurement by embedding signal processing and calibration algorithms directly into disposable test units. Pharmaceutical toxicology departments at contract research organizations are adopting these platforms to parallelize compound screening, eliminating the plate-washing and incubation steps that constrain ELISA throughput. This compression of analytical workflow is digitizing quality control documentation and enabling real-time data transmission to sponsor electronic data capture systems.
REACH chemical registration obligations are reshaping reagent formulation strategies for chromogenic substrate manufacturers distributing across EU member states. ECHA substance evaluation dossiers now require extensive toxicological data for tetrazolium salt derivatives commonly employed in superoxide dismutase activity assays, elevating compliance costs for European kit vendors. Reagent suppliers are responding by reformulating with pre-registered alternative substrates or restricting distribution to professional-use-only channels that exempt consumer product classification.
Hospital procurement departments are consolidating oxidative stress testing under long-term reagent rental agreements that bundle instrument placement, consumable supply, and maintenance into per-test pricing. This displaces capital purchase models for high-throughput analyzers in United States health system laboratories, compressing vendor margins while locking in multi-year volume commitments. Academic research institutes in Germany and Switzerland remain the primary holdouts, resisting bundled contracts to preserve instrument flexibility for method development protocols.
Global Oxidative Stress Assay Market Segmentation
Product differentiation in oxidative stress assays spans detection chemistry, clinical application, user workflow, and deployment setting. Each segmentation dimension captures distinct purchasing criteria, from antibody specificity requirements in immunoassays to throughput demands in pharmaceutical toxicology screening.
Product Type:
Cost tier determines reagent economics, with enzymatic and chromogenic methods occupying opposite ends of the per-test pricing spectrum.
- Immunoassays:Antibody-based detection of 4-HNE and 8-OHdG biomarkers leverages established ELISA infrastructure across diagnostic laboratories. Academic medical centers in the United States drive sustained kit consumption through NIH-funded neurodegeneration protocols requiring validated biomarker quantification.
- Electrochemical Assays:Amperometric detection of hydrogen peroxide and superoxide anion achieves picomolar sensitivity without enzymatic amplification steps. Pharmaceutical companies in Germany and Switzerland adopt these platforms for real-time compound screening during lead optimization phases.
- Enzyme Assays:Catalytic detection methods measure superoxide dismutase and catalase activity through chromogenic substrate turnover.
- Chromatographic Assays:HPLC and LC-MS methods provide reference-grade quantification of lipid peroxidation products for regulatory submissions.
- Fluorometric Assays:DCFDA and similar probes enable intracellular ROS imaging in live-cell microscopy workflows.
Immunoassays hold installed capacity. Electrochemical assays are rotating up the share rankings.
Therapy Area:
Application focus concentrates where oxidative damage mechanisms are clinically validated and regulatory pathways accept surrogate biomarker endpoints.
- Neurological Disorders:Cerebrospinal fluid and plasma 8-OHdG measurements track neurodegeneration progression in Alzheimer's and Parkinson's disease studies. The FDA biomarker qualification program streamlines assay adoption across academic research institutes pursuing amyloid-tau-oxidative stress multimarker panels.
- Cardiovascular Conditions:Oxidized LDL and isoprostane quantification supports atherosclerosis risk stratification and statin efficacy monitoring. Hospital laboratories in Japan integrate these panels into routine lipid profiles for metabolic syndrome management.
- Metabolic Diseases:Mitochondrial dysfunction markers guide diabetes complication screening and non-alcoholic fatty liver disease staging.
- Inflammatory Disorders:Reactive oxygen species burst assays quantify neutrophil activation in rheumatoid arthritis and inflammatory bowel disease.
- Respiratory Diseases:Exhaled breath condensate analysis detects airway oxidative stress in chronic obstructive pulmonary disease monitoring.
Neurological applications command premium pricing. Cardiovascular testing is expanding most quickly into routine clinical chemistry menus.
End User:
Customer type shapes procurement patterns, from capital-intensive analyzer purchases to reagent rental agreements and grant-funded kit acquisitions.
- Pharmaceutical Companies:High-throughput oxidative stress screening integrates into IND-enabling toxicology studies and mechanism-of-action research. Contract research organizations in India and China scale these services for Western sponsor demand.
- Academic Research Institutes:Method development flexibility and publication-grade validation drive preference for modular assay components over integrated systems. German and Swiss universities resist bundled reagent contracts to preserve protocol customization.
- Diagnostic Laboratories:Centralized reference networks in the United States consolidate testing under long-term vendor agreements with per-test pricing.
- Biotechnology Firms:Cell therapy developers require real-time ROS monitoring during CAR-T and iPSC manufacturing.
- Contract Research Organizations:Toxicology service providers multiplex oxidative stress endpoints into standard safety pharmacology packages.
Pharmaceutical companies anchor volume commitment. Academic institutes are climbing the fastest as translational research mandates institutionalize assay demand.
Delivery Mode:
Deployment setting determines workflow integration requirements, from batch-processing analyzers to bedside cartridge systems.
- Microfluidic Platforms:Lab-on-a-chip cartridges compress multi-hour ELISA protocols to sub-30-minute readouts with embedded calibration algorithms. Oncology infusion centers in the United States deploy these for point-of-care superoxide quantification during chemotherapy monitoring.
- High-Throughput Technologies:384-well and 1536-well formats enable parallel compound screening at contract research organizations. Plate-based automation concentrates margin pools among pharmaceutical toxicology departments running weekly batch campaigns.
- Manual Kits:Benchtop reagent sets serve resource-constrained laboratories and method development protocols.
- Automated Systems:Random-access analyzers integrate oxidative stress panels into routine clinical chemistry workflows.
- Point-of-Care Devices:Handheld electrochemical readers target emergency department triage and ambulatory monitoring.
High-throughput systems hold installed capacity. Microfluidic platforms are gaining share fastest as decentralized testing expands beyond centralized laboratory confines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies: the United States deploys oxidative stress assays primarily within NIH-funded translational research frameworks, while China integrates domestic reagent manufacturing into centralized hospital procurement networks, and Germany maintains method-development flexibility through academic resistance to bundled vendor contracts.
United States
NIH translational research mandates institutionalize assay demand across academic medical centers in Boston, San Francisco, and Bethesda. The FDA biomarker qualification pathway streamlines clinical validation for 8-OHdG and 4-HNE endpoints in neurodegeneration trials. Reference laboratory networks in North Carolina and Texas consolidate high-throughput testing under long-term reagent rental agreements.
Germany
Merck KGaA's Darmstadt-based analytical chemistry division anchors European supply chains for GMP-compliant reagent production. EMA qualification advice pathways validate oxidative stress endpoints for pharmaceutical toxicology submissions. University clusters in Heidelberg and Munich resist bundled procurement contracts to preserve protocol customization flexibility for method development.
China
Domestic manufacturers scale GMP-compliant reagent production to displace imported kit dependencies in tier-one hospital laboratories. NMPA regulatory harmonization accelerates clinical validation timelines for oxidative stress biomarkers. Life sciences industrial parks in Suzhou and Shanghai concentrate microfluidic platform assembly capacity for point-of-care diagnostic export.
Switzerland
Swissmedic oversight maintains stringent quality standards for assay kits distributed through Basel-centered pharmaceutical toxicology departments. Federal research funding programs require oxidative stress panel integration into neurodegeneration mechanism studies. The Zurich-Geneva corridor hosts contract research organizations multiplexing ROS endpoints into standard safety pharmacology packages.
India
Private diagnostic chains in Mumbai and Bangalore install automated oxidative stress panels to differentiate premium health screening offerings. CDSCO regulatory pathways increasingly recognize ISO 13485 certification for hospital group purchasing organization eligibility. Contract research organizations in Hyderabad scale toxicology screening services for Western pharmaceutical sponsor demand.
Global Oxidative Stress Assay Market Competitive Landscape
Capability concentration sits with specialized antibody and microfluidic engineering firms; scale advantage sits with diversified life sciences conglomerates commanding global distribution networks. The market structures around three archetypes: integrated analytical chemistry divisions with captive reagent manufacturing, sample-to-insight automation specialists, and modular assay component suppliers serving method-development protocols. Dominant competitive moves include strategic partnerships between microfluidic platform developers and pharmaceutical toxicology service providers, plus geographic expansion through ISO 13485 certification arbitrage into hospital procurement channels.
Among diversified analytical chemistry conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify scale-driven positioning through global distribution infrastructure and GMP-compliant manufacturing footprints. QIAGEN occupies a distinct tier representing sample-to-insight automation integration, embedding oxidative stress panels within broader molecular workflow architectures. These three entities anchor competitive dynamics by setting technical documentation standards and reagent rental contract terms that smaller kit manufacturers must match for hospital group purchasing organization participation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| QIAGEN |
| Abcam |
| Promega Corporation |
| Enzo Life Sciences |
| Cell Biolabs |
| AMSBIO |
| BioVision |
| Others |
Supply & Pricing Matrix
Undercapacity in high-affinity monoclonal antibody bioreactors concentrates pricing power among specialized suppliers, forcing kit manufacturers toward long-term reagent rental contracts that bundle instrument placement with consumable supply to lock in volume commitments and stabilize margin erosion.
Pricing Analysis
Long-term reagent rental agreements now dominate hospital laboratory procurement in the United States, displacing capital purchase models through per-test pricing that compresses vendor margins while securing multi-year volume commitments. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified kits for pharmaceutical toxicology from research-grade reagents and basic chromogenic methods. Cost compression in standard-tier immunoassays is intensifying because domestic Chinese manufacturers scale GMP-compliant production. Academic research institutes exhibit lowest price sensitivity, resisting bundled contracts to preserve protocol customization flexibility.
Supply Chain Analysis
Contract manufacturing for microfluidic cartridges concentrates in Suzhou and Shanghai industrial parks, where domestic Chinese assemblers feed from German-designed sensor arrays and Japanese-precision fluidic components. Tetrazolium salt derivatives and chromogenic substrates draw from specialized chemical synthesis facilities in Germany and Switzerland. Single-source vulnerability in high-affinity antibody production exposes kit manufacturers to batch-to-batch variability. Distribution runs through global life sciences conglomerates commanding refrigerated logistics networks for temperature-sensitive reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical sensor substitution in wearable form factors threatens ELISA-based antioxidant capacity assays, forcing incumbents to defend installed base through workflow integration and regulatory qualification pathways.
For Market Incumbents: Insulate high-throughput screening relationships by embedding oxidative stress panels into broader molecular workflow architectures that increase switching costs. Deepen backward integration into antibody bioreactor capacity to reduce batch-to-batch variability exposure in 4-HNE detection specificity. Secure FDA biomarker qualification for 8-OHdG and 4-HNE endpoints to create regulatory moats against electrochemical substitutes. For New Entrants and Emerging Players: Pursue ISO 13485 certification arbitrage into Indian private diagnostic chains in Mumbai and Bangalore, where premium health screening differentiation creates procurement channel access without incumbent lock-in. Target microfluidic platform development for point-of-care oncology infusion centers, leveraging sub-30-minute readout advantages over centralized ELISA workflows. Lead with sample-to-insight automation that integrates ROS monitoring into CAR-T manufacturing quality control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sample-to-insight automation specialists with installed base expansion through reagent rental agreements rather than capital equipment sales. Long-term viability over the next decade hinges on regulatory qualification pathway progress for oxidative stress surrogate endpoints in neurodegeneration and cardiovascular trials. Watch EMA and FDA biomarker qualification decisions as inflection indicators for pharmaceutical toxicology demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Pathway | FDA acceptance of 8-OHdG endpoints validates assay outputs for IND-enabling toxicology studies. |
| Microfluidic Platform Integration | Lab-on-a-chip cartridges compress ELISA workflows from hours to minutes for bedside deployment. |
| ISO 13485 Certification Arbitrage | Quality management accreditation opens hospital GPO procurement channels excluding uncertified vendors. |
| Antibody Bioreactor Backward Integration | In-house production of high-affinity monoclonals reduces batch variability in 4-HNE detection kits. |
| Reagent Rental Contract Expansion | Per-test pricing models displace capital purchases and lock in multi-year volume commitments from US health systems. |
Research Methodology
Desk research of FDA biomarker qualification dossiers, EMA submission databases, and NIH funding award records preceded structured interviews with pharmaceutical toxicology directors, diagnostic laboratory procurement managers, and contract research organization operations leads. Primary fieldwork with microfluidic platform engineers and antibody manufacturing specialists was cross-validated against secondary sources including ISO 13485 certification registries, hospital group purchasing organization contract filings, and REACH chemical registration dossiers. Bottom-up assay kit shipment estimates were triangulated with top-down pharmaceutical R&D spending allocations.
Assumptions held fixed include regulatory qualification pathway timelines for oxidative stress surrogate endpoints and continued NIH translational research mandate funding levels, while variables included microfluidic platform adoption rates and domestic Chinese reagent manufacturing scale-up velocity. Segmentation modeling spanned detection chemistry, therapy area application, end-user procurement pattern, and delivery mode deployment setting across the analysis window. CAGRs were derived from regression analysis of historical kit consumption against pharmaceutical pipeline progression and academic publication trends in neurodegeneration biomarker research.
Sensitivities concentrate around FDA biomarker qualification delays, electrochemical sensor substitution acceleration in wearable devices, and IVDR notified body bottlenecks extending European product registration timelines. Forecasts reflect documented assumptions regarding microfluidic platform miniaturization progress and antibody raw material supply stability. Cross-checking against NIH RePORTER funding allocations and pharmaceutical toxicology CRO service line expansions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Ion Chromatography Market
Testing Equipment
Liquid Chromatography Mass Spectrometry (LCMS) Market
Testing Equipment
Chemical Analyzer Market
Testing Equipment
Laboratory Accessories Market
Testing Equipment
Global Host Cell Contaminant Testing Market
Testing Equipment
Paint Tester Market
Testing Equipment
United States Material Testing Market
Testing Equipment
High Performance Liquid Chromatography (HPLC) Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
Global Analytical Standards Market
Testing Equipment
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market
Testing Equipment
Particle Size Analysis Market
Testing Equipment
Ammonia Testing Market
Testing Equipment
High Performance Liquid Chromatography-Tandem Mass Spectrometry System Market
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
Corrosion Testing Services Market