
 Rubber Plated Hose Market | 2026-2036
Rubber Plated Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Plated Hose Market Intelligence
Capital-intensity divergence between integrated compounders and assembly-only producers is reorganizing competitive tiers in rubber plated hose manufacturing. Continental AG leverages captive EPDM blending capacity to sustain margin control across European industrial accounts. Gates Corporation anchors North American hydraulic replacement demand through proprietary crimping technology and OEM service contracts. Parker Hannifin Corp. competes on fluid power system integration, extending hose sales into bundled motion-control packages.
Rubber plated hose denotes a reinforced flexible conduit comprising an inner rubber tube, textile or wire reinforcement layers, and an outer rubber cover vulcanized under heat and pressure, typically rated for working pressures from 150 to 6,000 psi depending on reinforcement class. Its primary industrial purpose is to convey fluids, gases, or abrasive materials under pressure while absorbing vibration and accommodating movement in machinery. Industrial hoses lead volume due to broad utility across manufacturing and processing plants, though hydraulic hoses capture premium pricing from severe-duty construction and mining applications. EPDM compounds dominate weather-exposed segments such as marine and agricultural equipment, while NBR retains cost advantages in petroleum-transfer uses where aromatic resistance is essential.
ISO 18752 defines global performance benchmarks for hydraulic hoses, while REACH in Europe restricts certain plasticizers and curatives in rubber compounding, elevating compliance costs for exporters. China's SAMR enforces GB/T standards for pressure-bearing rubber products, requiring domestic testing certification that foreign suppliers must obtain through joint-venture laboratories or licensed importers. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in the EU and US, as these chemicals appear in some fluoroelastomer hose liners and face phased elimination timelines that will force material reformulation across premium product lines.
Market Dynamics
Capital-intensity divergence between integrated compounders and assembly-only producers is reorganizing competitive tiers in rubber plated hose manufacturing. EPDM blending capacity and captive reinforcement wire drawing operations separate margin-sustainable suppliers from price-takers in replacement markets.
Growth Catalysts
- GB/T pressure equipment certification:China's SAMR enforcement tightens material traceability rules, forcing foreign suppliers into joint-venture laboratory partnerships that advantage pre-positioned multinationals.
- Hydraulic replacement cycles:Australian mining fleet utilization rates extend hose changeout intervals, concentrating demand among severe-service rated products.
- EPDM compound advances:Peroxide-cured formulations improve ozone resistance in marine and agricultural equipment, displacing chloroprene in weather-exposed segments.
Market Restraints
- EPDM polymer supply concentration:Three integrated petrochemical complexes control global ethylene feedstock allocation, creating input cost volatility for non-captive compounders.
- REACH plasticizer restrictions:ECHA curative limitations elevate compliance costs for European exporters and block certain legacy formulations from EU markets.
- Steel wire reinforcement dependency:High-tensile wire rod supply concentrates in East Asian electric arc furnace clusters, exposing hose manufacturers to freight and tariff exposure.
Strategic Opportunities
- India western industrial corridor:Pune and Ahmedabad manufacturing clusters lack localized high-pressure hose assembly capacity, creating white space for technical distributors with crimping capabilities.
- Fluoroelastomer liner reformulation:PFAS elimination timelines in the EU and US force material substitution, rewarding compounders with advanced FKM-alternative development pipelines.
- Motion-control bundling:Fluid power system integration creates attach opportunities for hose sales alongside pumps, valves, and filtration in automated machinery packages.
Industry Challenges
- Vulcanization technician scarcity:Heat-press operation expertise concentrates among aging workforces in European and Japanese manufacturing bases, constraining quality-consistency in greenfield facilities.
- ISO 18752 certification timelines:Impulse testing and burst validation protocols extend product launch cycles, compressing first-mover advantage windows for novel reinforcement architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Plated Hose Market |
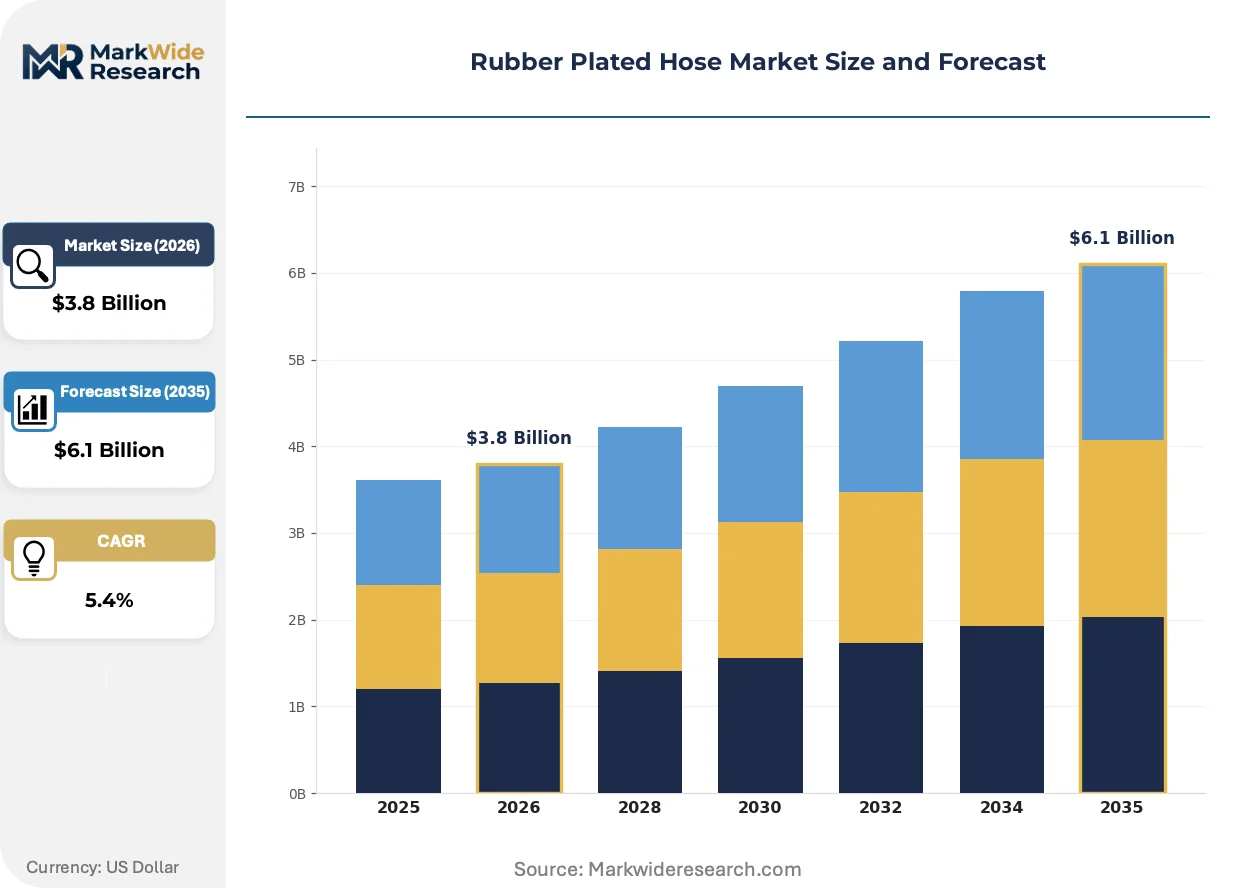
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Hoses, Garden Hoses, Hydraulic Hoses, Fire Hoses Application: Construction, Agriculture, Automotive, Marine Material: EPDM, NBR, PVC, Silicone End User: Manufacturers, Distributors, Retailers, Contractors |
| Companies Covered | Vardhman Hoses Pvt. Ltd., Shree Tirupati Rubber Products, ACE Hose & Rubber, Parker Hannifin Corp., Continental AG, Gates Corporation, Eaton Corporation, Trelleborg Group, HANSA-FLEX AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Plated Hose Market Strategic Shifts & Innovations
Thermoplastic hybrid constructions and digital crimping diagnostics are bifurcating the technical frontier from commodity replacement tiers. Regulatory chemistry restrictions and procurement centralization are simultaneously reshaping compound development and channel economics.
Aramid fiber reinforcement is bifurcating the high-pressure hydraulic segment from traditional steel-wire constructions. Mining and offshore rig operators in Australia and Brazil are specifying aramid-braided hoses for weight-critical installations. The technology is bifurcating procurement specifications into weight-optimized premium tiers versus cost-driven standard categories.
REACH per- and polyfluoroalkyl substance restrictions are forcing fluoroelastomer liner reformulation across premium product lines. ECHA phased elimination timelines compress material qualification windows for fuel-handling and chemical-transfer applications. European automotive and aerospace hose specifications are migrating toward FKM-alternative compounds ahead of enforcement dates.
Buyer concentration among national mining consortiums and agricultural equipment OEMs is consolidating specification authority at fewer decision points. Technical distributors with in-house crimping and testing capabilities are displacing pure trading intermediaries in aftermarket channels. This pattern concentrates most visibly in Australia's Pilbara mining region and India's western industrial corridor.
Rubber Plated Hose Market Segmentation
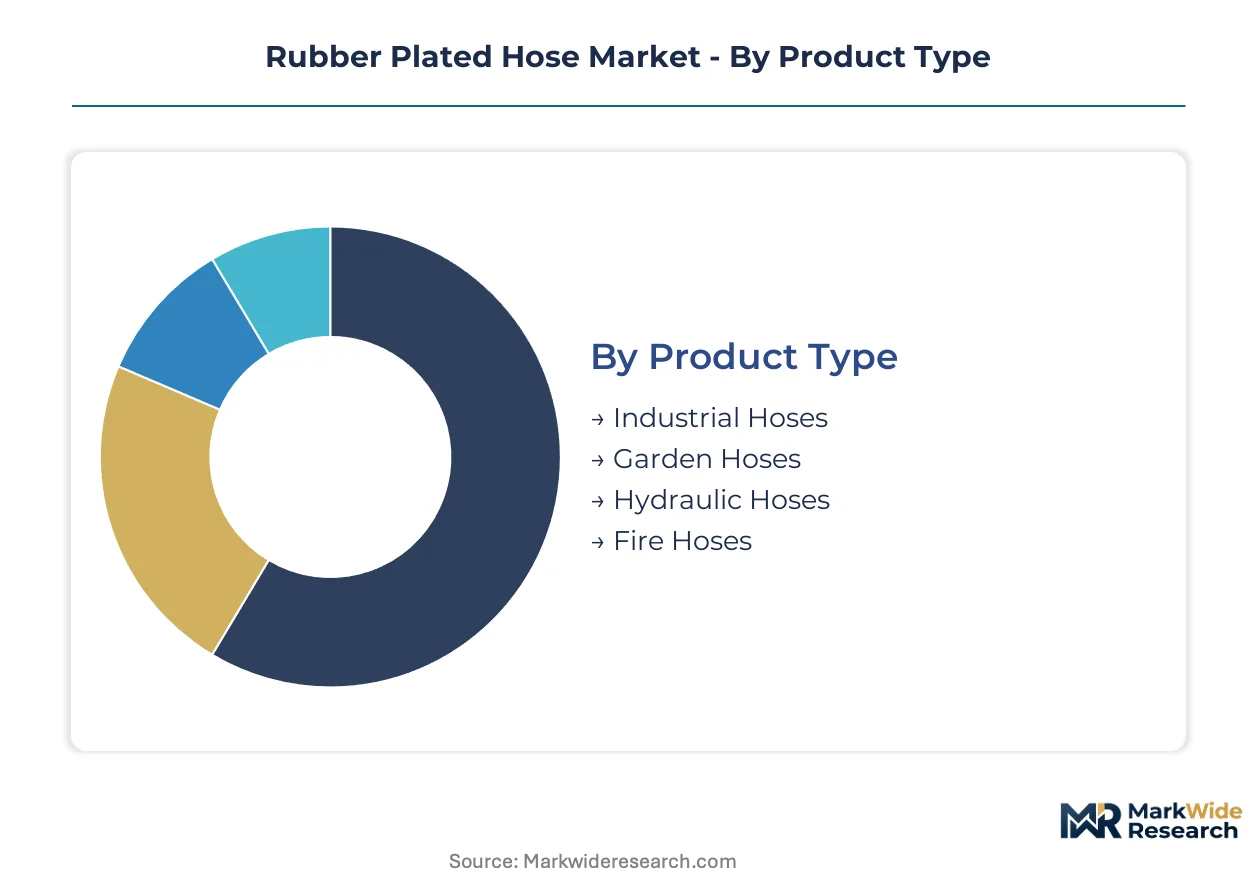
Rubber plated hose procurement splits across performance tiers, material chemistry, and channel economics. Specification authority concentrates at different decision points depending on whether the purchase serves OEM assembly, fleet maintenance, or retail replacement.
Product Type:
ISO 18752 certification requirements separate hydraulic hoses into impulse-tested premium grades versus unrated commodity tiers, creating regulatory-driven price stratification.
- Industrial Hoses:Multi-purpose constructions with textile reinforcement and EPDM or NBR covers serve manufacturing plants and process industries. Demand clusters around India's western industrial corridor in Pune and Ahmedabad, where localized assembly capacity remains scarce.
- Hydraulic Hoses:Steel-wire or aramid-braided constructions rated to 6,000 psi working pressure convey petroleum-based fluids under severe duty. Australian mining fleets in the Pilbara region are specifying severe-service rated products as fleet utilization extends changeout intervals.
- Garden Hoses:Light-duty PVC or EPDM constructions for residential irrigation and landscaping applications.
- Fire Hoses:Specialized synthetic-jacketed constructions with rubber lining for municipal firefighting and industrial safety systems.
Industrial hoses handle the majority of throughput; hydraulic hoses are expanding most quickly on share.
Application:
End-use severity determines reinforcement class and compound selection, with weather exposure and aromatic fluid contact driving material specifications.
- Construction:Severe-duty hydraulic hoses on excavators, loaders, and concrete pumps face abrasion, kinking, and pressure spike conditions. Australia's mining-adjacent civil projects are adopting aramid-braided constructions for weight-critical mobile equipment.
- Agriculture:EPDM-based spray and irrigation hoses resist ozone and UV degradation in open-field exposure. Peroxide-cured formulations are displacing chloroprene in Brazilian and Australian agricultural equipment procurement.
- Automotive:Fuel-line, coolant, and brake hoses subject to REACH plasticizer restrictions and temperature cycling.
- Marine:Saltwater-resistant EPDM and specialized constructions for bilge, sanitation, and deck wash systems.
Construction absorbs the highest premium volumes; agriculture is gaining share fastest.
Material:
Feedstock concentration and regulatory chemistry restrictions are forcing compound reformulation across all polymer classes.
- EPDM:Ethylene-propylene-diene terpolymer dominates weather-exposed segments with superior ozone and UV resistance. Three integrated petrochemical complexes control global ethylene feedstock allocation, creating input cost volatility for non-captive compounders serving marine and agricultural OEMs.
- NBR:Nitrile butadiene rubber retains cost advantages in petroleum-transfer applications where aromatic resistance is essential. ECHA curative limitations under REACH are elevating compliance costs for European NBR compounders.
- PVC:Plasticized polyvinyl chloride serves low-pressure garden and light industrial hose tiers.
- Silicone:High-temperature resistant formulations for automotive and aerospace thermal management applications.
EPDM commands the broadest application base; silicone is climbing the fastest.
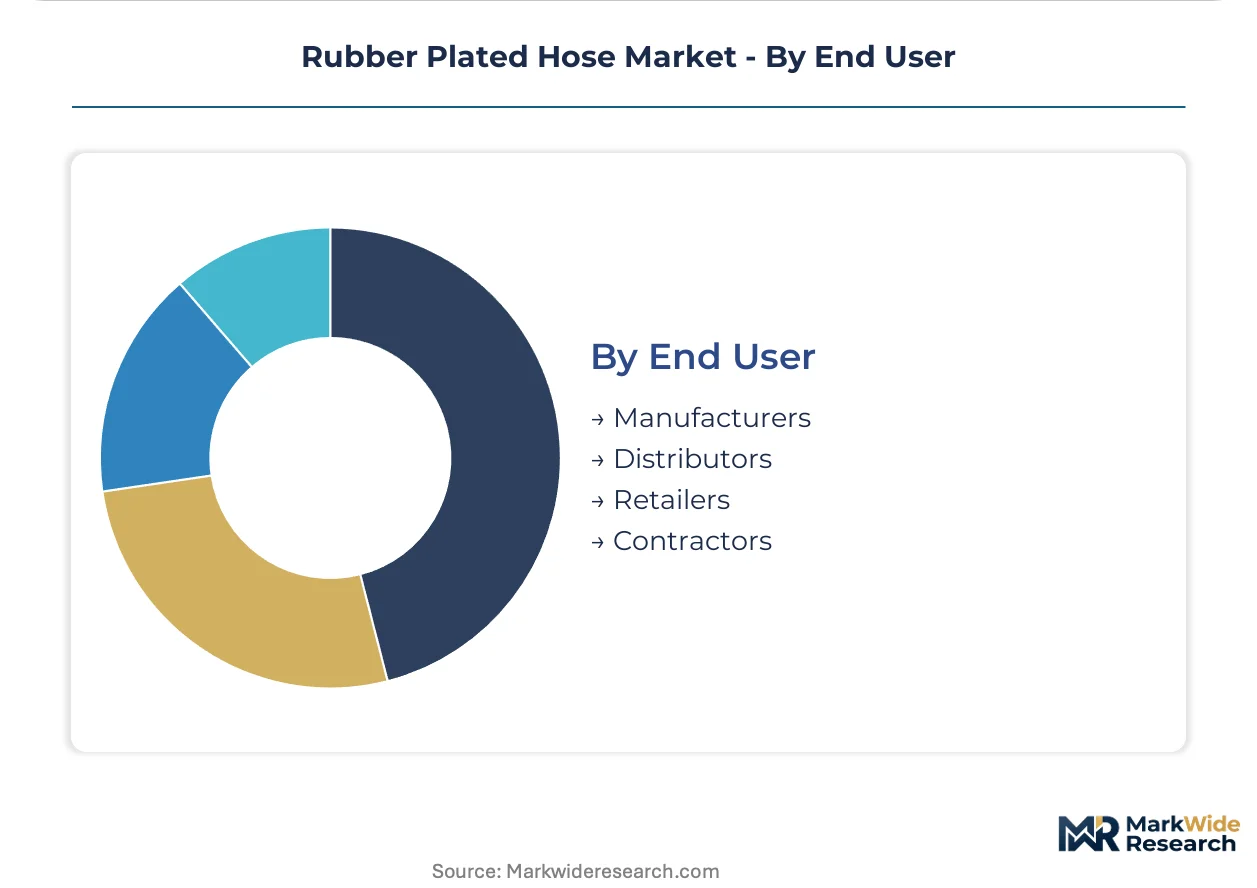
End User:
Channel consolidation and technical capability requirements are restructuring procurement access across the value chain.
- Distributors:Technical distributors with in-house crimping, testing, and inventory management capabilities are displacing pure trading intermediaries. India's western industrial corridor lacks localized high-pressure hose assembly capacity, creating white space for distributors investing in crimping equipment and SAMR certification support.
- Manufacturers:OEMs specify hoses as integrated fluid power system components, bundling procurement with pumps and valves. Parker Hannifin and Gates Corporation compete on system integration rather than standalone hose sales.
- Retailers:Big-box and specialty retailers serve replacement demand in garden and light industrial tiers.
- Contractors:Fleet maintenance operations in mining and construction purchase through service contracts or direct procurement.
Distributors intermediate the largest value flows; manufacturers are consolidating specification authority most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia consumes rubber plated hoses through severe-duty mining fleet maintenance, whereas India absorbs volume through distributed industrial manufacturing clusters lacking localized assembly capacity. This consumption-mix differential shapes procurement patterns and channel economics across geographies.
China
Domestic mining equipment refurbishment and agricultural machinery OEM assembly drive specification demand. SAMR enforces GB/T certification for pressure-bearing rubber products, requiring foreign suppliers to route through joint-venture laboratories. Yangtze River Delta manufacturing bases concentrate EPDM compounding capacity for marine and construction hose exports.
India
Pune and Ahmedabad industrial corridors generate concentrated demand for hydraulic and industrial hose assemblies. BIS pressure equipment standards tighten material traceability requirements for imports. Western Maharashtra and Gujarat lack localized high-pressure crimping facilities, forcing fleet operators to source from technical distributors in Mumbai.
Germany
Automotive OEM supply chains and fluid power system integrators anchor premium hose procurement. ECHA REACH restrictions on plasticizers and curatives elevate compliance costs for rubber compounders. Baden-Württemberg industrial zones host captive EPDM blending operations serving European construction equipment manufacturers.
Australia
Pilbara mining consortiums extend hydraulic hose replacement cycles through severe-service rated specifications. TGA-equivalent pressure equipment registration applies to imported assemblies for critical applications. Perth-based technical distributors with in-house crimping capabilities displace pure trading intermediaries in aftermarket channels.
United States
Construction fleet operators and agricultural equipment OEMs drive replacement demand across hydraulic and industrial tiers. EPA and OSHA regulations govern pressure equipment safety in mining and industrial settings. Texas and Oklahoma oilfield service clusters consume specialized high-pressure hose assemblies for hydraulic fracturing operations.
Rubber Plated Hose Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive polymer compounding and reinforcement wire drawing operations separating margin-sustainable suppliers from price-takers. Continental AG and Gates Corporation anchor the integrated tier through backward control over EPDM blending and proprietary crimping technology. Three strategic archetypes populate the competitive landscape: integrated compounder-assemblers, technology-licensed regional fabricators, and assembly-only trading specialists. Dominant competitive moves include geographic expansion through technical distributor partnerships and portfolio diversification into motion-control system bundling.
Among German-based integrated manufacturers, Continental AG and HANSA-FLEX AG exemplify the compounder-assembler archetype with captive material production. Parker Hannifin Corp. represents the North American fluid power integration model, extending hose sales into bundled system packages. Vardhman Hoses Pvt. Ltd. occupies a position within India's specialist fabricator tier, serving domestic industrial clusters with localized assembly capacity. These three anchors illustrate how geographic origin and vertical scope shape competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Vardhman Hoses Pvt. Ltd. |
| Shree Tirupati Rubber Products |
| ACE Hose & Rubber |
| Parker Hannifin Corp. |
| Continental AG |
| Gates Corporation |
| Eaton Corporation |
| Trelleborg Group |
| HANSA-FLEX AG |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between Australian mining consortiums and integrated hose manufacturers lock in EPDM compound supply and provide price visibility across severe-service replacement cycles. These arrangements insulate buyers from spot volatility in ethylene feedstock markets while securing capacity allocation from captive compounders.
Pricing Analysis
Contract-based long-term offtake dominates procurement for severe-duty hydraulic tiers, with spot purchasing limited to commodity industrial hoses. Price differentiation rests on ISO 18752 certification grade and geographic delivery cost to remote mining clusters. Cost compression in standard industrial tiers is intensifying because non-captive compounders face ethylene allocation volatility. Fleet maintenance contractors in Australia's Pilbara region exhibit lowest price sensitivity, while Indian manufacturing SMEs in Pune and Ahmedabad show highest sensitivity due to working capital constraints.
Supply Chain Analysis
China, Germany, and the United States anchor global rubber plated hose manufacturing through distinct competitive archetypes. China concentrates EPDM compounding capacity in Yangtze River Delta clusters; Germany hosts captive blending operations in Baden-Württemberg; the United States serves oilfield service demand from Texas and Oklahoma bases. Raw material inputs draw from East Asian electric arc furnace clusters for high-tensile wire rod and Middle Eastern ethylene crackers for polymer feedstock. Steel wire reinforcement dependency creates tariff exposure from trade policy shifts. Distribution runs through technical distributors with in-house crimping capabilities, displacing pure trading intermediaries in aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rubber plated hose demand sits in early-cycle expansion as Australian mining fleets extend replacement intervals and India's western industrial corridor lacks localized assembly capacity. Peroxide-cured EPDM advances and aramid fiber reinforcement adoption accelerate specification upgrades across weather-exposed and weight-critical applications.
For Market Incumbents: Consolidate specification authority through captive EPDM blending capacity and proprietary crimping technology licensing to technical distributors. Defend against aramid fiber substitution by embedding steel-wire constructions into bundled fluid power system packages with Parker Hannifin and Gates Corporation service contracts. For New Entrants and Emerging Players: Technical crimping and SAMR certification support in India's Pune-Ahmedabad corridor represents the most penetrable white space, where localized high-pressure hose assembly capacity remains scarce. Target fleet maintenance contractors through mobile crimping units and same-day delivery guarantees. Partner with Yangtze River Delta compounders for EPDM supply security rather than building captive blending. For Investors and Strategic Acquirers: Regional fabricators with ISO 18752 testing capabilities and established joint-venture laboratory relationships in China offer the strongest acquisition profile for mid-cycle consolidation. Monitor GB/T enforcement timelines and REACH plasticizer restriction implementation as inflection indicators for compound reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPDM Compounding | Captive polymer production insulates Continental AG from ethylene allocation volatility and secures margin control. |
| Technical Distributor Partnership Expansion | Crimping-capable intermediaries in Australia's Pilbara displace pure traders and capture aftermarket value. |
| Aramid Fiber Reinforcement Development | Weight-optimized constructions penetrate Brazilian offshore and Australian mining procurement specifications. |
| Fluoroelastomer Liner Reformulation | FKM-alternative pipelines address ECHA PFAS elimination timelines ahead of enforcement dates. |
| Motion-Control System Bundling | Parker Hannifin extends hose attach rates through integrated pump, valve, and filtration packages. |
Research Approach
Cross-validation between primary interviews with maintenance directors at Australian mining consortiums and secondary validation through customs trade data anchors the qualitative findings. Plant engineers at Pune and Ahmedabad manufacturing clusters, aftermarket service heads at Gates Corporation and Continental AG distribution networks, and procurement leads at hydraulic OEMs provided operational perspective. SEC 10-K filings, BIS pressure equipment notifications, ECHA REACH restriction updates, and SAMR GB/T certification registries supplied quantitative benchmarks. Bottom-up channel sizing and top-down polymer consumption estimates triangulate market boundaries.
Sensitivity analysis around ethylene feedstock price scenarios and mining fleet utilization assumptions shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include reinforcement class, compound chemistry, end-use severity tier, and regional regulatory cluster. CAGRs derive from replacement cycle analysis and OEM assembly volume trajectories. Aramid fiber penetration rates and peroxide-cured EPDM displacement curves inform technology transition assumptions.
Forecasts assume regulatory continuity in REACH plasticizer restrictions and SAMR GB/T enforcement; material policy shifts would require re-modeling. Compound supply disruptions from ethylene allocation constraints or steel wire tariff escalations represent specific revision triggers. Recalibration cycles align with material shifts in mining capital expenditure patterns and automotive hose specification migrations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Rubber Bulb Seals Market
Rubber
Polybutadiene Market
Rubber
Tire Chemicals Market
Rubber
Medical Rubber and Balloon Products Market
Rubber
Polyisoprene Market
Rubber
Rubber Ropes Market
Rubber
US Nitrile Gloves Market
Rubber
Liquid Silicone Rubber Market
Rubber
Global Rubber Processing Chemicals Market
Rubber
Rubber Conveyor Belt Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Acrylic Based Elastomers Market
Rubber
Flexible Rubber Sheets Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Industrial Rubber Products Market
Rubber
Hydroxyl Terminated Polybutadiene Market