
 Total Hydrocarbon Analyzers Market | 2026-2036
Total Hydrocarbon Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Total Hydrocarbon Analyzers Market Analytics
Market Context
North American instrument manufacturing is consolidating as domestic producers scale output for shale basin monitoring. Thermo Fisher Scientific leverages its chromatography portfolio to serve refinery stack emission testing. Teledyne Technologies anchors its position through infrared detection systems for pipeline leak surveys. Siemens AG competes with integrated process analytics platforms that tie hydrocarbon measurement into plant control systems.
Technical Definition and Segment Structure
Total hydrocarbon analyzers measure aggregate organic carbon content in gas streams through flame ionization detection or nondispersive infrared absorption, quantifying methane through hexane-plus concentrations for emission compliance and process optimization. Stationary analyzers dominate the product mix due to permanent installation at flare stacks and custody transfer points, while portable units capture the fastest expansion as field inspection protocols multiply. Gas chromatography technology leads on accuracy for complex stream composition, though optical sensors gain ground in cost-sensitive ambient monitoring deployments.
Regulatory Framework and Outlook
EPA greenhouse gas reporting mandates and OSHA process safety management standards shape equipment specifications and replacement cycles in the United States. The EU F-Gas Regulation and IECEx equipment certification frameworks influence product design for European and hazardous-area installations respectively. Stakeholders must monitor evolving methane intensity thresholds and cross-border standard harmonization to align R&D investment with enforceable compliance deadlines.
Market Dynamics
EPA methane emission rules under the Clean Air Act are forcing refineries and gas processors to upgrade continuous monitoring infrastructure, accelerating replacement cycles for legacy flame ionization systems.
Growth Catalysts
- Flare stack monitoring mandates:EPA regulations now require continuous hydrocarbon measurement at refinery flares, creating pull for permanent analyzer installations.
- Shale basin expansion:Permian and Bakken production growth drives demand for pipeline leak detection systems tied to custody transfer points.
- Optical sensor maturation:Tunable diode laser absorption spectroscopy cuts maintenance costs versus flame ionization in ambient air monitoring networks.
Market Restraints
- Platinum catalyst cost volatility:Flame ionization detectors depend on platinum electrodes, exposing OEMs to precious metal price swings.
- Specialized technician scarcity:Qualified service engineers for hazardous-area calibration remain concentrated in Texas and Louisiana.
- Optical interference limitations:Nondispersive infrared systems struggle with water vapor cross-sensitivity in humid Gulf Coast conditions.
Strategic Opportunities
- Biogas upgrading facilities:Renewable natural gas plants in California and New York need methane slip monitoring for pipeline injection compliance.
- Drone-mounted inspection:Portable analyzer integration with unmanned aerial systems opens midstream pipeline survey contracts.
- Carbon capture verification:45Q tax credit rules require CO2 stream purity validation, creating adjacent demand for total hydrocarbon measurement.
Industry Challenges
- IECEx certification timelines:Hazardous-area equipment approvals for Zone 1 installations stretch 14-18 months, delaying project revenue recognition.
- Legacy DCS integration complexity:Refinery control systems running 1990s protocols require costly middleware for modern analyzer data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Total Hydrocarbon Analyzers Market |
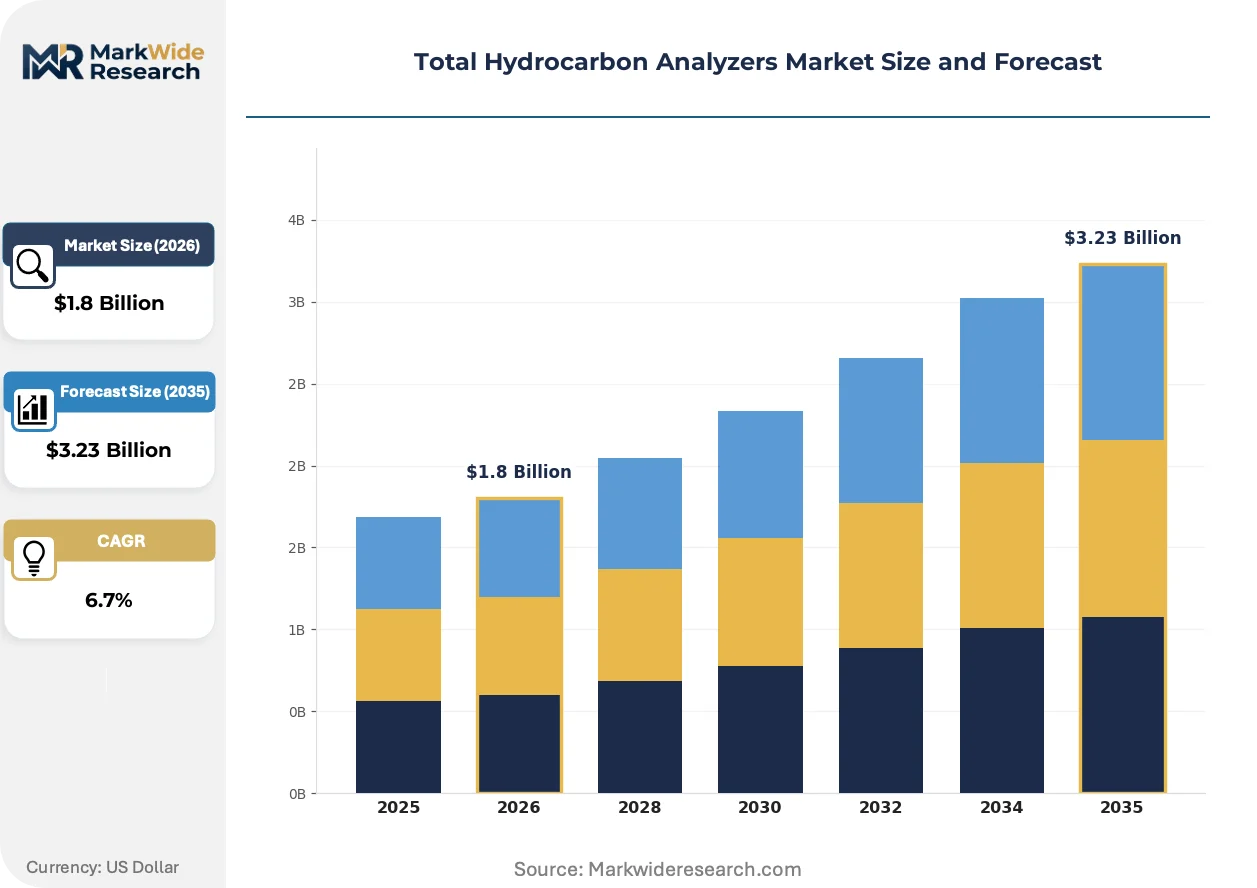
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Stationary Analyzers, Handheld Analyzers, Online Analyzers Technology: Gas Chromatography, Infrared Spectroscopy, Mass Spectrometry, Optical Sensors Application: Oil & Gas, Environmental Monitoring, Petrochemical, Water Treatment End User: Refineries, Chemical Manufacturers, Research Institutions, Regulatory Agencies |
| Companies Covered | Thermo Fisher Scientific, Teledyne Technologies, Siemens AG, AMETEK, Emerson Electric, ABB, Horiba, GE Analytical Instruments, Servomex Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Total Hydrocarbon Analyzers Market Evolving Landscape
Analyzer vendors are racing to embed predictive diagnostics and cloud connectivity into field hardware, transforming maintenance from scheduled to condition-based while opening subscription revenue streams.
Tunable diode laser spectroscopy is automating calibration routines through embedded reference cells, eliminating manual span checks. Midstream operators in the Permian Basin are deploying these self-calibrating units at remote compressor stations. The technology is automating service visit compression, cutting field technician dispatch frequency by half for distributed assets.
EPA's supplemental methane proposal tightens leak detection frequency at wellheads and tank batteries, mandating quarterly surveys versus annual for large facilities. Oil and gas producers are responding by purchasing portable optical analyzers for in-house inspection teams rather than contracting third-party surveyors. The rule is reshaping equipment ownership patterns across the Rocky Mountain and Appalachian production regions.
Refinery procurement teams are unbundling analyzer hardware from long-term service agreements, demanding separate pricing for installation, training, and maintenance. Equipment vendors face margin pressure as buyers pit specialized service contractors against OEM field teams. This shift is most pronounced along the Texas and Louisiana Gulf Coast, where petrochemical complexes run competitive tenders for analyzer maintenance across multi-site portfolios.
Total Hydrocarbon Analyzers Market Segmentation
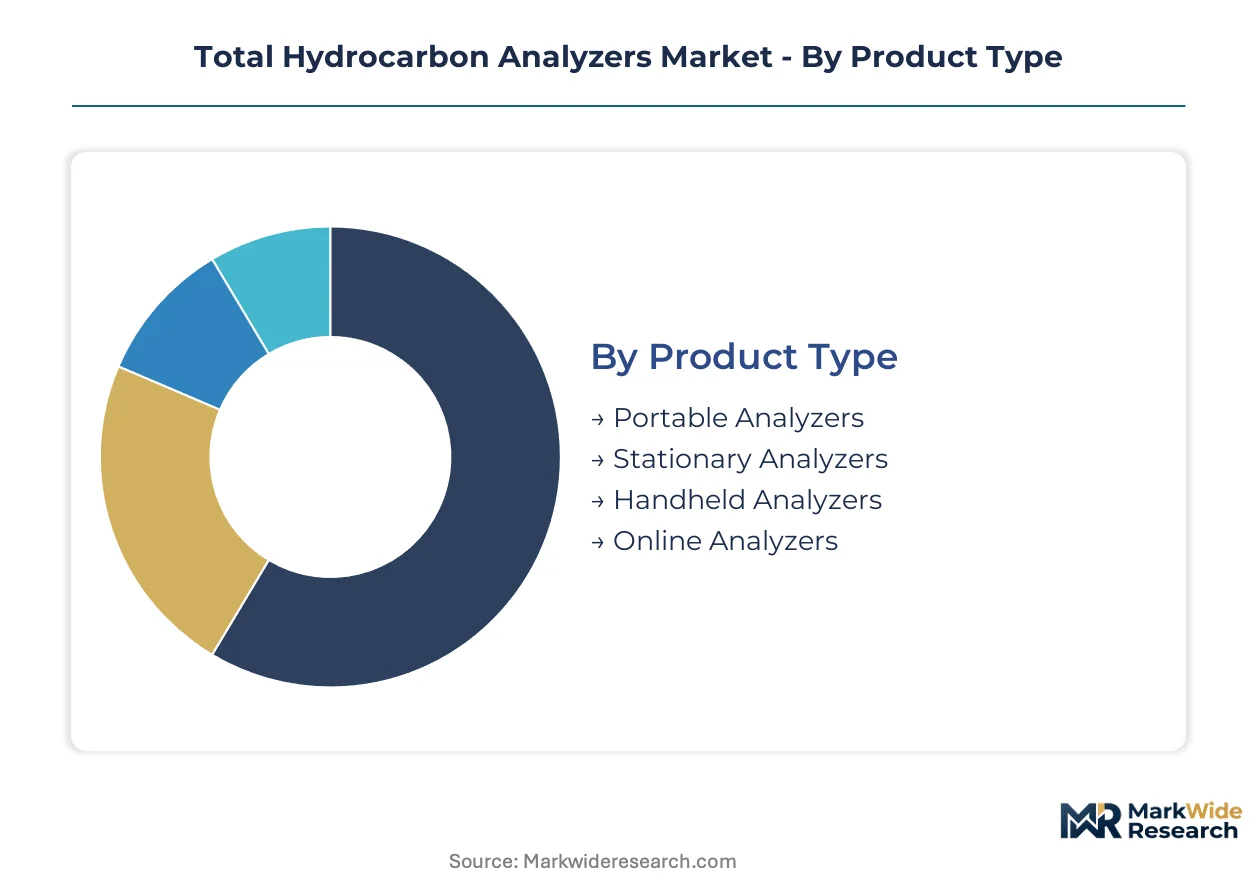
Equipment configuration in the Total Hydrocarbon Analyzers Market spans from permanent industrial installations to field-deployable inspection tools. Each segment carries distinct certification requirements, maintenance protocols, and replacement cycles that shape procurement patterns across end-use verticals.
Product Type:
Standardization dominates at the high-volume end of the spectrum, while portable variants demand customization for specific field conditions and communication protocols.
- Stationary Analyzers:Permanent rack-mounted systems with heated sample conditioning and multi-stream switching capabilities. Demand clusters at refinery flare stacks and custody transfer stations along the Texas Gulf Coast, where EPA continuous monitoring mandates drive replacement of legacy flame ionization units.
- Portable Analyzers:Battery-powered units with integrated data logging and GPS tagging for leak survey documentation. Operators in the Permian Basin and Bakken shale formations are acquiring these for quarterly wellhead inspection protocols under tightened methane rules.
- Handheld Analyzers:Lightweight single-point measurement devices for spot-checking valve seals and compressor connections.
- Online Analyzers:Real-time process stream monitors integrated into distributed control systems for closed-loop optimization.
Leading the category by volume: Stationary Analyzers. Expanding most quickly: Portable Analyzers.
Technology:
Cost tiers separate laboratory-grade precision from field-hardened durability, with mid-range optical platforms capturing ambient monitoring contracts.
- Gas Chromatography:Separation-based quantification through packed or capillary columns with flame ionization detection. Complex stream analysis in petrochemical laboratories and refinery quality control labs depends on this accuracy, though maintenance requirements limit field deployment.
- Optical Sensors:Tunable diode laser and nondispersive infrared systems with no consumable flames or carrier gases. Midstream pipeline operators favor these for remote compressor stations where technician access is constrained.
- Infrared Spectroscopy:Broadband absorption measurement for aggregate hydrocarbon determination in stack emission testing.
- Mass Spectrometry:Ion fragmentation analysis for detailed molecular identification in research and forensic applications.
Highest precision commands premium pricing: Gas Chromatography. Steepest expansion trajectory: Optical Sensors.
Application:
Customer type determines specification rigor, with oil and gas procurement teams demanding hazardous-area certifications absent from water treatment tenders.
- Oil & Gas:Upstream through downstream hydrocarbon measurement for production allocation, pipeline integrity, and emission compliance. Shale basin development in the United States anchors equipment demand, particularly for leak detection and repair programs.
- Petrochemical:Process analytics for ethylene crackers and aromatic complexes requiring continuous stream monitoring.
- Environmental Monitoring:Ambient air quality networks and fence-line monitoring for industrial facilities.
- Water Treatment:Dissolved hydrocarbon detection in wastewater discharge and potable water protection.
Dominant revenue concentration: Oil & Gas. Gaining share fastest: Environmental Monitoring.
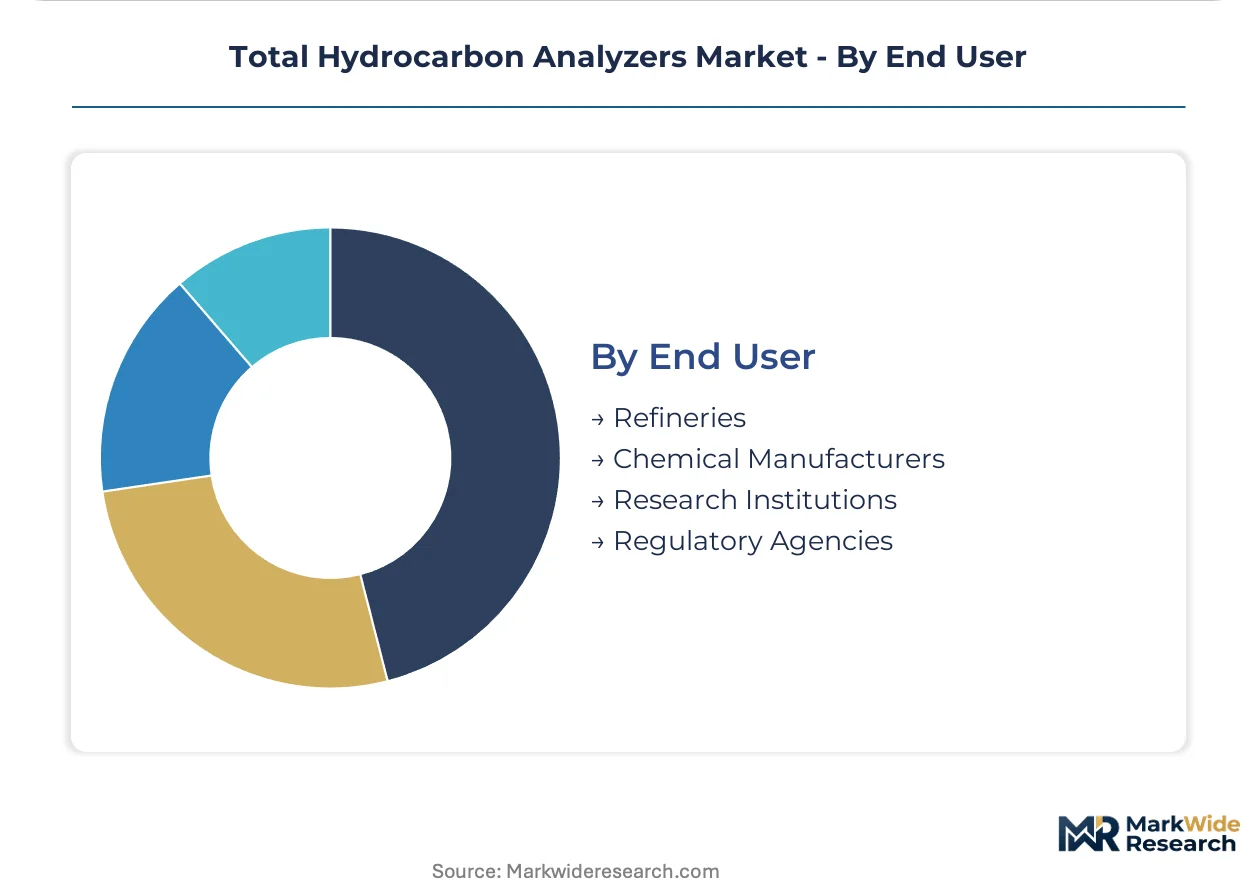
End User:
Margin profiles diverge sharply between price-sensitive regulatory procurement and value-driven refinery capital projects with long service contracts.
- Refineries:Integrated processing complexes with continuous emission monitoring systems at fluid catalytic crackers, sulfur recovery units, and storage tank vents. Gulf Coast facilities run competitive multi-year maintenance tenders that unbundle hardware from service agreements.
- Chemical Manufacturers:Specialty and commodity chemical producers with process analytical technology requirements for reactor control and product certification.
- Research Institutions:Universities and national laboratories with method development and standard reference material programs.
- Regulatory Agencies:State and federal environmental enforcement bodies with reference-grade instrumentation for compliance verification and stack testing oversight.
Largest installed base: Refineries. Fastest procurement cycle acceleration: Regulatory Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shale basins in the United States anchor geographic demand for hydrocarbon analyzers. Permian and Bakken production growth drives equipment procurement for leak detection and custody transfer monitoring.
United States
EPA methane rules under the Clean Air Act mandate quarterly leak surveys at wellheads and tank batteries. The Permian Basin in Texas and New Mexico concentrates analyzer demand for flare stack monitoring and pipeline integrity programs. Gulf Coast refineries in Texas and Louisiana run competitive tenders for continuous emission monitoring systems.
Germany
Industrial process analytics demand stems from chemical manufacturing clusters along the Rhine River. The EU F-Gas Regulation and IECEx certification frameworks shape equipment specifications for hazardous-area installations. BASF and Bayer facilities in Ludwigshafen and Leverkusen drive replacement cycles for legacy flame ionization systems.
China
Petrochemical expansion in the Yangtze River Delta and Pearl River Delta generates analyzer procurement for ethylene crackers and aromatics complexes. The Ministry of Ecology and Environment tightens volatile organic compound emission standards for industrial facilities. State-owned refineries in Shandong and Jiangsu provinces upgrade stack monitoring infrastructure.
Saudi Arabia
Saudi Aramco's Master Gas System expansion drives demand for pipeline leak detection and custody transfer measurement. The Saudi Standards, Metrology and Quality Organization implements equipment certification requirements for hazardous-area installations. Jubail Industrial City and Yanbu complexes concentrate analyzer deployment for process optimization and emission compliance.
Canada
Alberta's oil sands producers face provincial methane reduction targets requiring enhanced leak detection programs. Environment and Climate Change Canada regulations align with EPA frameworks for cross-border pipeline operators. Calgary and Edmonton serve as procurement hubs for Western Canadian shale gas and oil sands monitoring equipment.
Total Hydrocarbon Analyzers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue optical sensor miniaturization and drone integration. The vendor base stratifies across three tiers: diversified industrial conglomerates with process analytics portfolios, specialized gas detection firms with hazardous-area expertise, and regional system integrators serving local compliance markets. Consolidation pressure intensifies as refinery procurement teams unbundle hardware from service agreements. Dominant competitive moves include technology licensing for tunable diode laser spectroscopy and strategic partnerships with drone manufacturers for aerial inspection platforms.
Among diversified technology conglomerates, Thermo Fisher Scientific and Teledyne Technologies occupy positions exemplifying the chromatography and infrared detection archetypes respectively. Siemens AG represents the integrated process analytics platform approach. These three entities anchor the premium equipment tier where refinery capital projects concentrate procurement authority. Their geographic footprints span the shale basins and Gulf Coast corridors where EPA compliance deadlines accelerate replacement cycles.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Teledyne Technologies |
| Siemens AG |
| AMETEK |
| Emerson Electric |
| ABB |
| Horiba |
| GE Analytical Instruments |
| Servomex Group Limited |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up service specialists have consolidated calibration and maintenance networks across Texas and Louisiana, tightening pricing discipline for aftermarket support while compressing margins on hardware-only transactions.
Pricing Analysis
Warranty and service-bundling unbundling now dominates procurement negotiations, with Gulf Coast refineries demanding itemized pricing for installation, training, and maintenance separate from analyzer hardware. Three-tier pricing structure across premium, standard, and economy levels separates IECEx-certified hazardous-area units from general-purpose optical sensors and entry-level portable detectors. Cost compression in the standard tier is intensifying because procurement teams run competitive multi-site maintenance tenders that pit OEM field teams against third-party service contractors. Regulatory agencies exhibit the sharpest price sensitivity due to constrained public budgets, while integrated refinery operators prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with platinum catalyst suppliers concentrated in South Africa and Russia, exposing flame ionization detector manufacturers to precious metal price volatility and geopolitical disruption. Optical sensor production draws from semiconductor fabrication facilities in Taiwan, Japan, and the United States, with tunable diode laser components resting on indium phosphide wafer supply. Tariff exposure on Chinese-manufactured infrared detectors creates procurement risk for mid-range analyzer vendors. Distribution runs through authorized regional integrators who handle hazardous-area certification, installation, and calibration services for end-users across shale basins and industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA methane emission rules under the Clean Air Act erect regulatory barriers that favor established players with certified service infrastructure and IECEx approval capabilities.
For Market Incumbents: Deepen vertical integration into platinum catalyst recycling and optical component refurbishment to offset raw material volatility and capture circular economy revenue streams. Fortify service contract retention by embedding predictive diagnostics and cloud connectivity that lock refineries into subscription-based maintenance relationships, countering third-party service contractor encroachment. For New Entrants and Emerging Players: Begin with drone-mounted portable analyzer integration for midstream pipeline survey contracts in the Permian Basin, where quarterly EPA-mandated leak detection frequency outpaces incumbent service capacity. California biogas upgrading facilities represent the most penetrable segment, with methane slip monitoring requirements for pipeline injection compliance creating demand for cost-optimized optical sensors without legacy refinery certification complexity. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized gas detection firms with hazardous-area expertise and established IECEx certification track records in Texas and Louisiana, where refinery maintenance tender unbundling compresses standalone hardware margins but preserves service revenue durability. Monitor EPA supplemental methane proposal implementation timelines as the critical inflection signal for portable analyzer demand acceleration across Rocky Mountain and Appalachian production regions.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing for Tunable Diode Laser Spectroscopy | Self-calibrating optical sensors cut field technician dispatch frequency by half for Permian Basin compressor stations. |
| Strategic Partnership with Drone Manufacturers | Aerial inspection platforms open midstream pipeline survey contracts under tightened EPA quarterly leak detection mandates. |
| Backward Integration into Platinum Catalyst Supply | Captive precious metal sourcing insulates flame ionization detector production from South African and Russian supply disruption. |
| Cloud Connectivity and Predictive Diagnostics Embedding | Condition-based maintenance subscriptions transform hardware vendors into recurring revenue service providers for Gulf Coast refineries. |
| Biogas Facility Market Entry | Renewable natural gas plant methane slip monitoring in California and New York diversifies revenue beyond oil and gas cyclicality. |
Research Methodology
EPA regulatory filings, oil and gas operator sustainability reports, and IECEx certification databases formed the secondary backbone, cross-referenced with primary interviews involving refinery instrumentation managers, midstream leak detection program directors, environmental compliance officers, and analyzer OEM product strategy leads. Customs and trade data on optical component imports, SEC 10-K disclosures from diversified industrial conglomerates, and hazardous-area equipment registration records supplied quantitative anchors. Bottom-up equipment shipment analysis and top-down end-use spending estimates were triangulated to bracket market size and growth trajectories.
Historical trendline analysis of refinery capital expenditure cycles, shale basin production growth patterns, and regulatory compliance deadline clustering informed the projection framework across the analysis window. Segmentation modeling spanned product configuration, detection technology, end-use vertical, and geographic regulatory cluster. CAGRs were derived from fitted growth curves applied to equipment replacement cycles and new installation demand tied to EPA methane rule phase-in schedules. Forecast inputs incorporated tunable diode laser spectroscopy adoption curves and portable analyzer procurement acceleration under quarterly survey mandates.
Platinum price volatility, EPA enforcement intensity variation, and optical sensor water vapor cross-sensitivity resolution delays are the dominant revision risks that could compress or extend replacement timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Binary High Pressure Gradient Liquid Chromatography System Market
Testing Equipment
U-Tube Viscometer Market
Testing Equipment
High-Temperature Corrosion and Creep Testing Equipment for Process Industries Market
Testing Equipment
Flammability Test Chamber Market
Testing Equipment
Continuous Flow Analyzer Market
Testing Equipment
PFAS Ultra-Trace Water Analysis Test Instruments Market
Testing Equipment
Global Chromatography Instruments Market
Testing Equipment
Drop Weight Tear Tester Market
Testing Equipment
Rheology Controller Market
Testing Equipment
North America Dissolved Gas Analyzer Market
Testing Equipment
Polymer Testing Equipment Market
Testing Equipment
Fugitive Emissions Detection and Quantification Test Systems Market
Testing Equipment
Low-Pressure Liquid Chromatography Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Hydrogen Gas Analyzers Market
Testing Equipment
Durability Testing Systems Market