
 Isobutylene Market | 2026-2036
Isobutylene Market Size, Share, and Industry Trends Forecast 2026-2036
Isobutylene Market Outlook
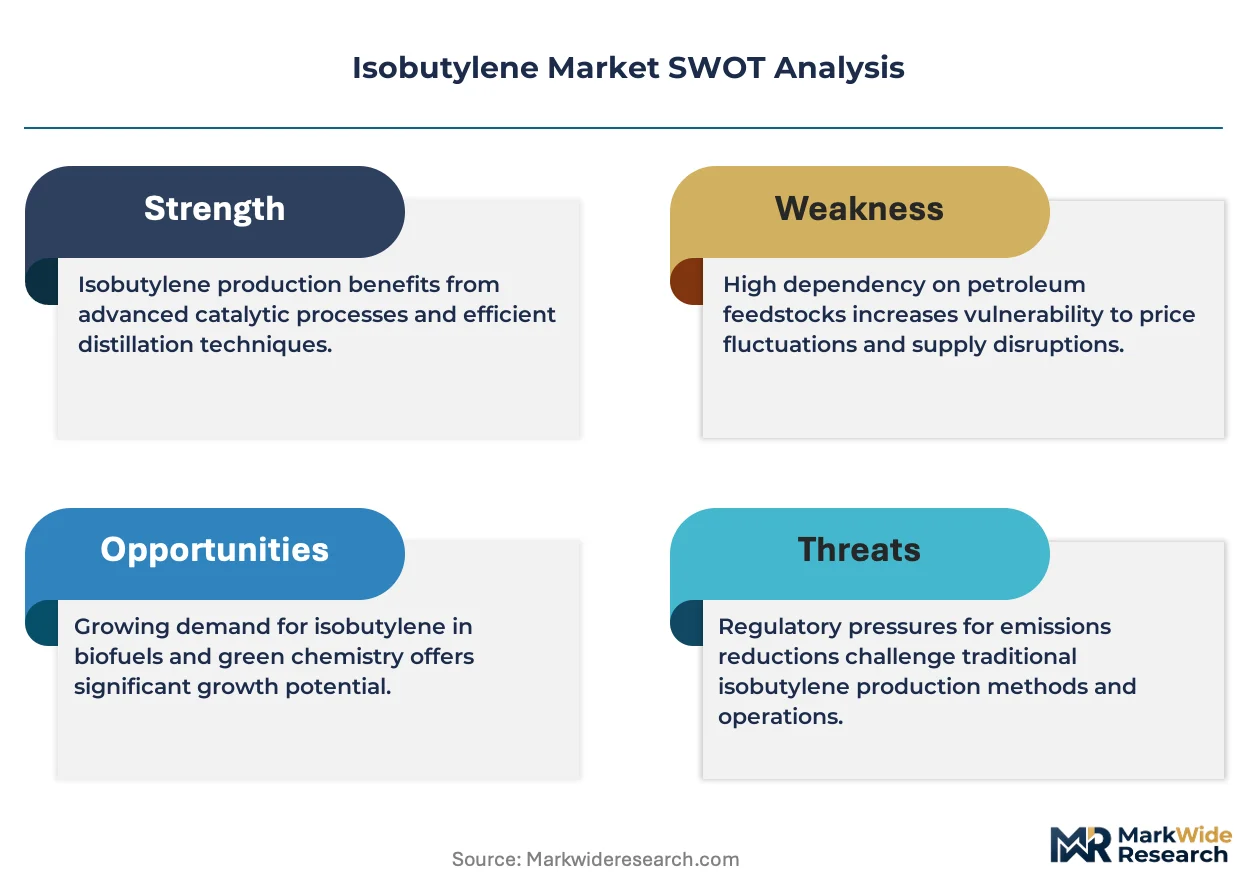
Asset-light leasing structures for steam cracker off-take agreements are reshaping competitive entry in isobutylene supply. ExxonMobil leverages integrated refinery-petrochemical complexes across the US Gulf Coast to sustain cost-advantaged feedstock access. TPC Group anchors domestic specialty-grade production through dedicated dehydrogenation units in Texas. BASF competes on technology leadership in high-purity derivative streams for pharmaceutical and fine-chemical applications.
Isobutylene is a branched C4 olefin with a molecular weight of 56.11 g/mol, produced primarily via catalytic dehydrogenation of isobutane or steam cracking of naphtha, serving as a critical feedstock for methyl tert-butyl ether, butyl rubber, and polyisobutylene lubricant additives. The fuel additives application dominates value capture due to octane enhancement mandates in transportation fuels across major economies. Rubber manufacturing represents the fastest-expanding segment as tire producers shift toward halogenated butyl grades for air-retention performance. Liquid isobutylene commands premium positioning over gaseous forms due to handling efficiency in downstream chemical synthesis.
The US EPA regulates volatile organic compound emissions from isobutylene storage and transfer under Clean Air Act provisions, while REACH in Europe imposes registration and hazard communication requirements on C4 olefin imports and derivatives. China's MEE enforces dual carbon goals that constrain coal-to-olefin routes and favor naphtha-based or dehydrogenation pathways with lower carbon intensity. Stakeholders must monitor evolving carbon border adjustment mechanisms and feedstock slates to secure long-term offtake contracts without stranded asset exposure.
Market Dynamics
Asset-light leasing structures for steam cracker off-take agreements are compressing capital barriers for new entrants while fragmenting supply concentration among integrated refinery-petrochemical complexes.
Growth Catalysts
- REACH and F-Gas Regulation:European emission mandates accelerate producer migration toward catalytic dehydrogenation pathways with lower carbon intensity. Specialty chemical buyers now specify certified low-emission isobutylene grades in procurement contracts.
- Reformulated gasoline standards:Octane enhancement mandates across major economies sustain methyl tert-butyl ether demand as a blending component. Automotive OEMs tighten fuel additive specifications to meet tailpipe emission targets.
- China's butyl rubber capacity scaling:Domestic tire manufacturers expand halogenated butyl rubber production for air-retention performance in electric vehicle tires. This concentrates derivative demand within integrated petrochemical zones.
Market Restraints
- Propylene co-production economics:Steam cracking yields isobutylene as a byproduct tied to naphtha feedstock volatility. Crude price swings compress margin predictability for non-integrated producers lacking captive refinery supply.
- US Gulf Coast supply concentration:Over half of North American specialty-grade capacity clusters along Texas-Louisiana chemical corridors. Hurricane exposure and pipeline bottlenecks create systemic disruption risk.
- Alkylation unit substitution:Refiners increasingly divert C4 streams to gasoline alkylation rather than chemical-grade extraction. This tightens merchant isobutylene availability for downstream derivative producers.
Strategic Opportunities
- India's specialty chemical import substitution:Domestic pharmaceutical and agrochemical formulators seek local high-purity isobutylene sources. PLI scheme incentives support dehydrogenation unit investments.
- Bio-based isobutylene pathways:Fermentation and biomass gasification technologies converge to produce renewable C4 olefins. Brand-owners in lubricant additives specify bio-content for Scope 3 reduction.
- Carbon border adjustment mechanisms:EU CBAM creates premium positioning for low-carbon-intensity production routes. Exporters with verified lifecycle assessments capture preferential offtake terms.
Industry Challenges
- Catalytic dehydrogenation engineering expertise:Chromia-alumina catalyst optimization and reactor design require specialized petrochemical process knowledge. Talent scarcity constrains debottlenecking timelines.
- High-purity certification timelines:Pharmaceutical-grade polyisobutylene derivatives demand multi-year validation protocols. Regulatory filing backlogs delay commercialization of new production assets.
- Legacy storage infrastructure compatibility:Existing sphere and bullet tank farms designed for gaseous handling require retrofit for liquid isobutylene logistics. Terminal operators face capex decisions amid demand uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isobutylene Market |
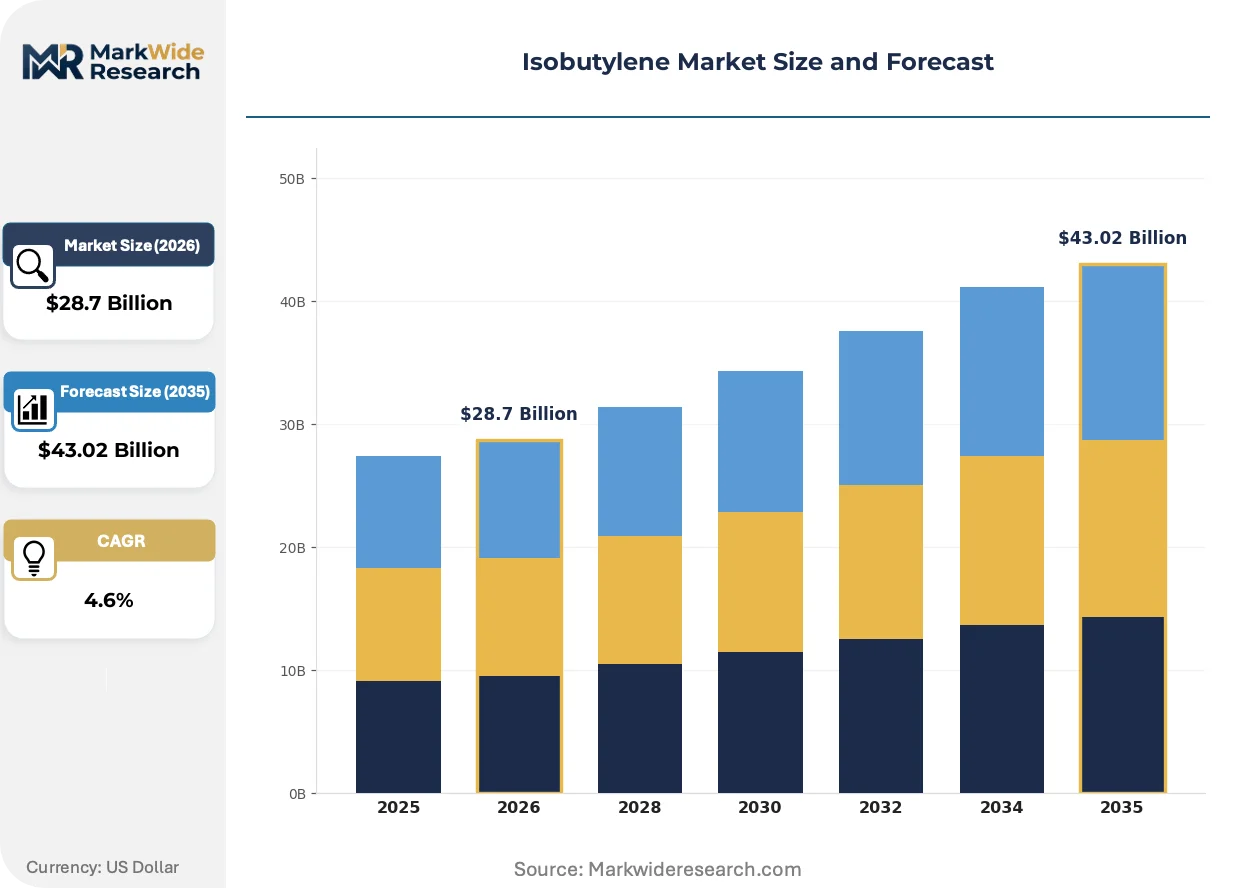
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $43.02 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas, Liquid, Polymer, Intermediate End Use Industry: Automotive, Agriculture, Chemicals, Pharmaceuticals Application: Fuel Additives, Rubber Manufacturing, Plastic Production, Lubricants Production Method: Dehydrogenation, Cracking, Catalytic Processes, Extraction |
| Companies Covered | ExxonMobil, TPC Group, BASF, LyondellBasell Industries, Shell plc, Evonik, Sumitomo Chemical, SIBUR Holding, Enterprise Products Partners, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isobutylene Market Strategic Shifts
Oxidative dehydrogenation catalyst advances and modular reactor designs are compressing the scale economics that historically favored mega-complex production.
Single-pass oxidative dehydrogenation using metal oxide catalysts achieves higher isobutylene selectivity than conventional steam cracking routes. Specialty chemical producers in pharmaceutical and fine-chemical applications adopt these units for captive feedstock security. The technology is rendering obsolete the assumption that only integrated refineries can achieve cost-competitive C4 olefin supply.
China's MEE enforces dual carbon goals that constrain coal-to-olefin routes and favor naphtha-based or dehydrogenation pathways with lower carbon intensity. Domestic producers face emissions intensity benchmarks that disqualify older production assets from operating permits. The regulation most acutely affects Shandong and Jiangsu province chemical clusters, where producers accelerate carbon capture retrofits.
Long-term offtake contracting with fixed-price escalators is displacing spot market purchases among tire manufacturers and lubricant additive blenders. Buyers seek supply security amid feedstock volatility, while producers lock in utilization rates for new dehydrogenation investments. This pattern concentrates in China and India, where domestic capacity expansion outpaces demand growth.
Isobutylene Market Segmentation
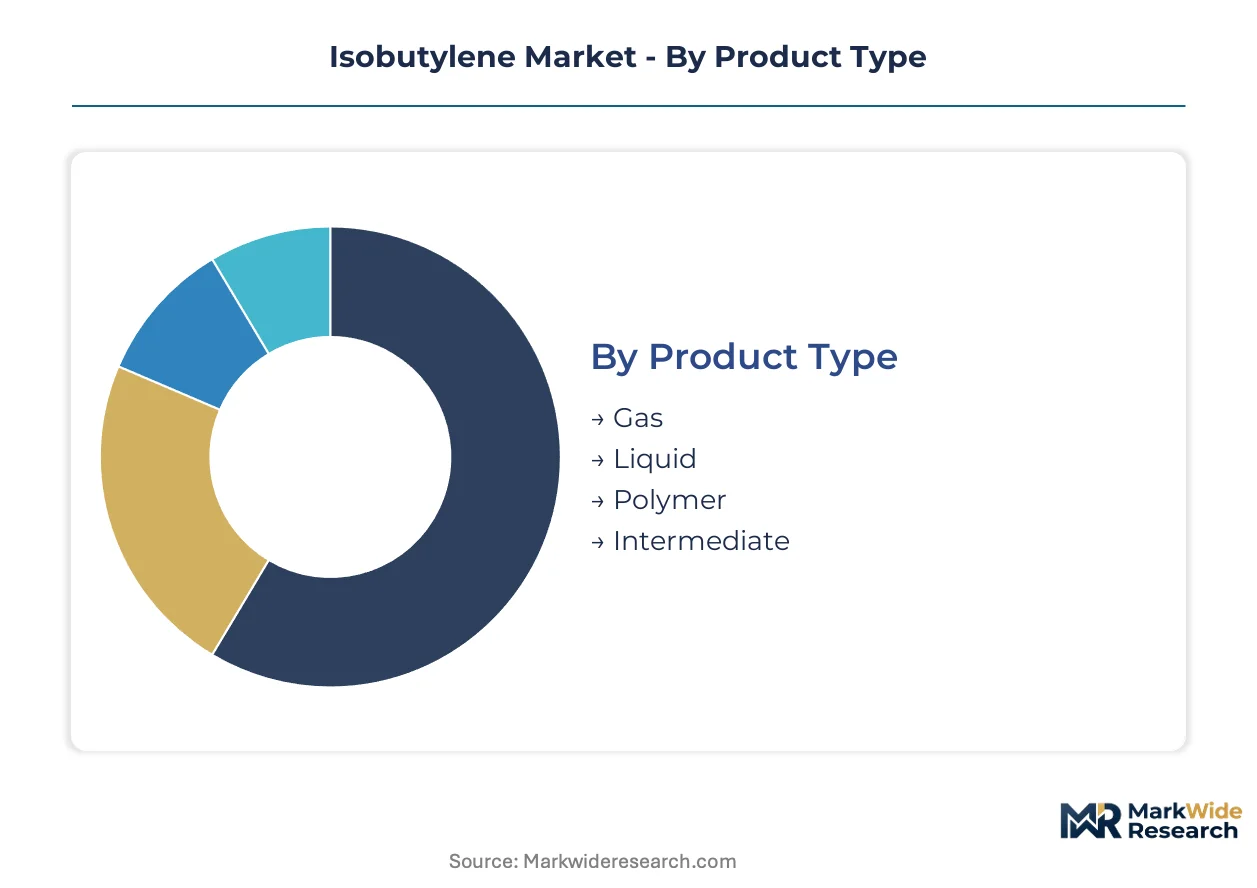
Isobutylene derivatives serve fundamentally different technical specifications across fuel blending, rubber curing, and pharmaceutical synthesis. Segmentation reveals how purity grades, physical states, and production pathways create distinct margin profiles and customer lock-in mechanisms.
Product Type:
Physical state and molecular configuration determine handling infrastructure, transport economics, and downstream compatibility.
- Liquid:Condensed form enables efficient bulk transport via rail and marine terminals. Chemical manufacturers in Texas and Louisiana prefer liquid delivery for continuous methyl tert-butyl ether production.
- Gas:Requires pressurized sphere storage and specialized vapor recovery systems. Refinery-integrated consumers capture gaseous streams directly from FCC off-gas without condensation costs.
- Polymer:Polyisobutylene grades span molecular weights from 300 to 50,000 daltons for sealant and lubricant applications.
- Intermediate:Partially purified streams feed captive butyl rubber units without final distillation.
Liquid holds installed capacity. Polymer is rotating up the share rankings.
End Use Industry:
Customer industries impose divergent certification protocols and volume requirements.
- Automotive:Tire manufacturers specify halogenated butyl rubber for inner liners and tubeless retention. Electric vehicle platforms double air-retention specifications versus conventional powertrains.
- Chemicals:Agrochemical and adhesive formulators drive merchant demand for high-purity methyl tert-butyl ether and polyisobutylene derivatives.
- Agriculture:Crop protection intermediates require pharmaceutical-grade isobutylene for active ingredient synthesis.
- Pharmaceuticals:Excipient and packaging sealant applications demand USP-grade polyisobutylene with full traceability documentation.
Automotive maintains volume leadership. Chemicals is climbing the fastest as specialty derivative demand broadens.
Application:
Downstream conversion chemistry determines value capture and regulatory exposure.
- Rubber Manufacturing:Butyl and halobutyl rubber production consumes isobutylene in copolymerization with isoprene. Domestic tire capacity expansion in China concentrates demand within integrated petrochemical zones.
- Fuel Additives:Methyl tert-butyl ether blending for octane enhancement faces regulatory pressure from groundwater contamination concerns. REACH and EPA restrictions constrain new capacity in Europe and North America.
- Lubricants:Polyisobutylene viscosity modifiers command premium pricing for synthetic motor oil formulations.
- Plastic Production:Specialty copolymers and modifier applications represent niche volume.
Fuel Additives retains legacy infrastructure. Rubber Manufacturing is gaining share fastest on electric vehicle tire specifications.
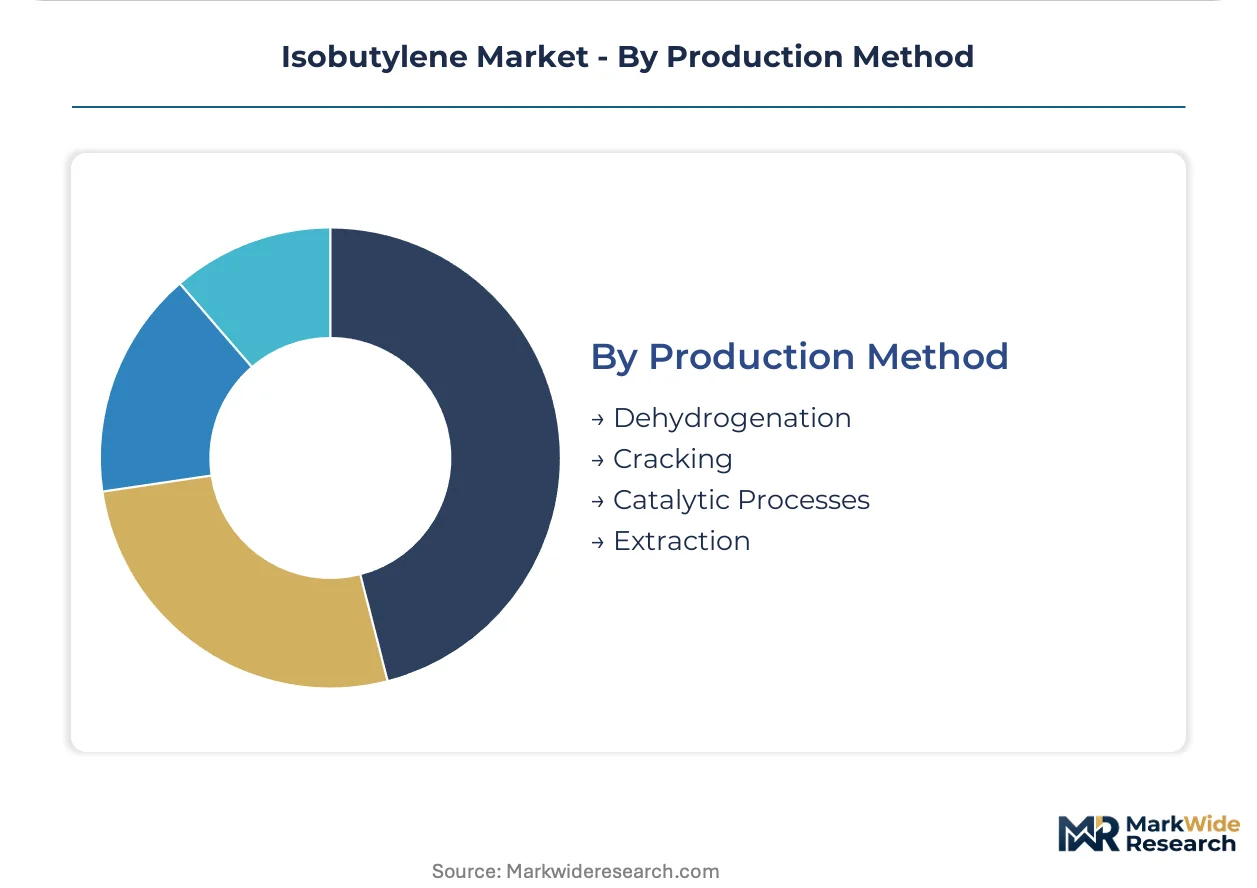
Production Method:
Feedstock flexibility and carbon intensity separate competitive positions.
- Dehydrogenation:Catalytic conversion of isobutane achieves dedicated isobutylene yields above 50 percent. TPC Group operates chromia-alumina units in Texas for specialty-grade supply.
- Catalytic Processes:Oxidative dehydrogenation using metal oxide catalysts reduces energy intensity versus steam cracking. Modular reactor designs enable mid-scale producers to achieve cost parity with integrated refineries.
- Cracking:Steam cracking of naphtha yields mixed C4 streams requiring extractive distillation. Crude price volatility compresses margin predictability for non-integrated operators.
- Extraction:Recovery from refinery FCC off-gas or steam cracker streams depends on alkylation unit economics for alternative C4 disposition.
Dehydrogenation holds installed capacity. Catalytic Processes is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redirecting isobutylene trade flows as regional self-sufficiency strategies clash with feedstock cost differentials. The United States maintains net export positioning through Gulf Coast petrochemical integration. China and Germany anchor import substitution programs that reshape traditional supply corridors.
United States
Automotive OEMs in Detroit and tire manufacturers in South Carolina drive specialty-grade consumption. EPA Clean Air Act provisions govern VOC emissions from Texas storage terminals. The Houston Ship Channel corridor concentrates dehydrogenation capacity operated by integrated refinery-petrochemical complexes.
China
Domestic butyl rubber scaling for electric vehicle tires absorbs merchant isobutylene volumes. MEE dual carbon goals disqualify coal-to-olefin assets in Shandong province. Ningbo and Shanghai chemical clusters host naphtha-based steam crackers with lower emissions intensity.
Germany
REACH registration requirements and F-Gas Regulation push pharmaceutical-grade polyisobutylene demand toward certified low-emission supply. ECHA hazard communication protocols extend to C4 olefin derivatives. Ludwigshafen and Marl industrial zones anchor BASF's integrated production of high-purity streams.
India
Pharmaceutical formulators in Mumbai and agrochemical blenders in Gujarat seek import substitution for high-purity feedstock. PLI scheme incentives support dehydrogenation unit investments. Dahej and Hazira chemical clusters attract capacity additions targeting specialty derivative exports.
Saudi Arabia
Refinery-petrochemical integration at Jubail and Yanbu captures C4 streams for regional methyl tert-butyl ether supply. SAMR standards align with international certification for lubricant additive exports. SABIC-affiliated complexes leverage ethane cracking economics to undercut naphtha-based European producers.
Isobutylene Market Competitive Environment
On the supply side, the industry is consolidating around integrated refinery-petrochemical complexes with captive feedstock access. Merchant producers face margin compression from naphtha volatility and alkylation unit competition for C4 streams. Two strategic archetypes dominate: Gulf Coast integrated operators with steam cracker integration, and European technology leaders specializing in pharmaceutical-grade purification. Capacity expansion and long-term offtake contracting represent the primary competitive moves as producers secure utilization rates ahead of carbon border adjustment implementation.
Within the integrated refinery-petrochemical tier, ExxonMobil and Shell plc exemplify scale-driven positioning through US Gulf Coast complex ownership. TPC Group represents the dedicated specialty-grade archetype with focused dehydrogenation operations. BASF occupies the technology leadership position in high-purity derivative streams. SIBUR Holding anchors the emerging market supply vector with Russian feedstock integration. Sumitomo Chemical and Evonik sit within the Asia-Pacific and European specialty chemical tiers respectively, though their specific strategic emphases vary by regional demand concentration.
| Leading Market Players |
|---|
| ExxonMobil |
| TPC Group |
| BASF |
| LyondellBasell Industries |
| Shell plc |
| Evonik |
| Sumitomo Chemical |
| SIBUR Holding |
| Enterprise Products Partners |
| Others |
Value Chain & Pricing Dynamics
Hurricane exposure along the Texas-Louisiana chemical corridor compresses pricing power for non-integrated merchant producers while amplifying premium spreads for Gulf Coast integrated operators with captive refinery access. This geographic risk concentration simultaneously shapes contract structures and drives diversification into asset-light leasing arrangements.
Pricing Analysis
Industrial OEM buyers anchor long-term offtake contracting with fixed-price escalators that displace spot market purchases. Pricing stratifies across pharmaceutical-grade, specialty-chemical-grade, and fuel-blending-grade tiers based on purity certification and traceability documentation. Cost compression in fuel-additive grades is intensifying because alkylation unit economics divert C4 streams toward gasoline blending rather than chemical extraction. Tire manufacturers demonstrate highest price sensitivity due to volume scale, while pharmaceutical formulators accept premium positioning for USP-grade polyisobutylene with full batch documentation.
Supply Chain Analysis
Enterprise Products Partners and TPC Group hold dominant midstream and production capacity positions across the US Gulf Coast. Supply concentrates in the United States, China, and Germany, with feedstock draws from naphtha crackers, refinery FCC off-gas, and dedicated isobutane dehydrogenation units. Raw material dependencies rest on crude oil price volatility, isobutane feedstock availability, and chromia-alumina catalyst supply. Single-source vulnerability runs through the Houston Ship Channel corridor where pipeline bottlenecks and storm disruption risk concentrate. Distribution runs through long-term supply agreements with integrated petrochemical complexes rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tire manufacturer consolidation in China and India has shifted procurement leverage toward buyers capable of committing decade-long offtake volumes. This buyer-power concentration rewards producers with balance sheet capacity to front-load dehydrogenation investments.
For Market Incumbents: Harden feedstock security through backward integration into isobutane supply or refinery-petrochemical complex ownership. Deepen certification investment for pharmaceutical-grade polyisobutylene to defend margin position against emerging oxidative dehydrogenation entrants with lower carbon intensity. Chromia-alumina catalyst optimization and reactor engineering expertise represents a defensible capability moat as talent scarcity constrains competitor debottlenecking timelines. For New Entrants and Emerging Players: Build out modular oxidative dehydrogenation units targeting India's specialty chemical import substitution opportunity under PLI scheme incentives. Pharmaceutical and agrochemical formulators in Mumbai and Gujarat present the most penetrable white-space for high-purity isobutylene supply. A go-to-market angle anchored in verified lifecycle assessments for EU CBAM compliance captures premium positioning over legacy naphtha-based producers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated refinery-petrochemical operators with captive C4 stream access. Long-term viability hinges on carbon intensity positioning as border adjustment mechanisms phase in. Acquisition target archetypes include mid-scale dehydrogenation specialists with pharmaceutical-grade certification and stranded naphtha-cracker assets in low-cost feedstock geographies. The signal to watch is MEE enforcement intensity against coal-to-olefin routes in Shandong province, which would accelerate demand migration toward certified low-emission supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive isobutane supply from refinery streams insulates margin from naphtha volatility. |
| Green Manufacturing Transition | Oxidative dehydrogenation with metal oxide catalysts reduces emissions intensity for EU CBAM positioning. |
| Long-term Supply Agreement | Fixed-price escalators with tire manufacturers lock in utilization rates ahead of capacity additions. |
| Capacity Expansion | Dehydrogenation unit investments in Dahej and Hazira clusters target India's import substitution demand. |
| Joint Venture | Partnerships with pharmaceutical formulators accelerate USP-grade polyisobutylene validation protocols. |
Study Parameters
Cross-validation between primary interviews with plant managers, procurement leads at downstream tire OEMs, distribution channel partners, and technical R&D directors and secondary validation through customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA emission disclosures anchors the qualitative findings. Bottom-up capacity and utilization assessments triangulate against top-down demand modeling across derivative applications. The analysis integrates forward-looking regulatory trajectories from EPA, ECHA, and China's MEE without projecting specific policy implementation dates.
Calibration against historical capacity addition patterns and offtake contract tenors shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include physical state, end-use industry, application chemistry, and production pathway feedstock. CAGRs derive from derivative demand elasticity to automotive production, tire specification evolution, and fuel additive regulatory constraints. Industry-specific forecast inputs incorporate electric vehicle air-retention specifications and REACH registration timelines for pharmaceutical-grade streams.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated refinery-petrochemical operators or state-backed Chinese capacity additions would shift outcomes. Unmodeled risks include alkylation unit economics diverting C4 streams permanently away from chemical extraction, and carbon border adjustment mechanism scope expansion beyond pilot phases. Quarterly review of MEE enforcement actions, EU CBAM verification protocol development, and Gulf Coast storm disruption frequency is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
US Nitrile Gloves Market
Rubber
Rubber Foam Materials Market
Rubber
Global Chloroprene Rubber Market
Rubber
Rubber Conveyor Belt Market
Rubber
Reclaimed Rubber Market
Rubber
Global Automotive Elastomers Market
Rubber
Recycled Elastomers Market
Rubber
Silica for S-SBR Market
Rubber
Polybutadiene Market
Rubber
Rubber Masterbatch Market
Rubber
Chloroprene Rubber Modified Asphalt Emulsion Market
Rubber
Rubber Compound Market
Rubber
Tire Reinforcement Materials Market
Rubber
Polyisoprene Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Rubber Accelerators Market