
 Freeze-Thaw Stabilizers Market | 2026-2036
Freeze-Thaw Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze-Thaw Stabilizers Market Analytics
REACH is repositioning the cost-of-entry calculus for freeze-thaw stabilizer suppliers selling into European food manufacturing. Thermo Fisher Scientific leverages its analytical certification infrastructure to validate additive purity for export compliance. BioLife Solutions anchors its positioning through specialized cold-chain logistics expertise that extends into stabilizer distribution for temperature-sensitive ingredients.
Freeze-thaw stabilizers are hydrocolloid, emulsifier, protein, or sugar-based additives that maintain texture, viscosity, and water-holding capacity through repeated temperature cycling, typically functioning at concentrations between 0.1% and 2.0% by weight in finished food matrices. Their primary commercial purpose is preventing syneresis, ice crystal growth, and phase separation in frozen and refrigerated goods during distribution. Hydrocolloids occupy the dominant margin pool due to their multifunctional performance in dairy applications, while emulsifier demand is accelerating fastest in plant-based frozen dessert formulations where fat-protein stabilization proves technically challenging. Powdered forms sustain the largest volume share given handling efficiency in industrial batch processing, though liquid concentrates are gaining traction in automated inline dosing systems at beverage production facilities.
The FDA's Food Safety Modernization Act and EFSA's re-evaluation programs for food additives are tightening toxicological data requirements for stabilizer approvals, directly extending product development timelines and testing expenditures for new entrants. Japan's FSSC 22000-aligned standards and China's GB 2760 food additive positive list create divergent compliance pathways that fragment formulation strategies across export markets. Stakeholders must monitor regulatory harmonization negotiations between Codex Alimentarius and national frameworks to anticipate whether unified purity standards will consolidate supplier landscapes or preserve regional formulation specialization.
Market Dynamics
Clean-label formulation mandates from EFSA and FDA are compressing the acceptable additive palette for freeze-thaw stabilizers, forcing suppliers to validate hydrocolloid functionality under stricter purity thresholds while maintaining cost parity with legacy emulsifier systems.
Growth Catalysts
- EFSA Re-evaluation Programs:Toxicological data requirements for food additives are tightening approval standards, advantaging incumbent suppliers with established dossiers and certified manufacturing infrastructure.
- Plant-Based Frozen Desserts:Fat-protein stabilization challenges in oat and almond-based formulations are accelerating emulsifier demand where technical performance gaps exceed conventional dairy processing tolerances.
- German Industrial Clusters:Concentrated bakery and dairy processing capacity around Munich and Hamburg sustains specialized stabilizer supply chains with just-in-time logistics integration.
Market Restraints
- Locust Bean Gum Volatility:Supply concentration in Mediterranean harvesting regions exposes hydrocolloid costs to climate-induced crop yield fluctuations and speculative commodity positioning.
- REACH Compliance Burden:Purity benchmarking for emulsifiers under EU chemical registration protocols extends validation timelines and analytical certification expenditures for new market entrants.
- Starch Substitution Threat:Modified starches from adjacent hydrocolloid categories are capturing cost-sensitive applications where texture tolerance permits reduced freeze-thaw cycle performance.
Strategic Opportunities
- India Cold-Chain Expansion:FSSAI-aligned frozen food distribution infrastructure is creating first-mover positioning for stabilizer suppliers with temperature-sensitive ingredient logistics capabilities.
- Automated Inline Dosing:Beverage production facilities are converting from powder handling to liquid concentrate systems, opening channel differentiation for pumpable stabilizer formulations.
- EU Green Deal Procurement:Sustainability-linked purchasing criteria in public food service contracts are favoring bio-based hydrocolloids with verified carbon footprint documentation.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in hydrocolloid-protein interaction modeling is concentrating at established suppliers, constraining R&D velocity for mid-tier competitors.
- FSSC 22000 Certification Timelines:Food safety management system audits for stabilizer manufacturing facilities are extending by four to six months due to auditor capacity constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze-Thaw Stabilizers Market |
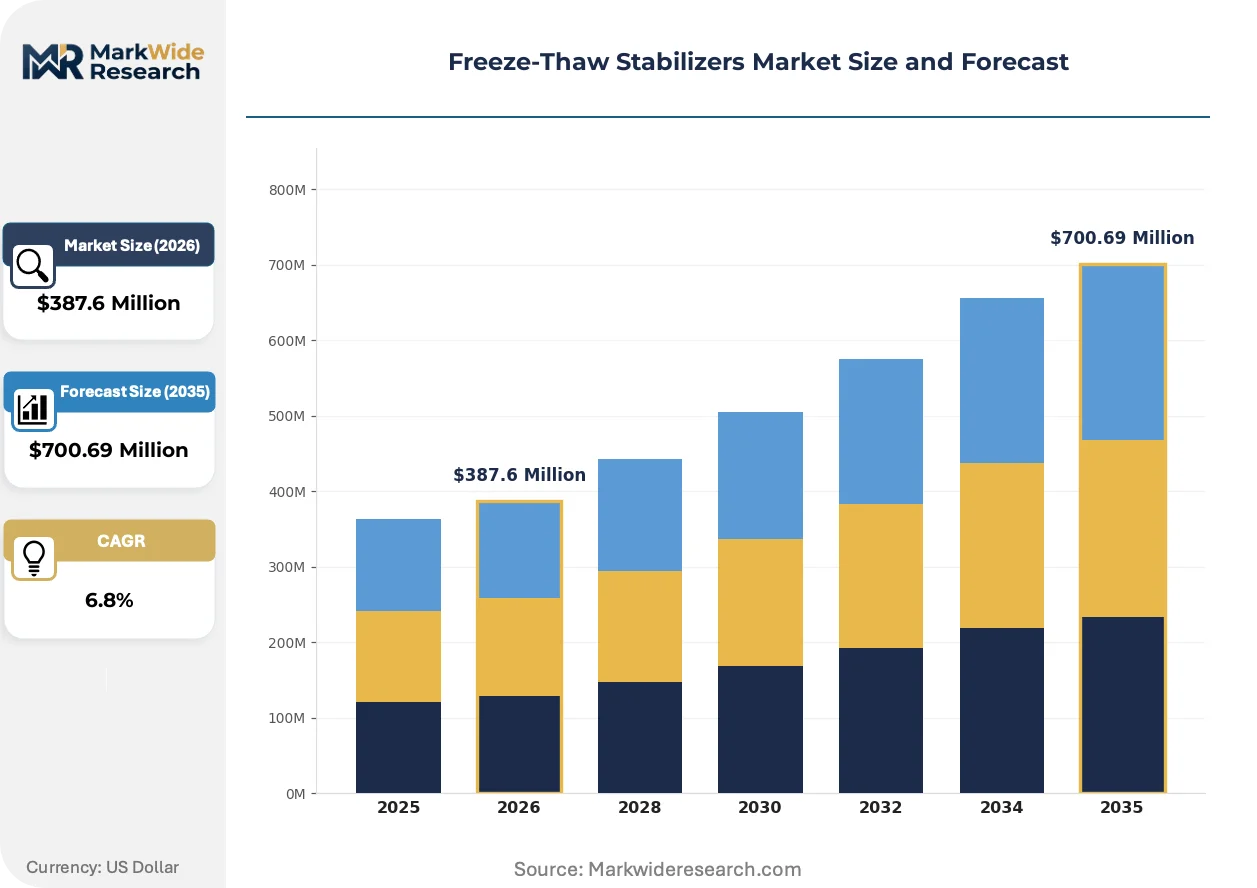
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloids, Emulsifiers, Proteins, Sugars Application: Dairy Products, Frozen Desserts, Sauces, Soups End User: Food Manufacturers, Beverage Producers, Catering Services, Retail Chains Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Thermo Fisher Scientific, Sartorius, BioLife Solutions, GE Healthcare, Cytiva, Meissner Filtration Products, HOF Sonderanlagenbau GmbH, Helmer Scientific, Single Use Support GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze-Thaw Stabilizers Market Evolving Landscape
Active reformulation of frozen dessert matrices is compressing the performance gap between clean-label hydrocolloids and conventional synthetic stabilizers, with adoption velocity determined by regulatory deadline proximity rather than technical readiness alone.
Fermentation-derived hydrocolloids are absorbing the functional load previously carried by chemically modified cellulose derivatives in premium ice cream applications. Artisanal and super-premium manufacturers in France and Italy are adopting these bio-based alternatives at three times the rate of mass-market processors. This absorption is compressing the addressable market for petrochemical-derived stabilizers while expanding the certified-organic ingredient tier.
REACH authorization requirements for persistent organic pollutants in food-contact substances are forcing emulsifier suppliers to revalidate supply chains for glycerol and fatty acid feedstocks. Industrial bakeries in Poland and the Netherlands are experiencing the most acute compliance friction due to legacy supplier concentration in non-EU jurisdictions. Affected processors are accelerating dual-sourcing strategies and demanding extended substance documentation from existing vendors.
Buyer consolidation among European retail private-label frozen dessert manufacturers is compressing supplier negotiation cycles and unbundling technical service from commodity pricing. Mid-sized stabilizer distributors in Belgium and Denmark are losing shelf position to direct manufacturer relationships as procurement functions centralize at German and Swiss headquarters. This concentration is most visible in the dairy-alternative segment where formulation complexity demands embedded technical support.
Freeze-Thaw Stabilizers Market Segmentation
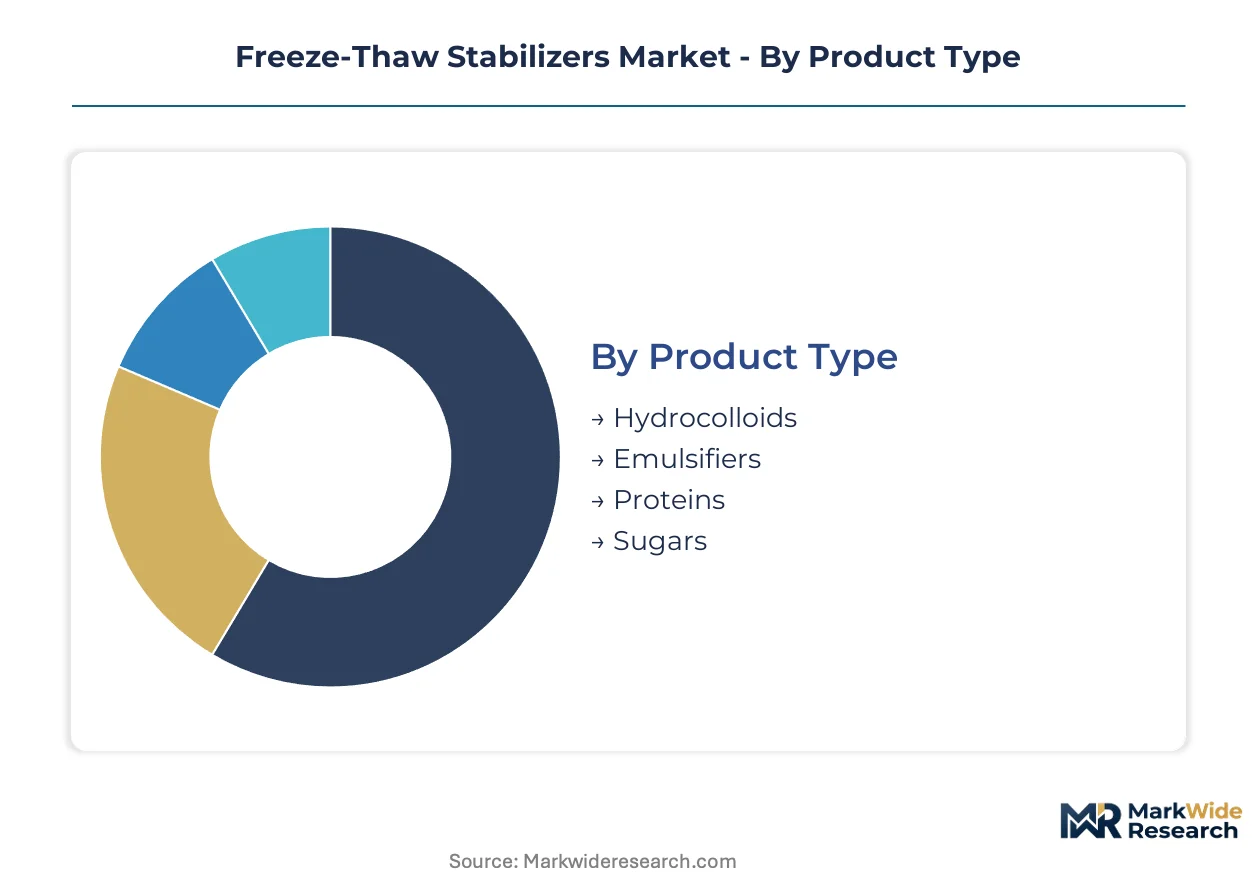
Freeze-thaw stabilizer procurement patterns diverge sharply across product chemistry and application matrix, with hydrocolloid buyers prioritizing multifunctional performance while emulsifier purchasers chase fat-protein stabilization in plant-based formulations. Form selection—powder versus liquid—determines logistics infrastructure requirements and dictates supplier qualification criteria for automated versus batch processing environments.
Product Type:
Hydrocolloids function as standalone texturizing systems in most frozen dairy matrices, whereas emulsifiers and proteins typically require co-formulation with secondary stabilizers to achieve full freeze-thaw resilience.
- Hydrocolloids:Polysaccharide networks from locust bean gum, guar, and carrageenan establish viscosity and water-holding capacity at 0.1-1.5% inclusion rates. German industrial dairy clusters around Munich sustain the densest procurement concentration, driven by clean-label mandates from EFSA's additive re-evaluation programs that advantage established hydrocolloid dossiers over novel chemistries.
- Emulsifiers:Mono- and diglycerides plus lecithin derivatives stabilize fat-protein interfaces during temperature cycling, critical for oat and almond-based frozen desserts where conventional dairy fat structures are absent. REACH purity benchmarks for glycerol feedstocks are extending validation timelines for new entrants, concentrating supply relationships with incumbent European manufacturers.
- Proteins:Milk and plant-derived proteins contribute structure through denaturation and gelation during freezing, typically requiring hydrocolloid co-stabilization for full syneresis control.
- Sugars:Cryoprotectant sugars including sorbitol and trehalose depress freezing points and inhibit ice crystal propagation in premium frozen dessert applications.
Hydrocolloids lead volumes today; emulsifiers are gaining share fastest.
Application:
Application segmentation tracks processing temperature severity and matrix complexity, with frozen desserts demanding the most sophisticated multi-component stabilization systems.
- Dairy Products:Ice cream and frozen yogurt formulations rely on hydrocolloid-protein synergies to control ice crystal growth through distribution cold chains. Italian artisanal manufacturers are adopting fermentation-derived alternatives at three times the rate of mass-market processors.
- Frozen Desserts:Plant-based formulations present acute fat-protein stabilization challenges where technical performance gaps exceed conventional dairy tolerances, accelerating emulsifier demand in this segment.
- Sauces:Cream-based frozen sauces require viscosity recovery after thawing, typically achieved with xanthan gum or modified starch systems at lower inclusion rates than dessert applications.
- Soups:Ready-to-heat frozen soups prioritize freeze-thaw stability without visible separation, favoring cost-optimized hydrocolloid blends over premium single-ingredient solutions.
Dairy Products anchor current procurement volumes; Frozen Desserts show the steepest expansion trajectory.
End User:
End user categories separate by technical service intensity, with food manufacturers demanding embedded formulation support while retail chains prioritize supply security and price stability.
- Food Manufacturers:Industrial dairy and bakery processors around Hamburg and Munich sustain specialized stabilizer supply chains with just-in-time logistics integration and dedicated technical service teams.
- Beverage Producers:Frozen beverage applications are converting from powder handling to liquid concentrate systems, opening channel differentiation for pumpable stabilizer formulations with automated inline dosing compatibility.
- Catering Services:Bulk frozen food service operations prioritize cost-optimized stabilizer blends with acceptable texture tolerance across variable thawing conditions.
- Retail Chains:Private-label frozen dessert procurement centralization at German and Swiss headquarters is compressing supplier negotiation cycles and unbundling technical service from commodity pricing.
Food Manufacturers dominate current offtake; Beverage Producers are expanding most quickly.
Form:
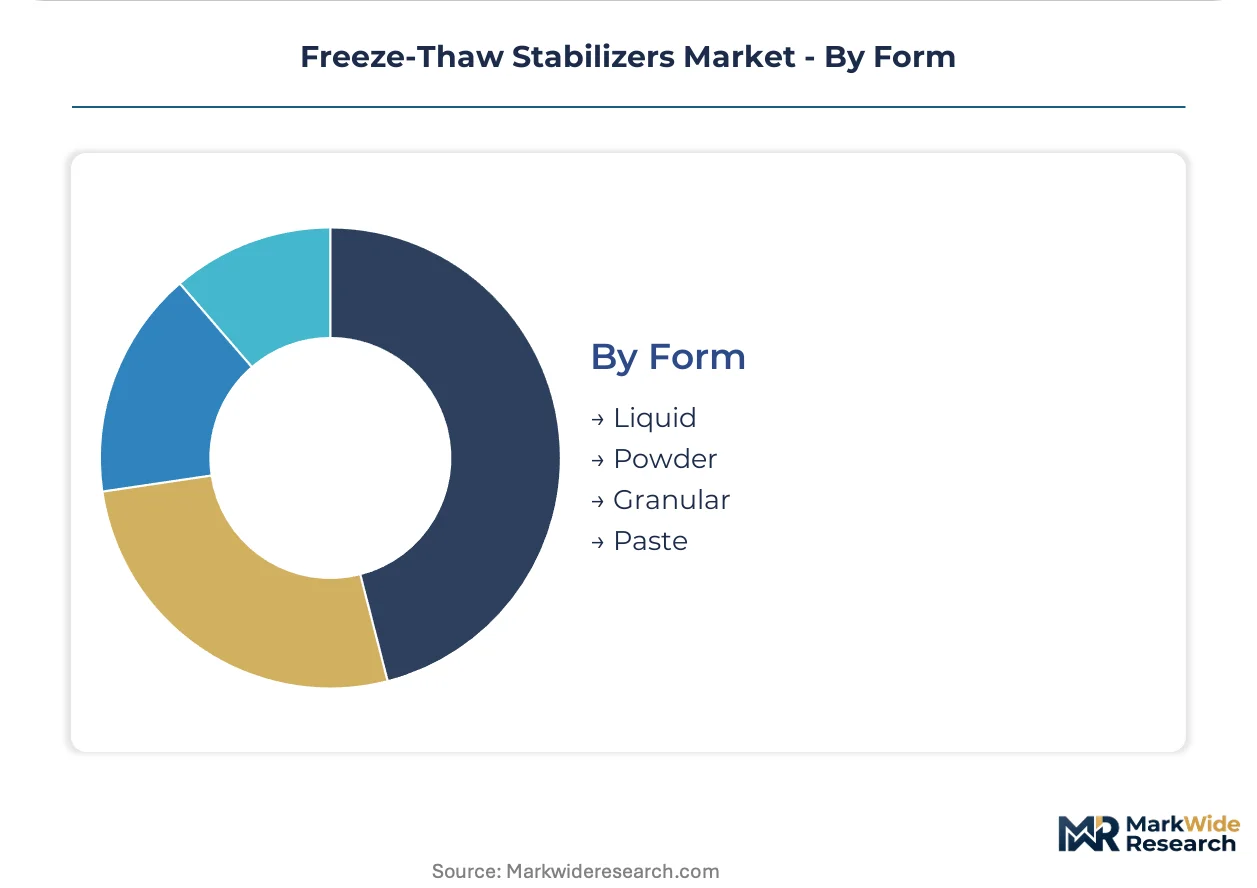
Form selection correlates with production automation level and handling infrastructure investment, creating distinct supplier qualification barriers.
- Powder:Spray-dried and milled stabilizer powders sustain the largest volume share given handling efficiency in industrial batch processing and established dust-control infrastructure.
- Liquid:Concentrated suspensions and solutions are gaining traction in automated inline dosing systems at beverage production facilities, requiring pumpable rheology and microbiological stability.
- Granular:Agglomerated forms reduce dusting and improve dispersibility for mid-scale processors without full liquid handling capability.
- Paste:High-solids stabilizer pastes serve niche applications requiring precise dosing without powder handling equipment.
Powder leads volumes today; Liquid is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized formulation chemists concentrate in German industrial clusters, anchoring European freeze-thaw stabilizer innovation and procurement intelligence.
Germany
Industrial dairy and bakery processors around Munich and Hamburg sustain specialized stabilizer supply chains with just-in-time logistics integration. REACH authorization protocols for emulsifier feedstocks extend validation timelines for new entrants. Bavaria's clean-label R&D facilities are tripling fermentation-derived hydrocolloid adoption rates compared to mass-market processors elsewhere.
United States
Frozen dessert manufacturers are converting beverage production lines to automated inline dosing systems for liquid concentrate stabilizers. FDA Food Safety Modernization Act toxicological data requirements compress approval timelines for novel additives. Pacific Northwest cold-chain logistics hubs are anchoring temperature-sensitive ingredient distribution networks for premium plant-based formulations.
France
Artisanal ice cream manufacturers in Rhône-Alpes and Provence-Alpes-Côte d'Azur are adopting bio-based hydrocolloids at three times the rate of industrial processors. EFSA additive re-evaluation programs advantage established hydrocolloid dossiers over novel chemistries. Île-de-France procurement centralization is compressing supplier negotiation cycles for private-label frozen dessert manufacturers.
Italy
Premium gelato producers in Lombardy and Emilia-Romagna are driving fermentation-derived stabilizer demand for certified-organic ingredient tiers. EU Green Deal sustainability-linked procurement criteria favor bio-based hydrocolloids with verified carbon documentation. Piedmont industrial dairy clusters are embedding technical service teams directly into formulation development workflows.
India
FSSAI-aligned frozen food distribution infrastructure expansion is creating first-mover positioning for stabilizer suppliers with temperature-sensitive logistics capabilities. Central food safety regulator purity benchmarks for imported additives extend certification timelines for multinational entrants. Maharashtra and Gujarat cold-chain development corridors are concentrating procurement demand from emerging quick-service restaurant chains.
Freeze-Thaw Stabilizers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply relationships. The vendor base organizes around analytical certification infrastructure, cold-chain logistics expertise, and hydrocolloid manufacturing scale. Three archetypes dominate: life-science conglomerates with additive purity validation capabilities, specialized temperature-control equipment providers with distribution extensions, and regional filtration and processing technology fabricators. Capacity expansion and strategic technical partnerships represent the dominant competitive moves as procurement centralization compresses distributor margins.
Among life-science conglomerates, Thermo Fisher Scientific occupies a position exemplifying analytical certification infrastructure for export compliance validation. BioLife Solutions anchors the specialized cold-chain logistics archetype that extends into stabilizer distribution for temperature-sensitive ingredients. HOF Sonderanlagenbau GmbH represents German precision engineering capabilities in customized processing equipment that supports stabilizer manufacturing workflows.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Sartorius |
| BioLife Solutions |
| GE Healthcare |
| Cytiva |
| Meissner Filtration Products |
| HOF Sonderanlagenbau GmbH |
| Helmer Scientific |
| Single Use Support GmbH |
| Others |
Value Network & Pricing Analysis
Locust bean gum futures on Mediterranean commodity exchanges cascade through hydrocolloid pricing tiers, compressing margins for standard-grade stabilizers while fermentation-derived alternatives command certified-organic premiums in German and French procurement channels.
Pricing Analysis
Bundled technical service versus unbundled commodity supply splits buyer archetypes into distinct pricing strata. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and embedded formulation support. Cost compression in economy hydrocolloids intensifies because modified starches capture texture-tolerant applications. Beverage producers adopting liquid concentrate systems show least price sensitivity; mass-market frozen dessert manufacturers centralizing procurement at German headquarters exhibit highest sensitivity to per-kilogram differentials.
Supply Chain Analysis
REACH purity certification and FSSC 22000 food safety audits gate supplier qualification, extending onboarding timelines for new entrants. Hydrocolloid raw material extraction concentrates in Spain, Morocco, and India; emulsifier glycerol feedstocks draw from Southeast Asian palm oil derivatives and European rapeseed processing. Single-source vulnerability runs through Mediterranean locust bean harvesting regions exposed to climate-induced yield volatility. Distribution runs through just-in-time logistics hubs anchored at Munich and Hamburg industrial dairy clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The freeze-thaw stabilizers market compounds steadily as clean-label regulatory deadlines across EFSA and FDA jurisdictions force systematic reformulation of frozen food matrices.
For Market Incumbents: Hedge locust bean gum cost exposure through dual-sourcing strategies in Moroccan and Indian harvesting regions. Deepen backward integration into fermentation-derived hydrocolloid production to offset petrochemical-derived stabilizer displacement. Fortify analytical certification infrastructure against tightening REACH purity benchmarks for emulsifier feedstocks. For New Entrants and Emerging Players: The premium-economy price-point gap in Indian cold-chain infrastructure creates white-space positioning for temperature-sensitive logistics specialists. Target Maharashtra and Gujarat frozen food distribution corridors with FSSAI-aligned certification packages. Pursue automated inline dosing compatibility for liquid concentrate formulations as beverage producers convert from powder handling systems. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized cold-chain logistics providers extending into stabilizer distribution for temperature-sensitive ingredients. Five-to-ten year viability favors acquisition targets with embedded technical service teams and established EFSA dossiers. Monitor Codex Alimentarius harmonization negotiations as inflection indicator for supplier landscape consolidation versus regional formulation specialization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation-Derived Hydrocolloids | Bio-based alternatives displace petrochemical stabilizers in EFSA-regulated clean-label formulations. |
| Automated Inline Dosing System Certification | Liquid concentrate compatibility opens beverage production channels converting from powder handling. |
| REACH Purity Benchmark Compliance Investment | Analytical certification infrastructure validates emulsifier feedstocks for EU export market access. |
| Temperature-Sensitive Logistics Capability Expansion | Cold-chain expertise captures first-mover positioning in FSSAI-aligned Indian frozen food distribution. |
| Embedded Technical Service Team Deployment | Formulation support integration defends relationships against procurement centralization at German headquarters. |
Research Methodology
Bottom-up food manufacturer demand modeling reconciled against top-down hydrocolloid and emulsifier supply tracking forms the analytical core. Primary interviews with formulation chemists, procurement leads at industrial dairy processors, distribution channel partners, and regulatory affairs specialists combine with secondary validation from EFSA additive re-evaluation dossiers, FDA Food Safety Modernization Act guidance documents, FSSAI purity benchmarks, and customs trade data for locust bean gum and guar imports. Triangulation across these sources anchors volume and value estimates.
Historical price trendline analysis for Mediterranean locust bean gum and Southeast Asian glycerol feedstocks informs projection frameworks across the analysis window. Segmentation dimensions modeled include product chemistry tier, application matrix complexity, end-user technical service intensity, and form factor automation compatibility. CAGRs derive from regression analysis against regulatory deadline proximity and clean-label adoption velocity in premium frozen dessert formulations.
Caveats apply where EFSA additive re-evaluation outcomes or FSSC 22000 auditor capacity constraints could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization progress and cold-chain infrastructure buildout rates. A model refresh is warranted upon material change in Codex Alimentarius purity standard negotiations or locust bean harvest yield volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
North America Perms and Relaxants Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Spiroglycol Market
Specialty Chemicals
Dimethyl Succinyl Succinate Market
Specialty Chemicals
Glutathione Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Mequinol Market
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
Lactic Acid Blend Market
Specialty Chemicals
Sizing and Thickening Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
UK Insect Repellent Market