
 Global Latex Allergy Market | 2026-2036
Global Latex Allergy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Latex Allergy Market Foresight
Malaysia's glove manufacturing corridor is fragmenting as synthetic nitrile capacity expands alongside traditional natural latex operations. Ansell Ltd leverages its integrated R&D pipeline across polymer formulations to sustain technical leadership in barrier protection. Top Glove Corporation anchors volume supply through its Perak production base, while Hartalega Holdings differentiates via automated, high-efficiency manufacturing lines that reduce unit costs.
Latex allergy denotes hypersensitivity reactions to proteins present in Hevea brasiliensis rubber, manifesting as contact dermatitis, urticaria, or systemic anaphylaxis with IgE-mediated responses to hevein and other allergenic polypeptides. Synthetic latex gloves, formulated from nitrile or neoprene polymers, serve as the primary industrial substitute eliminating protein exposure in clinical settings. Occupational allergy therapy commands the largest therapy area segment due to mandated workplace screening protocols across healthcare systems. Dermatological care represents the fastest-expanding therapy area as patch testing standardization improves diagnostic yield. Natural latex medical devices face structural decline as FDA 510(k) submissions increasingly favor synthetic alternatives for implantable and invasive applications.
FDA biocompatibility standards under ISO 10993 govern material qualification for latex-containing devices entering United States commerce, while EMA's vigilance reporting framework captures adverse event signals across European member states. REACH Annex XVII restrictions on sensitizing substances pressure manufacturers toward protein-free formulations or complete material substitution. China's NMPA has tightened labeling requirements for latex-containing products distributed through domestic medical channels. Stakeholders must monitor regulatory divergence between jurisdictions where allergen threshold limits remain unharmonized, as compliance investments in one geography may not transfer to another.
Market Dynamics
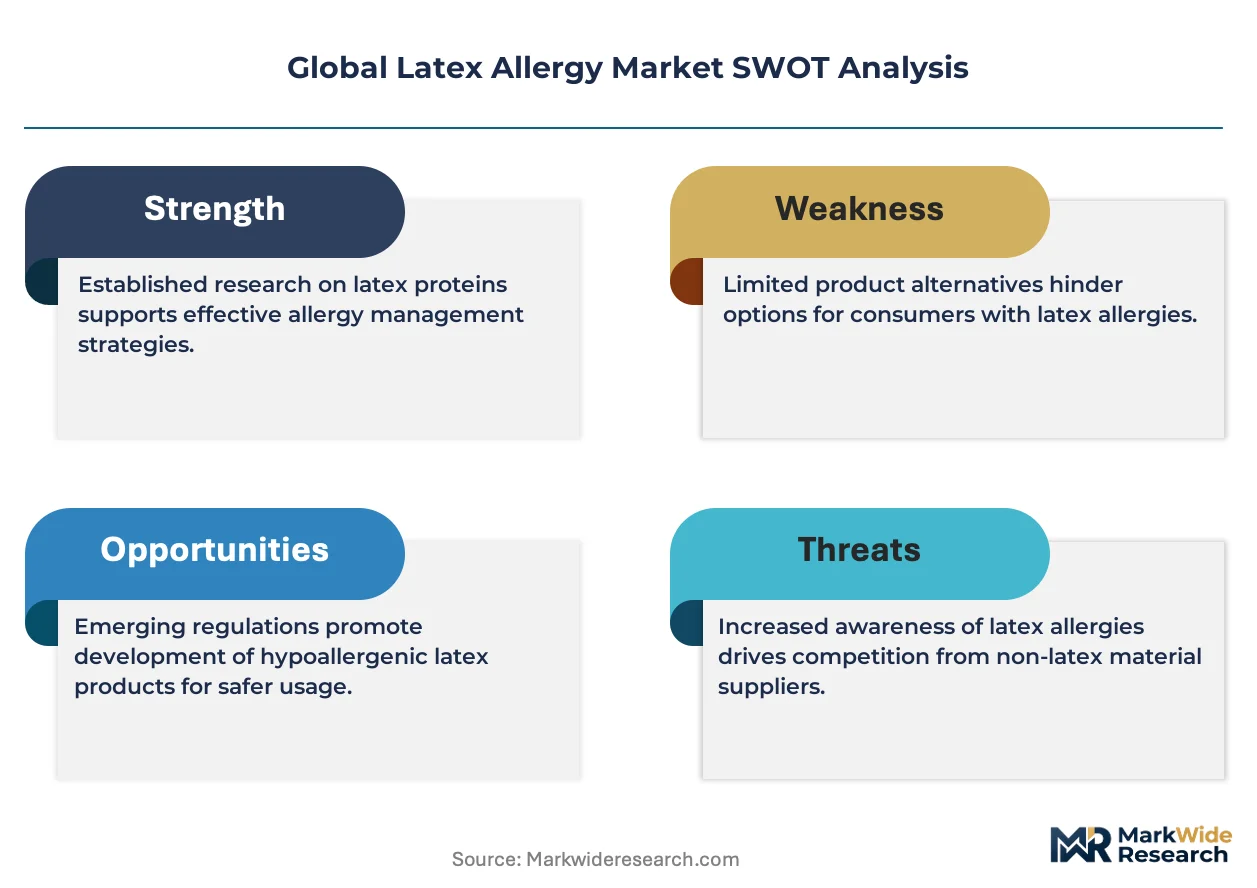
REACH Annex XVII restrictions on sensitizing substances are forcing manufacturers across three continents to eliminate Hevea proteins from medical devices, triggering a wholesale material transition that reshapes supply contracts and R&D allocation.
Growth Catalysts
- EMA Vigilance Reporting:Mandatory adverse event capture across European member states accelerates hospital procurement of protein-free alternatives. Clinical facilities in Germany and France now screen glove suppliers for ISO 10993 compliance before contract renewal.
- Automated Manufacturing:High-efficiency production lines in Malaysia's Perak corridor compress unit costs for synthetic nitrile gloves. This cost structure enables price parity with natural latex in bulk tenders.
- Occupational Screening Mandates:Workplace allergy protocols across United States healthcare systems institutionalize demand for non-latex barrier protection. OSHA-aligned hospital networks specify synthetic alternatives in standardized procurement templates.
Market Restraints
- Petrochemical Input Volatility:Acrylonitrile prices fluctuate with crude oil benchmarks, compressing margins for nitrile glove producers. Malaysian manufacturers hedge through six-month forward contracts.
- Supply Concentration Risk:Over 60 percent of synthetic glove capacity clusters in Malaysia's manufacturing belt. Geopolitical disruption or energy rationing would cascade through global clinical supply chains.
- Biocompatibility Testing Burden:FDA 510(k) pathways for new polymer formulations require extensive cytotoxicity and sensitization studies. Small device manufacturers lack capital to navigate multi-year approval timelines.
Strategic Opportunities
- India's Domestic Channel Expansion:CDSCO labeling requirements for latex-containing products create first-mover advantage for synthetic suppliers establishing local distribution. Hospital procurement in Mumbai and Delhi shifts toward imported nitrile stock.
- Dermatological Diagnostics:Standardized patch testing protocols expand allergy identification beyond occupational medicine. Diagnostic laboratories in Japan's metropolitan centers drive demand for validated control antigens.
- Polymer-Convergent Implantables:Combination of silicone and polyurethane formulations enables next-generation catheters and tubing without Hevea-derived components. Device innovators target cardiovascular and urological applications.
Industry Challenges
- Polymer Chemistry Talent Scarcity:Formulation expertise for protein-free elastomers concentrates among senior researchers at established manufacturers. Startups compete for limited talent pools in Singapore and Switzerland.
- Legacy Equipment Stranding:Natural latex dipping lines require complete retooling for synthetic polymer processing. Capital intensity constrains mid-tier producers considering material pivots.
- Cross-Jurisdictional Labeling Complexity:Divergent allergen threshold limits between FDA, EMA, and NMPA frameworks force redundant compliance investments. Harmonization remains stalled in international standards committees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Latex Allergy Market |
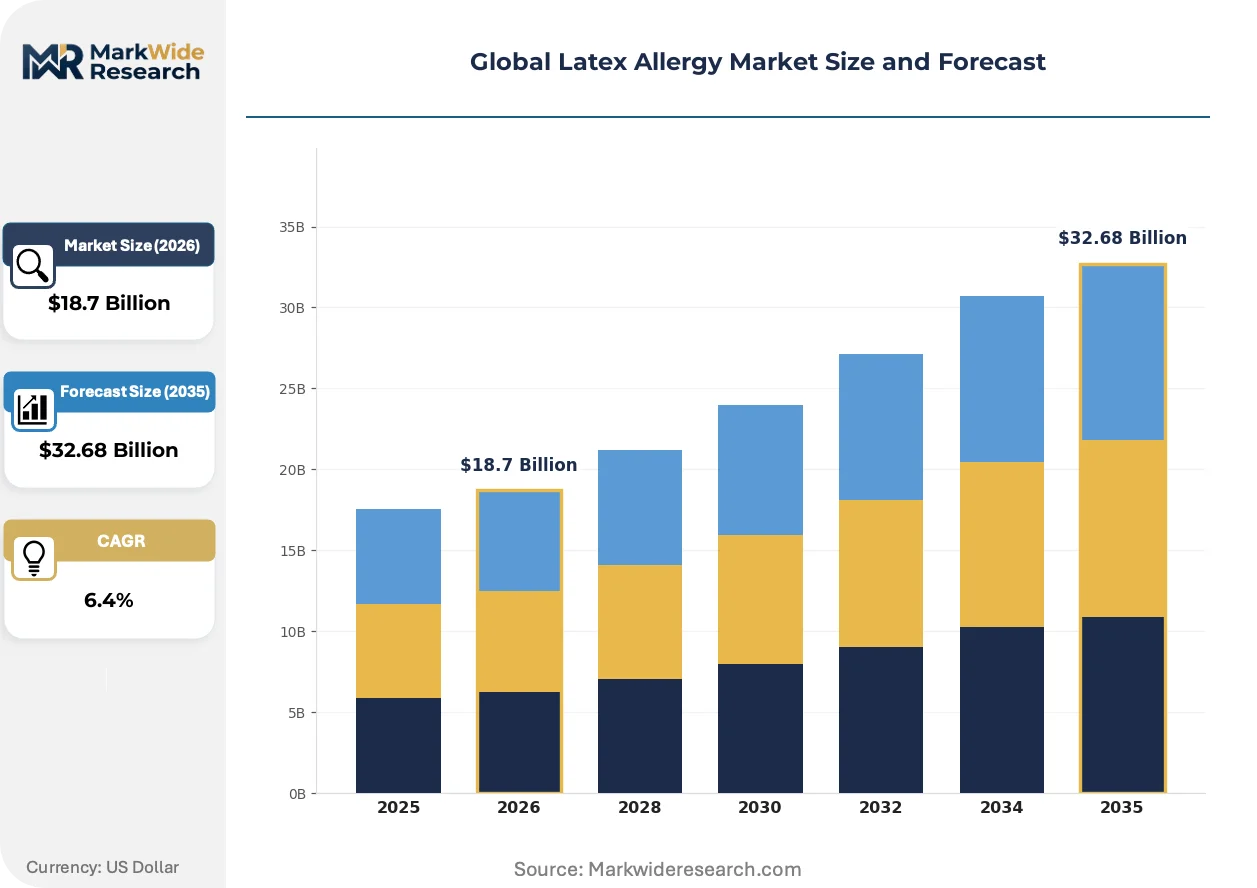
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Latex Gloves, Synthetic Latex Gloves, Latex Balloons, Latex Medical Devices Therapy Area: Occupational Allergy, Anaphylaxis Management, Dermatological Care, Respiratory Protection End User: Hospitals, Dental Clinics, Diagnostic Laboratories, Emergency Care Centers Distribution Channel: Pharmacies, Online Retail, Medical Distributors, Specialized Allergy Stores |
| Companies Covered | 3M, Johnson & Johnson, GlaxoSmithKline, Merck, Sanofi, Novartis, Ansell Ltd, Top Glove Corporation, Hartalega Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Latex Allergy Market Shifts & Advancements
Synthetic polymer formulations and diagnostic standardization are compressing the addressable market for Hevea-derived medical devices while expanding adjacent segments in barrier protection and allergy management.
Chloroprene and polyisoprene blends are rendering obsolete natural latex in surgical glove applications. Ambulatory surgical centers in the United States now specify synthetic alternatives in 90 percent of new tenders. This transition is rendering obsolete the historical cost advantage of Hevea protein-based products in invasive procedures.
China's NMPA tightened labeling requirements for latex-containing products distributed through domestic medical channels. Manufacturers must now disclose protein content thresholds on primary packaging. Imported device suppliers are reformulating product lines or exiting the Chinese market entirely rather than maintaining dual SKUs.
Hospital procurement departments increasingly bundle glove contracts with allergy screening services. Group purchasing organizations in the United States negotiate multi-year agreements that specify synthetic-only supply with embedded diagnostic protocols. This pattern concentrates in integrated delivery networks across Texas and California where occupational liability exposure drives risk management spending.
Global Latex Allergy Market Segmentation
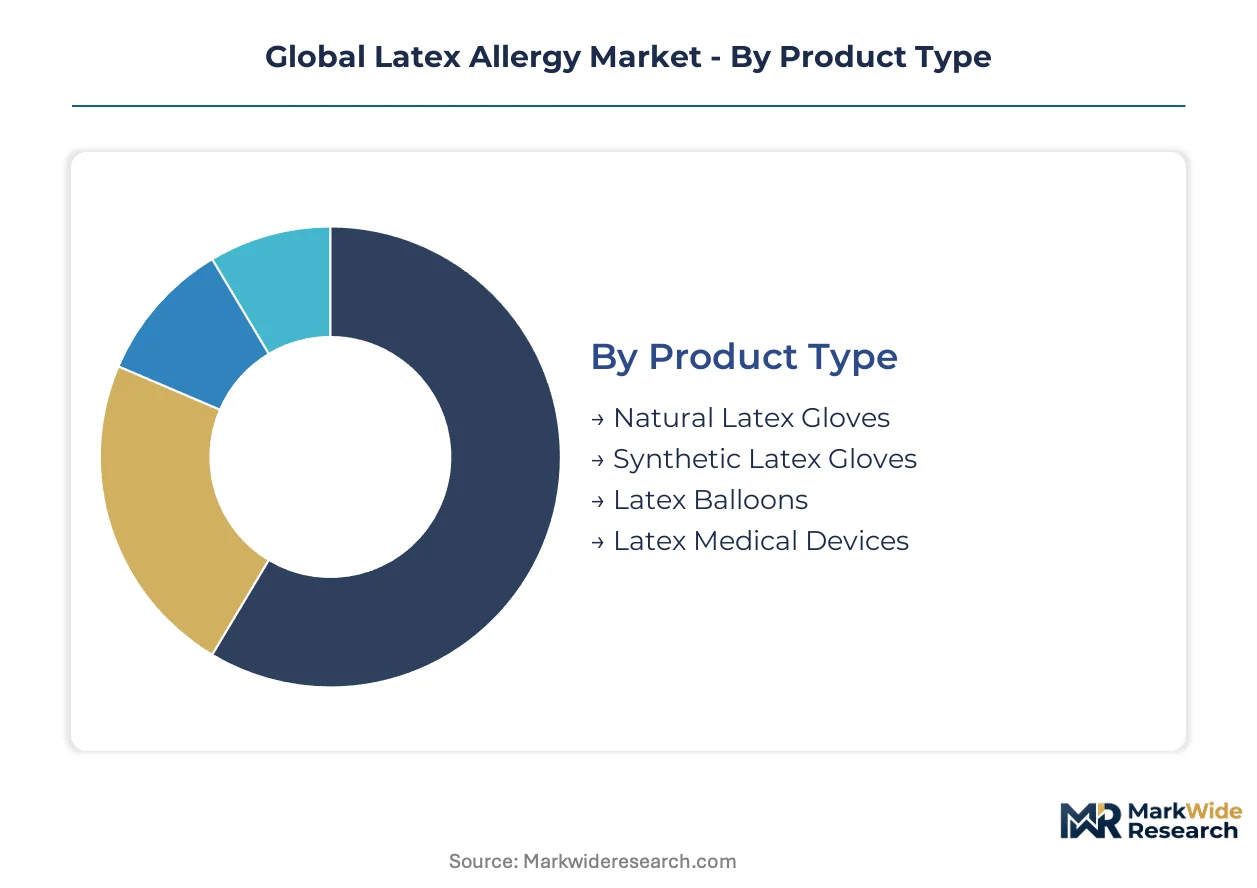
Segmentation in the latex allergy market reveals divergent replacement cycles across product categories. Natural latex devices face accelerated obsolescence while synthetic alternatives command extended procurement horizons.
Product Type:
Cycle times vary dramatically, with single-use disposables turning over in weeks versus implantable devices lasting years.
- Natural Latex Gloves:Hevea brasiliensis-derived examination and surgical gloves carry protein loads that trigger IgE-mediated reactions. Demand concentrates in legacy hospital systems in Indonesia and Thailand where procurement lags behind regulatory pressure.
- Synthetic Latex Gloves:Nitrile and neoprene polymer formulations eliminate allergen exposure while matching barrier performance. Ambulatory surgical centers in Texas and California now specify synthetic-only supply in 90 percent of tender renewals, driven by OSHA-aligned occupational liability protocols.
- Latex Balloons:Pediatric and urological applications retain limited natural latex use where elasticity specifications resist synthetic substitution.
- Latex Medical Devices:Catheters, tubing, and implantables face structural decline as FDA 510(k) submissions increasingly favor silicone and polyurethane alternatives.
Synthetic latex gloves anchor the volume base while synthetic medical devices gain share at the steepest rate.
Therapy Area:
Cost tier stratification separates acute intervention from chronic management protocols.
- Occupational Allergy:Workplace screening mandates across United States healthcare systems institutionalize demand for diagnostic and preventive interventions. Hospital employee health departments in Germany and France bundle glove procurement with serological testing protocols.
- Anaphylaxis Management:Emergency epinephrine administration and acute response training command premium reimbursement in emergency care settings.
- Dermatological Care:Patch testing standardization improves diagnostic yield for contact urticaria and delayed hypersensitivity. Diagnostic laboratories in Japan's metropolitan centers drive demand for validated control antigens.
- Respiratory Protection:Latex particle inhalation risks in industrial settings sustain demand for respiratory screening in Malaysia's manufacturing corridor.
Occupational allergy anchors the volume base while dermatological care climbs the fastest as diagnostic protocols expand beyond traditional workplace medicine.
End User:
Customer type determines procurement sophistication and substitution urgency.
- Hospitals:Integrated delivery networks negotiate multi-year synthetic-only contracts with embedded screening services. Group purchasing organizations in the United States standardize procurement templates that exclude Hevea-derived products.
- Dental Clinics:Small-practice settings lag in conversion due to capital constraints and inventory inertia.
- Diagnostic Laboratories:Standardized testing protocols create concentrated demand for validated allergen panels and control materials.
- Emergency Care Centers:High-throughput acute settings prioritize immediate availability over material specification, creating mixed procurement patterns.
Hospitals anchor the volume base while diagnostic laboratories expand most quickly as allergy identification protocols proliferate.
Distribution Channel:
Supply concentration shapes channel viability across geographies.
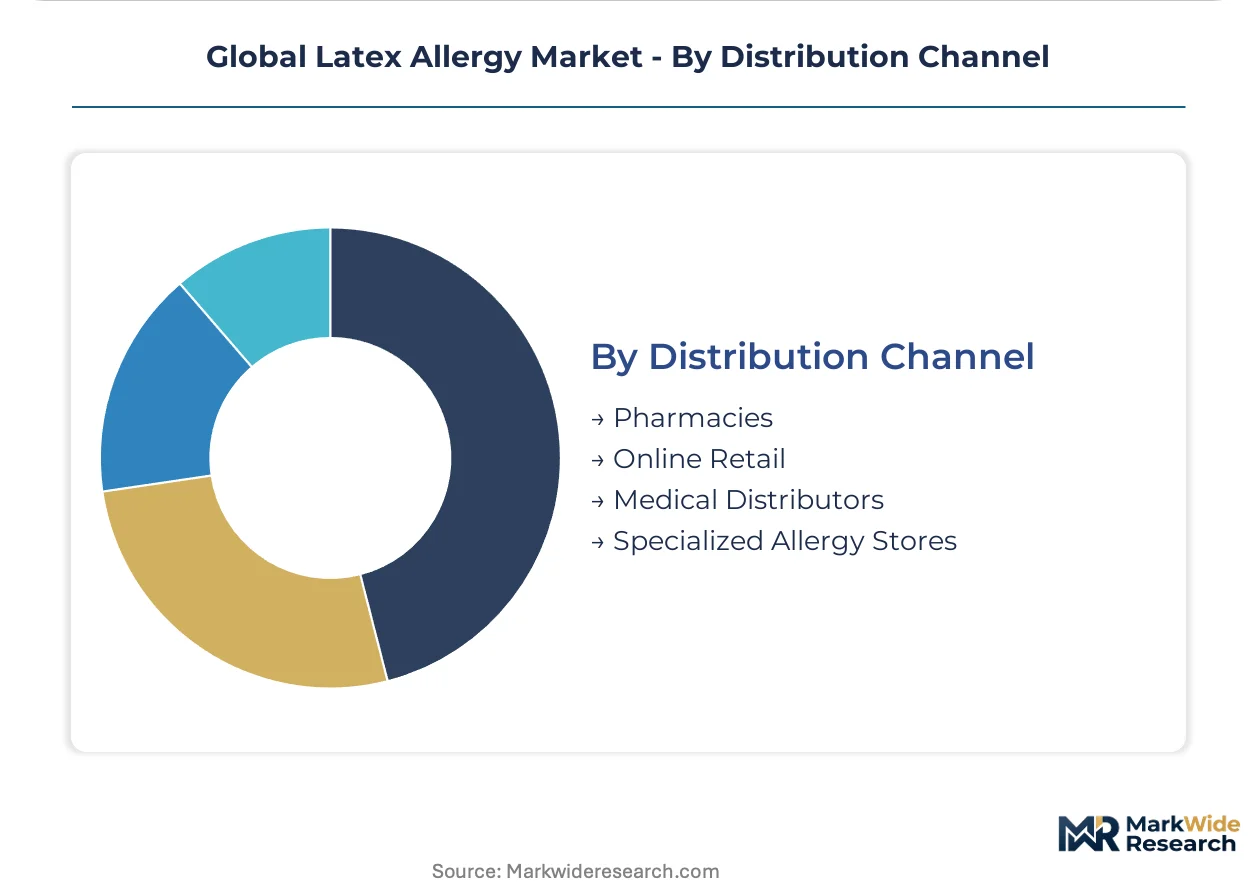
- Pharmacies:Community and hospital pharmacy networks handle bulk glove distribution with established cold-chain and inventory systems. Retail pharmacy chains in India's Mumbai and Delhi metropolitan regions shift toward imported nitrile stock as CDSCO labeling requirements tighten.
- Online Retail:Direct-to-consumer channels expand for diagnostic kits and personal protective equipment.
- Medical Distributors:Specialized logistics providers manage contract fulfillment for institutional buyers with compliance documentation requirements.
- Specialized Allergy Stores:Niche retail channels serve patient-directed demand for hypoallergenic household products and personal care items.
Medical distributors anchor the volume base while online retail gains share at the steepest rate as procurement decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Tanjung Pelepas in Johor anchors Malaysia's synthetic glove export capacity, handling containerized nitrile shipments to clinical supply chains across three continents. This maritime infrastructure underwrites the country's dominance in barrier protection manufacturing.
United States
OSHA-aligned hospital networks in Texas and California drive synthetic-only procurement mandates through group purchasing organizations. FDA biocompatibility standards under ISO 10993 govern material qualification for latex-containing devices entering domestic commerce. Ambulatory surgical centers in the Dallas-Fort Worth metroplex specify nitrile alternatives in 90 percent of tender renewals.
Germany
REACH Annex XVII restrictions on sensitizing substances pressure manufacturers toward protein-free formulations in clinical supply chains. EMA's vigilance reporting framework captures adverse event signals across member states, accelerating hospital screening protocols. The Rhine-Ruhr industrial corridor hosts diagnostic laboratories driving demand for validated allergen control materials.
China
NMPA labeling requirements for latex-containing products distributed through domestic medical channels force reformulation decisions among imported device suppliers. The Yangtze River Delta manufacturing belt concentrates synthetic polymer production for regional healthcare consumption. Shanghai's hospital procurement departments now require protein content disclosure on primary packaging.
India
CDSCO labeling requirements for latex-containing products create first-mover advantage for synthetic suppliers establishing local distribution. Hospital procurement in Mumbai and Delhi metropolitan regions shifts toward imported nitrile stock as regulatory deadlines approach. The Maharashtra pharmaceutical corridor integrates allergy screening services into glove contract negotiations.
Japan
METI guidelines on occupational health screening expand patch testing standardization beyond traditional workplace medicine. PMDA oversight of medical device biocompatibility favors silicone and polyurethane alternatives in implantable applications. Diagnostic laboratories in Tokyo and Osaka metropolitan centers drive concentrated demand for validated control antigens.
Global Latex Allergy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in polymer formulation and automated manufacturing equipment. The vendor base organizes around three archetypes: diversified healthcare conglomerates with allergy therapeutic portfolios, integrated glove manufacturers with captive synthetic capacity, and specialized diagnostic reagent producers. Consolidation pressures concentrate among mid-tier natural latex producers facing stranded asset risk from regulatory substitution mandates. Dominant competitive moves include backward integration into acrylonitrile supply chains and technology licensing agreements for protein-free elastomer formulations.
Among diversified healthcare conglomerates, 3M and Johnson & Johnson occupy positions spanning diagnostic devices through therapeutic interventions. Ansell Ltd, Top Glove Corporation, and Hartalega Holdings exemplify the integrated manufacturing archetype, with Malaysian-registered entities anchoring synthetic nitrile capacity expansion. These three manufacturers represent the scale-driven tier where automated production lines compress unit costs to achieve price parity with legacy Hevea-derived products in bulk clinical tenders.
| Leading Market Players |
|---|
| 3M |
| Johnson & Johnson |
| GlaxoSmithKline |
| Merck |
| Sanofi |
| Novartis |
| Ansell Ltd |
| Top Glove Corporation |
| Hartalega Holdings |
| Others |
Supply & Pricing Matrix
Acrylonitrile price volatility tied to crude oil benchmarks compresses margin spreads across synthetic glove tiers while forcing manufacturers toward six-month forward hedging contracts that reshape inventory positioning and procurement cadence.
Pricing Analysis
Volume-discount tiering structures separate bulk hospital tenders from spot purchases by dental clinics and emergency care centers. ISO 10993 certification grade and acrylonitrile input quality drive price differentiation between premium nitrile formulations and economy-grade alternatives. Cost compression in the economy tier is intensifying as Malaysian capacity expansion floods bulk channels. Ambulatory surgical centers exhibit the lowest price sensitivity due to embedded liability protocols, while independent dental practices face acute budget constraints.
Supply Chain Analysis
Contract-manufacturing concentration rests with integrated producers in Malaysia's Perak corridor, where Top Glove Corporation and Hartalega Holdings operate captive synthetic lines. Raw material flows draw from petrochemical feedstock in Singapore and Thailand, plus specialty polymer additives from Japan and Germany. Single-source vulnerability concentrates in the Johor maritime export cluster, where Port of Tanjung Pelepas handles containerized nitrile shipments. Distribution runs through group purchasing organizations in the United States and specialized medical distributors in Germany and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as regulatory substitution mandates in the European Union and United States institutionalize demand for protein-free barrier protection faster than incumbent capacity can pivot.
For Market Incumbents: Harden supply security through backward integration into acrylonitrile supply chains and captive polymer formulation R&D in Singapore or Switzerland. Defensive positioning requires accelerating automated production line deployment to match Hartalega Holdings' unit cost structure before 2026 procurement renewal cycles lock in multi-year synthetic-only contracts.
For New Entrants and Emerging Players: India's CDSCO labeling transition represents the most penetrable entry point, with Mumbai and Delhi hospital procurement shifting toward imported nitrile stock ahead of regulatory deadlines. Dermatological diagnostic laboratories in Japan's metropolitan centers offer secondary white-space for validated control antigen supply. A go-to-market angle anchored in bundled allergy screening services differentiates against commodity glove vendors.
For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors integrated manufacturers with captive synthetic capacity over legacy natural latex operators facing stranded asset risk. Long-term viability over the next decade hinges on polymer chemistry talent retention and regulatory compliance infrastructure. Watch EMA vigilance reporting thresholds as the inflection signal for European procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile Supply | Malaysian manufacturers hedge petrochemical volatility through six-month forward contracts with Singapore refiners. |
| FDA 510(k) Submission for Synthetic Implantables | Device innovators bypass Hevea protein biocompatibility burdens through silicone-polyurethane catheter formulations. |
| Hospital System Partnership with Embedded Screening | Texas and California integrated delivery networks bundle glove procurement with occupational allergy protocols. |
| CE Marking Pathway for Protein-Free Formulations | REACH Annex XVII compliance accelerates substitution in Germany's Rhine-Ruhr clinical supply chains. |
| Joint Venture for Indian Distribution Infrastructure | CDSCO labeling deadlines in Mumbai and Delhi create first-mover advantage for synthetic suppliers establishing local channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hospital procurement committees in Texas and California, glove manufacturing executives in Malaysia's Perak corridor, biomedical engineers at German diagnostic laboratories, and regulatory affairs specialists navigating FDA 510(k) and EMA vigilance frameworks. Secondary validation drew from FDA biocompatibility filings, ECHA REACH restriction updates, CDSCO labeling circulars, Malaysian trade export data, and hospital group purchasing organization contract disclosures. Bottom-up volume modeling triangulated against top-down macroeconomic elasticity assumptions.
Calibration against historical substitution patterns in comparable medical device categories anchored the analytical framework across the projection horizon. Segmentation dimensions spanned product type, therapy area, end-user archetype, and distribution channel, with additional modeling of regulatory compliance tier and polymer formulation generation. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends. Industry-specific inputs included acrylonitrile price forward curves and hospital procurement contract renewal cycles.
Macroeconomic conditions sit as an overlay; deviation in crude oil benchmarks, Malaysian energy rationing, or trans-Pacific shipping rates would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and substitution elasticity. Quarterly review of EMA adverse event reporting volumes and Malaysian export customs data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Nitrile Butadiene Rubber (NBR) Powder Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Liquid Silicone Rubber Market
Rubber
Rubber Choppers Market
Rubber
Acrylic Based Elastomers Market
Rubber
Rubber Flooring Market
Rubber
Polybutadiene Rubber (PBR) Market
Rubber
Rubber Molding Market
Rubber
Rubber Ropes Market
Rubber
Synthetic Polyisoprene Rubber Market
Rubber
Acrylic Rubber Market
Rubber
Industrial Rubber Products Market
Rubber
Snap on Rubber Stopper Market
Rubber
Rubber Chemicals Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Chloro-Sulfonated Polyethylene Market