
 Thailand Construction Chemicals Market | 2026-2036
Thailand Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Construction Chemicals Market Insights
Performance-grade specification tiers is bifurcating the Thailand construction chemicals landscape as developers distinguish between commodity-grade and certified polymer-modified systems. Sika AG leverages its localized manufacturing footprint to dominate waterproofing and concrete repair categories across Thai infrastructure corridors. MAPEI S.p.A. competes through specialized tile adhesive and grout formulations tailored to Southeast Asian humidity conditions. BASF SE anchors the high-performance admixture segment with technical service teams embedded in major Bangkok commercial developments.
Construction chemicals encompass formulated additives, binders, and protective compounds engineered to enhance concrete workability, structural durability, and substrate adhesion, typically specified by compressive strength gain rates and chloride permeability coefficients measured in coulombs. These formulations serve to extend building service life, reduce maintenance cycles, and enable architectural designs incompatible with unmodified Portland cement systems. Admixtures command the deepest margin pools among product type segments due to dosage-dependent value engineering and project-specific customization requirements. Water-based technology leads volume consumption in residential and commercial applications, while polymer-based systems capture premium positioning in infrastructure projects demanding extended durability warranties. The application split reveals infrastructure as the fastest-expanding demand channel, driven by mass transit expansion and flood-resilient roadway investments across central Thailand.
Thailand's Department of Public Works and Town & Country Planning enforces building energy codes that mandate moisture management and thermal performance standards, directly stimulating demand for certified sealant and adhesive systems. The Thai Industrial Standards Institute (TISI) governs product certification through TIS standards, creating compliance barriers for uncertified imports and favoring established domestic distribution networks. Contractors and developers must monitor evolving green building criteria from the Thailand Green Building Institute, as these specifications increasingly prescribe low-VOC and recycled-content formulations that reshape procurement qualification requirements.
Market Dynamics
Thailand's enforcement of stricter building energy codes under the Department of Public Works and Town & Country Planning is compressing specification windows for developers, forcing rapid qualification of certified polymer-modified systems over commodity-grade alternatives.
Growth Catalysts
- Transit-oriented construction:Mass transit expansion across the Greater Bangkok metropolitan corridor is generating concentrated demand for high-performance admixtures in elevated rail and station infrastructure.
- TISI certification mandates:The Thai Industrial Standards Institute's product certification requirements are filtering uncertified imports and strengthening domestic distribution networks for compliant sealant systems.
- Polymer-modified waterproofing:Flood-resilient roadway investments across central Thailand are accelerating specification of extended-durability membrane systems in transportation infrastructure.
Market Restraints
- Petrochemical input volatility:Acrylic and epoxy resin prices fluctuate with regional naphtha supply, compressing margin predictability for formulators serving price-sensitive residential contractors.
- Import dependency for specialty polymers:Thailand lacks domestic production of several high-performance polymer modifiers, creating supply concentration risk with Singapore and South Korean suppliers.
- Technical limitation in tropical curing:High humidity and temperature variations during monsoon seasons create inconsistent curing conditions that degrade adhesion performance in unmodified cementitious systems.
Strategic Opportunities
- Eastern Economic Corridor industrial zones:Underpenetrated heavy manufacturing construction in Chonburi and Rayong provinces offers white space for corrosion-resistant coating systems.
- Thailand Green Building Institute criteria:Evolving low-VOC and recycled-content specifications are creating procurement qualification advantages for certified sustainable formulation portfolios.
- Digital specification platforms:Contractor adoption of building information modeling is enabling direct-to-specifier channels that bypass traditional distributor relationships.
Industry Challenges
- Polymer chemistry specialization gap:Formulation chemists with expertise in tropical-climate polymer stabilization remain scarce in Thai technical labor markets.
- TISI certification timeline compression:Extended testing protocols for new admixture formulations delay product launches by 12-18 months against fast-moving project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Construction Chemicals Market |
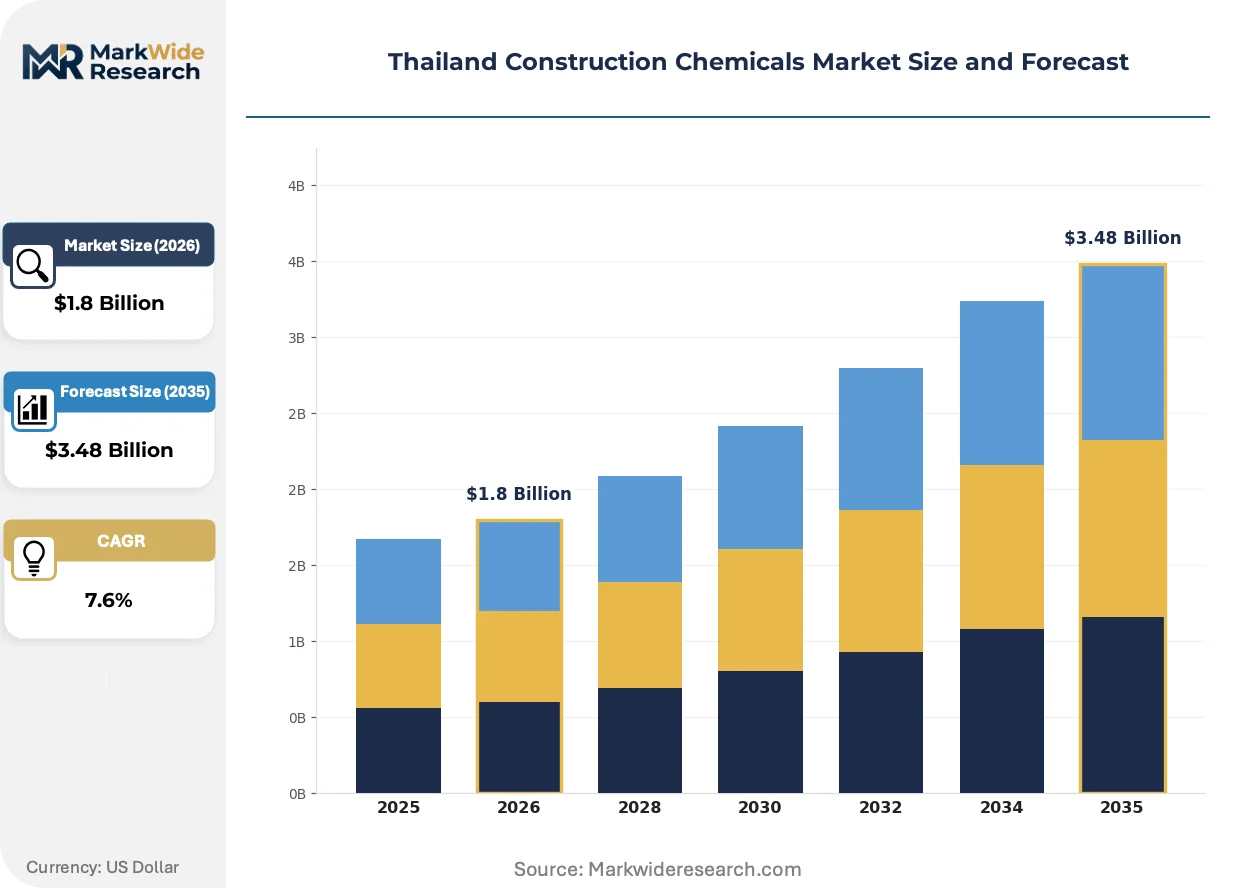
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Adhesives, Grouts Application: Residential, Commercial, Infrastructure, Industrial End User: Contractors, Developers, Architects, Engineers Technology: Water-Based, Solvent-Based, Polymer-Based, Chemical Curatives |
| Companies Covered | Saint-Gobain, Sika AG, MAPEI S.p.A., Fosroc, Inc., TOA Paint (Thailand) Public Company Limited, MBCC Group, Henkel AG & Co. KGaA, BASF SE, RPM International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Construction Chemicals Market Trends and Innovations
Formulation chemistry and procurement protocols are diverging sharply as climate-adaptive specifications and digital distribution reshape how contractors source construction chemicals in Thailand's built environment.
Self-healing concrete admixtures containing encapsulated bacterial spores or microvascular networks are advancing from pilot installations to commercial specification in Bangkok high-rise foundations and marine structures. Infrastructure contractors at Suvarnabhumi Airport expansion and deep-water port projects are embedding these systems to reduce lifecycle maintenance. This technology is bifurcating the repair and rehabilitation segment between conventional epoxy injection and autonomous crack-sealing solutions.
The Department of Public Works and Town & Country Planning's moisture management mandates under revised building energy codes are disqualifying solvent-based sealants from commercial and institutional projects. Contractors must now document thermal performance and vapor transmission rates for all specified membrane systems. Residential developers in Nonthaburi and Pathum Thani provinces are responding fastest, rewriting procurement checklists to exclude non-compliant product categories entirely.
Consolidated developer procurement through centralized technical offices is displacing project-by-project specification decisions previously controlled by site engineers. Major Bangkok-based property groups now mandate pre-approved vendor lists with certified polymer-modified systems locked in for multi-tower developments. This concentration is most visible in the Sukhumvit and Rama IX corridor residential clusters, where repeat-volume agreements override traditional competitive bidding for waterproofing and repair categories.
Thailand Construction Chemicals Market Segmentation
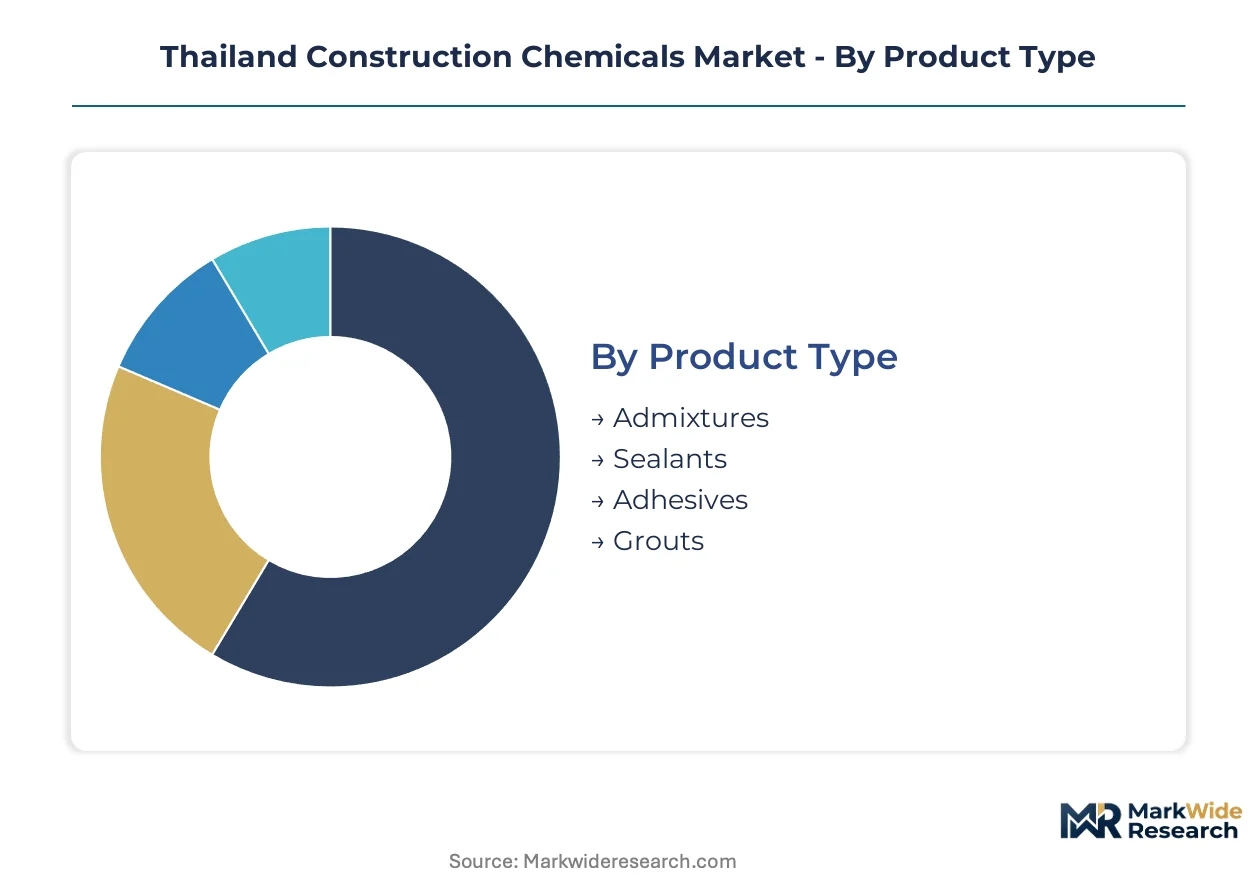
Thailand's construction chemicals market fragments across specification tiers that separate certified polymer-modified systems from commodity-grade alternatives. Each segmentation dimension carries distinct regulatory weight under TISI certification protocols and Department of Public Works energy code enforcement.
Product Type:
The Thai Industrial Standards Institute's certification timelines stretch longest for admixture formulations, compressing launch windows for new entrants against established domestic production.
- Admixtures:Dosage-dependent formulations engineered for compressive strength gain rates and chloride permeability coefficients. Bangkok's high-rise residential towers specify these systems most intensively, driven by foundation engineering requirements for transit-oriented developments along the Sukhumvit corridor. The deepest margin pools in construction chemicals concentrate here due to project-specific customization demands.
- Sealants:Moisture management compounds governed by thermal performance and vapor transmission mandates under revised building energy codes. Commercial and institutional projects across Greater Bangkok now exclude solvent-based alternatives entirely, forcing rapid qualification of water-based and polymer-modified systems.
- Adhesives:Substrate bonding systems spanning tile, flooring, and structural applications with humidity-resistant formulations for tropical conditions.
- Grouts:Cementitious and epoxy-based gap-filling compounds specified for tiling precision and structural crack remediation.
Admixtures handle the majority of throughput; sealants are expanding most quickly on share as energy code enforcement tightens.
Application:
Volume concentration follows infrastructure megaproject corridors, while margin capture diverges toward premium residential specifications.
- Infrastructure:Elevated rail, station construction, and flood-resilient roadway investments across central Thailand. Mass transit expansion through the Greater Bangkok metropolitan corridor generates concentrated demand for high-performance admixtures with extended durability warranties.
- Residential:High-rise developments in Bangkok, Nonthaburi, and Pathum Thani provinces. Developers here respond fastest to green building criteria from the Thailand Green Building Institute, rewriting procurement checklists to mandate certified low-VOC systems.
- Commercial:Office towers and retail complexes subject to strictest Department of Public Works moisture management mandates.
- Industrial:Heavy manufacturing construction in Chonburi and Rayong provinces within the Eastern Economic Corridor.
Infrastructure absorbs the largest project volumes; residential specifications are climbing the fastest on margin contribution.
End User:
Procurement authority is centralizing from site engineers to technical offices, reshaping how each stakeholder category influences specification decisions.
- Contractors:Direct implementation responsibility with growing adoption of building information modeling platforms that enable direct-to-specifier channels bypassing traditional distributors.
- Developers:Major Bangkok property groups now mandate pre-approved vendor lists with certified polymer-modified systems locked across multi-tower developments, concentrating volume through repeat agreements.
- Architects:Design-phase specification authority increasingly constrained by developer-mandated product lists.
- Engineers:Technical validation role for foundation and structural system performance under tropical curing conditions.
Developers control the dominant share of procurement volume; contractors are gaining influence fastest through digital specification platforms.
Technology:
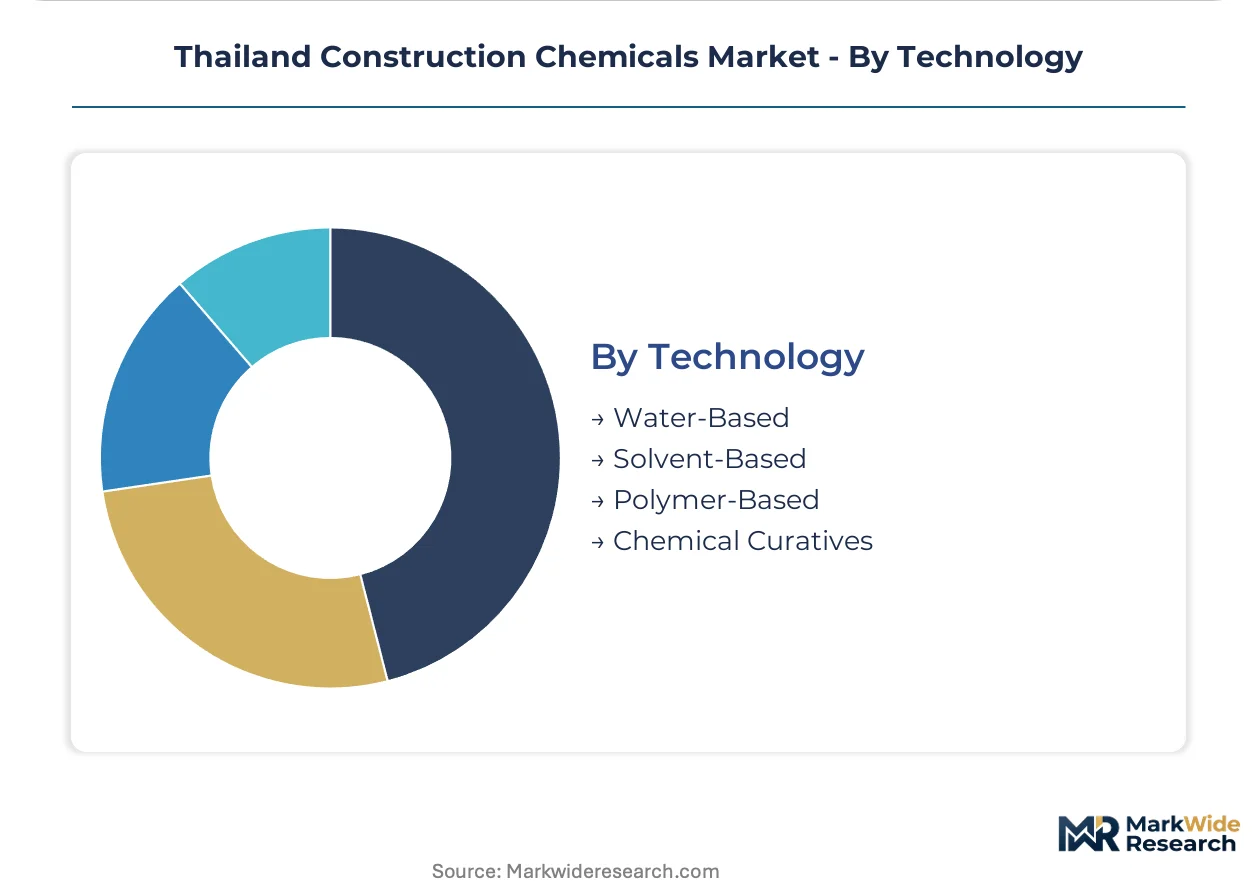
Regulatory disqualification of solvent-based systems is compressing the technology mix toward water-based and polymer alternatives.
- Water-Based:Volume-leading technology for residential and commercial applications with lowest VOC profiles. The Thailand Green Building Institute's evolving criteria directly favor these formulations for procurement qualification advantages.
- Polymer-Based:Premium positioning in infrastructure projects demanding extended durability warranties. Suvarnabhumi Airport expansion and deep-water port contractors specify these systems for reduced lifecycle maintenance.
- Solvent-Based:Disqualified from commercial and institutional projects under Department of Public Works moisture management mandates.
- Chemical Curatives:Specialized hardening and surface treatment compounds for industrial flooring and corrosion protection.
Water-based technology dominates current volume; polymer-based systems are gaining share fastest on infrastructure specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction chemicals demand across Thailand exhibits sharp elasticity contrasts. Residential contractors in peripheral provinces operate on thin margins and prioritize commodity-grade pricing, while Bangkok infrastructure megaprojects specify certified polymer-modified systems with limited price sensitivity.
Greater Bangkok Metropolitan Corridor
Elevated rail expansion and transit-oriented developments drive admixture consumption at scale. The Department of Public Works and Town & Country Planning enforces moisture management mandates that disqualify solvent-based sealants from commercial towers. Contractors along the Sukhumvit and Rama IX corridors now mandate pre-approved vendor lists with locked polymer-modified specifications across multi-tower residential clusters.
Eastern Economic Corridor
Heavy manufacturing construction in Chonburi and Rayong provinces generates underpenetrated demand for corrosion-resistant coating systems. Board of Investment incentives for advanced material production attract formulators seeking proximity to automotive and electronics assembly plants. Industrial zones around Laem Chabang deep-water port specify extended-durability membrane systems for flood-resilient foundations.
Central Plains Flood Zones
Flood-resilient roadway investments accelerate specification of polymer-modified waterproofing across Ayutthaya and Pathum Thani provinces. The Department of Public Works mandates thermal performance documentation for all membrane systems in public infrastructure. Provincial contractors report inconsistent curing conditions during monsoon seasons that degrade adhesion in unmodified cementitious applications.
Northern Urban Centers
Chiang Mai and Chiang Rai commercial developments adopt green building criteria from the Thailand Green Building Institute faster than national averages. Low-VOC procurement checklists now exclude conventional solvent-based alternatives from institutional projects. Local distributors build certified product inventories to capture specification authority from centralized Bangkok technical offices.
Southern Coastal Provinces
Marine infrastructure at Songkhla deep-water port and Phuket airport expansion embed self-healing concrete admixtures for reduced lifecycle maintenance. Salt-laden atmospheric conditions drive premium positioning for polymer-based systems with extended durability warranties. Regional contractors face 12-18 month TISI certification timelines that delay new admixture launches against fast-moving tourism-related construction schedules.
Thailand Construction Chemicals Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Thai construction chemicals market. Swiss and German multinational formulators dominate certified polymer-modified segments through localized manufacturing footprints, while regional commodity suppliers capture price-sensitive residential volume. The competitive structure separates into three archetypes: integrated global specialists with embedded technical service teams, regional distributors with TISI-certified import portfolios, and domestic blenders serving peripheral province contractors. Dominant competitive moves include backward integration into captive polymer modifier supply and repeat-volume agreements with consolidated Bangkok developer groups that override traditional bidding processes.
Among Swiss-anchored specialists, Sika AG exemplifies the integrated archetype with waterproofing and concrete repair positioning across Thai infrastructure corridors. MAPEI S.p.A. represents the Italian formulation tradition with humidity-resistant specialty systems. BASF SE anchors German technical leadership in high-performance admixtures through service teams embedded in major Bangkok commercial developments.
| Leading Market Players |
|---|
| Saint-Gobain |
| Sika AG |
| MAPEI S.p.A. |
| Fosroc, Inc. |
| TOA Paint (Thailand) Public Company Limited |
| MBCC Group |
| Henkel AG & Co. KGaA |
| BASF SE |
| RPM International |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Singaporean and South Korean polymer modifier plants shapes margin floors across Thailand's construction chemicals tiers, concentrating pricing power among formulators with captive supply agreements while compressing commodity-grade producers dependent on spot resin markets.
Pricing Analysis
TISI certification mandates dictate the pricing tier structure across admixture and sealant categories, separating certified polymer-modified systems from uncertified commodity alternatives. Pricing stratifies across certified premium, compliant standard, and uncertified economy tiers, with differentiation anchored in TIS standard compliance and extended durability warranty coverage. Cost compression in residential-grade admixtures intensifies because acrylic resin volatility feeds through to price-sensitive contractors in peripheral provinces. Infrastructure developers along Bangkok's mass transit corridors exhibit lowest price sensitivity, locking in repeat-volume agreements with technical service bundling.
Supply Chain Analysis
Singapore and South Korea anchor specialty polymer modifier production for Thailand's construction chemicals sector, with regional naphtha crackers feeding acrylic and epoxy resin streams. Thai formulators draw from imported high-performance polymer modifiers, cementitious binders from domestic sources, and solvent carriers from regional petrochemical hubs. Single-source vulnerability concentrates in humidity-stabilized polymer grades lacking domestic production alternatives. Distribution runs through TISI-certified import distributors serving Bangkok-based developer technical offices, with project-site delivery coordinated via regional logistics partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with tropical-climate polymer stabilization expertise remain scarce in Thai technical labor markets, constraining product development velocity and compressing launch windows against fast-moving infrastructure procurement schedules.
For Market Incumbents: Secure backward integration into captive acrylic and epoxy modifier supply to insulate margin structures from regional naphtha volatility. Lock repeat-volume agreements with consolidated Bangkok developer groups across multi-tower residential clusters, using embedded technical service teams to displace competitive bidding. Threat substitution from self-healing concrete admixtures demands accelerated R&D investment in autonomous crack-sealing formulations. For New Entrants and Emerging Players: TISI certification fast-tracks through pre-approved testing protocols offer entry pathways into underserved industrial coating segments. White space concentrates in corrosion-resistant systems for Eastern Economic Corridor manufacturing construction, where Board of Investment incentives attract foreign direct investment. Target Chonburi and Rayong province heavy manufacturing zones with humidity-resistant adhesive formulations, leveraging direct-to-specifier digital channels that bypass established distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulators with certified sustainable portfolios aligned to Thailand Green Building Institute low-VOC criteria. Long-term viability hinges on regulatory compliance depth rather than commodity volume scale. Acquisition targets should demonstrate TISI-certified production infrastructure and embedded technical service capabilities. The signal to watch is accelerated specification of recycled-content formulations in public infrastructure procurement guidelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Modifiers | Captive supply of humidity-stabilized resins insulates margins from Singapore-South Korean naphtha volatility. |
| TISI Certification Fast-Track Investment | Compressed 12-18 month testing timelines accelerate product launches against infrastructure procurement schedules. |
| Technical Service Team Embedding | Direct specification influence at Bangkok developer technical offices displaces traditional distributor channels. |
| Sustainable Formulation Portfolio Expansion | Low-VOC and recycled-content systems capture Thailand Green Building Institute procurement advantages. |
| Eastern Economic Corridor Manufacturing Footprint | Proximity to Chonburi-Rayong automotive and electronics assembly plants reduces logistics costs for industrial coatings. |
Research Methodology
Desk research of TISI certification databases, customs import records, and Department of Public Works building energy code documentation preceded structured interviews with formulation R&D directors, procurement leads at Bangkok-based developer groups, distribution channel partners, and infrastructure project contractors. Secondary validation drew from Thai Industrial Standards Institute technical bulletins, Board of Investment incentive disclosures, and Thailand Green Building Institute criteria updates. Bottom-up segment sizing triangulated against top-down construction expenditure flows across the analysis window.
Variance decomposition across product type, application, and technology dimensions informed volume and value projections throughout the forecast period. Modeled segmentation spanned admixture-sealant-adhesive-grout categories, infrastructure-residential-commercial-industrial end-uses, and water-based-polymer-based-solvent-based-chemical curative technologies. CAGRs derived from elasticity-adjusted demand curves responding to regulatory enforcement intensity and megaproject procurement cycles. Industry-specific inputs included TISI certification timeline compression effects and monsoon-season curing condition variability.
Decision-makers should treat outputs as directional under assumptions of sustained Department of Public Works energy code enforcement and continued mass transit expansion commitment; material deviation in regulatory stringency or infrastructure investment pace would warrant model refresh. Specific risk factors include petrochemical input price spikes, extended TISI testing delays, and technical labor market tightening for tropical polymer stabilization expertise. Recalibration cycles align with material shifts in TISI certification protocols and Thailand Green Building Institute criteria revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Stone Veneer Market
Building & Construction Materials
Watertight Doors Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Metal Grating Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market