
 Japan Prefab Wood Building Market | 2026-2036
Japan Prefab Wood Building Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Prefab Wood Building Market Foresight
Japan's domestic timber processing corridor in Hokkaido is reshaping raw material flows for prefabricated construction. Sekisui House leverages integrated supply chains from forest to factory floor. Toyota Housing Corporation anchors its position through precision manufacturing systems borrowed from automotive assembly. Daiwa House Industry competes on modular delivery speed across dense metropolitan zones.
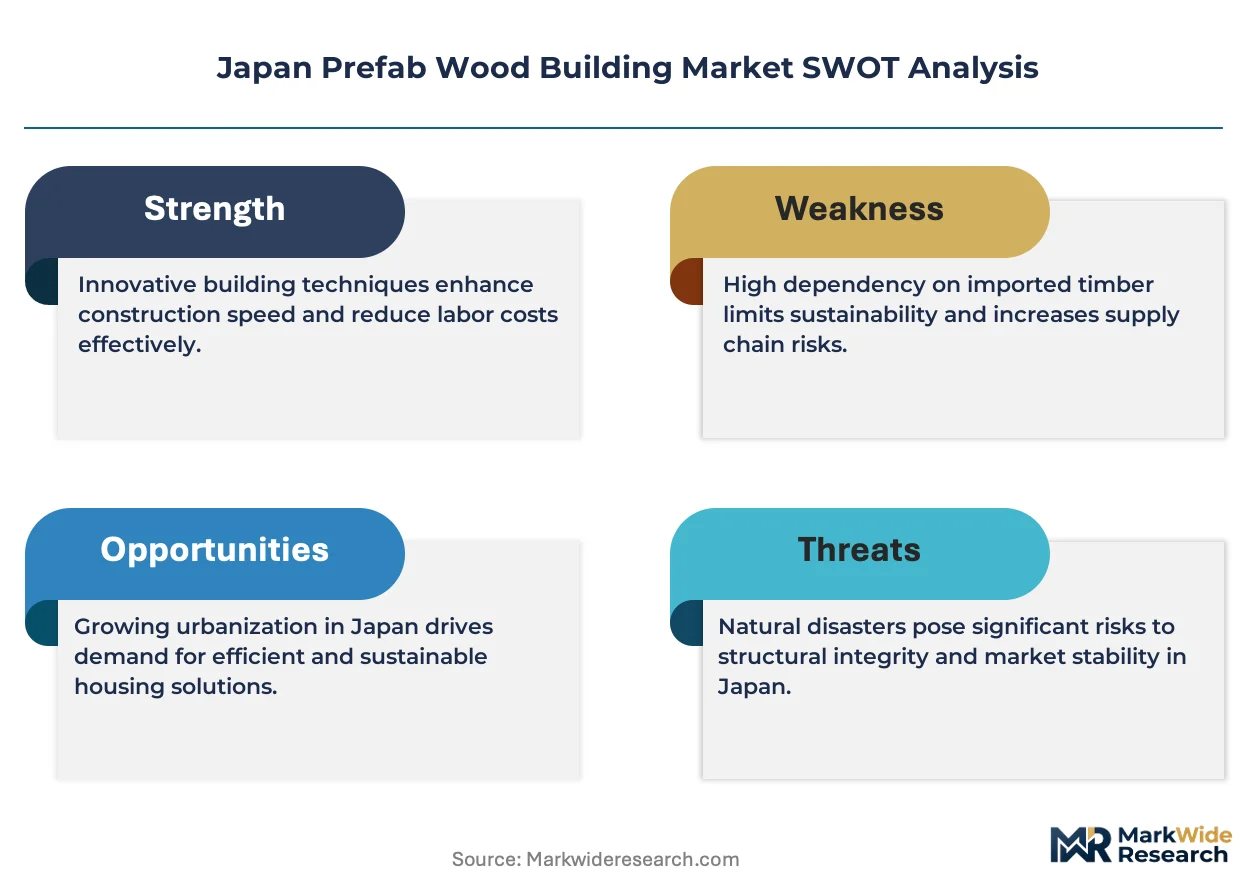
Prefab wood buildings are factory-manufactured structural systems using engineered timber components such as cross-laminated timber panels with specified fire-resistance ratings, assembled on-site to reduce construction duration and labor dependency. Their primary purpose is delivering standardized, high-precision housing and commercial structures with repeatable quality in markets facing skilled labor shortages. Wall panels and cross-laminated timber command the deepest margin pools due to technical complexity and import substitution potential. Floor systems dominate volume in residential applications while roof trusses sustain steady demand from commercial builders seeking span flexibility.
METI enforces building energy efficiency standards that directly elevate demand for high-performance prefab envelopes, while JIS standards govern structural timber grades and connector specifications. The country's national forestry agency promotes domestic cedar and cypress utilization through certified procurement rules that reshape material sourcing patterns. Stakeholders must monitor whether upcoming revisions to the Building Standard Law will tighten seismic performance thresholds for factory-built components.
Market Dynamics
METI's carbon-neutral housing mandates are compressing construction timelines and forcing builders toward factory-based timber systems that can deliver certified performance at scale. This regulatory pressure is redrawing competitive boundaries between traditional site-built methods and precision-manufactured alternatives.
Growth Catalysts
- Building Standard Law revisions:Upcoming seismic performance thresholds for factory-built components are accelerating engineering investment in prefab timber systems.
- Hokkaido timber corridor:Domestic cedar and cypress processing clusters are shortening raw material transit distances to Kanto region factories.
- Single-family residential demand:Urban renewal clusters around Tokyo are absorbing standardized wall panels and floor systems at volumes that justify dedicated production lines.
Market Restraints
- Cross-laminated timber import dependency:Domestic capacity constraints force reliance on European and North American panel suppliers, exposing margins to currency volatility and shipping cost spikes.
- JIS certification timelines:Structural timber grade approvals and connector testing protocols extend product development cycles by 12-18 months.
- Site-built concrete substitution:Conventional reinforced concrete retains cost advantages in mid-rise commercial segments where fire-resistance ratings exceed current prefab wood capabilities.
Strategic Opportunities
- Tohoku reconstruction zones:Post-disaster housing renewal programs in northern prefectures are specifying rapid-assembly timber structures for resilient community rebuilding.
- Modular commercial hospitality:Ryokan and boutique hotel developers are sourcing prefabricated timber guest room modules to compress construction schedules in heritage-sensitive districts.
- METI green building incentives:Carbon-neutral housing certification pathways are creating preference premiums for factory-manufactured envelopes with verified embodied carbon metrics.
Industry Challenges
- Precision assembly workforce:Factory floor technicians with combined timber processing and automated equipment skills command scarcity premiums that inflate labor costs.
- Legacy site-built contractor networks:Established construction relationships resist displacement by factory-direct delivery models that bypass traditional subcontractor hierarchies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Prefab Wood Building Market |
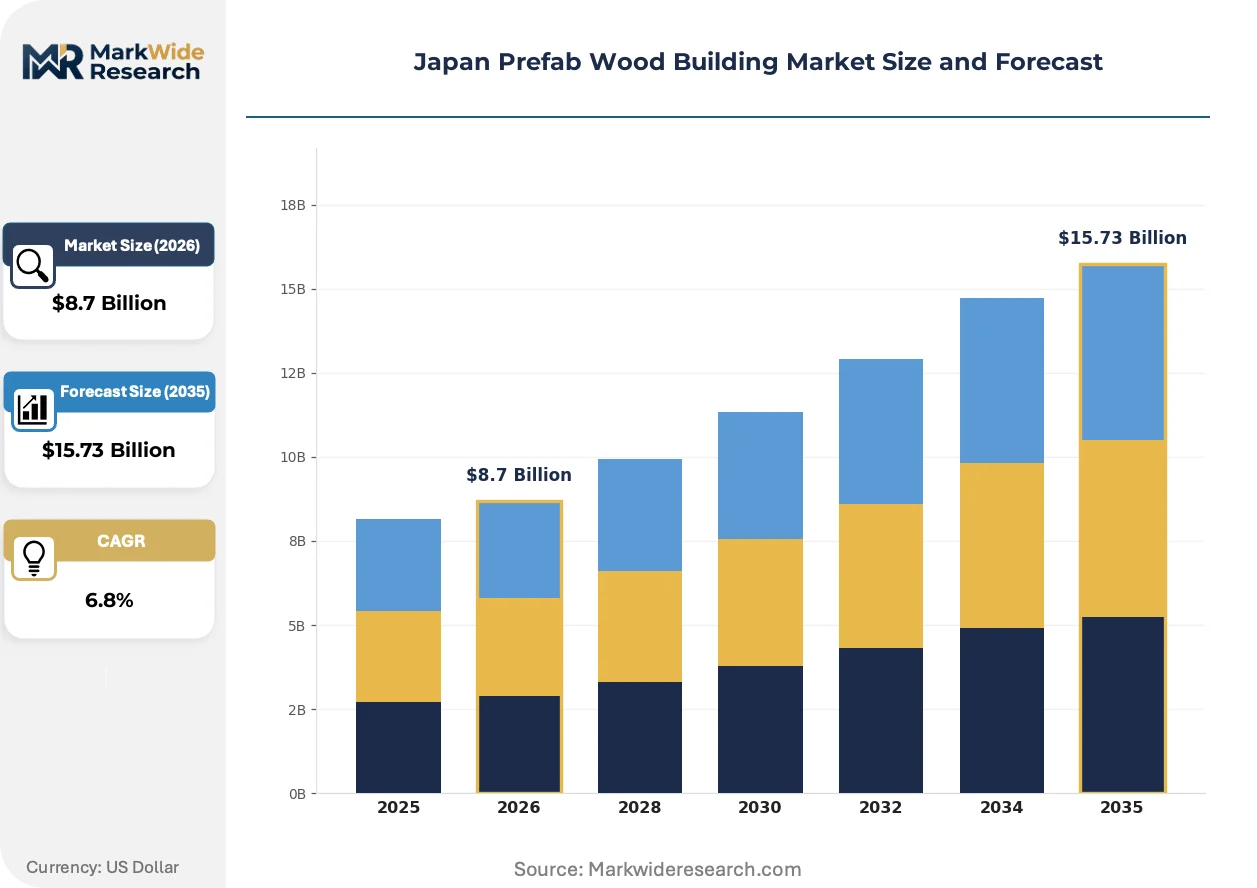
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Panels, Roof Trusses, Floor Systems, Cross-Laminated Timber End User: Residential, Commercial, Educational, Industrial Construction Method: Modular, Panelized, Hybrid, Traditional Material Type: Softwood, Hardwood, Engineered Wood, Others |
| Companies Covered | Sumitomo Forestry, Toyota Housing Corporation, Sekisui House, Misawa Homes, Asahi Kasei Homes, Daiwa House Industry, Hinokiya Group, BESS Wooden Homes, Panasonic Homes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Prefab Wood Building Market Shifts & Advancements
Digital fabrication workflows are collapsing the traditional boundary between architectural design and manufacturing execution. This convergence is enabling mass-customization at throughput rates previously reserved for standardized product lines.
Building information modeling platforms are virtualizing the entire prefab wood construction sequence from forest sourcing to on-site assembly. Japanese housing manufacturers are deploying these systems to compress design-to-delivery cycles for single-family buyers in Greater Tokyo. The technology is virtualizing quality assurance processes that previously required physical prototyping and site-based inspection.
METI's enforcement of building energy efficiency standards is elevating thermal performance requirements for residential envelopes. Factory-manufactured wall panels with integrated insulation and air-sealing layers are capturing preference from site-built alternatives that struggle to achieve comparable blower-door test results. Single-family residential developers in Saitama and Chiba prefectures are restructuring procurement specifications around these certified envelope systems.
Direct contracting between housing manufacturers and end-buyers is displacing traditional general contractor intermediaries in Tokyo's urban renewal zones. Sekisui House and Daiwa House Industry are building captive sales channels that capture margin previously distributed across layered subcontractor networks. This channel compression is most visible in Kanagawa prefecture where factory-direct delivery models now dominate new single-family construction.
Japan Prefab Wood Building Market Segmentation
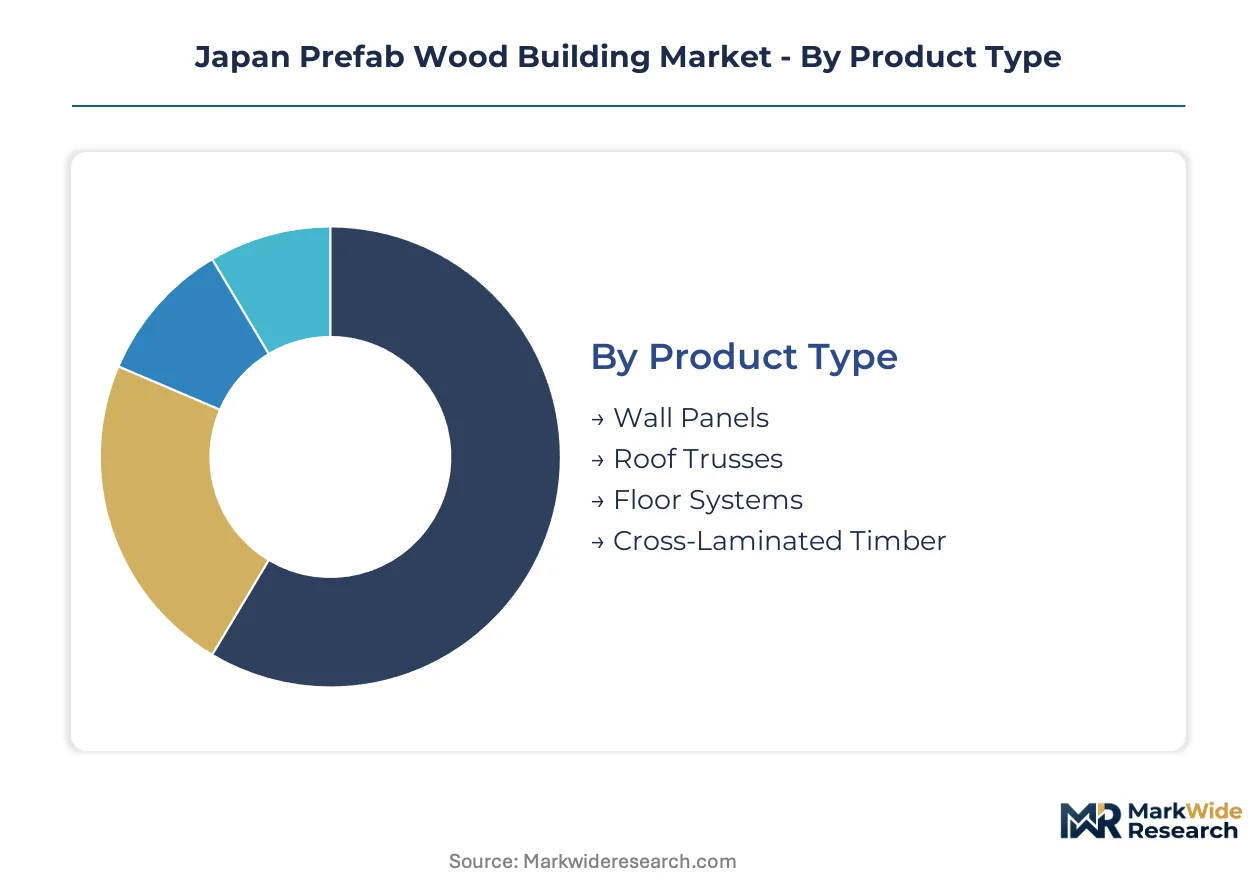
Prefab wood building components exhibit sharply divergent production cycles and inventory velocities. Wall panels turn in weeks while cross-laminated timber sits for months awaiting project-specific engineering sign-off. Understanding these cadence differences is essential for capacity planning and margin protection.
Product Type:
Wall panels rotate through factory floors fastest due to standardized residential specifications, while cross-laminated timber endures the longest production-to-installation intervals.
- Wall Panels:Factory-assembled structural envelopes with integrated insulation and vapor barriers. Demand concentrates in Saitama and Chiba prefectures where single-family developers specify METI-certified thermal performance for blower-door compliance.
- Cross-Laminated Timber:Multi-layer orthogonal timber panels delivering two-hour fire resistance ratings. Project timelines stretch 16-24 weeks as JIS structural grade approvals and seismic connector testing extend engineering cycles.
- Roof Trusses:Prefabricated triangular frameworks for residential and commercial span requirements.
- Floor Systems:Engineered joist and panel assemblies dominating residential volume in Greater Tokyo.
Floor systems anchor the volume base while cross-laminated timber gains share at the steepest rate.
End User:
Residential procurement moves on predictable quarterly cycles aligned with fiscal year housing starts, whereas commercial and educational projects follow irregular capital budget releases.
- Residential:Single-family and multi-family housing absorbing standardized panel systems. Tokyo urban renewal clusters in Kanagawa and Saitama prefectures drive repeat orders with minimal design variation.
- Commercial:Office and retail structures requiring custom fire-resistance engineering. Mid-rise concrete substitution limits penetration where occupancy loads exceed current prefab wood capabilities.
- Educational:Schools and university facilities specifying rapid-assembly timber for seismic resilience.
- Industrial:Warehouse and light manufacturing structures with lower thermal performance requirements.
Residential commands the procurement volume while commercial represents the fastest-climbing application tier.
Construction Method:
Modular systems compress on-site labor to single-day crane placements, whereas hybrid methods stretch timelines by mixing factory and field assembly phases.
- Modular:Three-dimensional volumetric units factory-finished with MEP systems. Ryokan and boutique hotel developers in heritage-sensitive districts specify these for schedule compression.
- Panelized:Two-dimensional wall and floor components requiring on-site joining. Kanto region factories optimize line layouts for this method given its dominance in single-family construction.
- Hybrid:Combinations of modular cores with panelized envelopes for architectural flexibility.
- Traditional:Site-cut timber framing retaining cost advantages in remote prefectures with limited factory access.
Panelized methods hold the installed base while modular approaches expand most quickly in hospitality applications.
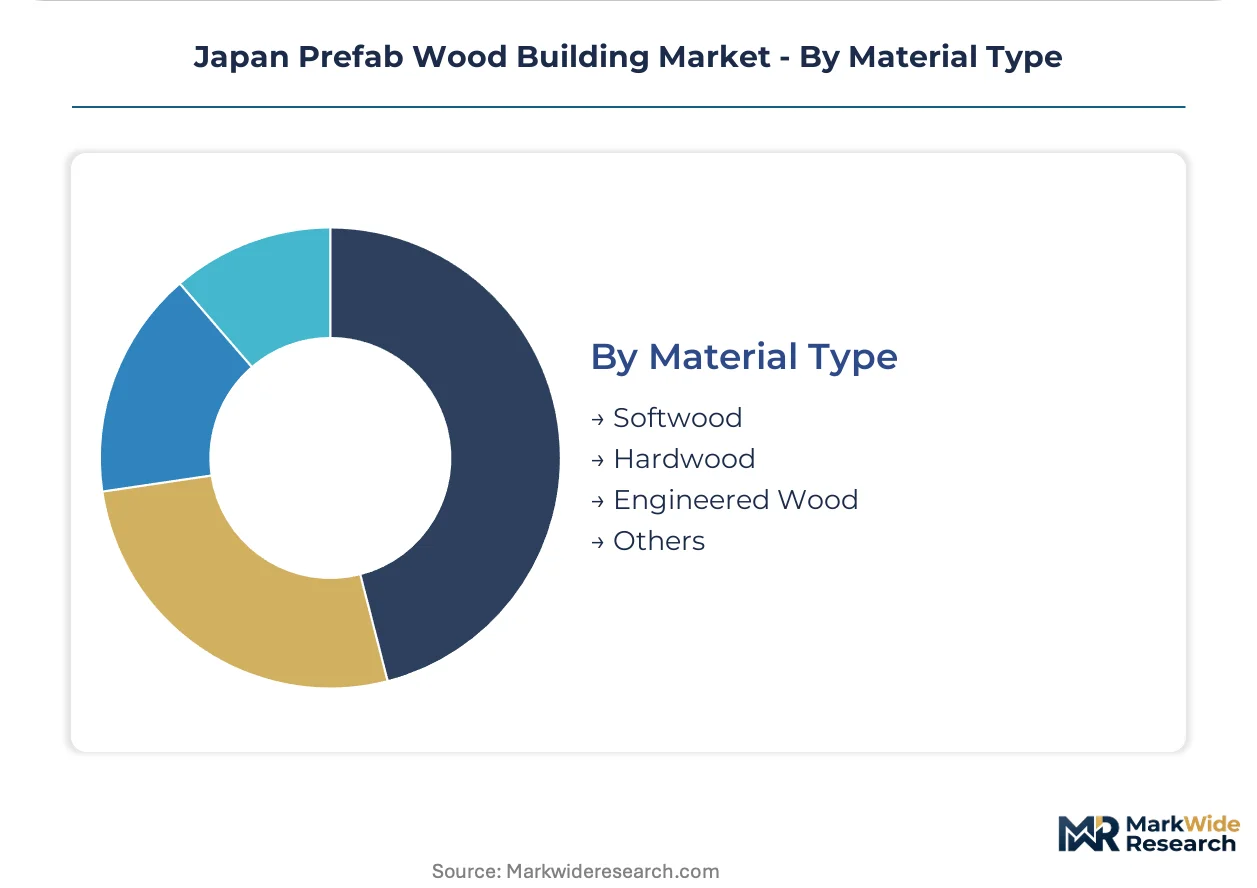
Material Type:
Softwood cycles through domestic Hokkaido processing corridors on monthly rhythms, while engineered wood depends on adhesive supply chains with longer procurement horizons.
- Softwood:Domestic cedar and cypress from national forestry agency certified sources. Hokkaido timber clusters shorten transit distances to Kanto factories, supporting just-in-time panel production.
- Engineered Wood:Laminated veneer lumber and oriented strand board with controlled dimensional stability. METI carbon-neutral housing mandates elevate demand for these materials in certified envelope systems.
- Hardwood:Imported species for premium interior finishes and exposed structural elements.
- Others:Bamboo and composite alternatives with limited current penetration.
Softwood supplies the foundational volume while engineered wood demonstrates the steepest expansion trajectory under tightening energy efficiency standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hokkaido's timber processing clusters feed factory demand across Japan's eastern seaboard, with raw material flows shortening transit distances to Kanto manufacturing zones. Prefabricated wood construction concentrates where urban renewal density justifies dedicated production lines.
Kanto
Tokyo's urban renewal clusters absorb standardized wall panels and floor systems at volumes that justify continuous factory operation. METI's carbon-neutral housing mandates accelerate builder migration toward certified prefab envelopes in Saitama and Chiba prefectures. Yokohama-Kawasaki industrial corridors host precision manufacturing facilities serving Greater Tokyo's single-family residential market.
Kansai
Osaka's commercial hospitality sector sources modular timber guest room modules for ryokan developments in heritage-sensitive districts. JIS structural grade approvals govern connector specifications for seismic performance in Kyoto's educational facility renewals. Sakai industrial zones maintain panelized production capacity for Osaka Bay metropolitan housing starts.
Chubu
Nagoya's automotive supplier networks transfer precision manufacturing expertise into timber component fabrication. The region's machinery builders adapt robotic assembly systems for factory floor panel production. Aichi prefecture factories serve central Japan's hybrid construction method demand.
Hokkaido
Domestic cedar and cypress processing corridors anchor raw material supply for national prefab wood production. National forestry agency certified procurement rules reshape material sourcing patterns toward domestic softwood utilization. Tomakomai and Kushiro timber clusters shorten transit distances to Kanto region factories.
Tohoku
Post-disaster housing renewal programs in Miyagi and Iwate prefectures specify rapid-assembly timber structures for resilient community rebuilding. Prefabricated construction compresses schedules in northern prefectures facing skilled labor shortages. Sendai metropolitan zones absorb modular systems for educational and residential seismic resilience projects.
Japan Prefab Wood Building Market Competitive Landscape
Integrated housing manufacturers and specialized timber fabricators split the market between captive sales channels and subcontractor-dependent delivery. Three strategic archetypes dominate: diversified housing conglomerates with forest-to-factory supply chains, automotive-derived precision manufacturers, and regional timber specialists with domestic material sourcing advantages. Competitive moves concentrate on backward integration into Hokkaido timber corridors and direct-to-buyer channel compression that bypasses traditional general contractor networks.
Among diversified housing conglomerates, Sekisui House and Daiwa House Industry exemplify integrated supply chain operators with captive sales channels in Kanto urban renewal zones. Toyota Housing Corporation represents automotive-derived manufacturing precision applied to timber component fabrication. These three anchors occupy distinct competitive positions: Sekisui House and Daiwa House Industry sit within the factory-direct delivery tier, while Toyota Housing Corporation exemplifies cross-industry manufacturing methodology transfer.
| Leading Market Players |
|---|
| Sumitomo Forestry |
| Toyota Housing Corporation |
| Sekisui House |
| Misawa Homes |
| Asahi Kasei Homes |
| Daiwa House Industry |
| Hinokiya Group |
| BESS Wooden Homes |
| Panasonic Homes |
| Others |
Supply & Pricing Matrix
Cross-laminated timber import dependency determines both pricing tier spreads and supply chain shape in Japan's prefab wood building market. European and North American panel suppliers expose domestic builders to currency volatility and shipping cost spikes that compress margins across standard-grade envelope systems while premium-certified domestic alternatives command scarcity premiums.
Pricing Analysis
METI's building energy efficiency standards dictate the pricing tier structure across Japan's prefab wood building market. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified thermal performance envelopes from baseline JIS-compliant systems and non-certified alternatives. Price differentiation centers on blower-door test certification and seismic connector grade ratings. Pricing pressure stems from European CLT import cost volatility that squeezes mid-tier margins. Single-family residential developers in Saitama and Chiba prefectures demonstrate highest price sensitivity, while ryokan hospitality buyers absorb premiums for heritage-compatible rapid assembly.
Supply Chain Analysis
Sekisui House, Daiwa House Industry, and Toyota Housing Corporation hold captive manufacturing capacity across Japan's prefab wood supply chain. Raw material flows draw from Hokkaido cedar and cypress processing corridors, European CLT mills, and domestic engineered wood adhesive suppliers. Supply chain risk centers on single-source vulnerability for cross-laminated timber panels where domestic capacity constraints force reliance on transoceanic shipments. Distribution runs through factory-direct sales channels that bypass traditional general contractor networks in Kanto urban renewal zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's prefab wood building market enters a cyclical recovery phase driven by METI's carbon-neutral housing mandates compressing construction timelines toward factory-based timber systems. Regulatory enforcement tightens across the analysis window as building standard revisions accelerate.
For Market Incumbents: Build captive Hokkaido timber supply moats through backward integration into national forestry agency certified procurement corridors. Secure JIS structural grade pre-approvals for seismic connector systems ahead of Building Standard Law revisions. Incumbent housing manufacturers must defend against emerging automotive-derived precision manufacturers by controlling wall panel inventory velocity through dedicated Kanto production lines. For New Entrants and Emerging Players: Mid-market commercial hospitality in Kansai heritage-sensitive districts represents the most penetrable entry point for modular timber guest room modules. Tohoku post-disaster reconstruction zones offer secondary white-space for rapid-assembly educational facilities specifying seismic resilience. New entrants should pursue direct contracting relationships with ryokan developers seeking schedule compression without traditional general contractor intermediaries. For Investors and Strategic Acquirers: Upcoming Building Standard Law seismic performance threshold revisions reshape the acquisition landscape toward engineering-capable timber fabricators. Long-term viability favors vertically integrated operators with forest-to-factory supply chain control across the next decade. Investors should monitor JIS certification timeline compression as the signal indicating regulatory inflection favoring domestic panel capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hokkaido Timber Corridors | Captive cedar and cypress supply secures margin protection against import volatility for Kanto manufacturers. |
| JIS Pre-Certification Investment | Accelerated structural grade approvals compress 12-18 month product development cycles ahead of regulatory tightening. |
| Factory-Direct Channel Expansion | Bypassing general contractor networks captures margin previously distributed across layered subcontractor hierarchies in urban renewal zones. |
| Modular Hospitality Partnership | Ryokan developers in Kyoto and Osaka heritage districts source rapid-assembly guest room modules for schedule compression. |
| Seismic Connector R&D Program | Engineering investment addresses upcoming Building Standard Law performance thresholds for factory-built components. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across Japan's prefab wood building ecosystem. Housing manufacturer procurement directors, METI regulatory affairs specialists, Hokkaido timber processing facility managers, and Kanto region general contractors provided operational perspectives. Secondary validation drew from METI building energy efficiency standard filings, JIS structural timber grade certification databases, national forestry agency procurement reports, and customs import data for cross-laminated timber panels. Bottom-up volume modeling triangulated against top-down construction spend forecasts.
Calibration against historical housing starts data and prefabricated construction permit records anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, end user category, construction method, and material sourcing origin. CAGRs derived from regression analysis of quarterly installation volumes against regulatory milestone timing. Industry-specific forecast inputs incorporated METI carbon-neutral housing certification adoption curves and Hokkaido timber corridor capacity expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in yen exchange rates against euro and dollar benchmarks would shift the trajectory for import-dependent CLT pricing tiers. Forecasts reflect assumptions regarding Building Standard Law revision implementation pace and domestic engineered wood adhesive supply stability. Quarterly review of JIS certification backlog indicators and transoceanic shipping rate indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Sawn and Profiled Wood Products Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
Aluminum Board Raised Access Floor Market
Building & Construction Materials
Sawn Timber Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Exterior Wall System Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Basalt Fiber Reinforced Polymer BFRP Market