
 GCC Cement Market | 2026-2036
GCC Cement Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Cement Market Intelligence
Carbon capture integration in clinker kilns is rewriting production economics across the Gulf. Yamama Cement Company leverages its Riyadh proximity to feed Saudi Arabia's gigaproject pipeline with low-carbon product lines. Yanbu Cement Company anchors western Saudi supply chains through Red Sea port access and captive limestone quarries. Saudi Cement sustains market presence via integrated operations spanning raw material extraction to bulk distribution.
GCC cement comprises hydraulic powder manufactured from limestone, clay, and gypsum calcined at 1,450°C, forming calcium silicate compounds that harden through hydration when mixed with water. Ordinary Portland Cement dominates volume but faces margin compression as Blended Cement gains share under stricter emissions protocols. Infrastructure and Residential Construction segments lead end-user offtake, with Road Construction applications absorbing the fastest-growing share of sulfate-resistant and high-early-strength formulations.
Saudi Standards, Metrology and Quality Organization (SASO), UAE's Ministry of Industry and Advanced Technology (MoIAT), and Qatar's General Organization for Standardization (QS) enforce compressive strength, chemical composition, and environmental compliance thresholds that determine market access. These frameworks push producers toward blended and alternative fuel-compatible formulations. Stakeholders must monitor how evolving carbon border mechanisms and local green procurement rules reshape cost structures and competitive ranking across the six Gulf states.
Market Dynamics
Saudi Arabia's gigaproject pipeline is compressing demand cycles and forcing producers to reconfigure capacity deployment around NEOM, Red Sea, and Qiddiya construction schedules rather than traditional seasonal patterns.
Growth Catalysts
- NEOM Infrastructure Mandate:Saudi Arabia's linear city project requires sulfate-resistant and high-early-strength cement grades at volumes that absorb excess regional clinker capacity.
- SASO Building Code Enforcement:The Saudi Standards, Metrology and Quality Organization mandates higher-performance cement specifications that favor blended formulations with lower carbon intensity.
- Red Sea Port Access:Western Saudi cement terminals with captive limestone quarries and deep-water berths are capturing logistics premiums on bulk exports to East African markets.
Market Restraints
- Natural Gas Price Volatility:GCC clinker kilns depend on subsidized natural gas feedstock; any price reform would compress margins on Ordinary Portland Cement production.
- Overcapacity Concentration:Saudi Arabia and the UAE together hold surplus grinding capacity that suppresses regional pricing power during demand troughs.
- Limestone Quality Depletion:Decades of extraction in the Eastern Province are forcing longer haul distances from captive quarries to coastal plants.
Strategic Opportunities
- Carbon Capture Retrofit:Post-combustion capture on Riyadh-area kilns could position Saudi producers for EU carbon border adjustment compliance on future exports.
- Oman Underpenetration:The Sultanate's construction pipeline lacks sufficient local clinker capacity, creating import substitution potential for UAE-based suppliers.
- Alternative Fuel Blending:Refinery waste and municipal solid waste co-processing offers fuel cost arbitrage against natural gas dependence.
Industry Challenges
- Kiln Process Engineering Talent:GCC universities produce insufficient chemical engineers with pyroprocessing expertise to staff carbon capture retrofits.
- Blended Cement Certification Lag:MoIAT and QS approval timelines for new supplementary cementitious material blends stretch 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Cement Market |
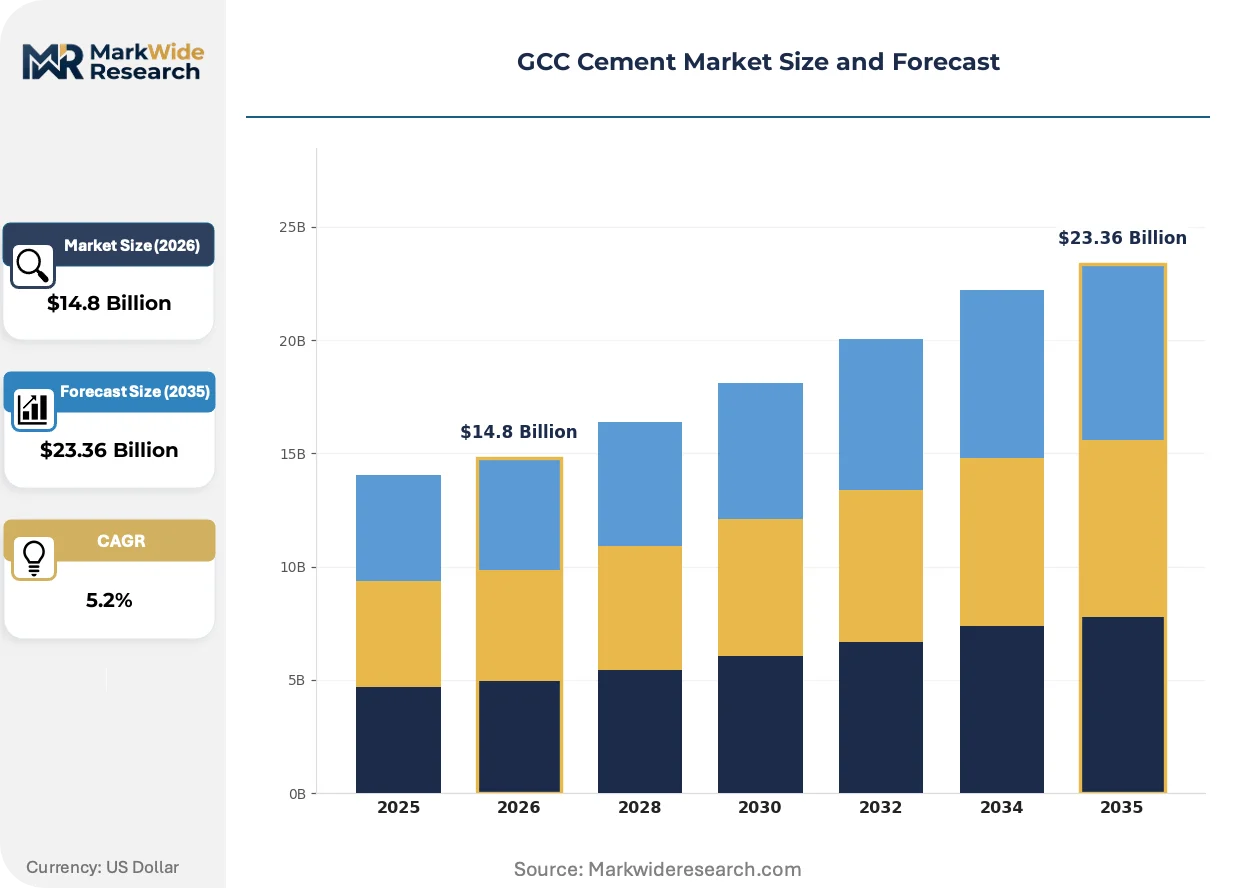
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.36 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ordinary Portland Cement, Blended Cement, White Cement, Sulfate Resisting Cement Distribution Channel: Retail, Direct Sales, Online, Wholesale End User: Residential Construction, Commercial Construction, Infrastructure, Industrial Application: Road Construction, Building Materials, Precast Concrete, Cement-Based Products |
| Companies Covered | Yamama Cement Company, Yanbu Cement Company, Saudi Cement, Dubai Cement, Najran Cement Company, Qatar National Cement Company, Southern Province Cement Company, United Cement Company, Kuwait Cement Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Cement Market Strategic Shifts & Innovations
Clinker factor reduction technologies are rewriting product economics as regulatory pressure on Scope 1 emissions intensifies across Gulf national building codes.
Calcined clay activation is collapsing the performance gap between blended and Ordinary Portland Cement in high-humidity Gulf construction environments. Saudi gigaproject contractors are specifying LC3 (limestone calcined clay cement) formulations for below-grade concrete. The technology is collapsing premium pricing for sulfate-resistant Portland cement in coastal applications.
MoIAT's UAE Green Building Regulations now mandate Environmental Product Declarations for cement procured by federal infrastructure projects. Industrial consequence includes accelerated investment in lifecycle assessment certification by Dubai and Abu Dhabi-based suppliers. Road and marine infrastructure segments are responding fastest, embedding carbon intensity thresholds into tender evaluation matrices.
Buyer concentration around Saudi sovereign wealth fund-backed developers is compressing supplier negotiation cycles from annual frameworks to project-specific bulk procurement. Traditional distributor networks are losing share to direct mill-to-site logistics contracts. The shift is most visible in Tabuk and Neom Bay construction zones where single-source supply agreements now dominate.
GCC Cement Market Segmentation
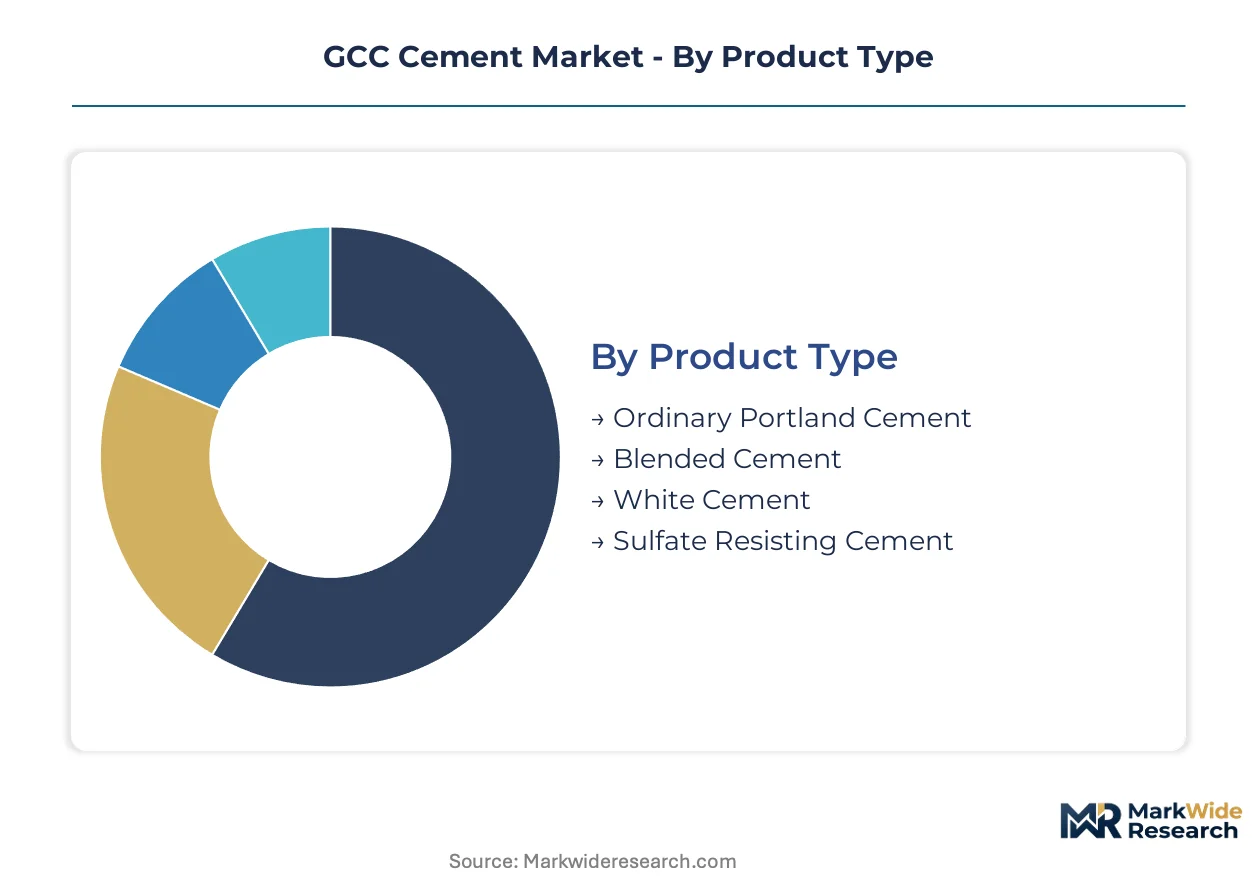
Segmentation in the GCC cement market reveals how procurement cycles, specification intensity, and logistics requirements fragment revenue streams. Understanding these divisions exposes where margin compression concentrates and where premium positioning survives.
Product Type:
Cycle times vary dramatically across formulations, with commodity grades turning inventory weekly while specialty products sit in specification review for months.
- Ordinary Portland Cement:Composed of 95% clinker with 5% gypsum addition, this grade dominates bulk infrastructure procurement. NEOM and Red Sea contractors absorb the majority of Saudi OPC offtake under single-source agreements that bypass traditional distributors.
- Blended Cement:Incorporates fly ash, slag, or calcined clay to reduce clinker content below 65%, cutting embodied carbon. SASO's building code enforcement and UAE MoIAT green procurement rules are accelerating specification shifts in federal projects across Riyadh and Abu Dhabi.
- White Cement:Low-iron clinker formulation demands selective raw material sourcing and specialized kiln firing. Decorative facade applications in Dubai and Doha luxury developments sustain niche premiums despite limited volume.
- Sulfate Resisting Cement:Tricalcium aluminate content below 5% protects against groundwater sulfate attack. Coastal infrastructure in Jeddah and Manama specifies this grade for marine pile foundations and below-grade structures.
Ordinary Portland Cement anchors the volume base while Blended Cement gains share at the steepest rate.
Distribution Channel:
Channel economics diverge sharply on logistics control, with direct contracts capturing margin that retail networks surrender to inventory risk.
- Retail:Bagged cement sales through construction material yards serve fragmented residential contractors. Saudi Arabia's Eastern Province and UAE's northern emirates retain dense retail networks despite gigaproject-driven consolidation elsewhere.
- Direct Sales:Mill-to-site bulk delivery eliminates intermediary handling and enables just-in-time scheduling. NEOM, Qiddiya, and Red Sea developers mandate direct procurement frameworks that compress payment cycles and demand volume commitments.
- Online:Digital platforms aggregate small-lot buyers for price discovery and delivery scheduling. UAE-based procurement startups are gaining traction among fit-out contractors in Dubai's secondary construction market.
- Wholesale:Regional distributors stockpile imported clinker and domestically produced cement for resale to smaller contractors. Oman's construction pipeline relies heavily on UAE wholesale supply given limited local clinker capacity.
Direct Sales commands the largest revenue pool while Online channels expand most quickly.
End User:
Customer concentration varies from sovereign wealth fund-backed developers with multi-year frameworks to fragmented residential builders purchasing spot.
- Residential Construction:Single-family and low-rise apartment development drives bagged cement consumption through retail channels. Saudi Arabia's mortgage subsidy programs and UAE's visa reform are sustaining housing starts in Riyadh and Dubai's peripheral districts.
- Commercial Construction:Office, retail, and hospitality projects specify higher-grade formulations with performance warranties. Doha's Lusail development and Kuwait's Silk City are absorbing premium blended cements through contractor-direct procurement.
- Infrastructure:Roads, bridges, ports, and utilities represent the highest-volume, lowest-margin segment. Saudi gigaproject concrete demand is compressing regional pricing power and forcing capacity reconfiguration around Tabuk and Neom Bay logistics corridors.
- Industrial:Manufacturing facilities, power plants, and petrochemical complexes require specialized sulfate-resistant and high-early-strength grades. Jubail Industrial City and Ruwais refinery expansions sustain consistent offtake for technical cement formulations.
Infrastructure anchors the volume base while Industrial end-use climbs the fastest on specialized specification premiums.
Application:
Application-driven demand cycles track project phasing, with road and marine works preceding vertical construction and extending cement consumption timelines.
- Road Construction:Pavement concrete and soil stabilization consume bulk Ordinary Portland Cement in continuous pours. Saudi Arabia's Riyadh-Tabuk highway corridor and UAE's Etihad Rail extensions are absorbing record volumes of high-early-strength formulations.
- Building Materials:Block, tile, and precast wall panel manufacturing creates steady intermediate demand for blended cements. Kuwait's Sabah Al Ahmad Sea City and Bahrain's Diyar Al Muharraq rely on captive block plants with dedicated mill supply agreements.
- Precast Concrete:Factory-cast structural elements demand tight quality control and low-variability cement supply. NEOM's modular construction strategy is concentrating precast demand around specialized batching plants in Tabuk and Sharma.
- Cement-Based Products:Mortars, grouts, and repair compounds serve maintenance and renovation markets with higher formulation complexity. Qatar's FIFA legacy infrastructure maintenance and UAE's building stock aging are sustaining aftermarket demand.
Building Materials anchors the volume base while Road Construction shows the steepest expansion trajectory on gigaproject phasing.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sovereign wealth fund-backed developers concentrate procurement power across the Gulf, compressing supplier negotiation cycles and favoring direct mill-to-site logistics contracts over traditional distribution networks.
Saudi Arabia
NEOM, Red Sea Global, and Qiddiya projects absorb the majority of regional clinker capacity under single-source supply agreements. SASO building code enforcement mandates higher-performance blended cement specifications. Tabuk and Neom Bay construction zones anchor western supply chains with dedicated batching plants.
United Arab Emirates
Dubai's luxury hospitality pipeline and Abu Dhabi's industrial zone expansions sustain premium cement offtake. MoIAT green procurement rules now require Environmental Product Declarations for federal infrastructure cement. Ruwais and Jebel Ali industrial clusters concentrate sulfate-resistant grade demand from refinery and port contractors.
Qatar
Lusail City completion and FIFA legacy infrastructure maintenance create steady demand for high-early-strength formulations. QS certification timelines for new supplementary cementitious blends stretch procurement cycles. Doha's West Bay and Pearl-Qatar districts concentrate decorative white cement applications in high-end residential towers.
Kuwait
Silk City and Boubyan Island developments drive bulk infrastructure cement consumption through contractor-direct frameworks. The country's national standards body enforces compressive strength thresholds that favor imported blended formulations. Subiya and Mutlaa residential zones anchor bagged cement retail demand for low-rise construction.
Oman
Duqm Special Economic Zone and Salalah port expansions outpace local clinker capacity, creating import dependency on UAE wholesale supply. The Sultanate's national standardization framework lags neighboring regimes on alternative fuel certification. Muscat and Sohar construction corridors absorb the majority of bulk cement arrivals through marine terminals.
GCC Cement Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement tiers. Saudi Arabia and the UAE together hold surplus grinding capacity that suppresses regional pricing power during demand troughs. Two strategic archetypes dominate: integrated producers with captive quarry-to-distribution control, and coastal terminals leveraging deep-water berths for export arbitrage. Capacity reconfiguration and direct logistics contracting represent the dominant competitive moves.
Among Saudi-based integrated producers, Yamama Cement Company and Yanbu Cement Company exemplify the quarry-captive archetype, while Saudi Cement occupies a position spanning raw material extraction through bulk distribution. These three anchors represent how Riyadh-area kilns and Red Sea port access shape competitive positioning under gigaproject procurement frameworks.
| Leading Market Players |
|---|
| Yamama Cement Company |
| Yanbu Cement Company |
| Saudi Cement |
| Dubai Cement |
| Najran Cement Company |
| Qatar National Cement Company |
| Southern Province Cement Company |
| United Cement Company |
| Kuwait Cement Company |
| Others |
Cost & Logistics Intelligence
Natural gas price volatility in Saudi Arabia and the UAE determines both the spread between blended and Ordinary Portland Cement tiers and the geographic shape of clinker sourcing across Gulf kilns. Feedstock cost uncertainty compresses margins on carbon-intensive grades while rewarding producers with captive quarry access and alternative fuel flexibility.
Pricing Analysis
Cost-plus contracts indexed to natural gas benchmarks dominate procurement frameworks for Saudi gigaproject offtake. Three-tier pricing structure across premium blended, standard sulfate-resistant, and economy bulk Ordinary Portland Cement segments reflects certification grade and volume scale differentiation. Pricing pressure stems from surplus grinding capacity in the Eastern Province and UAE northern emirates during demand troughs. Infrastructure contractors exhibit highest price sensitivity through competitive tendering, while industrial end-users with technical specifications show lowest sensitivity due to performance warranty requirements.
Supply Chain Analysis
Integrated producers in Saudi Arabia, the UAE, and Qatar hold captive clinker capacity that feeds regional grinding terminals. Limestone extraction, gypsum sourcing, and supplementary cementitious material imports anchor raw material dependencies. Single-source vulnerability concentrates around Red Sea port access for western Saudi supply chains serving NEOM construction zones. Distribution runs through direct mill-to-site bulk contracts that displace traditional retail networks around Tabuk and Neom Bay logistics corridors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcined clay and geopolymer substitutes threaten Ordinary Portland Cement incumbents as SASO and MoIAT enforcement accelerates specification shifts toward lower-carbon formulations.
For Market Incumbents: Build regulatory compliance moats through SASO certification for LC3 limestone calcined clay cement grades ahead of competitor approval timelines. Secure captive limestone reserves in Saudi Arabia's Western Province to defend feedstock position against haul-cost inflation. Carbon capture retrofit investment at Riyadh-area kilns addresses EU carbon border adjustment exposure for future export positioning. For New Entrants and Emerging Players: Build out import terminal capacity in Oman to capture Duqm and Salalah construction demand exceeding local clinker production. Target wholesale distribution partnerships with UAE-based suppliers serving Muscat construction corridors. Direct sales channel entry via marine terminal access offers lowest friction path against entrenched Saudi integrated producers. For Investors and Strategic Acquirers: MoIAT green procurement mandates reshape the acquisition landscape toward Environmental Product Declaration-certified assets with alternative fuel co-processing capability. Five-to-ten year viability hinges on clinker factor reduction technology deployment and carbon capture economics. Monitor SASO approval timelines for new supplementary cementitious material blends as inflection indicator for competitive repositioning velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | Positions Saudi producers for EU carbon border compliance on future clinker exports. |
| LC3 Certification Investment | Accelerates SASO approval for limestone calcined clay cement in NEOM specifications. |
| Alternative Fuel Co-processing | Reduces natural gas dependence through refinery waste and municipal solid waste feedstock. |
| Oman Terminal Expansion | Captures import substitution demand from Duqm and Salalah infrastructure projects. |
| Direct Mill-to-Site Logistics | Bypasses distributor networks for sovereign wealth fund-backed gigaproject procurement. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with cement plant managers, gigaproject procurement officers, and MoIAT regulatory affairs leads, alongside secondary validation through SASO standards filings, customs trade records, and SEC 10-K disclosures from listed producers. Bottom-up volume triangulation across product grades and end-use segments was cross-checked against top-down macro construction spend data.
Forecast inputs spanned clinker capacity utilization rates, gigaproject phasing schedules, and regulatory enforcement timelines across the projection horizon. Segmentation modeling incorporated product formulation, distribution channel, end-user concentration, and application intensity dimensions. CAGRs were derived from regression analysis of historical consumption patterns against announced infrastructure commitments.
Practitioners should monitor natural gas subsidy reform announcements and SASO building code amendment drafts for early signals of cost structure disruption. Forecasts reflect assumptions around gigaproject execution continuity and alternative fuel certification pathway clarity. Quarterly review of clinker import volumes and LC3 specification adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
United States Commercial Construction Market
Building Construction
Turkey Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Vietnam Construction Market
Building Construction
Tunnels Design and Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
El Salvador Construction Market
Building Construction
Tanzania Construction Market
Building Construction
Early Production Facility Market
Building Construction
Japan Construction Market
Building Construction
China Building Construction Market
Building Construction
Oman Construction Market
Building Construction
Bangladesh Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
Modular and Portable Building Market
Building Construction
Global Modular Fabrication Market