
 Aluminum Curtain Wall Market | 2026-2036
Aluminum Curtain Wall Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Curtain Wall Market Analysis
Modular unitized curtain wall systems is shifting buyer preference toward factory-assembled, site-installed configurations that compress construction schedules and reduce labor risk. Schüco International leverages its European manufacturing footprint to anchor premium unitized supply chains across German-speaking markets. Kawneer Company, Inc. competes through deep specialization in thermally broken stick-built systems for North American commercial towers. YKK AP America Inc. extends its position via integrated extrusion and finishing capabilities that control lead times for institutional clients.
An aluminum curtain wall is a non-structural building envelope system comprising extruded aluminum framing members, infill panels, and glazing assemblies engineered to resist wind loads, thermal transfer, and air infiltration while transferring gravity and lateral forces to the building's primary structure. Its primary commercial purpose is to maximize daylight penetration and aesthetic flexibility in mid-rise and high-rise construction without contributing to structural dead load. Unitized systems command the dominant share of new high-rise activity because panelized factory production yields tighter quality control than field assembly. Stick-built configurations retain margin pools in renovation and retrofit applications where existing structural constraints resist standardized module dimensions. Composite product types incorporating hybrid metal-and-thermal-break materials represent the fastest-growing specification tier as energy-code stringency escalates across jurisdictions.
EMA energy-performance benchmarks, REACH substance restrictions on coating chemistries, and CE marking conformity requirements collectively shape product composition and market access for European-manufactured systems. EPA stormwater and OSHA fall-protection regulations in the United States influence installation-method selection and contractor qualification standards for commercial facade projects. Stakeholders must monitor evolving carbon-border adjustment mechanisms and embodied-carbon disclosure rules that threaten to resegment competitive advantage toward low-carbon primary aluminum sourcing.
Market Dynamics
Factory prefabrication of curtain wall modules is compressing field labor exposure and compressing project timelines as Southeast Asian high-rise construction accelerates. This structural shift toward unitized systems is redistributing value capture from installation contractors to manufacturing-integrated suppliers.
Growth Catalysts
- EU Green Deal energy-performance mandates:Tightening building envelope standards across European member states is mandating thermally broken aluminum systems for commercial new-build and deep renovation projects.
- Commercial high-rise construction in Vietnam:Manufacturing and service-sector investment flows are generating concentrated demand for unitized curtain wall systems in Ho Chi Minh City and Hanoi metro corridors.
- Modular factory assembly:Panelized production yields tighter quality control than stick-built field assembly, reducing air infiltration defects and warranty exposure for institutional clients.
Market Restraints
- Primary aluminum price volatility:London Metal Exchange aluminum pricing fluctuations compress margin predictability for system fabricators with fixed-price commercial contracts.
- Low-carbon aluminum supply concentration:Smelters with hydroelectric power access in Norway, Canada, and Iceland control limited volumes of embodied-carbon-compliant primary metal.
- Silicone structural glazing adhesive substitution limits:Alternative bonding technologies for glass-to-aluminum attachment remain technically immature for high-rise wind-load applications.
Strategic Opportunities
- Carbon-border adjustment mechanisms:Emerging EU CBAM scope expansion toward aluminum-intensive building products will advantage European-manufactured systems with verified low-carbon supply chains.
- Deep energy retrofit of 1970s commercial stock:Aging curtain wall replacement cycles in Germany, France, and the United Kingdom are opening specification windows for high-performance replacement systems.
- Digital fabrication integration:Convergence of BIM-to-CNC workflows with automated extrusion cutting is compressing custom unit lead times for architecturally complex facade geometries.
Industry Challenges
- Facade installation technician certification gaps:OSHA fall-protection and unitized panel rigging competencies remain inconsistently standardized across contractor workforces in high-rise construction markets.
- CE marking conformity assessment timelines:Extended third-party testing durations for novel thermal-break geometries delay product launch cycles for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Curtain Wall Market |
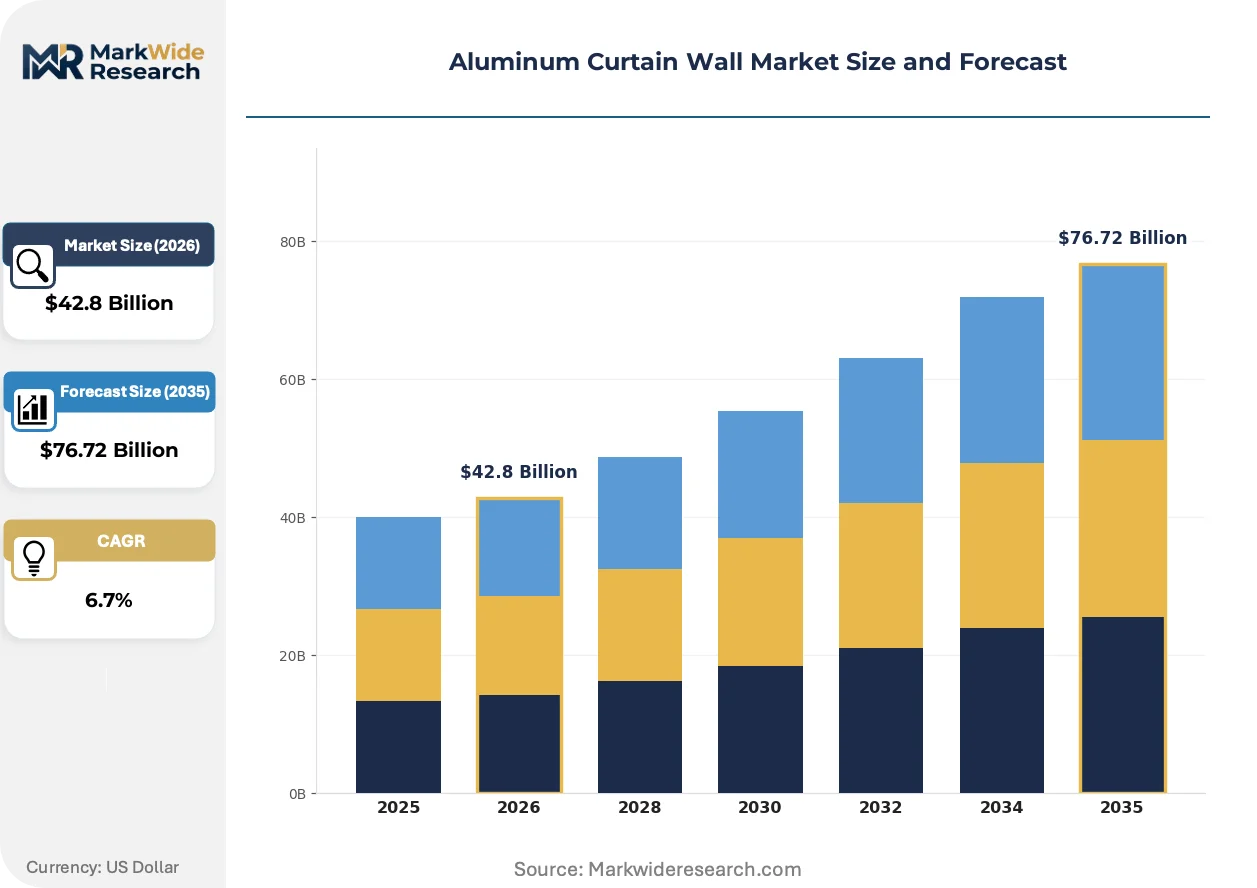
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $76.72 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stick-Built, Unitized, Semi-Unitized, Composite Installation Method: New Construction, Renovation, Retrofit, Prefabricated End User: Commercial, Residential, Institutional, Government Material Grade: 6063-T5, 5052-H32, 6061-T6, Others |
| Companies Covered | Alumil Aluminium Industry S.A., EFCO Corporation, Kawneer Company, Inc., GUTMANN AG, HansenGroup Ltd., Schüco International, Reynaers Aluminium, YKK AP America Inc., Enclos Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Curtain Wall Market Emerging Trajectories
Curtain wall engineering is converging around thermal-performance optimization and digital fabrication integration as energy-code stringency and project delivery speed requirements tighten simultaneously. Three developments are restructuring competitive positioning.
Hybrid metal-and-thermal-break composite framing is unifying structural aluminum extrusions with polyamide thermal barriers into single-source factory-assembled modules. High-rise developers in Singapore and Dubai are specifying these systems to meet stringent U-value targets without field-installed thermal breaks. This unification is compressing the performance gap between premium European systems and mid-market Asian alternatives.
REACH substance restrictions on coating chemistries are eliminating hexavalent chromium pretreatments and certain fluoropolymer topcoats from European-manufactured aluminum finishes. System suppliers are reformulating with trivalent chrome conversion coatings and high-durability polyester powders to maintain warranty terms. German and Austrian fabricators are most affected, with reformulation costs flowing into 2026-2027 specification pricing.
Developer procurement of curtain wall packages is consolidating toward design-build facade specialists with captive engineering and installation capabilities. Traditional bid-specify tender processes are losing share to negotiated partnerships with performance-guaranteed outcomes. This pattern is most visible in London commercial tower development and selective Southeast Asian mixed-use projects where single-point accountability reduces interface risk.
Aluminum Curtain Wall Market Segmentation
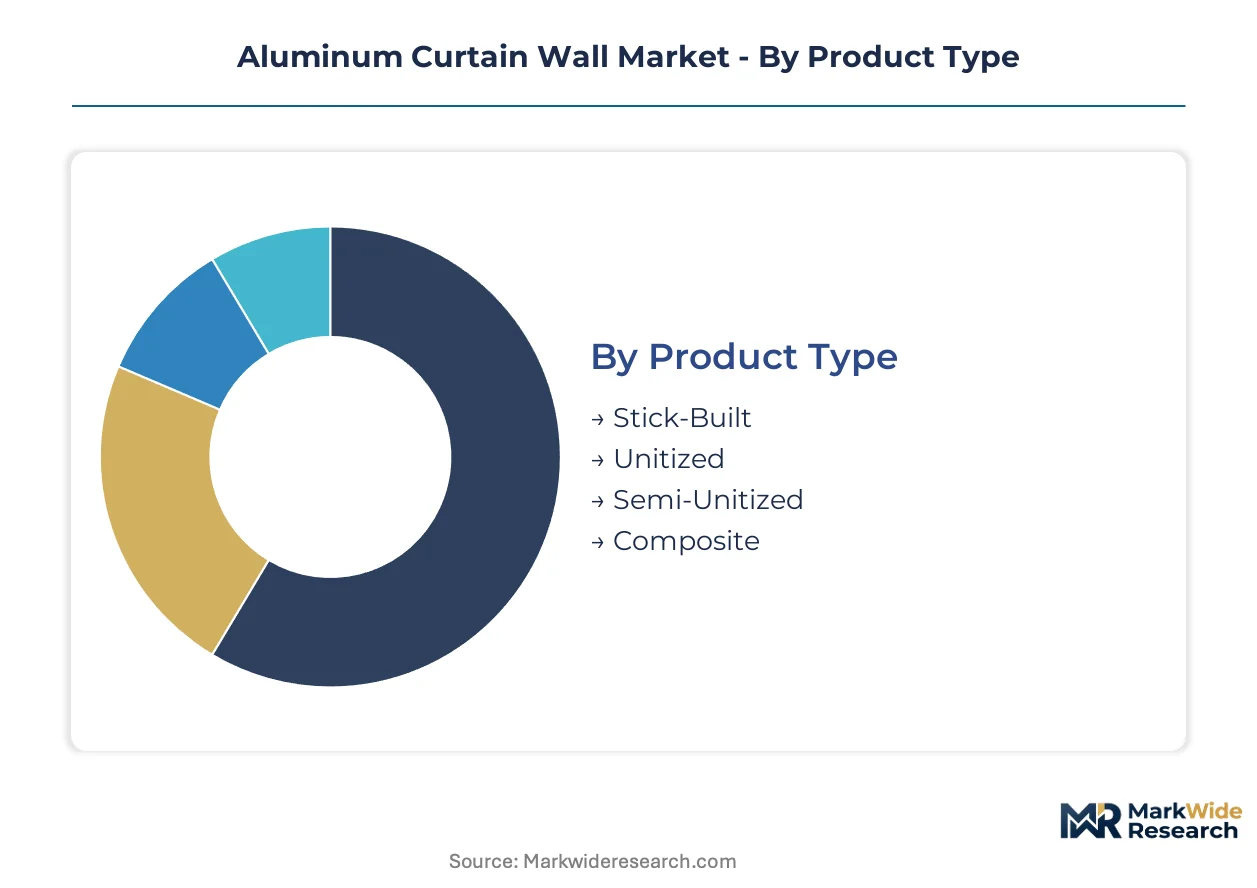
Aluminum curtain wall segmentation reveals how fabrication methods, installation contexts, and material specifications partition value capture across project types. Suppliers configure production assets and certification portfolios around these divisions to defend margin pools in high-rise construction.
Product Type:
Supply concentration in unitized manufacturing is redistributing competitive advantage toward factory-integrated fabricators with captive panel assembly lines.
- Unitized:Factory-assembled panels integrate aluminum framing, glazing, and thermal breaks into single modules craned into place. Demand concentrates in Vietnam and Indonesia where high-rise construction compresses field schedules and labor availability.
- Stick-Built:Field-assembled mullions and transoms accommodate irregular structural conditions. North American commercial towers specify these for renovation projects where existing floor plates resist standardized module dimensions.
- Semi-Unitized:Hybrid approach combining factory-glazed vision panels with field-installed spandrel sections.
- Composite:Hybrid metal-and-thermal-break configurations are climbing the fastest as energy-code stringency escalates across jurisdictions.
Today's leader: Unitized. Tomorrow's challenger: Composite.
Installation Method:
Cost tier differentiation separates premium prefabricated packages from conventional site-built approaches in project procurement.
- New Construction:Greenfield high-rise development specifies unitized systems for schedule compression. Singapore and Dubai towers drive volume for performance-guaranteed facade packages with single-point accountability.
- Retrofit:Aging 1970s commercial stock in Germany and France demands high-performance replacement systems. Deep energy renovation cycles open specification windows for thermally broken upgrades to existing envelopes.
- Renovation:Partial facade replacement addressing localized failure or aesthetic refresh.
- Prefabricated:Off-site panel production with just-in-time delivery to congested urban sites.
New Construction commands current procurement volume. Retrofit offers the steepest expansion trajectory as building stock ages.
End User:
Application-specific performance requirements segment supplier relationships by warranty exposure and technical service intensity.
- Commercial:Office towers and mixed-use developments in Ho Chi Minh City and Hanoi generate concentrated demand. Developers prioritize unitized systems with performance guarantees to reduce interface risk in fast-track delivery.
- Institutional:Museums, airports, and civic buildings specify custom geometries. Digital fabrication integration with BIM-to-CNC workflows compresses lead times for architecturally complex facades.
- Residential:High-rise apartment construction with standardized module repetition.
- Government:Public procurement with domestic content and certification requirements.
Commercial dominates specification volume. Institutional commands premium pricing for technical complexity.
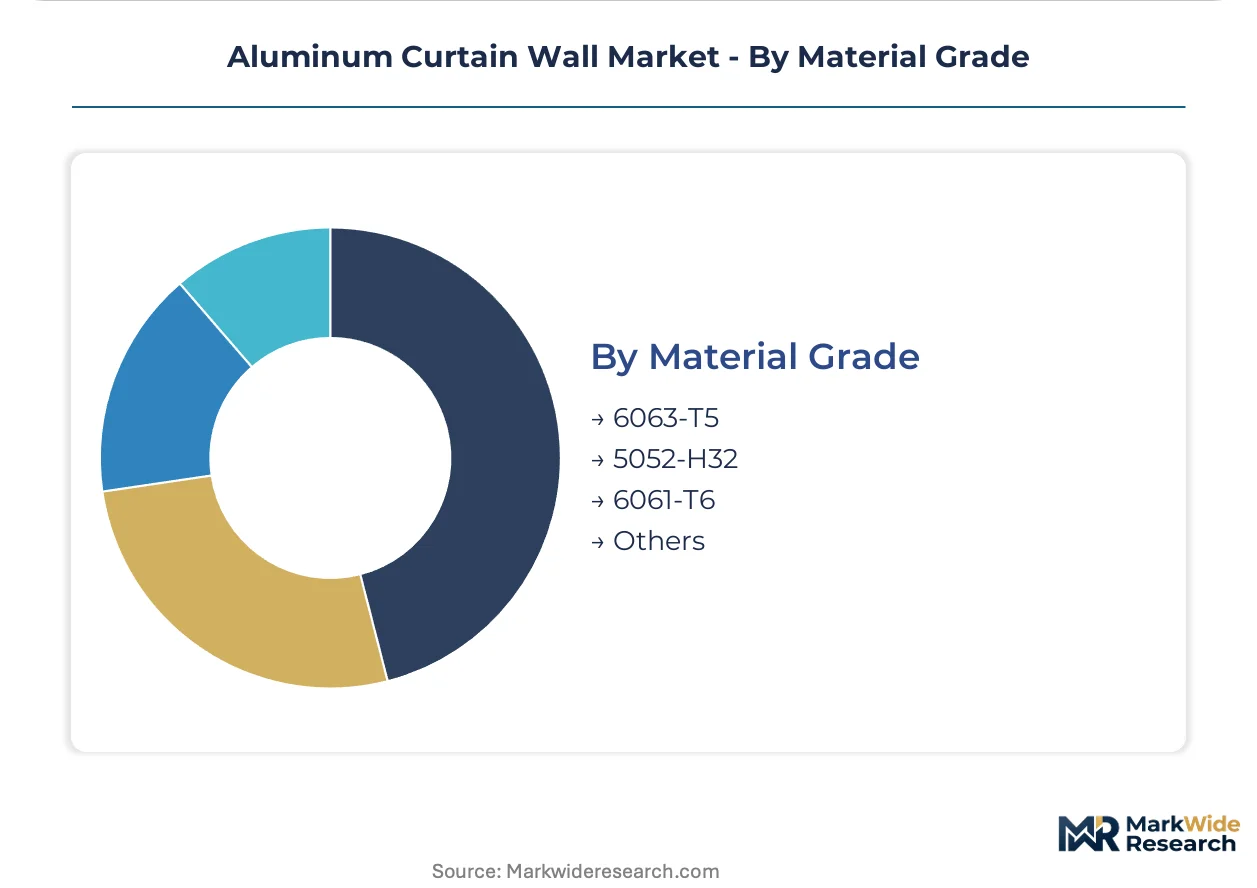
Material Grade:
Volume concentration in 6063-T5 extrusions shapes mill relationships and hedging strategies for system fabricators.
- 6063-T5:Medium-strength alloy with superior extrudability for complex thermal-break geometries. European manufacturers specify this grade for CE-marked systems requiring tight dimensional tolerance in polyamide barrier integration.
- 6061-T6:Higher-strength alloy for structural mullions in high-rise wind-load applications. Southeast Asian towers specify this grade for typhoon-resistant facade engineering.
- 5052-H32:Marine-grade corrosion resistance for coastal installations.
- Others:Specialized alloys for fire-rated or blast-resistant applications.
6063-T5 anchors standard production. 6061-T6 gains share in structural-intensive high-rise segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum curtain wall engineering originated in post-war North America before migrating to European system houses that refined thermal-break technology. German and Austrian fabricators established the performance benchmarks now governing CE-marked specifications. Contemporary demand concentrates in Southeast Asian high-rise corridors where European-engineered systems meet Chinese-scale manufacturing.
United States
Commercial tower development in Manhattan and Chicago drives specification of unitized systems with performance-guaranteed facade packages. OSHA fall-protection regulations and EPA stormwater mandates shape contractor qualification standards for high-rise installation. Los Angeles and Miami metro corridors concentrate demand for hurricane-resistant engineering in coastal high-rise construction.
Germany
Deep energy renovation of 1970s commercial stock in Frankfurt and Hamburg generates replacement cycles for thermally broken curtain wall systems. EU Green Deal energy-performance mandates and REACH substance restrictions on coating chemistries reformulate product specifications. Bavarian and North Rhine-Westphalian fabricators anchor premium system supply chains across German-speaking markets.
Vietnam
Manufacturing and service-sector investment flows into Ho Chi Minh City and Hanoi generate concentrated demand for fast-track unitized facade delivery. National construction codes increasingly reference European thermal-performance benchmarks for commercial high-rise envelopes. Metro corridor developers prioritize factory-prefabricated panels to compress schedules amid skilled labor constraints.
Singapore
Marina Bay and Orchard Road commercial developments specify hybrid composite framing to meet stringent U-value targets in tropical high-rise construction. Building and Construction Authority energy codes mandate continuous thermal barriers for non-residential envelopes above 2,000 square meters. Design-build facade specialists with captive engineering capabilities capture procurement share from traditional bid-specify tender processes.
United Arab Emirates
Dubai Creek Harbour and Abu Dhabi Financial District towers drive volume for architecturally complex facade geometries requiring digital fabrication integration. Dubai Municipality green building regulations and Estidama Pearl Rating System criteria shape thermal-performance specifications for commercial developments. Sharjah-based installation contractors increasingly partner with European system houses for unitized panel supply.
Aluminum Curtain Wall Market Vendor Landscape
Premium-margin players sit above commodity-margin players across thermal-performance certification and factory-integration depth. The vendor base stratifies into three tiers: European system houses with captive R&D and CE-marked product portfolios; North American specialists in thermally broken stick-built configurations; and Asian fabricators scaling unitized production for fast-track Southeast Asian delivery. Consolidation pressure runs through backward integration into aluminum extrusion and forward integration into installation services. Technology licensing agreements between European designers and Asian manufacturers redistribute geographic production footprints.
Among European system houses, Schüco International and Reynaers Aluminium exemplify the premium-tier archetype through integrated engineering and manufacturing footprints. Kawneer Company, Inc. represents North American specialization in thermally broken stick-built systems for commercial tower applications. These named entities anchor competitive positioning without exhausting the vendor landscape, as regional fabricators in Vietnam and Indonesia occupy volume-driven positions in emerging high-rise corridors.
| Leading Market Players |
|---|
| Alumil Aluminium Industry S.A. |
| EFCO Corporation |
| Kawneer Company, Inc. |
| GUTMANN AG |
| HansenGroup Ltd. |
| Schüco International |
| Reynaers Aluminium |
| YKK AP America Inc. |
| Enclos Corp. |
| Others |
Supply Flow & Price Mechanics
Design-build facade specialists with captive engineering capabilities command procurement leverage that compresses margin pools for fragmented installation contractors. This buyer concentration rewards factory-integrated fabricators with performance-guaranteed pricing models while penalizing site-dependent stick-built suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European systems from mid-market Asian alternatives and commodity field-assembled configurations. Price differentiation hinges on thermal-performance certification grade and factory-integration depth, with premium tiers capturing margin from institutional clients demanding warranty-backed U-value guarantees. Cost compression in standard tiers is intensifying because Chinese-scale manufacturing scales unitized output for Southeast Asian fast-track delivery. Public-sector procurement offices exhibit highest price sensitivity, while Singapore and Dubai commercial developers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Direct-to-developer channels anchor premium system distribution for high-rise projects with performance-guaranteed outcomes. Geographic supply concentration centers on Germany, Austria, and China, with Bavarian fabricators controlling CE-marked thermal-break technology and Guangdong-based extruders scaling unitized panel output. Raw material dependencies draw from primary aluminum smelters in Norway, Canada, and Iceland for low-carbon metal, plus polyamide thermal-barrier suppliers and silicone structural glazing adhesive producers. Single-source vulnerability in hydroelectric-powered primary aluminum threatens margin stability as carbon-border adjustment mechanisms expand scope.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory prefabrication adoption is compressing field-labor exposure and expanding premium-tier margin capture for manufacturing-integrated suppliers. This cost-down driver rewards backward integration into aluminum extrusion and captive panel assembly.
For Market Incumbents: Extend thermal-performance certification portfolios to preempt EU Green Deal energy-code escalation and REACH substance restriction compliance deadlines. Backward integration into low-carbon primary aluminum sourcing defends margin position against carbon-border adjustment mechanism exposure. Captive installation service capabilities reduce interface risk in design-build procurement consolidation. For New Entrants and Emerging Players: Regional installation contractors in Vietnam and Indonesia represent the most penetrable channel partner type for factory-integrated system supply. Target deep energy retrofit cycles in German and French commercial stock where aging 1970s curtain wall replacement demands thermally broken upgrades. A design-build facade partnership model with performance-guaranteed outcomes bypasses traditional bid-specify tender barriers. For Investors and Strategic Acquirers: European system houses with captive R&D and CE-marked product portfolios are the most active acquirer in this space, consolidating backward into extrusion and forward into installation services. Mid-cap fabricators with BIM-to-CNC digital fabrication integration present viable acquisition targets over a five-to-ten year consolidation window. Monitor carbon-border adjustment mechanism scope expansion toward aluminum-intensive building products as the inflection signal for low-carbon supply chain premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extrusion | Captive supply of 6063-T5 alloy secures dimensional tolerance for CE-marked thermal-break geometries. |
| Digital Fabrication Integration | BIM-to-CNC workflows compress custom unit lead times for architecturally complex Singapore and Dubai facades. |
| Low-Carbon Aluminum Sourcing | Hydroelectric-powered primary metal from Norway and Iceland satisfies emerging EU carbon-border adjustment requirements. |
| Design-Build Facade Partnerships | Single-point accountability reduces interface risk in Ho Chi Minh City and Hanoi fast-track delivery. |
| Thermal-Performance Certification Investment | CE marking conformity for novel thermal-break geometries accelerates European market entry timelines. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with facade system fabricators, installation contractors, commercial developer procurement officers, and architect specification consultants alongside secondary validation. Trade data from customs authorities, SEC filings from listed building materials suppliers, construction project databases tracking high-rise development pipelines, and CE marking conformity assessment records anchored volume estimates. Bottom-up project pipeline analysis and top-down construction spend allocation triangulated market sizing across unitized, stick-built, and composite product categories.
Comparable-period anchoring linked historical installation volumes to forward projection frameworks across the analysis window, with segmentation modeling across fabrication method, installation context, end-use application, and material grade dimensions. CAGRs derived from regression analysis against construction spend elasticity and energy-code stringency indices. Forecast inputs incorporated London Metal Exchange aluminum price volatility assumptions and skilled technician availability constraints in Southeast Asian metro corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon-border adjustment mechanism implementation timing and primary aluminum smelter power-source transitions. Base assumptions reflect EU Green Deal energy-performance mandate adoption trajectories and REACH substance restriction enforcement patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Europe Ready-Mix Concrete Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
Concrete Formwork System Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Italy Prefab Wood Buildings Market