
 Canada Solar Energy Market | 2026-2036
Canada Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
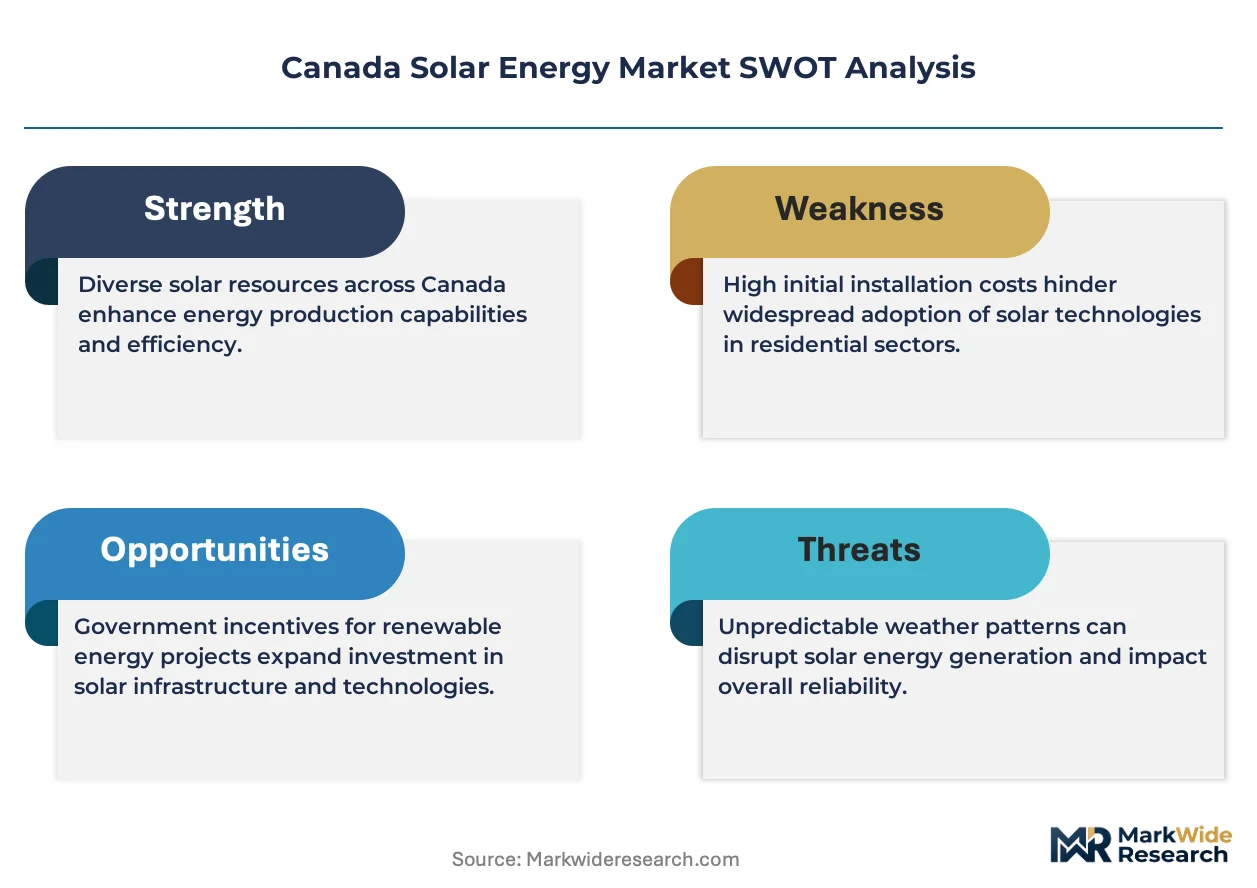
Canada Solar Energy Market Analysis
Green bond issuance and project finance syndication is rewriting capital access for solar developers across Canada. Innergex Renewable Energy leverages its operational portfolio to secure non-recourse debt at scale. Canadian Solar anchors its position through backward integration into polysilicon and module assembly. Brookfield Renewable Partners competes via its infrastructure fund structure that pools institutional capital for utility-scale arrays.
Canada solar energy encompasses photovoltaic systems that convert sunlight into direct-current electricity through semiconductor junctions, with crystalline silicon modules dominating domestic installations above 400 Wp per panel. These systems serve grid-connected generation, behind-the-meter commercial offset, and remote community displacement of diesel microgrids. Monocrystalline technology leads the technology dimension due to higher conversion efficiency in Canada's lower insolation latitudes. Utility-scale installation commands the largest revenue pool, while off-grid deployment in northern territories represents the fastest-expanding niche despite smaller absolute volumes.
Health Canada and PMRA oversee environmental assessments for large solar footprints, while the Canada Revenue Agency administers the clean technology Investment Tax Credit that directly shapes project pro forma returns. Provincial regulators including the Alberta Utilities Commission and Ontario Energy Board determine interconnection timelines and net metering rules that gate market access. Stakeholders must monitor how federal-provincial jurisdiction splits over transmission permitting will affect queue delays and development carry costs.
Market Dynamics
The Investment Tax Credit administered by the Canada Revenue Agency is compressing project payback periods and rerouting capital toward utility-scale arrays in Alberta and commercial rooftops across southern Ontario.
Growth Catalysts
- Clean Technology ITC:The federal refundable tax credit covers specified clean energy equipment, improving project IRRs for developers financing crystalline silicon installations.
- Alberta Power Cooperative Procurement:Rural electrification associations in Alberta are aggregating demand for multi-megawatt solar farms, creating anchor offtake for new capacity.
- Monocrystalline Efficiency Gains:Higher conversion rates in lower insolation conditions extend viable project geography northward into Prairie provinces previously considered marginal.
Market Restraints
- Polysilicon Supply Concentration:Upstream refining capacity clusters in Xinjiang and Inner Mongolia, exposing Canadian module assemblers to forced labor scrutiny and tariff risk.
- Interconnection Queue Friction:The Alberta Utilities Commission and Ontario Energy Board process timelines for grid connection studies extend development carry costs by twelve to eighteen months.
- Diesel Microgrid Entrenchment:Remote northern communities maintain legacy fossil backup despite solar-battery economics, slowed by federal-provincial jurisdictional splits over infrastructure ownership.
Strategic Opportunities
- Northern Territory Off-Grid Deployment:Yukon, Northwest Territories and Nunavut settlements present first-mover potential for solar-plus-storage displacing diesel generation.
- Behind-the-Meter Industrial Aggregation:Manufacturing facilities in Windsor-Sarnia corridor seek peak-shaving installations to manage Global Adjustment charges on Ontario electricity bills.
- Green Bond Syndication:Project finance vehicles certified under Climate Bonds Initiative standards unlock institutional capital pools previously inaccessible to mid-scale developers.
Industry Challenges
- Electrical Engineer Talent Scarcity:Specialized expertise in utility-scale inverter configuration and grid synchronization commands premium compensation, constraining project execution velocity.
- PMRA Environmental Assessment Timelines:Health Canada pesticide and environmental review processes for large-footprint solar sites add six to nine months to permitting schedules.
- Legacy Distribution Infrastructure:Rural feeders in Saskatchewan and Manitoba lack capacity for bidirectional power flows, forcing costly upstream substation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Solar Energy Market |
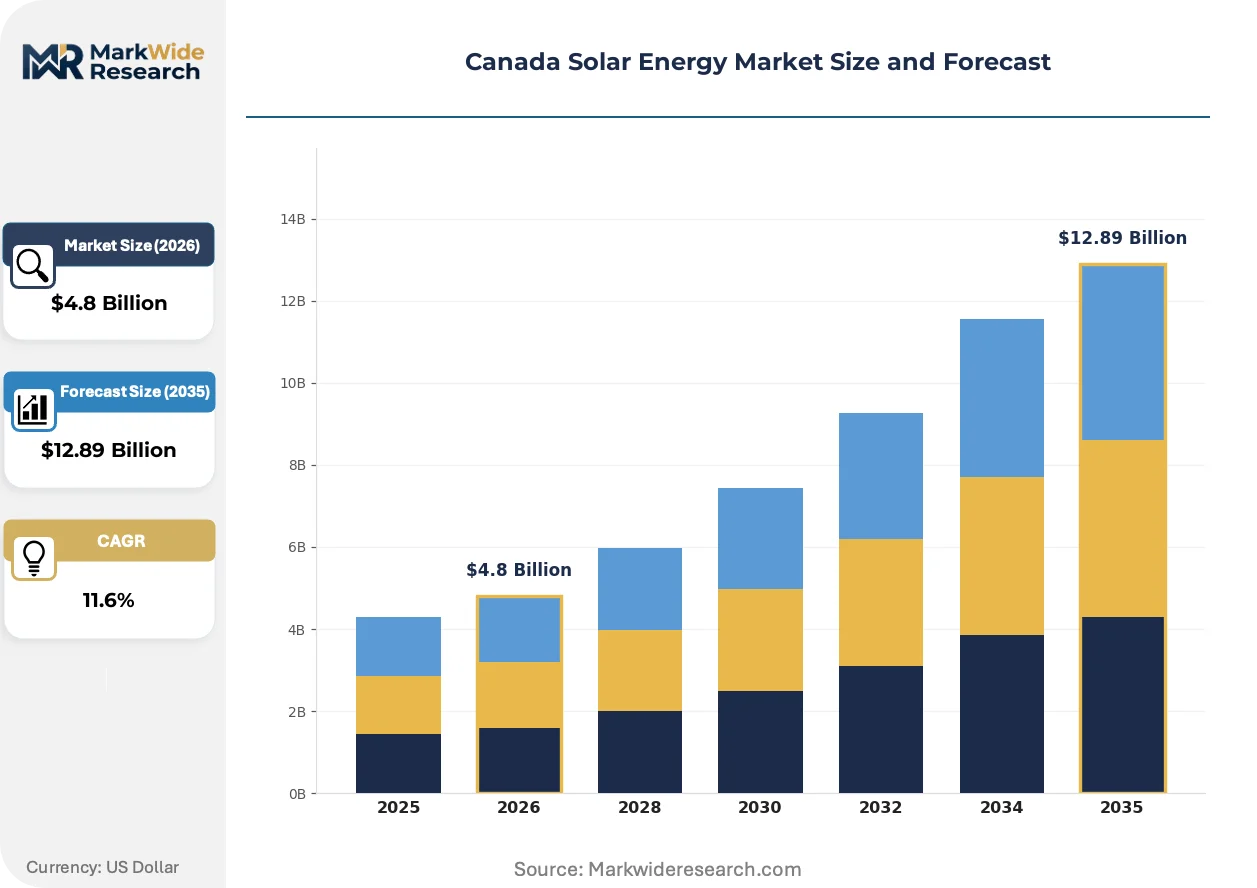
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Solar Inverters, Mounting Systems, Batteries Technology: Thin-Film, Monocrystalline, Polycrystalline, Bifacial Installation: Residential, Commercial, Utility-Scale, Off-Grid End User: Homeowners, Businesses, Government, Non-Profits |
| Companies Covered | Innergex Renewable Energy, AMP.ENERGY, Canadian Solar, Algonquin Power & Utilities, Cordelio Power, Brookfield Renewable Partners, EDF Renewables Canada, Northland Power, Boralex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Solar Energy Market Emerging Trajectories
Module efficiency improvements, financing instrument innovation, and procurement model evolution are compressing deployment timelines and expanding addressable market segments across Canadian provinces.
Bifacial photovoltaic modules are migrating from niche ground-mount applications to standard specification in utility-scale RFPs. Alberta power cooperatives now require rear-side gain estimates in technical submissions. This technology is compressing LCOE calculations by five to eight percent in high-albedo Prairie installations.
The Canada Revenue Agency's clean technology ITC implementation rules are reshaping project ownership structures. Limited partnership flip structures dominate tax equity arrangements. Utility-scale developers in Ontario are reorganizing as Canadian-controlled private corporations to maximize refundable credit capture.
Corporate offtake agreements are displacing traditional utility PPAs as the primary revenue contract for new capacity. Industrial buyers in Hamilton-Niagara manufacturing corridor negotiate sleeved arrangements through local distribution companies. This pattern concentrates in Ontario where Global Adjustment volatility drives hedging demand.
Canada Solar Energy Market Segmentation
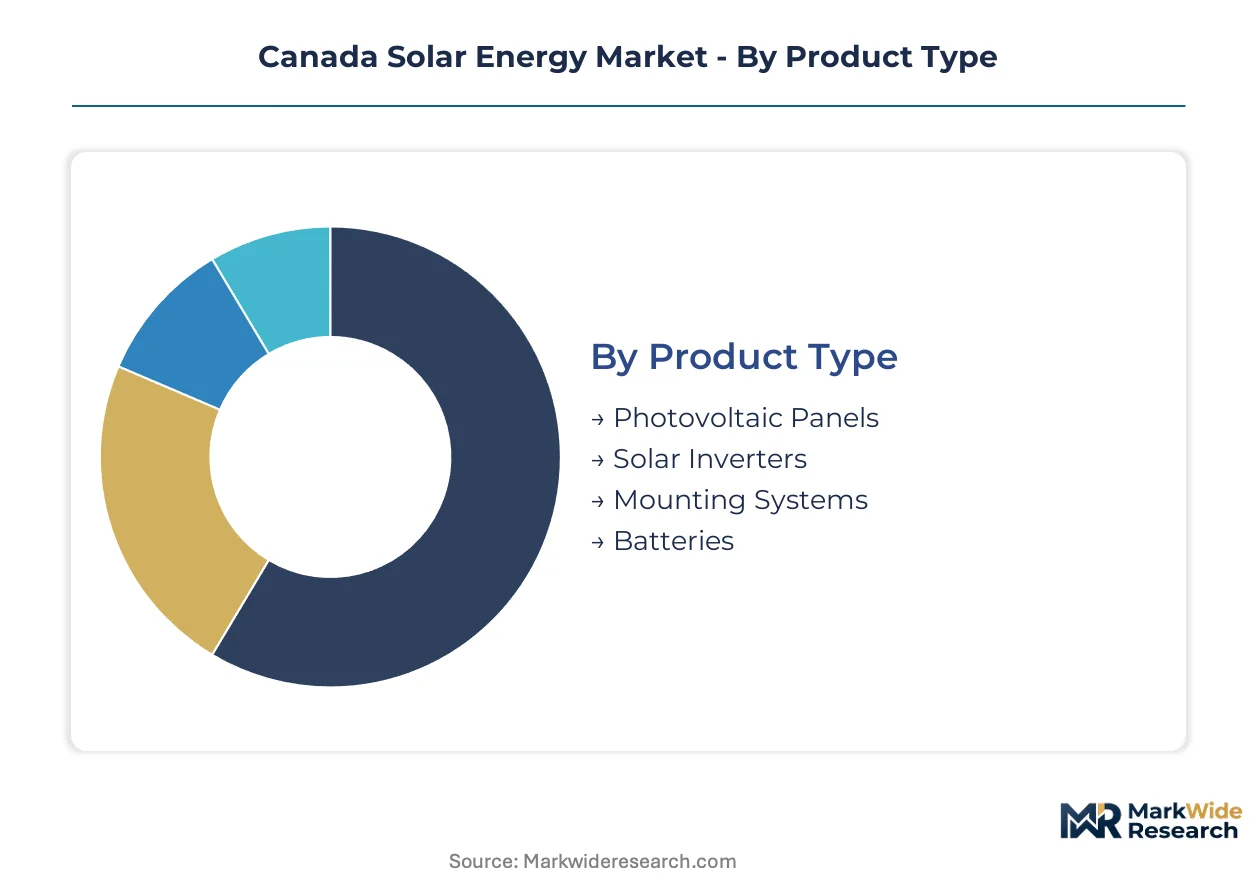
Segmentation in Canadian solar reveals how technology choices, installation scale, and end-user economics fragment procurement patterns across provinces. Each dimension carries distinct regulatory footprints and capital requirements that shape developer strategy.
Product Type:
The hardware stack spans generation, conversion, storage, and mechanical integration, with cost tiers shifting as domestic assembly capacity expands.
- Photovoltaic Panels:Crystalline silicon modules rated above 400 Wp dominate utility-scale and commercial rooftops across southern Ontario and Alberta. Prairie installations favor higher wattage classes to maximize yield per rack in lower insolation conditions.
- Solar Inverters:String and central inverter architectures convert DC array output to grid-synchronous AC, with utility-scale procurement specifying 1500V DC input capability to reduce cabling costs. Central inverters anchor Alberta cooperative farms while string units penetrate behind-the-meter commercial sites in Hamilton-Niagara.
- Mounting Systems:Fixed-tilt racking predominates in utility arrays; tracking systems gain traction in high-albedo southern Alberta terrain.
- Batteries:Lithium-ion storage paired with solar displaces diesel microgrids in Yukon and Northwest Territories remote settlements.
Established volume favors photovoltaic panels; emerging adoption favors batteries.
Technology:
Cell architecture determines conversion efficiency and project viability across Canada's latitude gradient, with premium technologies commanding share in space-constrained applications.
- Monocrystalline:Single-crystal silicon delivers the highest conversion efficiency, extending economically viable project geography into Prairie provinces with marginal solar resource. Southern Ontario commercial rooftops specify monocrystalline to maximize generation per square meter under net metering caps.
- Bifacial:Dual-sided modules capture reflected irradiance from high-albedo ground surfaces, compressing LCOE by five to eight percent in Alberta ground-mount installations. Rural electrification associations now mandate rear-side gain estimates in technical RFP submissions.
- Thin-Film:Cadmium telluride and CIGS technologies occupy niche building-integrated applications where weight constraints or aesthetic requirements override efficiency metrics.
- Polycrystalline:Multi-crystal silicon retains cost advantage in price-sensitive remote deployments where module efficiency is secondary to capital outlay minimization.
Technology leadership concentrates in monocrystalline; steepest expansion trajectory belongs to bifacial.
Installation:
Scale determines interconnection jurisdiction, permitting pathway, and financing instrument, with each tier responding to distinct provincial regulatory frameworks.
- Utility-Scale:Multi-megawatt arrays interconnect at transmission voltage levels, requiring Alberta Utilities Commission or Ontario Energy Board queue positions that extend development timelines. The Canada Revenue Agency's clean technology ITC reshapes ownership structures through limited partnership flip arrangements.
- Commercial:Behind-the-meter systems from 100 kW to 5 MW target Global Adjustment charge mitigation in Ontario and demand charge management in Alberta. Manufacturing facilities in Windsor-Sarnia corridor aggregate procurement to secure volume pricing.
- Residential:Rooftop systems under 20 kW leverage provincial net metering rules, with interconnection standards varying by local distribution company territory.
- Off-Grid:Remote northern settlements in Nunavut and Northwest Territories deploy solar-plus-storage to displace diesel generation, constrained by federal-provincial infrastructure ownership disputes.
Capital formation favors utility-scale; policy innovation favors off-grid.
End User:
Customer type dictates contract structure, with procurement sophistication ranging from individual homeowner net metering to institutional power purchase agreements.
- Businesses:Industrial offtakers in Ontario's Hamilton-Niagara corridor negotiate sleeved corporate PPAs through local distribution companies to hedge Global Adjustment volatility. Alberta agribusinesses aggregate demand through rural electrification associations.
- Government:Federal and provincial procurement targets clean electricity standards, with Public Services and Procurement Canada coordinating multi-departmental solar installations.
- Homeowners:Residential adoption concentrates in net metering jurisdictions, constrained by upfront capital requirements and interconnection study timelines.
- Non-Profits:Community solar cooperatives in Alberta and British Columbia aggregate member capital to develop shared arrays bypassing individual rooftop constraints.
Contract sophistication favors businesses; participation barriers favor non-profits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's solar energy market exhibits pronounced regional variation in deployment patterns, with interprovincial electricity market structures and resource endowments driving divergent adoption trajectories across the federation.
Ontario
Commercial and industrial rooftop installations dominate procurement in southern Ontario, where manufacturing facilities in the Windsor-Sarnia corridor aggregate demand to manage Global Adjustment charges. The Ontario Energy Board determines net metering rules and interconnection timelines that shape developer economics. Toronto and Hamilton-Niagara industrial clusters anchor behind-the-meter deployment as corporate offtakers negotiate sleeved power purchase agreements.
Alberta
Utility-scale arrays command the largest revenue pool, with rural electrification associations aggregating multi-megawatt demand through cooperative procurement structures. The Alberta Utilities Commission processes transmission-level interconnection studies that extend development carry costs. Calgary-Edmonton corridor developers reorganize ownership structures to capture federal Investment Tax Credit benefits through limited partnership flip arrangements.
British Columbia
Community solar cooperatives aggregate member capital to develop shared arrays, bypassing individual rooftop constraints in Vancouver and Victoria metropolitan areas. BC Hydro net metering policies and provincial clean electricity standards shape deployment feasibility. The Okanagan Valley presents emerging commercial opportunity for agribusiness solar integration.
Quebec
Hydro-Québec's dominant low-cost hydroelectric supply constrains solar competitiveness, though remote off-grid applications in northern regions displace diesel microgeneration. Provincial energy planning documents acknowledge distributed solar potential for load management. Montreal-area commercial installations target peak demand charge mitigation in constrained distribution zones.
Northern Territories
Yukon, Northwest Territories and Nunavut settlements represent the fastest-expanding niche, with solar-plus-storage systems displacing diesel generation in remote communities. Federal-provincial jurisdictional splits over infrastructure ownership slow procurement velocity despite compelling economics. Whitehorse and Yellowknife anchor territorial deployment as regulatory frameworks mature.
Canada Solar Energy Market Vendor Landscape
On the supply side, the industry is moderately concentrated with distinct capability tiers separating integrated energy conglomerates from specialized renewable developers and mid-scale independent power producers. Strategic archetypes include utility-scale project developers leveraging tax equity structures, vertically integrated module manufacturers with captive polysilicon supply, and infrastructure fund vehicles pooling institutional capital for yield-focused ownership. Competitive dynamics center on securing interconnection queue positions and optimizing capital stacks through green bond syndication or limited partnership flip structures.
Among Canada-domiciled developers, Innergex Renewable Energy exemplifies the operational portfolio archetype securing non-recourse debt at scale, while Canadian Solar anchors the backward-integrated manufacturer position through upstream polysilicon and module assembly control. Brookfield Renewable Partners occupies the infrastructure fund tier, channeling institutional capital into utility-scale array ownership through its yield-co structure.
| Leading Market Players |
|---|
| Innergex Renewable Energy |
| AMP.ENERGY |
| Canadian Solar |
| Algonquin Power & Utilities |
| Cordelio Power |
| Brookfield Renewable Partners |
| EDF Renewables Canada |
| Northland Power |
| Boralex |
| Others |
Supply Flow & Price Mechanics
Xinjiang and Inner Mongolia polysilicon concentration funnels margin capture toward crystalline silicon module assemblers with captive refining arrangements, while Canadian developers absorb tariff and forced-labor audit premiums in procurement economics.
Pricing Analysis
Industrial OEM buyers anchor project-based long-term offtake structures, with utility-scale arrays commanding premium pricing against commercial rooftop installations. Price differentiation hinges on module efficiency certification tiers and volume scale aggregation through rural electrification associations. Cost compression in standard-grade modules is intensifying because polysilicon spot volatility feeds through wafer pricing. Alberta power cooperatives exhibit highest price sensitivity due to aggregated procurement mandates, while federal government offtakers prioritize performance guarantees over capital outlay minimization.
Supply Chain Analysis
Polysilicon feedstock draws from China, Malaysia, and Germany, with ingot slicing and cell fabrication clustering in Southeast Asian tariff-advantaged jurisdictions. Canadian module assemblers source aluminum frames from domestic extruders and encapsulant films from South Korean petrochemical suppliers. Single-source vulnerability concentrates in metallurgical-grade silicon refining, where Xinjiang capacity dominates global output. Distribution runs through EPC contractor networks that bundle engineering, procurement, and construction services for utility-scale developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's solar market sits at a platform-economics inflection where Alberta cooperative procurement platforms and Ontario corporate sleeved-PPA marketplaces are creating interoperability standards that favor first-movers in aggregation software and offtake matching.
For Market Incumbents: Insulate project pipeline value by securing interconnection queue positions at the Alberta Utilities Commission and Ontario Energy Board before regulatory processing timelines extend further. Deepen backward integration into polysilicon sourcing through offtake agreements with Southeast Asian refiners to circumvent forced-labor scrutiny exposure. Prioritize certification investment in bifacial module assembly capacity to capture premium pricing in Prairie cooperative RFPs. For New Entrants and Emerging Players: Pursue northern territory off-grid deployment where diesel displacement economics and federal infrastructure investment bypass saturated southern markets. Target Yukon and Northwest Territories settlements with solar-plus-storage integrated offerings that bundle engineering with community ownership structures. Establish go-to-market positioning through Indigenous partnership frameworks that navigate federal-provincial jurisdictional complexity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with yield-co structured infrastructure funds holding Ontario commercial rooftop portfolios nearing contract repricing windows. Long-term viability concentrates on developers with secured land positions and interconnection agreements rather than speculative pipeline. Watch Alberta Utilities Commission queue processing velocity as the inflection signal for development carry cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Interconnection Queue Positioning | Securing Alberta Utilities Commission study slots compresses development timelines before carry costs escalate. |
| Bifacial Module Specification | Rear-side gain certification unlocks premium pricing in high-albedo Prairie cooperative procurement. |
| Tax Equity Structure Optimization | Limited partnership flip arrangements maximize Canada Revenue Agency clean technology ITC capture for institutional investors. |
| Corporate Sleeved PPA Origination | Hamilton-Niagara industrial offtake agreements hedge Global Adjustment volatility through local distribution company intermediation. |
| Remote Community Diesel Displacement | Yukon and Northwest Territories solar-plus-storage deployments access federal infrastructure funding pools. |
Methodological Framework
The analysis maps utility-scale procurement, commercial rooftop deployment, off-grid diesel displacement, and residential net metering segments, each validated through utility planning officers, IPP project developers, EPC contractors, and rural electrification association managers. Primary fieldwork combined with secondary validation from Canada Revenue Agency ITC guidance documents, Alberta Utilities Commission interconnection queue filings, Ontario Energy Board regulatory decisions, and IEA renewable energy deployment databases. Bottom-up project pipeline aggregation triangulates against top-down provincial capacity targets.
Assumptions held federal Investment Tax Credit implementation rules and provincial net metering frameworks fixed across the projection horizon, while module efficiency improvement trajectories and polysilicon supply chain configurations were varied in sensitivity scenarios. Segmentation dimensions modeled include installation scale, technology architecture, end-user contract type, and provincial regulatory jurisdiction. CAGRs derive from installed capacity build rates applied to capital cost learning curves and financing structure evolution. Forecast inputs incorporate Alberta cooperative procurement aggregation timelines and Ontario Global Adjustment charge volatility patterns.
Sensitivities concentrate around interconnection study processing delays, forced-labor supply chain audit outcomes, and federal-provincial infrastructure ownership negotiations in northern territories. Forecasts reflect documented assumptions on policy continuity and technology cost trajectories. Cross-checking against IEA Canada renewable energy outlook benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Venezuela Solar Energy Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Solar PV Junction Box Market
Solar Power Systems
Solar Photovoltaics Wafer Market
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
Spain Rooftop Solar Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market