
 Digital Power Conversion Market | 2026-2036
Digital Power Conversion Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Power Conversion Market Analysis
China is reconfiguring regional supply dynamics through aggressive capacity additions in semiconductor fabrication and power electronics packaging. Infineon Technologies leverages its SiC and GaN portfolios to dominate high-efficiency conversion segments for automotive traction inverters. Texas Instruments sustains broad market coverage through integrated digital controllers and isolated gate drivers that span industrial and consumer applications. Analog Devices anchors precision measurement capabilities within loop control architectures, differentiating on converter accuracy and transient response.
Digital power conversion encompasses electronically managed transformation of electrical energy using real-time digital control algorithms rather than analog feedback networks, typically operating at switching frequencies from hundreds of kilohertz to several megahertz with resolution down to sub-nanosecond pulse-width modulation. These systems enable precise voltage regulation, reactive power compensation, and harmonic correction across grid-tied and isolated topologies. Converter products now capture the largest value pool as data center and EV charging deployments scale, while FPGA-based control architectures represent the fastest-expanding technology segment due to reprogrammability demands in prototype-to-production cycles. Microcontroller-based solutions retain cost advantages in high-volume consumer electronics and appliance motor control, where algorithm complexity remains bounded.
The U.S. EPA Energy Star program and DOE efficiency mandates are tightening minimum performance standards for external power supplies and server infrastructure, directly influencing controller IC specification sheets and topology selection. EU Ecodesign regulations and the F-Gas Regulation are simultaneously restricting conventional cooling in power-dense conversion systems, pushing adoption of liquid-cooled and wide-bandgap semiconductor designs. China's GB standards and dual carbon goals from MEE are mandating efficiency tiers that exceed prior international baselines, creating segmented compliance requirements across export markets. Stakeholders must monitor regulatory divergence between efficiency metrics, harmonic limits, and material restrictions to avoid stranded inventory and certification gaps.
Market Dynamics
The transition from analog to digital control architectures is compressing development cycles and forcing component suppliers to bundle software stacks with hardware offerings.
Growth Catalysts
- Data center buildouts:Hyperscale operators in the United States are standardizing on digitally controlled power modules to meet EPA Energy Star efficiency mandates for server infrastructure.
- EU F-Gas Regulation:Restrictions on conventional refrigerants in power-dense conversion systems are accelerating liquid-cooled and wide-bandgap semiconductor adoption across European industrial installations.
- SiC substrate availability:Expanded 150mm and 200mm silicon carbide wafer production is reducing unit costs for high-frequency switching applications in automotive traction inverters.
Market Restraints
- Rare earth magnet dependence:Neodymium and dysprosium price volatility constrains cost predictability for high-power magnetic components in converter designs.
- Foundry concentration:Advanced node fabrication for digital controllers concentrates in Taiwan, creating single-source vulnerability for controller IC supply.
- Wide-bandgap packaging limits:Thermal cycling reliability in GaN-on-Si devices remains below silicon IGBT benchmarks for grid-tied applications above 650V.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for semiconductor and power electronics manufacturing are attracting module assembly investments for domestic solar inverter and EV charger supply.
- FPGA-based control convergence:Integration of adaptive algorithms with hardware-level protection is opening prototype-to-production workflows in aerospace and medical power systems.
- Direct sales to utilities:Bypassing traditional distribution channels through utility procurement frameworks is capturing margin in grid-scale battery energy storage system projects.
Industry Challenges
- Embedded software talent scarcity:Shortage of engineers proficient in both power electronics and real-time digital control algorithm development extends product qualification timelines.
- Multi-jurisdiction certification:Divergent efficiency metrics and harmonic limits across EPA, EU Ecodesign, and China's GB standards fragment testing requirements for universal product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Power Conversion Market |
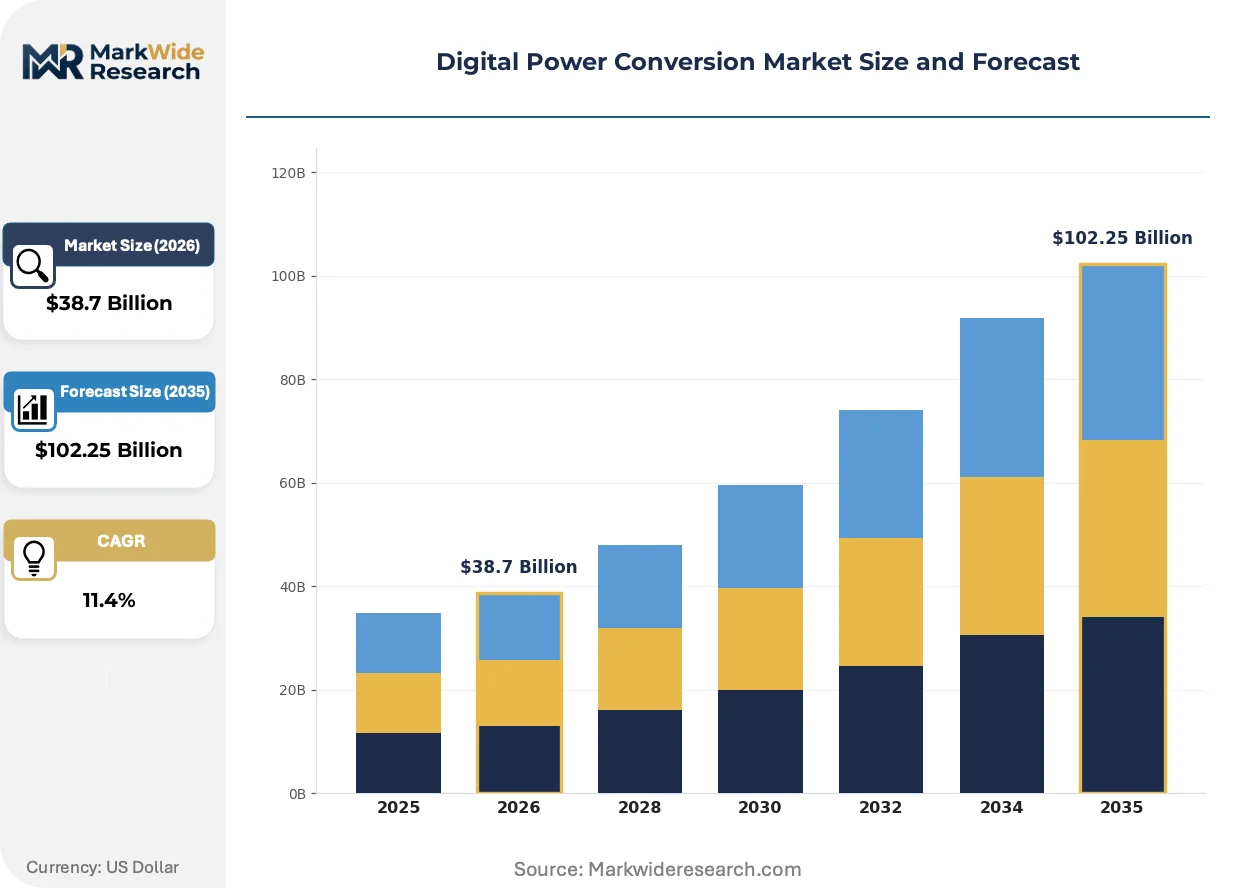
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rectifiers, Inverters, Converters, Regulators Technology: Digital Signal Processing, FPGA, ASIC, Microcontroller End User: Consumer Electronics, Industrial Equipment, Automotive, Renewable Energy Application: Energy Management, Battery Charging, Power Supply, Motor Control |
| Companies Covered | Texas Instruments, Infineon Technologies, Analog Devices, Microchip Technology, STMicroelectronics, Vicor Corporation, ROHM Semiconductor, Cirrus Logic, Cosel Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Power Conversion Market Emerging Trajectories
Digital twin methodologies are migrating from grid simulation into hardware-in-the-loop validation, collapsing the boundary between design and deployment phases.
GaN-based resonant converters are virtualizing the magnetic component footprint in data center power supplies. Hyperscale operators are qualifying these topologies for 48V direct-conversion architectures. This is virtualizing the traditional intermediate bus converter tier, compressing bill-of-materials count and board area by eliminating discrete magnetics.
China's GB standards and dual carbon goals from MEE are mandating efficiency tiers exceeding prior international baselines. Export-oriented manufacturers must maintain parallel product variants to satisfy segmented compliance requirements. Converter suppliers are responding with firmware-configurable efficiency modes that adapt to regional certification thresholds.
Specification ownership is migrating from OEM engineering teams to procurement functions with total-cost-of-ownership mandates. Traditional distributor relationships are yielding to direct vendor engagement with data center operators and automotive Tier 1s. This pattern is most pronounced in the United States, where the Inflation Reduction Act is reshaping domestic manufacturing incentives and concentrating buying power among federally subsidized project developers.
Digital Power Conversion Market Segmentation
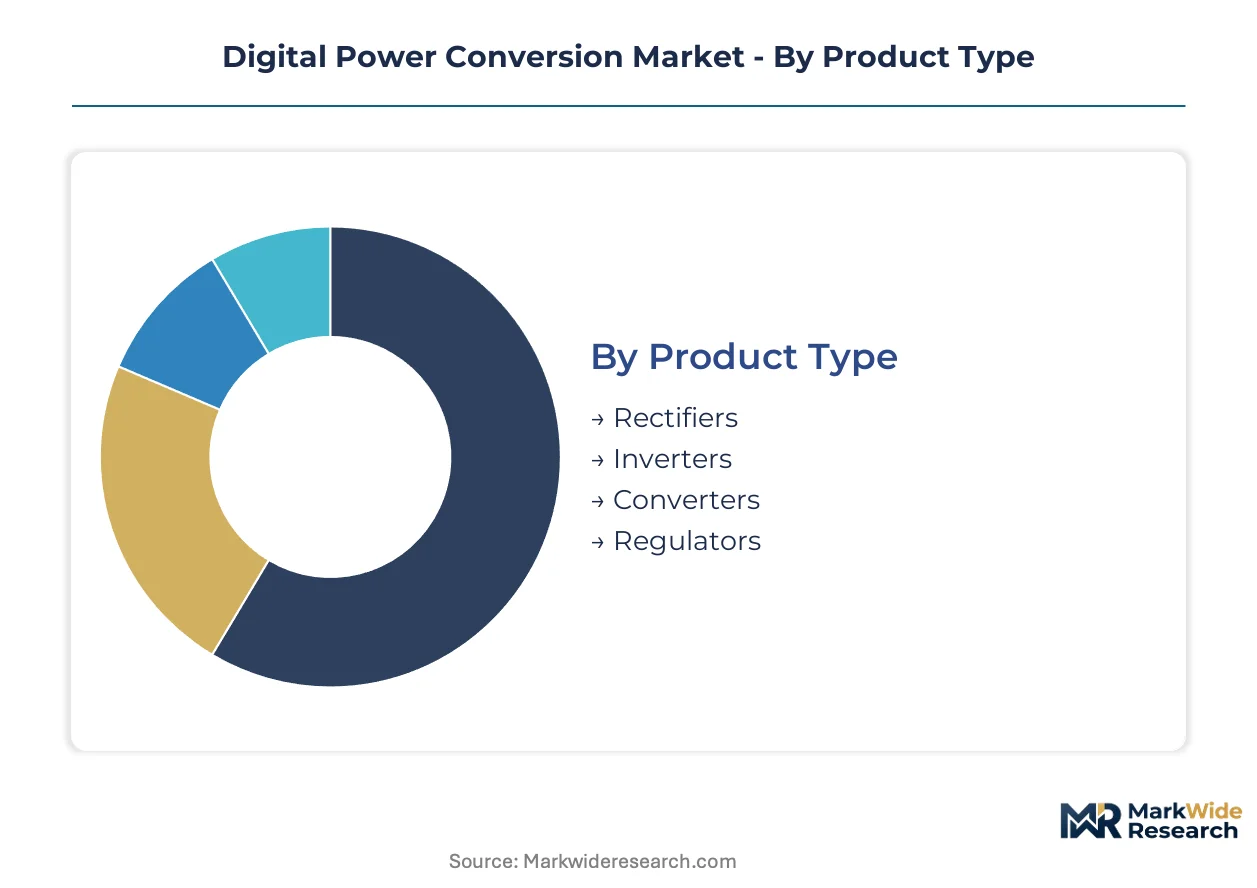
Digital power conversion markets fragment across four distinct dimensions, each imposing different qualification cycles and margin structures. Product type determines hardware refresh cadence, while technology choice locks in firmware development timelines. End-user concentration shapes procurement scale, and application specificity dictates certification complexity.
Product Type:
Rectifiers turn over fastest in high-volume consumer refresh cycles, while grid-tied inverters operate on decade-long depreciation schedules.
- Converters:Electronically managed transformation systems using real-time digital control algorithms, typically operating at switching frequencies from hundreds of kilohertz to several megahertz. Data center operators in the United States are accelerating procurement of digitally controlled power modules to meet EPA Energy Star mandates for server infrastructure.
- Inverters:DC-to-AC conversion hardware employing pulse-width modulation with resolution down to sub-nanosecond precision. Demand concentrates in China as the country expands renewable energy infrastructure and electric vehicle production capacity, though rare earth magnet price volatility constrains cost predictability for high-power magnetic components.
- Rectifiers:AC-to-DC conversion units capturing the largest value pool as data center and EV charging deployments scale across hyperscale operator buildouts.
- Regulators:Precision voltage control modules anchoring loop control architectures in industrial and automotive applications where transient response specifications are tightening.
Converters anchor the volume base while inverters gain share at the steepest rate.
Technology:
Cost tier separates reprogrammable premium solutions from fixed-function economy alternatives, with mid-range microcontroller options dominating appliance motor control.
- FPGA:Field-programmable gate arrays enabling adaptive algorithms with hardware-level protection, opening prototype-to-production workflows in aerospace and medical power systems. Hyperscale operators are qualifying GaN-based resonant topologies for 48V direct-conversion architectures using FPGA control.
- Microcontroller:Integrated digital controllers retaining cost advantages in high-volume consumer electronics where algorithm complexity remains bounded and firmware-configurable efficiency modes adapt to regional certification thresholds.
- Digital Signal Processing:Real-time computational engines for harmonic correction and reactive power compensation across grid-tied topologies.
- ASIC:Application-specific integrated circuits offering lowest unit cost at maximum production scale, common in automotive traction inverter production.
Microcontroller solutions dominate unit shipments while FPGA architectures command the fastest expansion trajectory in revenue terms.
End User:
Application maturity varies sharply, with consumer electronics running shortest design cycles and automotive imposing longest qualification gates.
- Automotive:Traction inverters and onboard charging systems requiring functional safety certification under ISO 26262. Infineon Technologies leverages SiC and GaN portfolios to dominate high-efficiency conversion segments as expanded 150mm and 200mm silicon carbide wafer production reduces unit costs.
- Renewable Energy:Grid-scale solar inverters and battery energy storage system power conditioning units. India's PLI scheme for semiconductor and power electronics manufacturing is attracting module assembly investments for domestic solar inverter and EV charger supply.
- Consumer Electronics:External power supplies and adapter modules facing tightening EPA Energy Star and DOE efficiency mandates for minimum performance standards.
- Industrial Equipment:Motor drives and factory automation power systems where EU F-Gas Regulation restrictions on conventional refrigerants are accelerating liquid-cooled and wide-bandgap semiconductor adoption.
Automotive anchors technology investment intensity while renewable energy climbs fastest in absolute capacity additions.
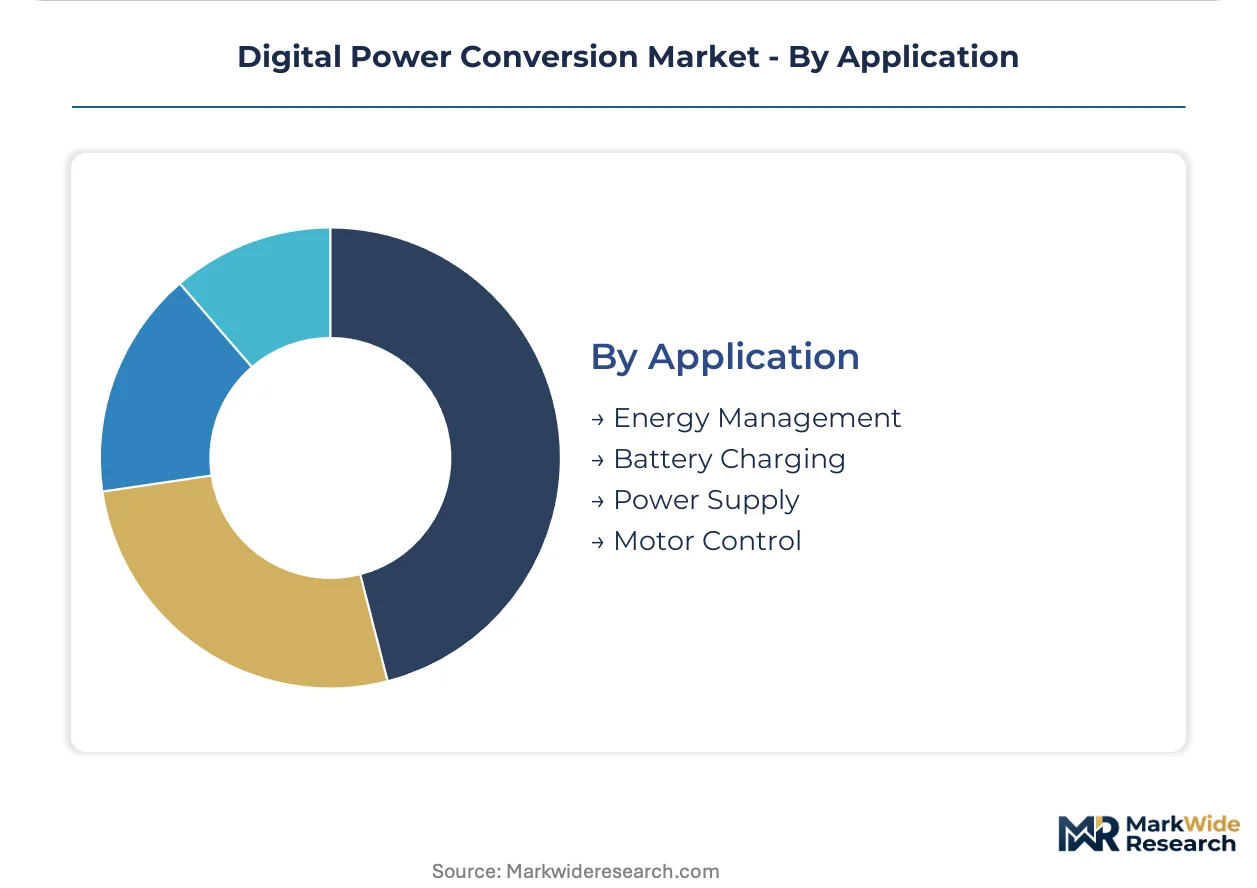
Application:
Customer procurement power concentrates in data center energy management and utility-scale battery storage, squeezing margins in commodity power supply segments.
- Energy Management:Grid-tied and isolated topologies enabling precise voltage regulation, reactive power compensation, and harmonic correction. Specification ownership is migrating from OEM engineering teams to procurement functions with total-cost-of-ownership mandates, most pronounced in the United States where the Inflation Reduction Act is reshaping domestic manufacturing incentives.
- Battery Charging:Infrastructure for electric vehicle and stationary storage systems. Direct sales to utilities through procurement frameworks are capturing margin in grid-scale battery energy storage system projects, bypassing traditional distribution channels.
- Power Supply:Server infrastructure and computing hardware facing fragmented testing requirements across EPA, EU Ecodesign, and China's GB standards with divergent efficiency metrics and harmonic limits.
- Motor Control:Appliance and industrial drive systems where Texas Instruments sustains broad market coverage through integrated digital controllers and isolated gate drivers.
Energy management commands the highest average selling prices while battery charging expands most quickly in deployment volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced node fabrication for digital controllers concentrates in Taiwan, creating single-source vulnerability for controller IC supply. Foundry capacity expansion across multiple geographies is redrawing procurement geography for power electronics.
United States
Hyperscale operators are standardizing on digitally controlled power modules to meet EPA Energy Star mandates for server infrastructure. The Inflation Reduction Act is reshaping domestic manufacturing incentives for energy conversion hardware. Specification ownership is migrating from OEM engineering teams to procurement functions with total-cost-of-ownership mandates, concentrating buying power among federally subsidized project developers in Northern Virginia and Dallas-Fort Worth data center clusters.
China
Demand concentrates as the country expands renewable energy infrastructure and electric vehicle production capacity. GB standards and dual carbon goals from MEE are mandating efficiency tiers that exceed prior international baselines. Yangtze River Delta fabrication hubs are reconfiguring regional supply dynamics through aggressive capacity additions in semiconductor fabrication and power electronics packaging.
Germany
EU F-Gas Regulation restrictions on conventional refrigerants are accelerating liquid-cooled and wide-bandgap semiconductor adoption across European industrial installations. Ecodesign regulations are tightening minimum performance standards for external power supplies. Bavarian automotive suppliers are qualifying SiC-based traction inverters under ISO 26262 functional safety certification for export markets.
India
Production-linked incentives for semiconductor and power electronics manufacturing are attracting module assembly investments for domestic solar inverter and EV charger supply. Central Electricity Authority mandates are driving grid-scale battery energy storage system procurement. Tamil Nadu and Gujarat industrial corridors are capturing module assembly investments targeting domestic renewable energy and electric vehicle supply chains.
Japan
METI efficiency standards are pushing adoption of wide-bandgap semiconductor designs in consumer electronics and industrial equipment. JIS certification requirements are fragmenting testing requirements for universal product platforms. Kansai region power electronics clusters are maintaining precision manufacturing capabilities for automotive and medical power system applications.
Digital Power Conversion Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base separates into three distinct tiers: IDMs with captive fabrication, fabless controller designers, and module assemblers. Two strategic archetypes dominate: vertically integrated semiconductor manufacturers controlling SiC substrate supply, and fabless specialists licensing digital control IP. Competitive moves center on foundry partnership securing and wide-bandgap material backward integration.
Among diversified analog and mixed-signal suppliers, Texas Instruments, Infineon Technologies, and Analog Devices exemplify the integrated portfolio archetype. Texas Instruments sustains broad market coverage through controller and driver integration. Infineon Technologies leverages wide-bandgap material portfolios to anchor high-efficiency conversion segments. Analog Devices occupies a position emphasizing precision measurement capabilities within control loop architectures. Each represents a distinct competitive vector: scale-driven integration, materials-led efficiency, and accuracy-focused differentiation.
| Leading Market Players |
|---|
| Texas Instruments |
| Infineon Technologies |
| Analog Devices |
| Microchip Technology |
| STMicroelectronics |
| Vicor Corporation |
| ROHM Semiconductor |
| Cirrus Logic |
| Cosel Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta fabrication hubs anchor global controller IC capacity, and their expansion velocity directly determines downstream pricing power for digitally controlled power modules. Taiwan's foundry concentration creates asymmetric leverage, compressing margins for fabless designers while IDMs with captive fabrication capture premium tier positioning.
Pricing Analysis
EPA Energy Star mandates and EU Ecodesign regulations dictate the pricing tier structure across digital power conversion markets. Three-tier pricing structure across premium, standard, and economy levels separates FPGA-based adaptive control solutions from fixed-function microcontroller units and commodity ASIC alternatives. Cost compression in the economy tier is intensifying because hyperscale data center operators are consolidating procurement volumes and demanding firmware-configurable efficiency modes. Automotive Tier 1 suppliers exhibit the lowest price sensitivity due to ISO 26262 functional safety certification requirements, while consumer electronics OEMs drive the hardest unit-cost negotiations.
Supply Chain Analysis
Silicon carbide substrate supply draws from Japan, the United States, and China, with 150mm and 200mm wafer production scaling unevenly across these geographies. Rare earth magnet feedstock hinges on Chinese separation and refining capacity, while advanced node digital controller fabrication rests on Taiwan Semiconductor Manufacturing Company and Samsung Foundry output. Single-source vulnerability in 7nm and below controller IC production creates exposure to geopolitical disruption. Distribution runs through authorized component distributors and direct vendor engagement with data center operators and automotive Tier 1s, bypassing traditional channels in utility-scale battery energy storage procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital power conversion markets are recovering from the 2021-2023 semiconductor inventory cycle, with data center capex normalization and EV production ramp providing cyclical lift. Procurement concentration among federally subsidized project developers under the U.S. Inflation Reduction Act is reshaping competitive positioning.
For Market Incumbents: Harden supply chain resilience through backward integration into SiC substrate supply or captive 200mm wafer capacity additions in Germany or Japan. Infineon's materials-led model demonstrates defensibility against fabless controller designers facing foundry allocation constraints. Certification investment in China's GB standards exceeds prior international baselines and creates switching costs for export-oriented customers. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized module assembly corridor for domestic solar inverter and EV charger supply. Tamil Nadu and Gujarat industrial corridors offer white-space penetration before incumbent distribution networks solidify. Direct utility procurement frameworks for grid-scale battery energy storage systems provide a bypass channel to capture margin without distributor relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated semiconductor manufacturers with captive wide-bandgap material supply over fabless controller IP licensors. The five-to-ten year viability window rewards IDMs controlling SiC substrate growth and packaging thermal cycling reliability. The signal to watch is 200mm silicon carbide wafer cost parity against silicon IGBT benchmarks in grid-tied applications above 650V.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrate Supply | Captive wafer production insulates margin from rare earth price volatility and foundry allocation constraints. |
| Firmware-Configurable Efficiency Mode Development | Parallel product variants for EPA, EU Ecodesign, and China's GB standards reduce stranded inventory risk. |
| Direct Utility Procurement Framework Engagement | Bypassing distributors captures margin in grid-scale battery energy storage system deployments. |
| Liquid-Cooled Wide-Bandgap Packaging Investment | EU F-Gas Regulation compliance opens European industrial motor drive and data center power supply markets. |
| FPGA-to-ASIC Conversion Service Launch | Prototype-to-production workflow capture in aerospace and medical power systems commands premium pricing. |
Methodological Framework
A standing panel of power electronics design engineers, data center procurement directors, automotive Tier 1 supplier sourcing managers, and utility-scale battery energy storage system project developers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against SEC 10-K filings, EPA Energy Star certification databases, EU Ecodesign preparatory study reports, and China MEE dual carbon policy documentation. Bottom-up unit shipment modeling triangulated against top-down value chain analysis to anchor market size estimates.
Scenario bracketing framed low, baseline, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include product type, control technology architecture, end-user industry, and application specificity alongside regional regulatory cluster differentiation. CAGRs were derived from slope analysis of technology adoption curves and capacity expansion announcements. Forecast inputs incorporated SiC substrate wafer supply ramp schedules and hyperscale data center operator disclosed capex trajectories.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital equipment spending cycles or renewable energy deployment subsidy continuity would shift the trajectory. Forecasts reflect documented assumptions regarding foundry capacity allocation and wide-bandgap packaging thermal cycling reliability improvement rates. Cross-checking against IEA power system investment benchmarks and EIA electricity storage deployment data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
North America Gas Turbine Market
Power Equipment
Wind Power Fastener Market
Power Equipment
Industrial Gas Turbine Ignition System Market
Power Equipment
France Power EPC Market
Power Equipment
ASEAN Power EPC Market
Power Equipment
China Power EPC Market
Power Equipment
Egypt Power EPC Market
Power Equipment
Turbine Governor Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
Power Analyzers Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Cogeneration Equipment Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Saudi Arabia Power EPC Market
Power Equipment
Clean Steam Separator Market