
 Hydrogen Purification Market | 2026-2036
Hydrogen Purification Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Purification Market Insights
Aftermarket service revenue for purification unit refurbishment and membrane replacement is rewriting profit pool distribution across the hydrogen value chain. Linde leverages its global maintenance network to capture recurring service contracts at industrial hydrogen hubs. Honeywell UOP anchors its position through proprietary sorbent regeneration technologies that extend unit life cycles. Air Products and Chemicals, Inc. competes by integrating purification with on-site generation systems, reducing customer logistics burdens.
Hydrogen purification encompasses processes that remove contaminants—water, carbon monoxide, sulfur compounds, nitrogen, and hydrocarbons—to achieve purity grades from 99.97% to 99.9999% for specific end uses, employing pressure swing adsorption, palladium-alloy membranes, or cryogenic distillation depending on feedstock quality and target specification. The primary commercial purpose is to protect downstream catalysts, fuel cell membranes, and semiconductor deposition equipment from poisoning or performance degradation. Pressure Swing Adsorption dominates installed capacity for large-scale refinery and ammonia applications where throughput volume justifies capital intensity. Membrane Separation represents the fastest-expanding technology segment for distributed electrolysis and small-scale fueling stations requiring modular, rapid-response purification. Carbon Capture integration is emerging as a margin-advantaged configuration where purification units co-process carbon dioxide streams for sequestration or utilization.
The EU Green Deal and F-Gas Regulation are mandating lower-carbon hydrogen certification pathways that elevate purity verification requirements for imported and domestically produced supply. In the United States, the IRA production tax credits are conditioning incentive eligibility on lifecycle emissions accounting that depends critically on purification efficiency and source gas quality. China's MIIT dual carbon goals and GB standards for fuel cell vehicles are accelerating domestic membrane and adsorbent material qualification programs. Stakeholders must monitor evolving certification regimes to align capital deployment with jurisdictions where regulatory clarity on hydrogen quality standards precedes infrastructure scale-up.
Market Dynamics
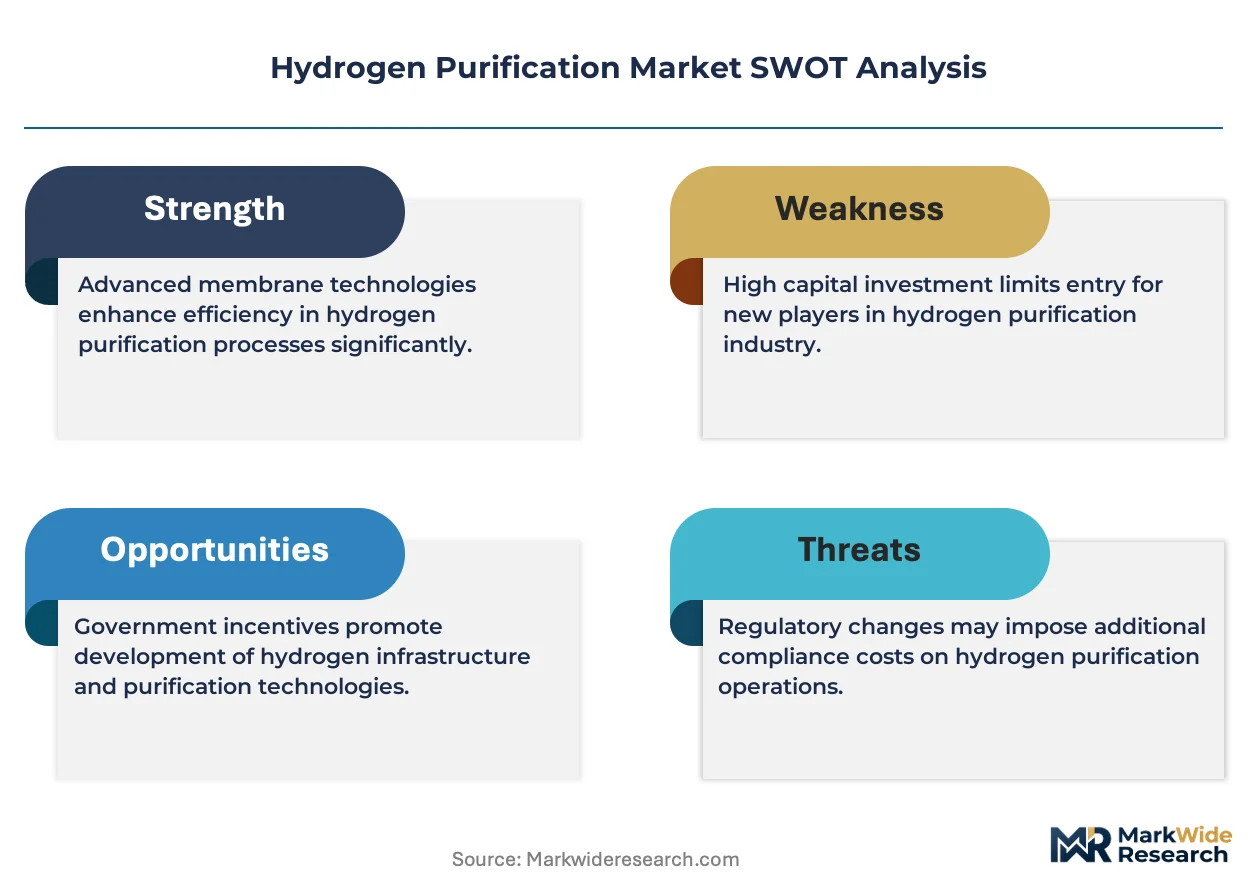
The hydrogen purification market is being fundamentally restructured by regulatory mandates for lifecycle emissions certification, which force infrastructure investors to verify purity provenance across transnational supply chains and reward membrane-based systems with superior carbon accounting transparency.
Growth Catalysts
- Fuel cell vehicle deployment:Germany's national hydrogen strategy mandates ultra-high-purity hydrogen for mobility corridors, requiring purification upgrades at every production node feeding automotive fueling stations.
- Semiconductor fab expansion:East Asian industrial clusters in South Korea and Taiwan are commissioning dedicated hydrogen purification trains to protect EUV lithography equipment from moisture and hydrocarbon contamination.
- EU Green Deal certification pathways:The bloc's delegated acts on renewable hydrogen are creating enforceable purity tiers that disqualify unverified supply, accelerating replacement of legacy refinery off-gas processing.
Market Restraints
- Palladium supply concentration:Russian and South African mining operations control over 70% of global palladium extraction, exposing membrane manufacturers to geopolitical supply disruptions and price volatility.
- Cryogenic energy intensity:Distillation-based purification requires 4-6 kWh per kilogram of hydrogen processed, rendering the technology uneconomical in jurisdictions with industrial electricity tariffs above $0.12 per kWh.
- F-Gas Regulation compliance friction:The EU's phasedown of fluorinated gases complicates cooling system design for cryogenic units, extending equipment qualification timelines by 18-24 months.
Strategic Opportunities
- Carbon capture integration:Purification units co-located with steam methane reformers can process carbon dioxide for sequestration while upgrading hydrogen purity, capturing IRA production tax credits in the United States.
- Modular electrolysis pairing:Distributed green hydrogen production in Japan's industrial ports is creating demand for containerized membrane systems that scale with renewable energy availability.
- India's PLI scheme for electrolyzers:Domestic manufacturing incentives are attracting purification technology licensors to establish local membrane and sorbent production, bypassing import duty exposure.
Industry Challenges
- Membrane fabrication technician scarcity:Palladium-alloy rolling and defect-free welding require specialized metallurgical expertise concentrated in German and Japanese supplier bases, constraining capacity expansion.
- Multi-standard certification burden:Equipment must simultaneously satisfy ISO 14687 for fuel cells, SEMI standards for semiconductors, and regional purity grades, multiplying testing costs and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Purification Market |
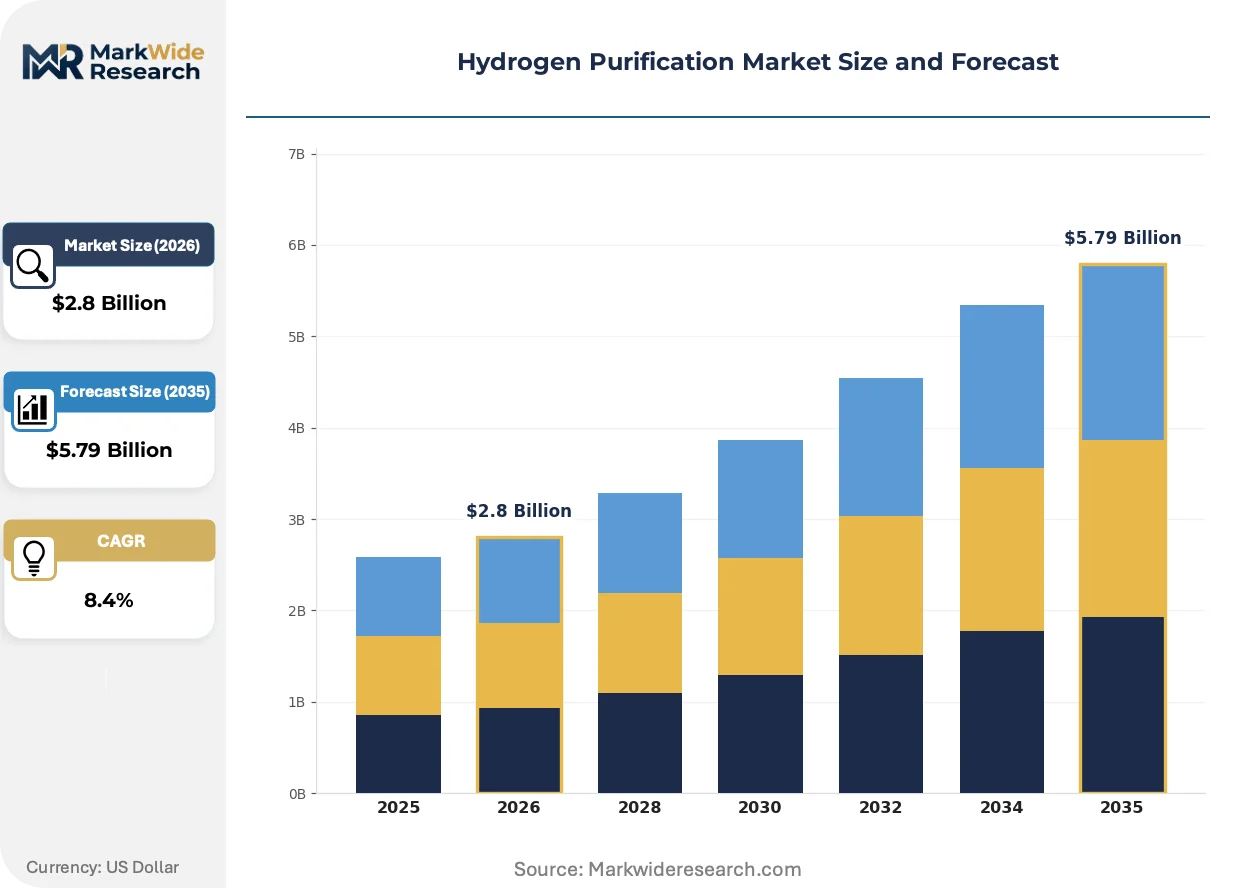
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pressure Swing Adsorption, Membrane Separation, Cryogenic Distillation, Carbon Capture End User: Refineries, Fuel Cell Manufacturers, Industrial Users, Chemical Producers Application: Fuel Processing, Ammonia Production, Semiconductor Manufacturing, Metal Processing Product Type: Electrolyzer, Purification Unit, Compressor, Analyzer |
| Companies Covered | Linde, Air Liquide, Air Products and Chemicals, Inc., Nel Hydrogen, Siemens Energy, McPhy Energy, Honeywell UOP, Chart Industries, Proton OnSite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Purification Market Trends and Innovations
Active research programs are dissolving the historical boundary between purification and carbon management, with emerging system architectures treating contaminant removal and CO2 handling as integrated process design problems rather than sequential unit operations.
Pressure swing adsorption technology is hybridizing with temperature swing regeneration cycles to reduce energy consumption in large-scale ammonia and methanol applications. Industrial gas majors are retrofitting existing PSA trains with advanced sorbent materials that cut regeneration steam requirements by 30%. This hybridization is compressing the total cost gap between conventional and renewable hydrogen purification pathways.
The EU F-Gas Regulation is accelerating refrigerant substitution in cryogenic distillation systems, forcing equipment redesigns that eliminate hydrofluorocarbon cooling circuits. German engineering firms are qualifying propane and ethane as alternative refrigerants for hydrogen liquefaction trains. Cryogenic purification capacity expansions in Rotterdam and Hamburg are now contingent on demonstrating compliance with the regulation's 2030 phase-down targets.
Long-term offtake contracting is displacing spot market procurement for high-purity hydrogen in semiconductor manufacturing. Samsung and TSMC are negotiating 10-15 year supply agreements that bundle purification, generation, and logistics into single-source arrangements. This pattern is most visible in South Korea's Pyeongtaek and Yongin industrial complexes, where fab operators seek supply security over price optimization.
Hydrogen Purification Market Segmentation
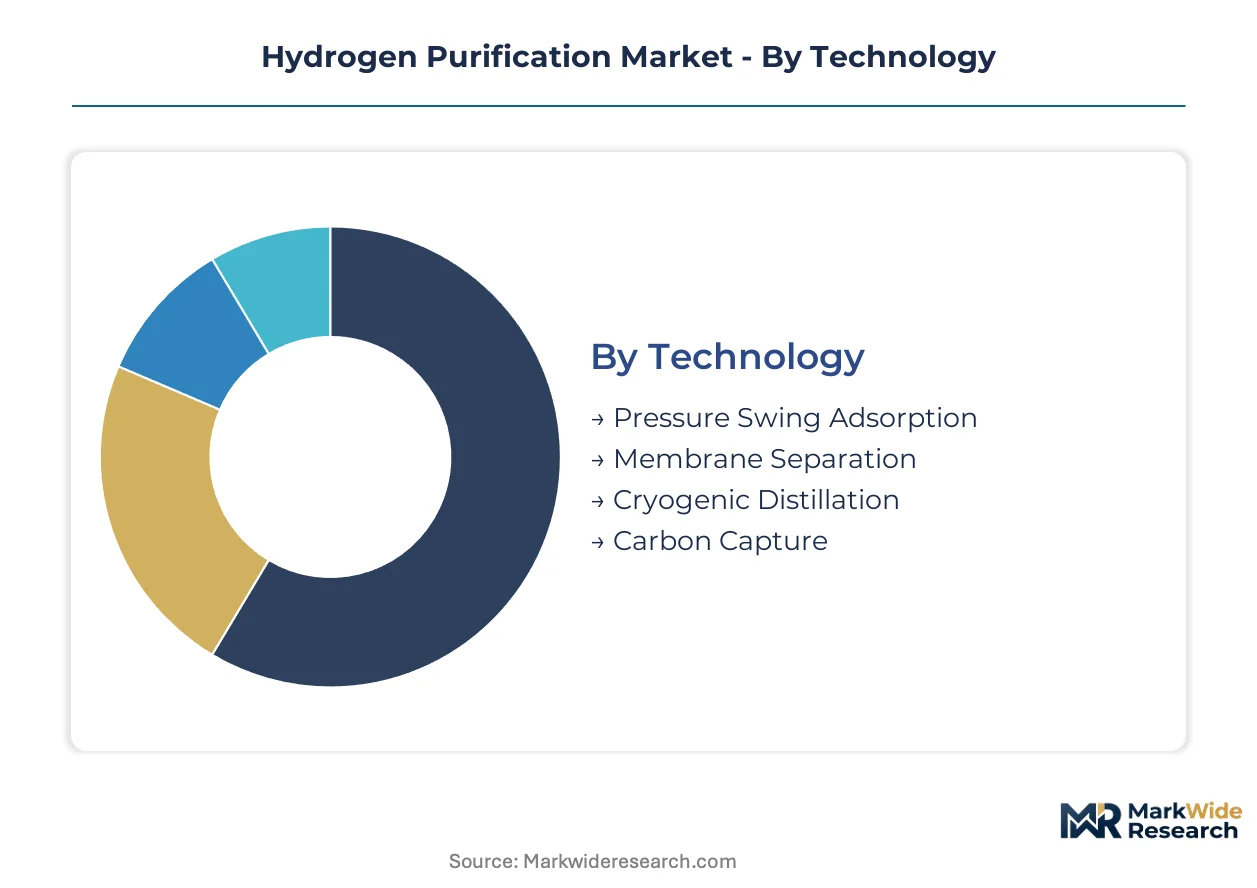
Technology selection in hydrogen purification directly determines capital efficiency, operating energy intensity, and regulatory compliance pathways. End-use purity specifications and feedstock quality create sharp segmentation boundaries that equipment suppliers must navigate.
Technology:
Mature separation methods anchor large-scale industrial deployment while emerging membrane architectures capture distributed and mobility-linked demand.
- Pressure Swing Adsorption:Cyclic gas separation using solid adsorbents under pressure differentials achieves 99.9% purity for refinery and ammonia applications. South Korean and German industrial clusters deploy PSA trains for high-volume hydrogen upgrading where energy costs remain below $0.08 per kWh.
- Membrane Separation:Palladium-alloy or polymer membranes exploit selective permeability to deliver modular, rapid-response purification for electrolysis-fed fueling stations. Japan's port-based hydrogen hubs favor membrane systems that scale with intermittent renewable supply.
- Cryogenic Distillation:Ultra-low-temperature fractionation yields 99.9999% purity for semiconductor and specialty chemical feedstock.
- Carbon Capture:Integrated contaminant removal and CO2 handling architectures qualify for IRA production tax credits in the United States.
Pressure Swing Adsorption retains volume leadership; Membrane Separation holds the steepest expansion curve.
End User:
Customer procurement patterns split between integrated energy majors seeking lifecycle cost optimization and specialized manufacturers demanding purity guarantees.
- Refineries:Hydrotreating and hydrocracking operations consume purified hydrogen for sulfur removal and heavy crude upgrading. German refineries along the Rhine corridor are retrofitting purification trains to process renewable hydrogen blends mandated by the EU Green Deal.
- Fuel Cell Manufacturers:Proton exchange membrane fuel cells require sub-ppm CO and sulfur levels to prevent catalyst poisoning. California and Japan's mobility corridors enforce ISO 14687 Grade D specifications that drive membrane-based purification adoption.
- Industrial Users:Steel, glass, and electronics manufacturers deploy on-site purification for process gas quality control.
- Chemical Producers:Ammonia and methanol synthesis loops demand consistent hydrogen purity to protect synthesis catalysts and optimize conversion yields.
Refineries dominate current installed base; Fuel Cell Manufacturers are gaining share fastest.
Application:
Application requirements range from bulk fuel upgrading to sub-ppb contamination control for advanced manufacturing.
- Fuel Processing:Desulfurization and reforming of natural gas or liquid fuels yields hydrogen for stationary power and transport. South Korean hydrogen filling stations deploy dedicated purification skids to meet KGS certification for automotive fuel cell supply.
- Ammonia Production:Haber-Bosch synthesis demands 99.99% hydrogen purity to maintain catalyst activity and prevent reactor poisoning. Taiwan's petrochemical complexes integrate purification trains with naphtha reformers and emerging electrolysis capacity.
- Semiconductor Manufacturing:EUV lithography and epitaxial deposition require ultra-high-purity hydrogen with sub-ppb moisture and hydrocarbon limits.
- Metal Processing:Annealing, sintering, and reducing atmospheres in steel and specialty metals production use purified hydrogen to prevent oxidation.
Ammonia Production commands the largest throughput volumes; Semiconductor Manufacturing exhibits the most rapid specification escalation.
Product Type:
Equipment categories span integrated generation-purification systems to standalone quality verification instruments.
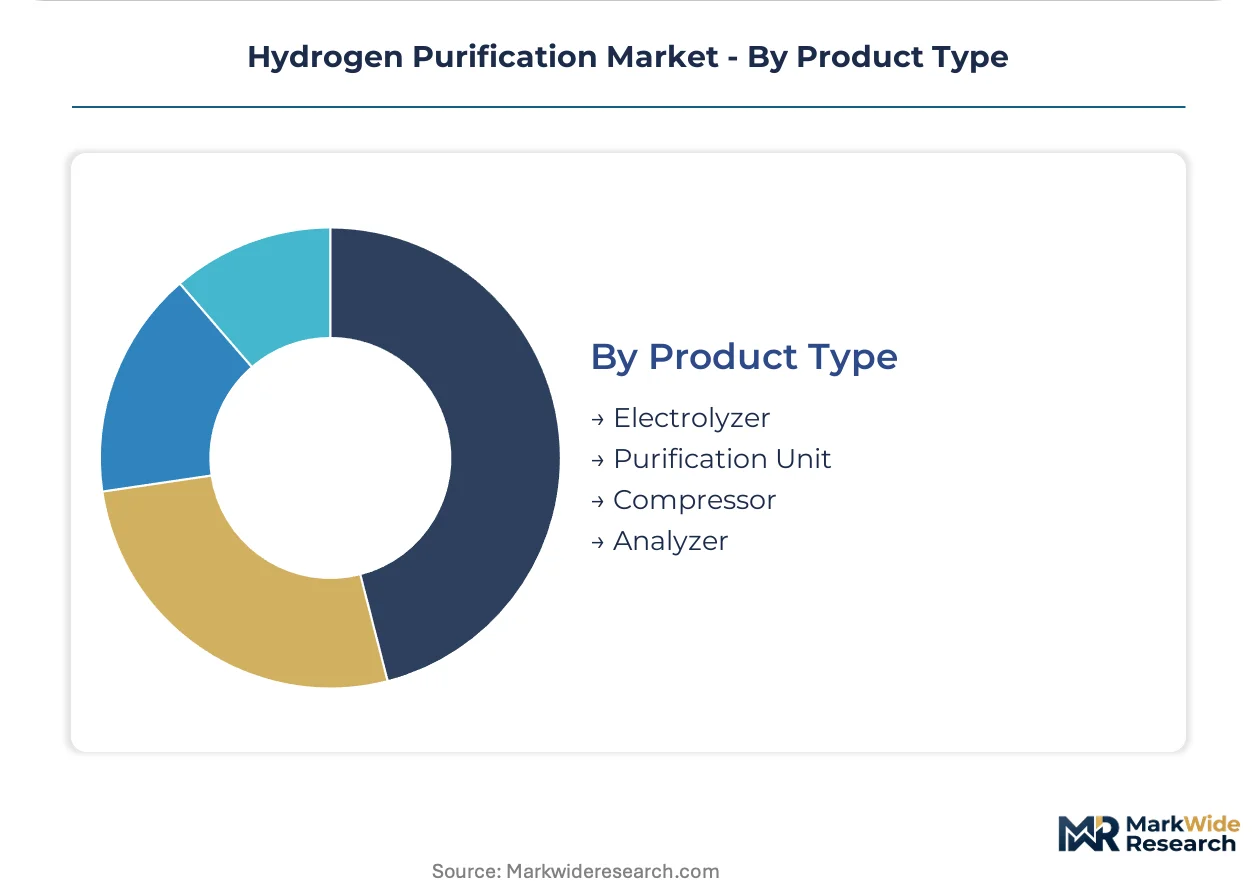
- Electrolyzer:Alkaline and PEM electrolysis systems with integrated purification stages deliver high-purity hydrogen from water splitting. China's MIIT-qualified electrolyzer manufacturers are bundling membrane purification to meet GB/T 37244 fuel cell vehicle standards.
- Purification Unit:Standalone PSA, membrane, or cryogenic systems upgrade externally sourced hydrogen to specification. India's PLI scheme for electrolyzers is attracting purification unit licensors to establish local membrane and sorbent production.
- Compressor:Diaphragm and ionic liquid compressors handle purified hydrogen without contamination for high-pressure storage and dispensing.
- Analyzer:Gas chromatography and laser spectroscopy instruments verify purity grades for certification and process control.
Purification Unit shipments lead in value terms; Electrolyzer-integrated systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and South Korea absorb premium pricing for ultra-high-purity hydrogen without volume elasticity, while Indian and Chinese procurement remains acutely sensitive to unit capital cost per standard cubic meter of capacity.
United States
California's mobility corridors and Texas industrial clusters drive membrane-based purification demand for fuel cell vehicle infrastructure and ammonia production hubs. IRA production tax credits condition incentive eligibility on lifecycle emissions verification that rewards high-efficiency purification systems. Houston's petrochemical corridor hosts retrofit programs linking steam methane reformers with carbon capture-integrated purification trains.
Germany
Rhine corridor refineries and Bavarian industrial parks anchor European demand for pressure swing adsorption upgrades processing renewable hydrogen blends. The national hydrogen strategy mandates ISO 14687 Grade D purity for automotive fueling stations, tightening certification requirements. Hamburg's port infrastructure expansion includes cryogenic purification capacity contingent on F-Gas Regulation compliance by 2030.
China
MIIT dual carbon goals and GB/T 37244 fuel cell vehicle standards accelerate domestic membrane and adsorbent material qualification across Yangtze River Delta manufacturing bases. Provincial governments in Jiangsu and Zhejiang subsidize electrolyzer-purification bundled deployments for industrial hydrogen supply. Shanghai's Lingang Special Area concentrates electrolyzer manufacturing with integrated purification stages for export markets.
Japan
Port-based hydrogen hubs in Kobe and Yokohama favor modular membrane systems scaling with intermittent renewable energy availability for fuel cell vehicle supply chains. METI hydrogen roadmaps specify sub-ppm contaminant limits for mobility applications, elevating verification requirements. Chubu region industrial clusters deploy containerized purification skids paired with offshore wind-electrolysis pilots.
South Korea
Pyeongtaek and Yongin semiconductor fabs negotiate decade-long supply agreements bundling purification, generation, and logistics for EUV lithography protection. KGS certification mandates for hydrogen filling stations drive dedicated purification skid deployment nationwide. Ulsan petrochemical complexes integrate purification trains with naphtha reformers and emerging electrolysis capacity for ammonia export.
Hydrogen Purification Market Competitive Landscape
Capability concentration sits with specialized membrane fabricators possessing palladium-alloy metallurgical expertise; scale advantage sits with integrated industrial gas majors leveraging global maintenance networks and recurring service contract portfolios. The market structures around three tiers: technology licensors controlling proprietary sorbent regeneration protocols, equipment fabricators with regional manufacturing presence, and project developers bundling purification with generation assets. Dominant competitive moves include strategic partnerships between membrane specialists and electrolyzer manufacturers, plus geographic expansion through local licensing arrangements in India and China.
Within the industrial gas major tier, Linde, Air Liquide, and Air Products and Chemicals, Inc. occupy positions defined by captive maintenance infrastructure and long-term offtake contracting relationships. Linde exemplifies the service-network archetype through recurring refurbishment contracts at industrial hydrogen hubs. Air Liquide represents European-centered technology licensing with regional adaptation capabilities. Air Products and Chemicals, Inc. anchors the integrated-systems vector by bundling purification with on-site generation to reduce customer logistics burdens.
| Leading Market Players |
|---|
| Linde |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Nel Hydrogen |
| Siemens Energy |
| McPhy Energy |
| Honeywell UOP |
| Chart Industries |
| Proton OnSite |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in palladium-alloy membrane fabrication is compressing lead times and elevating pricing power for German and Japanese metallurgical specialists, while Chinese electrolyzer bundling strategies force cost transparency downstream.
Pricing Analysis
Long-term offtake contracts dominate procurement for semiconductor fabs and fuel cell corridors, with Samsung and TSMC negotiating decade-long supply agreements that bundle purification, generation, and logistics. Pricing stratifies across ISO 14687 Grade D certification tiers, ultra-high-purity semiconductor specifications, and standard industrial grades. Cost compression in membrane-based systems is intensifying because Chinese electrolyzer manufacturers are integrating purification stages and publishing transparent cost structures. Refineries exhibit the highest price sensitivity due to throughput volume economics, while semiconductor fabs absorb premiums without volume elasticity.
Supply Chain Analysis
Contract manufacturing concentration sits with German membrane fabricators possessing palladium-alloy rolling expertise and Japanese suppliers controlling defect-free welding protocols. Geographic supply concentration centers on Germany, Japan, and South Korea for membrane systems; China dominates adsorbent and electrolyzer-integrated production. Raw material dependencies draw from Russian and South African palladium extraction, Chinese rare earth processing, and German precision metallurgy. Single-source vulnerability in palladium supply exposes membrane manufacturers to geopolitical disruption. Distribution runs through industrial gas majors' captive maintenance networks and regional equipment fabricators with local licensing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen purification is approaching a platform-economics inflection where interoperability between electrolyzer output standards and fuel cell input specifications determines ecosystem capture, with China's GB/T 37244 and Europe's delegated acts on renewable hydrogen driving consolidation around certified purity tiers.
For Market Incumbents: Pre-empt modular membrane displacement by retrofitting existing PSA trains with advanced sorbent materials that cut regeneration energy requirements. Anchor position through backward integration into palladium-alloy metallurgy or captive sorbent regeneration protocols. Defend against Chinese electrolyzer bundling by embedding purification within long-term offtake contracts that lock in semiconductor fab demand.
For New Entrants and Emerging Players: Pursue India's PLI scheme for electrolyzers as a white-space entry point, where domestic manufacturing incentives attract purification technology licensors to establish local membrane production. Target containerized membrane systems for Japan's port-based hydrogen hubs, where intermittent renewable supply favors rapid-response modular architectures. Lead with carbon capture integration as a differentiated value proposition for IRA tax credit eligibility.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across membrane separation as Chinese manufacturing scales and process standardization reduces specialized technician requirements. Favor acquisition targets possessing proprietary sorbent regeneration IP or established certification relationships with SEMI and ISO standards bodies. Monitor F-Gas Regulation compliance timelines as an inflection indicator for cryogenic distillation capacity viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palladium Metallurgy | Captive supply of critical membrane alloys insulates against Russian and South African extraction concentration. |
| Carbon Capture Integration | Co-processing CO2 streams qualifies purification trains for IRA production tax credits in Texas and California hubs. |
| Modular Electrolyzer Pairing | Containerized membrane systems align with Japan's METI hydrogen roadmaps for port-based renewable supply chains. |
| Long-term Offtake Contracting | Decade-long agreements with Samsung and TSMC secure revenue visibility against spot market volatility. |
| Local Licensing in India | PLI scheme partnerships bypass import duties and establish regional manufacturing footprint for Asian export markets. |
Research Methodology
The analysis maps pressure swing adsorption, membrane separation, cryogenic distillation, and carbon capture integration architectures, each validated through purification unit procurement managers, fuel cell system engineers, semiconductor fab gas specialists, and industrial gas major technology licensors. Primary interviews triangulate against customs trade data for palladium and adsorbent material flows, SEC filings from industrial gas majors, IEA hydrogen project databases, and EU delegated acts on renewable hydrogen certification. Bottom-up unit deployment counts reconcile with top-down market value estimates across technology and end-use segments.
Assumption sets held electrolyzer capacity expansion trajectories and F-Gas Regulation phase-down schedules fixed while varying IRA tax credit permanence and Chinese export subsidy intensity across sensitivity scenarios. Segmentation dimensions model technology type, end-user industry, application purity requirement, and regional regulatory framework. CAGRs derive from installed base growth rates, replacement cycle timing, and specification escalation curves in semiconductor manufacturing. Forecast inputs incorporate palladium price volatility bands and membrane fabrication technician availability constraints.
Sensitivities concentrate around palladium supply disruption, F-Gas Regulation compliance timeline extensions, and IRA tax credit eligibility revisions. Forecasts reflect documented assumptions regarding electrolyzer cost reduction curves and certification standard harmonization. Quarterly review of EU delegated act implementation, Chinese MIIT qualification announcements, and semiconductor fab construction permits is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Brown Hydrogen Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Green Hydrogen Energy Storage System Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Hydrogen Gas Generator Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market